
 Automotive Piston Engine System Market | 2026-2036
Automotive Piston Engine System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Piston Engine System Market Outlook
Aftermarket parts distribution is tilting toward consolidated digital platforms that bypass traditional jobber networks. MAHLE GmbH leverages its forged piston foundry network to sustain direct-to-garage fulfillment across Europe. Tenneco Inc. competes through its ring and liner portfolio, while Aisin Seiki anchors Asian OEM supply with integrated powertrain module production.
An automotive piston engine system comprises the piston assembly, connecting rod, wrist pin, piston rings, and cylinder liner operating within swept displacement volumes typically from 0.8L to 16L, converting linear thermal force into rotary motion through crankshaft articulation. Inline engine configurations dominate light-duty manufacturing due to packaging efficiency and lower tooling costs, while V engine architectures command premium margin pools in performance and heavy-duty segments where thermal load management demands advanced skirt coatings and ring land reinforcement. Diesel technology applications retain structural importance in commercial vehicle and fleet operator channels despite emissions compliance investments, whereas hybrid technology integration is expanding fastest as OEMs adopt Atkinson-cycle piston geometries optimized for intermittent combustion.
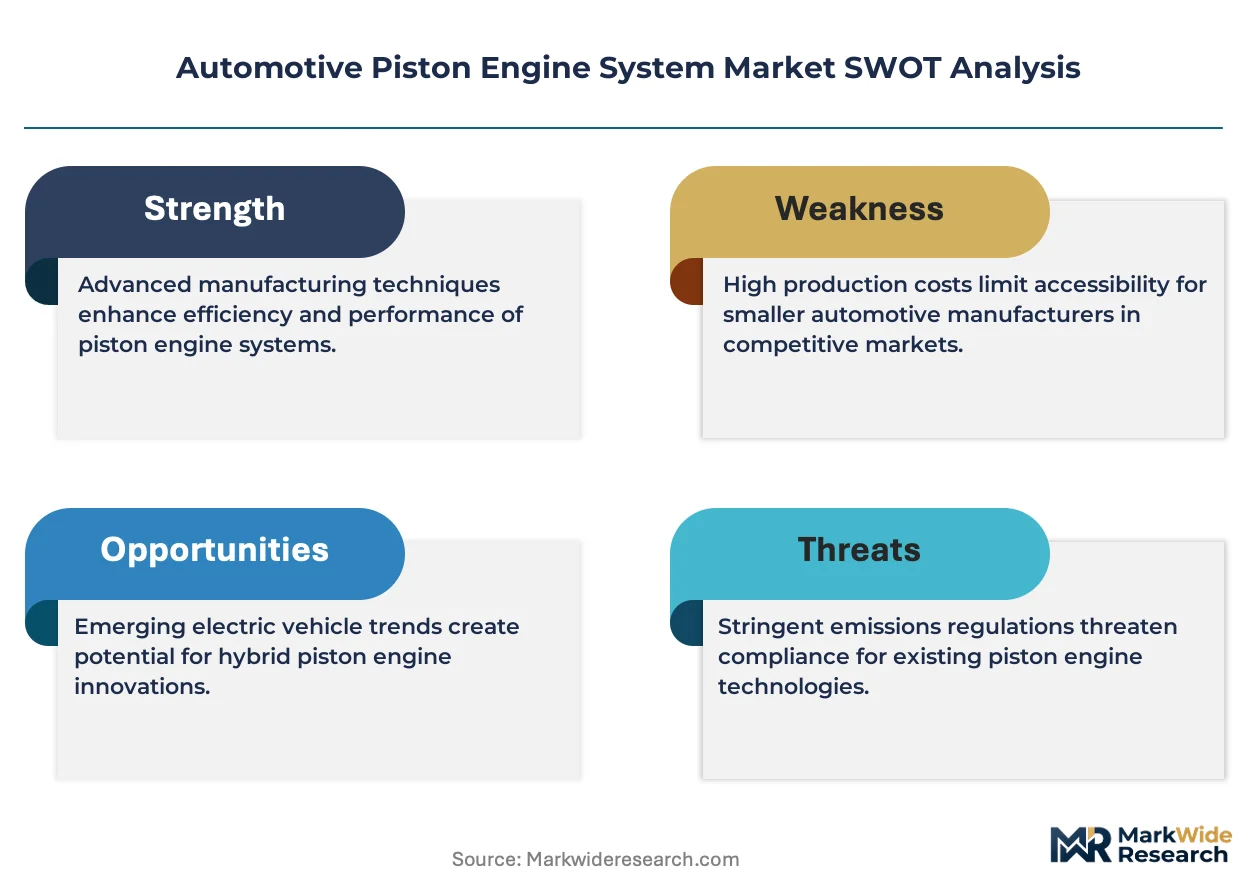
EPA Tier 4 and Euro 7 standards are forcing piston manufacturers to redesign crown geometries and ring packages for lower blow-by and reduced particulate formation, while India's BIS and China's MIIT impose parallel domestic testing protocols that fragment certification requirements. The EU F-Gas Regulation and REACH chemical restrictions additionally constrain lubricant and coating material selections across export-bound production. Stakeholders must monitor regulatory divergence between emission jurisdictions and decide whether to platform-engineer pistons for multi-market compliance or specialize in regional specification variants.
Market Dynamics
Euro 7 emission limits are compressing piston crown geometries and ring package designs, forcing foundries to retool for tighter blow-by tolerances while commercial vehicle OEMs accelerate procurement of reinforced skirt coatings for thermal load management.
Growth Catalysts
- Atkinson-cycle piston geometries:Hybrid powertrain integration demands modified compression ratios and valve timing compatibility, pulling demand from Japanese and South Korean OEM module suppliers.
- Euro 7 material specifications:Tightened particulate formation standards are expanding procurement of advanced ring land reinforcements and skirt coating formulations across German and Italian manufacturing clusters.
- Commercial vehicle fleet renewal:Heavy-duty diesel channel operators in India and Brazil are replacing aging piston assemblies to meet BIS and PROCONVE emission enforcement timelines.
Market Restraints
- Aluminum-silicon alloy volatility:Primary ingot price swings and scrap availability constraints in Chinese and Russian supply channels compress foundry margin structures.
- REACH chemical restrictions:Lubricant additive and coating material selections face ECHA authorization bottlenecks, extending formulation validation cycles for export-bound production.
- Electric powertrain substitution:Battery-electric commercial vehicle pilots in Nordic markets and California are displacing incremental piston engine system demand in urban delivery segments.
Strategic Opportunities
- India BIS domestic testing protocols:Fragmented certification requirements create white space for localized piston crown redesign services serving Maruti Suzuki and Tata Motors supply chains.
- Digital platform distribution:Consolidated e-procurement channels bypass traditional jobber networks, enabling direct-to-garage fulfillment for aftermarket ring and liner replacement in Poland and Czech Republic.
- China MIIT dual carbon alignment:Domestic OEMs are incentivizing lightweight piston architectures and reduced-friction ring packages for extended-range hybrid platforms.
Industry Challenges
- Thermal fatigue simulation expertise:Finite element analysis capability for crown temperature gradient modeling remains concentrated among German and Japanese engineering service providers, creating talent access bottlenecks for mid-tier foundries.
- Multi-jurisdiction certification timelines:Parallel EPA Tier 4, Euro 7, and China VI validation protocols extend product launch cycles and inflate testing capex for platform-engineered piston families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Piston Engine System Market |
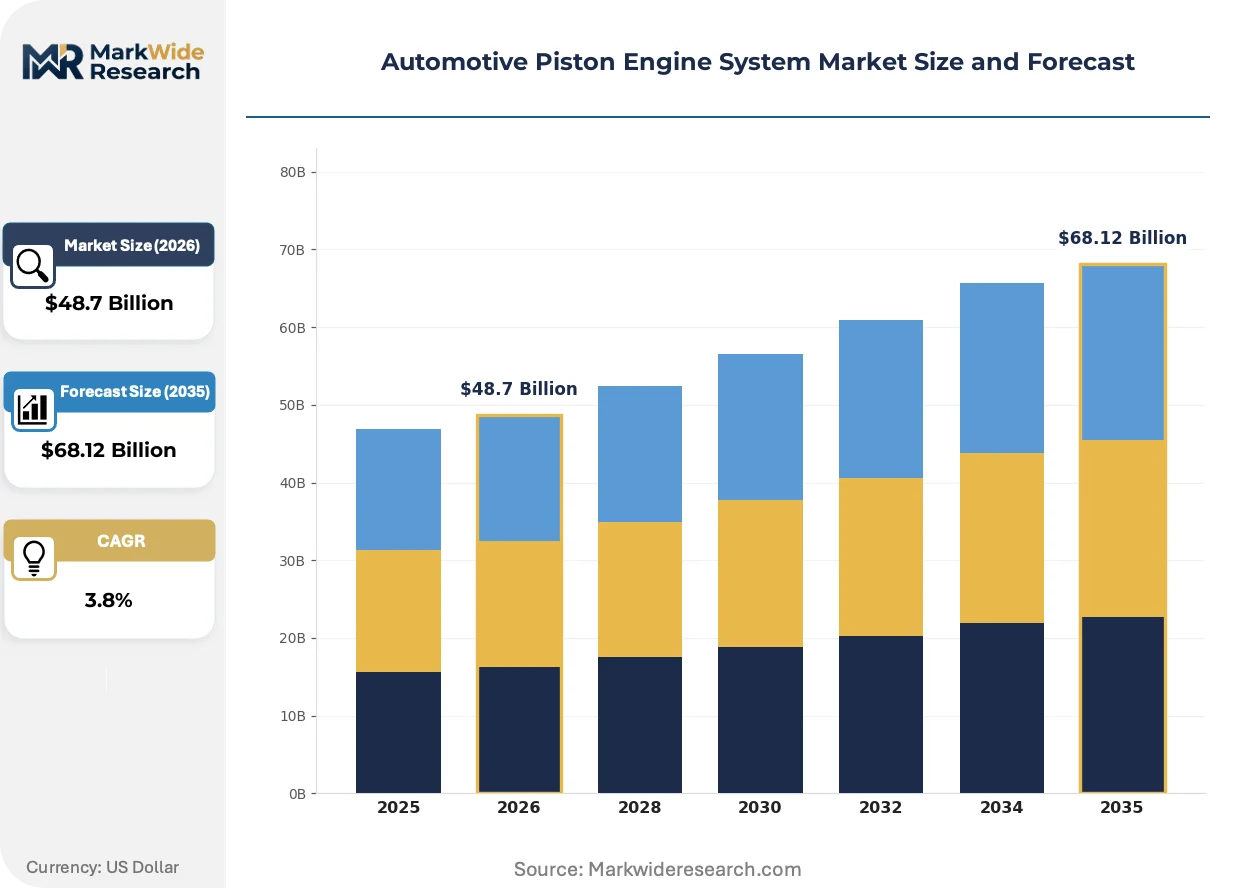
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $68.12 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Engines, V Engines, Flat Engines, Rotating Engines Technology: Hybrid, Gasoline, Diesel, Propane End User: OEMs, Aftermarket Providers, Dealerships, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, Sports Cars, Motorcycles |
| Companies Covered | MAHLE GmbH, Tenneco Inc., Aisin Seiki, Rheinmetall, Federal Mogul Holding LLC, Capricorn Automotive, Hitachi Automotive Systems, Shriram Pistons & Rings Ltd, Riken Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Piston Engine System Market Strategic Shifts
Active material substitution and combustion chamber optimization are compressing traditional design cycles, while regulatory divergence between emission jurisdictions fragments engineering resource allocation across product development teams.
Steel piston architectures with integrated cooling galleries are hybridizing thermal management capabilities for high-boost gasoline direct injection applications. European premium OEMs are adopting these assemblies for downsized 2.0L performance variants. The technology is hybridizing forged aluminum dominance in the 250-400 bar peak cylinder pressure segment.
EPA Tier 4 and Euro 7 particulate number limits are forcing simultaneous reduction of oil consumption and blow-by emissions. Piston manufacturers are deploying anodized ring grooves and plasma-transferred wire arc sprayed cylinder liners. Heavy-duty commercial vehicle segments in Germany and the US face the steepest compliance cost escalation.
Aftermarket procurement through consolidated digital platforms is displacing traditional jobber-tier distribution for piston rings and cylinder liners. Independent repair chains in France and Spain are sourcing directly from foundry-affiliated fulfillment networks. This channel compression is most visible in light-duty passenger vehicle service intervals across Southern European markets.
Automotive Piston Engine System Market Segmentation
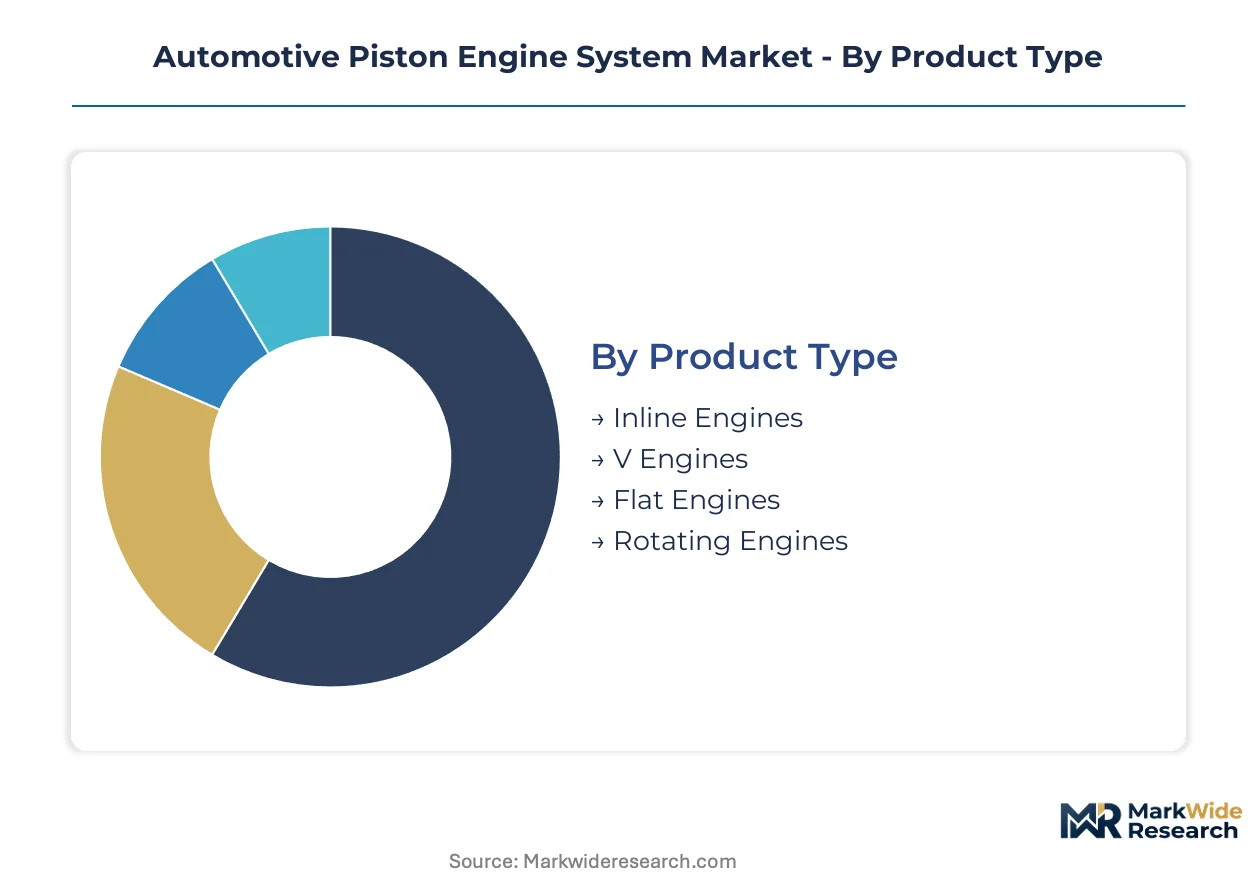
Piston engine system procurement patterns diverge sharply across powertrain architectures and compliance regimes. Segment-specific engineering requirements dictate foundry tooling investments and coating formulation portfolios.
Product Type:
Inline configurations serve cost-optimized mass production while V architectures command thermal management premiums in performance segments.
- Inline Engines:Cylinder banks arranged in single linear configuration enable simplified casting geometries and reduced machining complexity. Light-duty OEM assembly plants in Germany and Japan standardize these architectures for 1.0L-2.0L displacement volumes where packaging density and tooling amortization dominate procurement decisions.
- V Engines:Dual cylinder bank arrangements with 60-90 degree included angles distribute thermal loads across reinforced skirt structures. Premium SUV and heavy-duty commercial vehicle programs specify these architectures for 3.0L-6.0L applications where peak cylinder pressures exceed 250 bar.
- Flat Engines:Horizontally opposed cylinder configurations lower center of gravity for sports car and performance applications.
- Rotating Engines:Wankel-based architectures persist in niche motorcycle and range-extender hybrid applications.
Established volume favors Inline Engines; emerging adoption favors V Engines.
Technology:
Emission jurisdiction alignment determines fuel-specific piston crown geometries and ring package specifications.
- Hybrid:Atkinson-cycle modified compression ratios and reduced friction ring packages optimize for intermittent combustion duty cycles. Japanese and South Korean OEM module suppliers specify these architectures for extended-range electric platforms where thermal efficiency targets exceed 40 percent.
- Gasoline:Direct injection compatibility demands anodized ring grooves and reinforced top land structures for 350+ bar fuel pressures. European premium OEM foundries concentrate procurement of these specifications for downsized turbocharged variants.
- Diesel:High-swirl combustion chambers with steel piston architectures retain structural importance in Indian and Brazilian commercial vehicle fleet channels.
- Propane:Alternative fuel conversions require hardened valve seats and modified compression ratios for gaseous fuel energy densities.
Diesel retains installed base dominance; hybrid specifications expand most quickly.
End User:
Channel structure determines fulfillment velocity and technical support intensity.
- OEMs:Integrated powertrain module suppliers specify piston-ring-liner matched sets with finite element validated thermal profiles. German and Italian manufacturing clusters concentrate procurement engineering resources for platform-engineered families.
- Aftermarket Providers:Consolidated digital platforms bypass traditional jobber networks for direct-to-garage ring and liner fulfillment. Independent repair chains in Poland and Czech Republic drive demand for standardized replacement geometries.
- Dealerships:Authorized service channels access OEM-affiliated parts distribution for warranty-compliant repairs.
- Fleet Operators:Commercial vehicle maintenance depots procure remanufactured assemblies for total cost of ownership optimization.
OEMs anchor engineering value capture; aftermarket channels gain share fastest.
Application:
Vehicle duty cycles dictate thermal fatigue margins and skirt coating durability requirements.
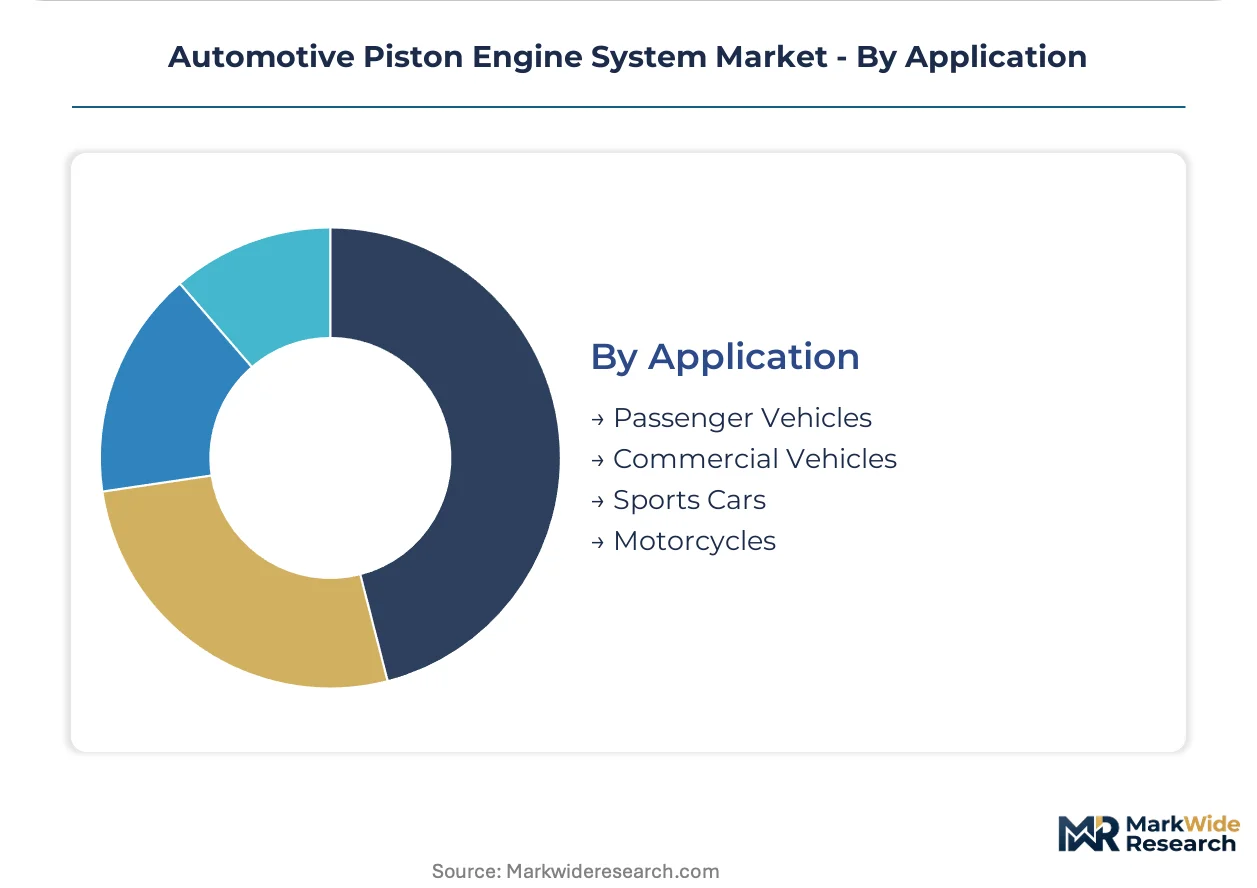
- Passenger Vehicles:Light-duty service intervals prioritize low-tension oil control rings and reduced mass piston architectures for fuel economy certification. European and Japanese OEM programs dominate specification development for 1.0L-2.5L displacements.
- Commercial Vehicles:Heavy-duty diesel applications demand steel piston assemblies with integrated cooling galleries for 500,000+ kilometer durability targets. Indian BIS and Brazilian PROCONVE enforcement timelines accelerate fleet renewal procurement.
- Sports Cars:Forged aluminum and steel hybrid architectures serve 400+ bar peak cylinder pressures in performance variants.
- Motorcycles:Compact single and twin-cylinder geometries prioritize power-to-weight ratios in Asian manufacturing clusters.
Commercial Vehicles concentrate procurement volume; passenger vehicle specifications fragment fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German foundry clusters while Indian manufacturers absorb margin compression from BIS compliance costs and aluminum-silicon alloy volatility.
Germany
MAHLE GmbH and Rheinmetall anchor precision manufacturing clusters around Stuttgart and Neuss. Euro 7 emission limits tighten material specifications for pistons and rings, forcing foundries to retool for blow-by tolerances below 0.5%. The Baden-Württemberg engineering corridor concentrates thermal fatigue simulation expertise for crown temperature gradient modeling.
United States
EPA Tier 4 standards drive heavy-duty diesel fleet renewal across Texas and California freight corridors. Steel piston architectures with integrated cooling galleries penetrate premium SUV segments. The Detroit manufacturing belt sustains forged aluminum production for 250-400 bar peak cylinder pressure applications.
China
MIIT dual carbon alignment incentivizes lightweight piston architectures for extended-range hybrid platforms. Yangtze River Delta foundries supply Atkinson-cycle geometries to domestic OEM module producers. Shanghai-based engineering centers validate reduced-friction ring packages for 40 percent thermal efficiency targets.
India
BIS domestic testing protocols fragment certification requirements for Maruti Suzuki and Tata Motors supply chains. Commercial vehicle operators in Maharashtra and Gujarat replace aging piston assemblies ahead of enforcement timelines. The Pune industrial corridor concentrates remanufactured assembly production for total cost of ownership optimization.
Japan
METI-guided hybrid powertrain integration pulls demand for modified compression ratios and valve timing compatibility. Aisin Seiki anchors integrated powertrain module production in the Aichi prefecture manufacturing belt. Toyota City engineering centers optimize piston geometries for intermittent combustion duty cycles exceeding 500,000 kilometer durability targets.
Automotive Piston Engine System Market Competitive Environment
Integrated powertrain module suppliers and precision forging specialists split the market between platform-engineered OEM supply and aftermarket fulfillment channels. The vendor base concentrates in German and Japanese engineering corridors where thermal fatigue simulation capabilities create entry barriers. Three archetypes dominate: foundry-affiliated fulfillment networks, ring-and-liner portfolio diversifiers, and hybrid powertrain geometry specialists. Competitive moves center on digital platform distribution bypassing traditional jobber networks and localized crown redesign services for fragmented certification regimes.
Within the integrated module supplier tier, MAHLE GmbH and Aisin Seiki exemplify divergent geographic anchoring strategies. MAHLE leverages its forged piston foundry network across European manufacturing clusters. Aisin Seiki occupies a position within Asian OEM supply chains for powertrain module production. Tenneco Inc. represents the ring-and-liner portfolio archetype competing through cylindrical component diversification.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Tenneco Inc. |
| Aisin Seiki |
| Rheinmetall |
| Federal Mogul Holding LLC |
| Capricorn Automotive |
| Hitachi Automotive Systems |
| Shriram Pistons & Rings Ltd |
| Riken Corporation |
| Others |
Value Chain & Pricing Dynamics
German foundry clusters around Stuttgart and Neuss concentrate precision forging capacity for Euro 7-compliant piston assemblies, anchoring margin capture downstream at OEM module suppliers and tier-1 ring manufacturers. This upstream concentration enables configured-to-order pricing premiums for thermal fatigue-validated geometries while standard replacement geometries compete on aluminum-silicon alloy cost pass-through.
Pricing Analysis
Configured-to-order pricing for Euro 7-validated piston crown geometries commands 15-25% premiums over standard replacement specifications. Price differentiation rests on certification grade and volume scale, with BIS-compliant variants for Indian OEMs trading at intermediate tiers. Cost compression in standard aftermarket rings is intensifying because consolidated digital platforms bypass traditional jobber markups. Fleet operators exhibit highest price sensitivity, while German premium OEMs prioritize thermal validation over unit cost.
Supply Chain Analysis
Tariff exposure between China and European Union markets dominates supply chain risk planning for aluminum-silicon alloy procurement. Foundry capacity concentrates in Germany, China, and Japan, with primary ingot sourcing drawing from Chinese and Russian supply channels. Single-source vulnerability persists in anodized ring groove coating formulations subject to REACH authorization bottlenecks. Distribution runs through foundry-affiliated fulfillment networks for direct-to-garage aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA Tier 4, Euro 7, and BIS testing protocols creates white space for specialized piston crown redesign services, fragmenting what was consolidated platform engineering.
For Market Incumbents: Entrench thermal fatigue simulation capabilities through captive engineering service acquisitions in the Baden-Württemberg corridor. Prioritize backward integration into anodized ring groove coating supply to offset REACH authorization delays. Battery-electric commercial vehicle pilots in Nordic markets threaten heavy-duty diesel replacement demand; defend through extended-range hybrid geometry partnerships. For New Entrants and Emerging Players: Pursue localized crown redesign services for India's BIS fragmented certification regime, targeting Maruti Suzuki and Tata Motors supply chain entry. Digital platform distribution channels in Poland and Czech Republic offer lowest barrier aftermarket penetration. Lead with direct-to-garage fulfillment partnerships rather than jobber network replication. For Investors and Strategic Acquirers: Capital is best deployed toward thermal simulation-enabled foundry specialists with EPA-Euro 7 dual certification track records. The five-to-ten year viability window favors platform-engineered OEM suppliers over pure aftermarket replacement plays. Monitor steel piston architecture adoption rates in 250-400 bar peak cylinder pressure segments as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces retooling costs for multi-jurisdiction piston families serving Euro 7 and EPA Tier 4. |
| Backward Integration | Captures anodized ring groove coating capacity to bypass REACH authorization bottlenecks. |
| Digital Platform Partnership | Enables direct-to-garage fulfillment bypassing traditional jobber networks in Southern Europe. |
| Hybrid Geometry Development | Positions for Atkinson-cycle demand from Japanese and South Korean OEM module suppliers. |
| Regional Certification Investment | Creates BIS-compliant redesign capability for Maruti Suzuki and Tata Motors supply chains. |
Study Parameters
Desk research of vehicle production databases, customs trade filings, and regulatory submission records preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and foundry operations managers. Primary fieldwork across German, Japanese, and Indian manufacturing clusters was cross-validated against IHS Markit registration data and MIIT production disclosures. Bottom-up unit economics and top-down market sizing were triangulated to constrain variance.
Assumptions held fixed include current Euro 7 enforcement timelines, aluminum-silicon alloy price band stability, and hybrid powertrain penetration curves across the analysis window. Segmentation modeling incorporated vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from regression against historical displacement volume trends and projected fleet renewal cycles, with thermal efficiency targets and emission compliance cost curves as primary demand shapers.
Sensitivities concentrate around battery-electric commercial vehicle adoption rates, REACH authorization timeline slippage, and China-Russia primary ingot supply disruptions. Forecasts reflect these assumptions without contingency weighting. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Tow Bar Market
Automotive Parts
China Automotive Parts Aluminum Die Casting Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Europe Ball Bearings Market
Automotive Parts
South Korea Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Brake Wheel Cylinder Market
Automotive Parts
Automotive Vents Market
Automotive Parts
Timing Gear Market
Automotive Parts
Global Aerodynamic Automotive Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
Undercarriage Systems Market
Automotive Parts
Global Automotive Adaptive Suspension System Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
Rear Spoiler Market