
 Global Intelligent Road System Market | 2026-2036
Global Intelligent Road System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intelligent Road System Market Intelligence
Edge-to-cloud data fusion is tilting intelligent road architectures toward distributed computing nodes. Kapsch TrafficCom AG leverages its European installed base to anchor toll collection modernization programs. Siemens AG sustains R&D intensity across radar-based incident detection systems. Huawei Technologies Co., Ltd. dominates video analytics deployments in Asia-Pacific smart highway contracts.
An intelligent road system integrates sensors, communication networks, and computing platforms to monitor traffic flow, detect incidents, and automate roadside responses with sub-second latency requirements. These systems primarily serve to reduce congestion-related losses and prevent fatalities through real-time intervention. Traffic Management systems occupy the largest revenue pool given legacy infrastructure retrofit cycles, while Machine Learning applications represent the fastest-expanding technology tier as neural models displace rule-based signal optimization. Video Analytics competes closely with LiDAR for urban mobility budgets where object classification accuracy determines procurement awards.
The U.S. Department of Transportation coordinates with state-level agencies to enforce NHTSA guidelines on connected vehicle interoperability, while the EU AI Act imposes conformity requirements on automated decision systems in traffic management. China's MIIT and MEE jointly administer GB standards for vehicle-to-infrastructure communication protocols. Stakeholders must weigh regulatory fragmentation against standardization momentum when selecting technology partners for multi-jurisdiction deployments.
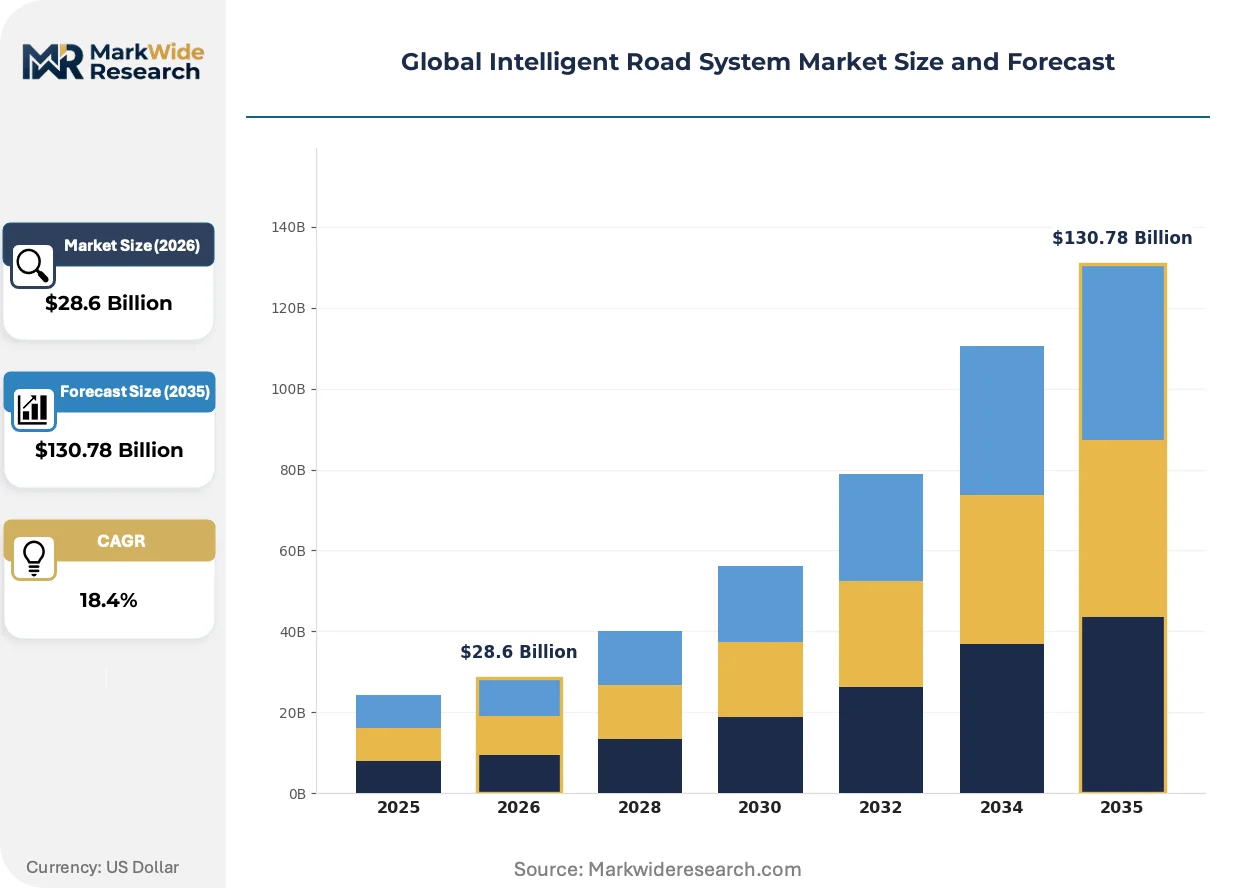
Market Dynamics
Edge computing architectures are forcing a wholesale redesign of traffic management infrastructure as municipalities demand sub-100-millisecond response times for automated incident intervention. This latency imperative is redistributing computational load from centralized cloud servers to roadside cabinets and vehicle-mounted units.
Growth Catalysts
- EU AI Act Conformity Mandates:Automated decision systems in traffic signal control must now meet algorithmic transparency requirements, accelerating replacement of legacy rule-based controllers across German and French urban corridors.
- China's MEE Smart Corridor Directives:Provincial environmental authorities in Jiangsu and Zhejiang are mandating vehicle-to-infrastructure integration along freight-heavy expressways to enable real-time emissions monitoring and dynamic routing.
- LiDAR Cost Curves:Solid-state sensor manufacturing scale-up is collapsing unit economics for 3D object detection, enabling dense urban deployments previously constrained by mechanical scanning device pricing.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium processing capacity clusters in China's Inner Mongolia region, exposing radar and motor actuator supply chains to export quota volatility.
- F-Gas Regulation Hardware Lock-in:EU restrictions on hydrofluorocarbon coolants are stranding existing roadside server cabinet installations that cannot accommodate alternative thermal management retrofits.
- Silicon Photonics Yield Defects:Co-packaged optical interconnects for high-bandwidth edge nodes remain constrained by wafer-level testing failures above 20% at leading foundries.
Strategic Opportunities
- India's NHAI Smart Highway Tenders:National highway authority procurement for 5,000 kilometers of instrumented corridors remains undersupplied by qualified system integrators familiar with tropical climate hardware specifications.
- V2X-Cellular Convergence:Integration of dedicated short-range communication with 5G network slicing is opening unified connectivity platforms that eliminate redundant roadside radio infrastructure.
- Japan's METI Carbon-Neutral Roadmap:Ministry incentives for solar-integrated pavement and kinetic energy harvesting are creating first-mover advantages for suppliers with photovoltaic-roadway pilot credentials.
Industry Challenges
- Embedded Systems Security Certification:ISO/SAE 21434 automotive cybersecurity standards are extending to roadside units, imposing 18-24 month validation timelines on firmware updates for connected intersection controllers.
- Multi-Vendor Integration Complexity:Procurement packages combining Kapsch tolling hardware, Siemens detection arrays, and Huawei video analytics require custom middleware development that inflates deployment risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intelligent Road System Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $130.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Traffic Management, Incident Detection, Adaptive Lighting, Toll Collection, Weather Monitoring Technology: Wireless Sensor Networks, Machine Learning, Video Analytics, Radar Systems, LiDAR Application: Urban Mobility, Highway Safety, Emergency Response, Freight Logistics, Smart Parking End User: Municipal Authorities, Infrastructure Operators, Fleet Managers, Road Safety Agencies, Transport Planners |
| Companies Covered | Siemens AG, Hitachi Ltd., Thales Group, Huawei Technologies Co., Ltd., Kapsch TrafficCom AG, TomTom International BV, Indra Sistemas S.A., Verra Mobility, Cubic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intelligent Road System Market Strategic Shifts & Innovations
Neural network inference at the roadside is compressing decision loops from seconds to milliseconds, enabling automated responses that were previously impossible with human-in-the-loop architectures. This shift is redrawing competitive boundaries between sensor manufacturers, telecom operators, and cloud infrastructure providers.
Federated learning architectures are rendering obsolete centralized model training paradigms that required bulk transmission of sensitive vehicle trajectory data to remote data centers. Municipal traffic authorities in Singapore and Dubai are piloting edge-coordinated parameter updates that keep raw video feeds local while refining detection accuracy. Privacy-preserving computation is becoming a procurement discriminator for systems handling license plate and facial imagery.
The EU AI Act's risk classification framework is imposing conformity assessment obligations on automated traffic signal optimization systems deemed high-risk due to their direct safety implications. Manufacturers must now maintain technical documentation, human oversight protocols, and accuracy logging that exceed legacy CE marking requirements. German KBA type approval processes are expanding to encompass machine learning model versioning and rollback procedures.
Performance-based maintenance contracts are displacing traditional hardware warranty arrangements as primary procurement vehicles for intelligent road infrastructure. Australian state transport departments and UK highway agencies are contracting integrated service providers against availability metrics and incident detection accuracy rather than capital expenditure schedules. Vendor selection increasingly weights predictive maintenance algorithms and spare parts logistics over initial equipment specifications.
Global Intelligent Road System Market Segmentation
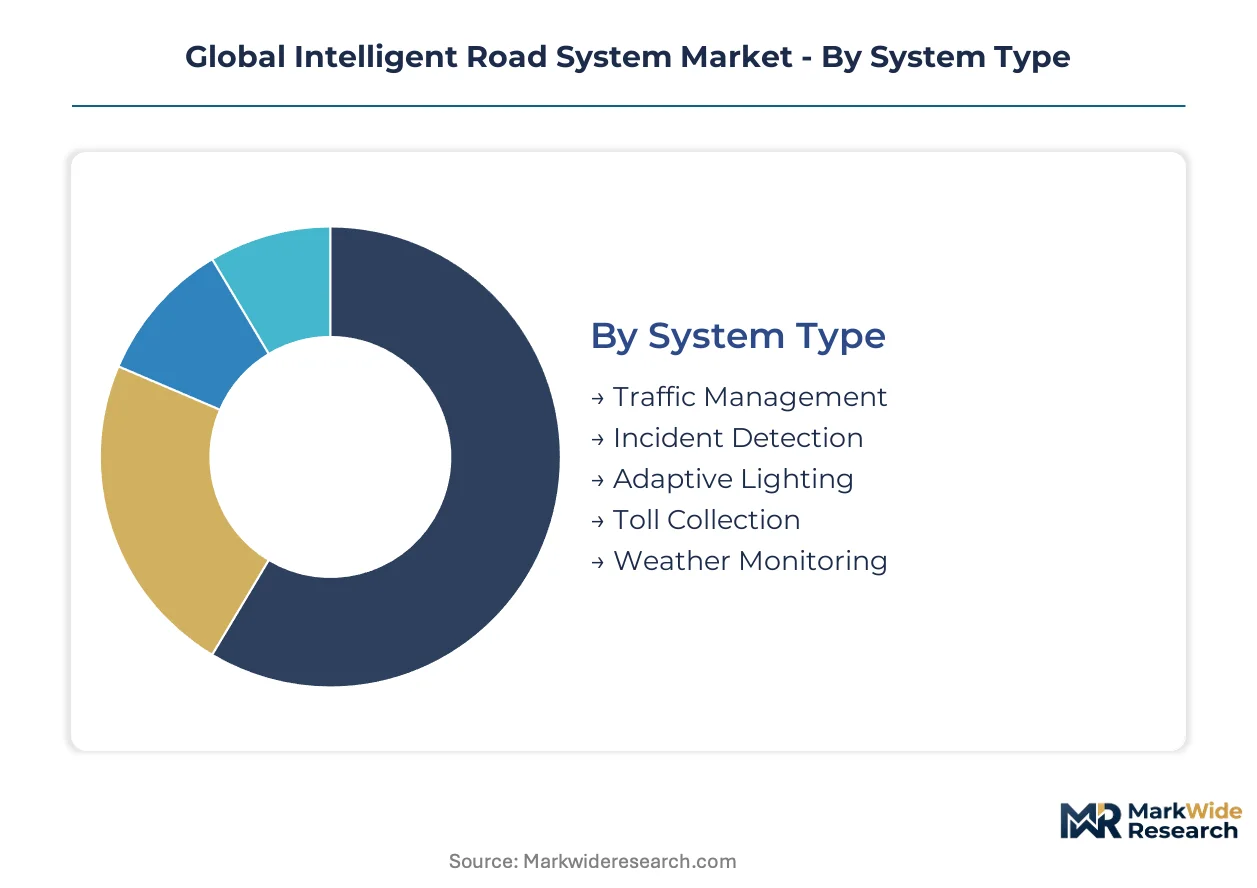
Intelligent road system procurement patterns diverge sharply between legacy infrastructure retrofits and greenfield deployments. Municipal buyers prioritize interoperability across vendor ecosystems, while fleet operators demand real-time data feeds with standardized APIs.
System Type:
Mature corridor management solutions coexist with emerging automated response architectures as procurement cycles split between refresh and replacement investments.
- Traffic Management:Adaptive signal control and corridor optimization software dominate municipal procurement volumes. German and Japanese urban authorities are replacing legacy rule-based controllers with algorithmic systems to satisfy EU AI Act transparency mandates.
- Incident Detection:Radar arrays and video analytics fusion enable sub-second crash identification and automated emergency dispatch. China's eastern coastal provinces mandate these systems along freight corridors to reduce collision-related freight delays.
- Adaptive Lighting:LED luminaries with occupancy-based dimming reduce energy consumption on low-traffic rural routes.
- Toll Collection:Multi-lane free-flow systems are displacing plaza-based gantries on European expressways.
- Weather Monitoring:Road surface sensors and atmospheric stations feed predictive maintenance algorithms for ice and hydroplaning risk.
Traffic Management handles the majority of throughput; Incident Detection is climbing the fastest on share.
Technology:
Cost tier differentiation separates proven sensing modalities from experimental edge-computing architectures requiring custom silicon.
- Machine Learning:Neural signal optimization models displace fixed-timing plans in high-congestion corridors. Singapore and Dubai traffic authorities deploy federated learning architectures that retain raw video locally while refining detection parameters.
- Video Analytics:Edge-deployed object classification enables automated incident verification without cloud transmission latency. Privacy-preserving computation variants are becoming procurement discriminators for license plate recognition systems.
- Wireless Sensor Networks:Mesh deployments monitor pavement strain and bridge structural health.
- Radar Systems:77GHz automotive-grade units are penetrating roadside detection budgets as solid-state manufacturing scales.
- LiDAR:Solid-state sensor cost curves are collapsing unit economics for dense urban 3D mapping deployments.
Video Analytics commands the largest installed base; Machine Learning exhibits the steepest expansion trajectory.
Application:
Customer type determines latency requirements, with emergency services demanding millisecond response and freight operators prioritizing predictive routing over real-time intervention.
- Urban Mobility:Signal coordination and multimodal integration dominate smart city procurement in Jiangsu and Zhejiang provinces under MEE smart corridor directives. Congestion pricing and curb management applications are accelerating hardware refresh cycles.
- Highway Safety:Automated incident detection and wrong-way driver alerts target fatality reduction on high-speed corridors. Australia's state transport departments contract against availability metrics rather than capital schedules.
- Emergency Response:Automated dispatch integration with fire and ambulance services requires sub-100-millisecond edge computing architectures.
- Freight Logistics:Dynamic routing and weigh-in-motion systems optimize heavy vehicle flows.
- Smart Parking:Occupancy sensors and mobile payment integration address last-mile congestion.
Urban Mobility absorbs the greatest deployment volume; Highway Safety is expanding most quickly on policy priority.
End User:
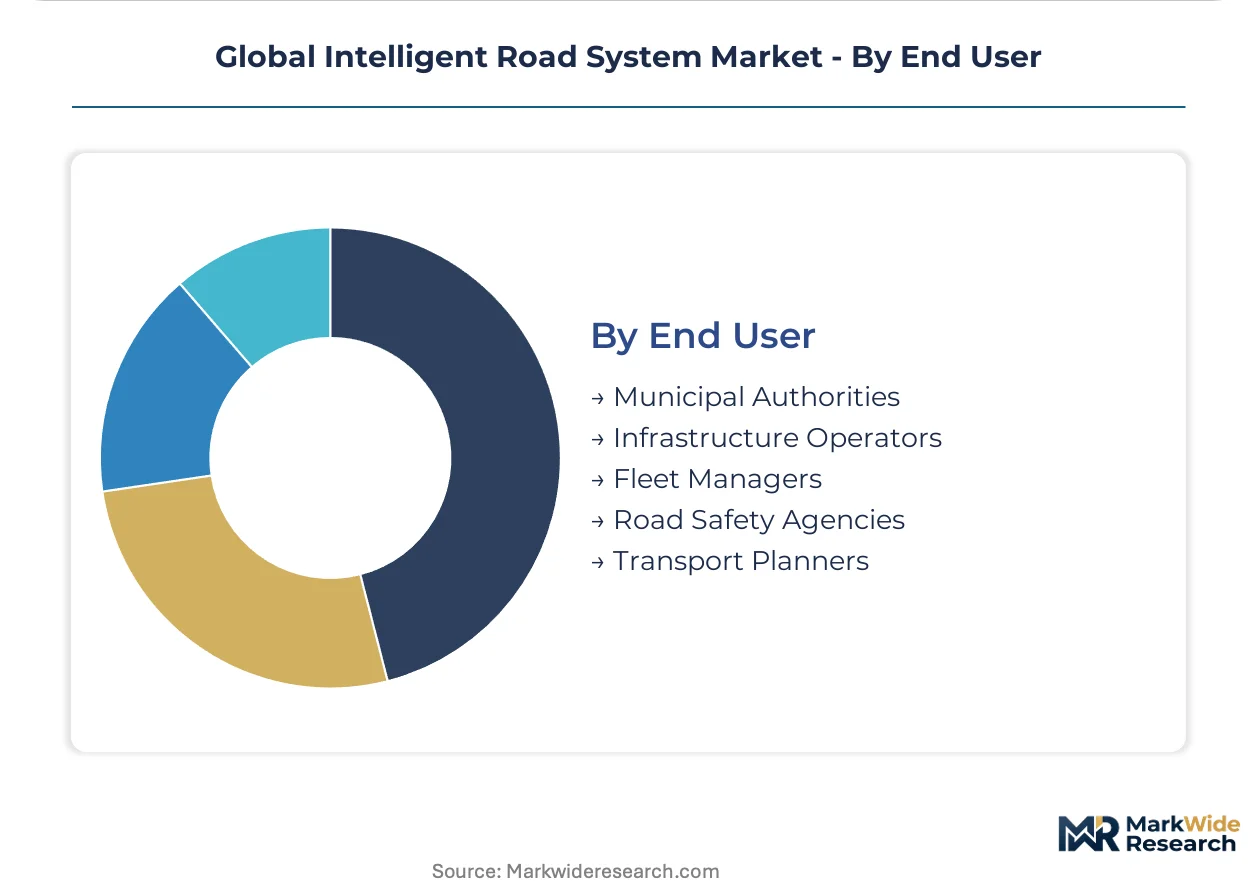
Procurement sophistication varies across public and private balance sheets, with municipal authorities favoring performance-based maintenance and fleet managers demanding data sovereignty.
- Municipal Authorities:City and regional governments purchase integrated traffic management suites with 10-15 year service contracts. EU AI Act conformity assessments now extend procurement timelines for automated decision systems.
- Infrastructure Operators:Toll road concessionaires and tunnel operators prioritize availability guarantees and predictive maintenance algorithms over initial equipment specifications.
- Fleet Managers:Commercial vehicle operators purchase V2X integration for platooning and cooperative adaptive cruise control.
- Road Safety Agencies:National regulators mandate interoperability standards and cybersecurity certification under ISO/SAE 21434 extensions.
- Transport Planners:Metropolitan planning organizations aggregate multi-source data for long-term corridor investment decisions.
Municipal Authorities dominate procurement volume; Infrastructure Operators are gaining share fastest on performance-contracting adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement concentrates in jurisdictions with active infrastructure modernization mandates. Germany, Japan, China, the United States, and Australia each exhibit distinct buyer archetypes shaped by regulatory frameworks and funding mechanisms.
Germany
Urban authorities in Berlin and Munich are replacing legacy signal controllers with algorithmic systems. The EU AI Act imposes conformity assessments on automated traffic decision systems, extending procurement timelines. The KBA type approval process now encompasses machine learning model versioning for roadside units.
Japan
METI carbon-neutral roadmaps are accelerating solar-integrated pavement pilots. The ministry incentivizes kinetic energy harvesting technologies for highway infrastructure. Osaka and Nagoya metropolitan governments are tendering for instrumented corridors with edge-computing architectures.
China
Jiangsu and Zhejiang provincial authorities mandate vehicle-to-infrastructure integration along freight corridors under MEE smart corridor directives. The MIIT and MEE jointly administer GB standards for V2I communication protocols. Shenzhen and Shanghai clusters dominate video analytics deployment contracts.
United States
State DOTs coordinate with the NHTSA on connected vehicle interoperability guidelines. California and Texas authorities are expanding procurement of adaptive signal networks. The U.S. Department of Transportation enforces cybersecurity standards extending ISO/SAE 21434 to roadside infrastructure.
Australia
State transport departments contract integrated service providers against availability metrics rather than capital schedules. New South Wales and Victoria are piloting performance-based maintenance arrangements for incident detection systems. The TGA cybersecurity framework influences procurement specifications for connected road infrastructure.
Global Intelligent Road System Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement tiers. The market exhibits moderate concentration with established traffic management incumbents anchoring municipal relationships. Three archetypes dominate: European infrastructure conglomerates with legacy installed bases, Asian technology conglomerates with video analytics scale, and specialized tolling system integrators with regional lock-in. Competitive moves center on M&A for sensor technology capabilities and strategic partnerships for edge-computing software stacks.
Within the European infrastructure tier, Siemens AG and Kapsch TrafficCom AG exemplify contrasting positioning strategies. Siemens anchors radar-based detection system deployments through sustained R&D intensity, while Kapsch leverages its continental installed base to secure toll collection modernization programs. Huawei Technologies Co., Ltd. occupies a distinct position in Asia-Pacific procurement, representing the technology-scale archetype that dominates video analytics contract awards.
| Leading Market Players |
|---|
| Siemens AG |
| Hitachi Ltd. |
| Thales Group |
| Huawei Technologies Co., Ltd. |
| Kapsch TrafficCom AG |
| TomTom International BV |
| Indra Sistemas S.A. |
| Verra Mobility |
| Cubic Corporation |
| Others |
Cost & Logistics Intelligence
Rare earth magnet processing capacity clusters in China's Inner Mongolia region, anchoring margin capture for radar and motor actuator suppliers while downstream system integrators face squeezed procurement leverage on hardware refresh cycles.
Pricing Analysis
Cost-plus contracts with rare earth indexation dominate procurement for roadside detection hardware. Three-tier pricing structure across premium-certified, standard-compliant, and economy-grade equipment separates EU AI Act-conformant systems from legacy controllers. Cost compression in the economy tier is intensifying because solid-state LiDAR manufacturing scale-up is collapsing unit economics. Municipal authorities exhibit the highest price sensitivity due to budget approval cycles, while toll road concessionaires prioritize availability guarantees over upfront capital outlay.
Supply Chain Analysis
Upstream feedstock concentration in China for neodymium and dysprosium, South Korea for advanced semiconductor packaging, and Taiwan for silicon photonics wafers creates multi-node dependency. Radar systems and edge-computing nodes draw from automotive-grade 77GHz chipsets, co-packaged optical interconnects, and solid-state LiDAR emitters. Single-source vulnerability in rare earth magnet supply chains exposes hardware refresh programs to export quota volatility. Distribution runs through system integrators with multi-vendor middleware capabilities serving municipal procurement authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intelligent road system market is recovering from pandemic-delayed infrastructure procurement, with EU AI Act compliance deadlines and China's MEE smart corridor mandates serving as cyclical accelerators for hardware replacement investment.
For Market Incumbents: Entrench position through backward integration into solid-state LiDAR manufacturing and captive rare earth magnet sourcing to defend against supply chain volatility. Siemens and Kapsch should anchor municipal relationships by pre-certifying edge-computing architectures under evolving ISO/SAE 21434 cybersecurity extensions before challenger systems achieve validation.
For New Entrants and Emerging Players: India's NHAI smart highway tenders for tropical climate corridors represent the most penetrable white-space opportunity, given undersupply from qualified integrators. Target performance-based maintenance contracts in Australian state transport departments where availability metrics displace capital schedules. Lead with federated learning architectures that preserve data sovereignty for privacy-sensitive municipal buyers.
For Investors and Strategic Acquirers: Capital is best deployed toward edge-computing software specialists with video analytics scale and V2X protocol certification. Long-term viability hinges on positioning for 5G network slicing convergence that eliminates redundant roadside radio infrastructure. Monitor Japan's METI carbon-neutral roadmap pilot awards as an inflection indicator for solar-integrated pavement technology maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Architecture Certification | ISO/SAE 21434 validation accelerates procurement timelines for automated intersection controllers under EU AI Act mandates. |
| Federated Learning Partnership | Singapore and Dubai traffic authorities pilot privacy-preserving parameter updates that retain raw video feeds locally. |
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts with Inner Mongolia processors mitigate export quota volatility for radar actuator production. |
| V2X-Cellular Platform Integration | 5G network slicing convergence eliminates redundant roadside DSRC infrastructure for unified connectivity platforms. |
| Solar-Pavement Pilot Credential | Japan's METI incentives reward first-mover suppliers with photovoltaic-roadway deployment experience in carbon-neutral tenders. |
Research Approach
A spread of perspectives from municipal traffic authority procurement officers, toll road concessionaire operations directors, edge-computing platform engineers, and automotive Tier 1 supplier technology strategists converged on the working assumptions. Primary interview insights were cross-validated against secondary sources including NHTSA connected vehicle guidance documents, EU AI Act implementing acts, MIIT GB standard filings, and state transport department tender databases. Bottom-up project pipeline enumeration was triangulated with top-down infrastructure investment budget aggregation across the analysis window.
Demand-supply balance modeling anchored volume projections on retrofit cycle timing for legacy signal controllers and greenfield smart corridor deployment schedules. Segmentation dimensions spanned system type, technology tier, application latency requirement, and end-user procurement sophistication. CAGRs were derived from regression-weighted historical deployment trajectories and policy-mandated replacement deadlines. Industry-specific inputs included F-Gas Regulation hardware lock-in effects and solid-state LiDAR cost curve assumptions.
Practitioners should monitor rare earth export quota announcements, EU AI Act conformity assessment timeline shifts, and 5G network slicing commercialization milestones for early signals of forecast revision. Cross-checking against TGA cybersecurity framework updates and KBA type approval process expansions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Parking Finder Apps Market
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Europe Hyperloop Technology Market
Smart Transportation Solutions
Smart Fleet Management Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Traffic Monitoring Market
Smart Transportation Solutions
Smart Roads Market
Smart Transportation Solutions
Mobility Technologies Market
Smart Transportation Solutions
Global IoT in Transportation Market
Smart Transportation Solutions
Intelligent Traffic Management Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
GCC Electronic Toll Collection Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Connected Parking Solutions Market