
 Farm Trucks Market | 2026-2036
Farm Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Farm Trucks Market Analysis
Modular chassis-and-body bundling is consolidating buyer choice around configurable platforms that accommodate multiple implements within a single vehicle registration. John Deere leverages its integrated precision-ag ecosystem to anchor premium positioning in North American dealer networks. AGCO Corporation competes through specialized Fendt and Massey Ferguson configurations tailored to European mixed-farming operations. Kubota Corporation extends its dominance in compact utility segments across East Asian rice-growing prefectures and Australian broadacre stations.
Farm trucks are motorized commercial vehicles engineered for off-highway agricultural duty cycles, typically featuring reinforced frames, high-torque diesel powertrains, and payload ratings from three to thirty-plus tons for hauling grain, livestock, equipment, and inputs across unpaved terrain. Diesel fuel types still occupy the majority of installed fleets due to energy density and refueling infrastructure, though electric prototypes are gaining trial placements in cooperative-owned operations with centralized depot charging. Pickup trucks lead unit volume in light-duty and medium-duty load capacity bands where individual farmers and small cooperatives dominate procurement, while heavy-duty dump trucks and stake trucks command stronger margin pools in enterprise-scale agricultural logistics.
EPA Tier 4 Final and upcoming CARB requirements in the United States, alongside EU Stage V non-road emission standards enforced by national type-approval authorities in Germany and France, are forcing engine redesigns and after-treatment cost pass-throughs that reshape fleet replacement timing. The USDA and EU Common Agricultural Policy indirect vehicle investment incentives further condition purchasing power across their respective territories. Stakeholders must monitor regulatory divergence between North American and European emission compliance pathways when configuring product portfolios and after-sales service networks.
Market Dynamics
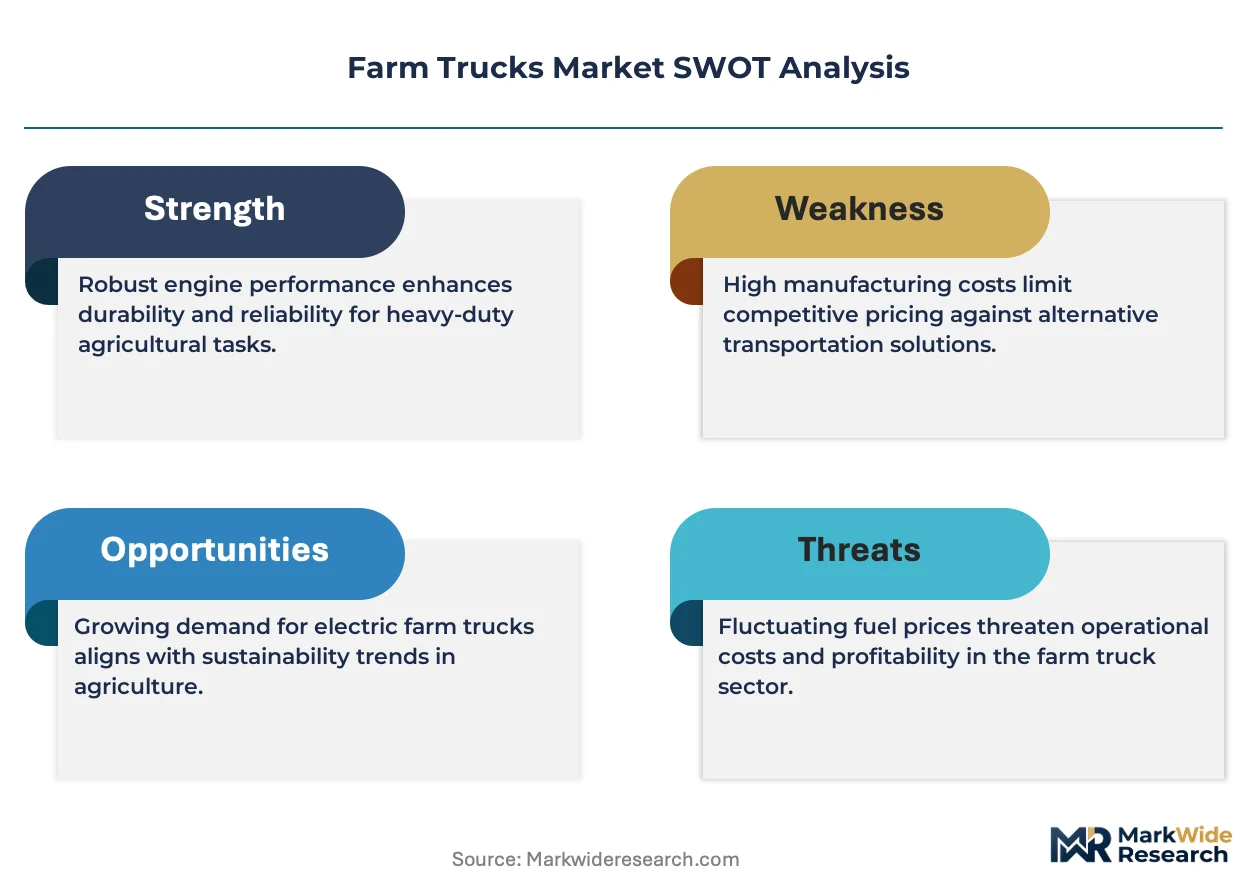
EPA Tier 4 Final and Euro VI emission architectures are compressing replacement cycles across heavy-duty farm truck fleets as compliance costs force early retirement decisions and accelerate platform consolidation around modular chassis systems.
Growth Catalysts
- EPA Tier 4 Final mandates:United States grain operations face forced fleet turnover as legacy pre-2015 engines lose grandfathered operating exemptions in non-attainment zones.
- Livestock logistics density:Concentrated animal feeding operations in the Texas Panhandle and Nebraska Sandhills drive demand for refrigerated stake truck configurations with biosecurity washdown compatibility.
- Battery-electric depot trials:Cooperative-owned operations with centralized grain elevators in Iowa and Illinois are absorbing early electric prototypes for sub-50-mile radius hauls.
Market Restraints
- After-treatment cost pass-through:Diesel particulate filter and selective catalytic reduction systems add fifteen to twenty-five percent to powertrain unit costs, squeezing margin pools for mid-scale equipment dealers.
- Steel and aluminum input volatility:Reinforced frame manufacturing depends on hot-rolled coil pricing that fluctuates with scrap metal flows from construction demolition cycles.
- Refueling infrastructure lock-in:Rural diesel distribution networks through farm supply cooperatives create path dependency that slows electric charging infrastructure capital deployment.
Strategic Opportunities
- Autonomous convoy pilot zones:Saskatchewan and Manitoba provincial regulators are permitting limited self-driving grain truck trials on designated rural highway corridors.
- Precision-ag data integration:Telematics-enabled payload monitoring converges with yield mapping software to create subscription revenue streams for OEM service divisions.
- EU Common Agricultural Policy indirect support:French and German farm modernization grants now explicitly include commercial vehicle fleet upgrades within eligible capital expenditure categories.
Industry Challenges
- Diesel-electric hybrid certification timelines:Dual-powertrain architectures face extended type-approval processes with Germany's KBA and France's national automotive approval authority.
- Legacy fleet technician retraining:High-voltage battery maintenance and CAN-bus diagnostics require skill sets scarce in rural equipment service networks concentrated in Kansas and Ohio.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Farm Trucks Market |
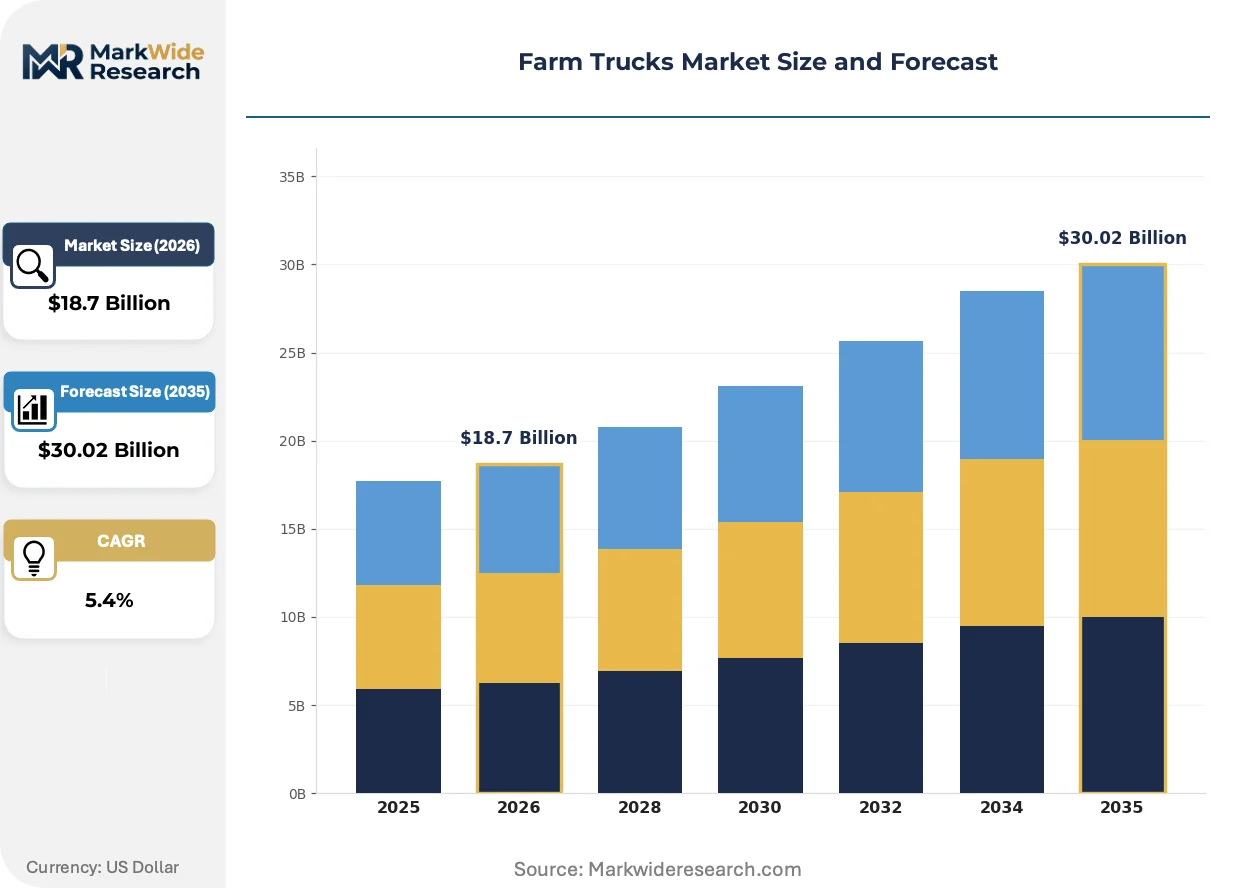
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pickup Trucks, Stake Trucks, Dump Trucks, Flatbed Trucks End User: Agricultural Cooperatives, Farmers, Construction Firms, Logistics Providers Fuel Type: Diesel, Gasoline, Electric, Hybrid Load Capacity: Light-Duty, Medium-Duty, Heavy-Duty, Super-Duty |
| Companies Covered | CNH Industrial, JCB, John Deere, International Tractors Ltd., Tractors and Farm Equipment's Ltd., Mahindra and Mahindra, Kubota Corporation, Iseki & Co., Ltd., AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Farm Trucks Market Emerging Trajectories
Powertrain electrification and precision-ag data convergence are compressing traditional equipment replacement cadences while redefining how farm trucks generate value beyond pure hauling utility.
Modular battery-electric platforms with swappable pack architectures are absorbing early trial placements in cooperative-owned operations with centralized depot charging. Iowa grain elevators and Illinois livestock terminals are piloting these configurations for sub-50-mile radius hauls where route predictability offsets range anxiety. The technology is absorbing capital that would otherwise flow to Tier 4 Final diesel replacements, compressing the addressable market for conventional powertrains in light-duty segments.
EPA Tier 4 Final and upcoming CARB requirements in the United States are forcing engine redesigns with diesel particulate filters and selective catalytic reduction systems that add cost and complexity. Agricultural logistics enterprises in California's Central Valley face the most acute compliance pressure as the state's Air Resources Board phases in stricter in-use performance standards ahead of federal timelines. Heavy-duty dump truck configurations for nut and vegetable harvesting are absorbing disproportionate engineering resources as manufacturers prioritize the highest-margin segments for emission architecture investments.
Cooperative procurement consortia are consolidating purchasing power across multi-county grain handling networks in the United States Corn Belt. Individual farm operators in Nebraska and Indiana are ceding specification authority to centralized buying committees that negotiate fleet-wide platform standardization. This concentration is most visible in heavy-duty stake truck segments where enterprise-scale agricultural logistics operations demand interchangeable parts inventories and unified service training protocols across their distributed facilities.
Farm Trucks Market Segmentation
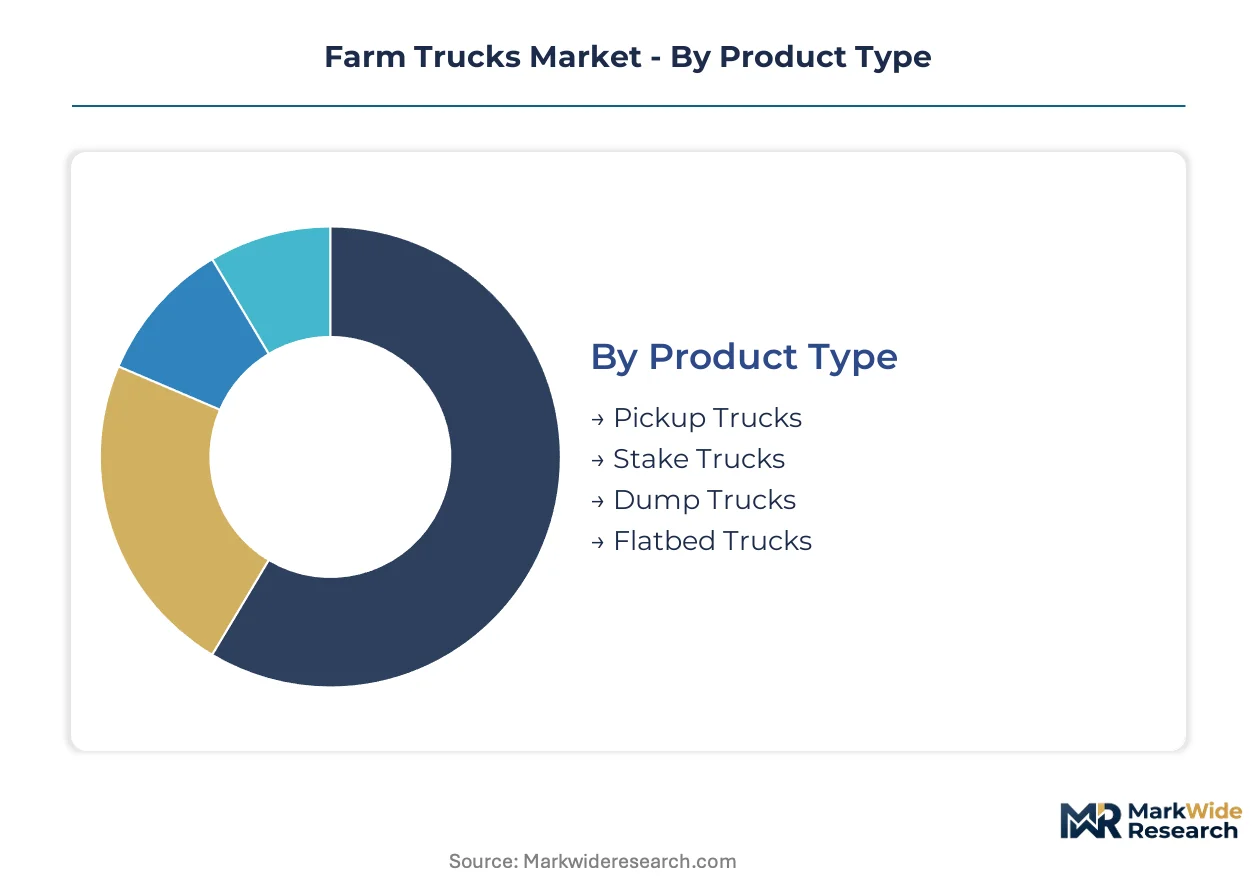
Farm truck procurement patterns diverge sharply across operational scales and duty cycles. Understanding these splits reveals where specification authority concentrates and how powertrain investments flow.
Product Type:
Payload geometry and unloading mechanism separate buyers by haul frequency and material type.
- Pickup Trucks:Light-duty configurations with enclosed cabs and open beds rated below four tons dominate individual farmer and small cooperative fleets across the United States Corn Belt. Nebraska and Indiana operations favor half-ton and three-quarter-ton diesel variants for daily equipment transport and grain sampling runs.
- Stake Trucks:Open-bed designs with removable side panels accommodate bulk commodities and livestock with forklift compatibility. Texas Panhandle cattle feedlots and Iowa hog confinement operations specify aluminum stake bodies with biosecurity washdown protocols for animal health compliance.
- Dump Trucks:Hydraulic lift mechanisms enable rapid unloading of grain, silage, and aggregate. Heavy-duty steel box configurations serve enterprise-scale elevators in Illinois and commercial composting facilities.
- Flatbed Trucks:Deck-mounted winch and tie-down systems transport oversized equipment between fields and service depots. Australian broadacre stations specify extended wheelbases for combine header movement.
Volume sits with Pickup Trucks; growth tilts toward Stake Trucks.
End User:
Procurement centralization versus distributed purchasing authority shapes fleet standardization and service contract structures.
- Agricultural Cooperatives:Multi-county grain handling networks consolidate specification authority through centralized buying committees. Iowa and Nebraska cooperatives negotiate fleet-wide platform standardization to unify parts inventories across distributed elevators.
- Farmers:Individual owner-operators in Kansas and Ohio prioritize acquisition cost and dealer proximity over interoperability, fragmenting demand across multiple OEM dealer networks.
- Construction Firms:Dual-use specifications bridge agricultural and earthmoving applications, particularly in California Central Valley irrigation infrastructure projects.
- Logistics Providers:Third-party haulers serving meatpacking plants and ethanol refineries demand refrigerated stake configurations with electronic logging device integration.
Agricultural Cooperatives command the heaviest unit volumes; Logistics Providers are expanding most quickly.
Fuel Type:
Energy density requirements and refueling infrastructure availability determine powertrain selection across rural geographies.
- Diesel:Compression-ignition architectures deliver torque curves optimized for heavy towing and extended idling. EPA Tier 4 Final after-treatment systems add cost complexity that squeezes mid-scale dealer margins.
- Gasoline:Spark-ignition powertrains occupy light-duty pickup segments where capital constraints limit diesel adoption among part-time farmers.
- Electric:Battery-electric prototypes with depot charging gain trial placements in cooperative-owned Iowa grain elevators for sub-50-mile radius hauls.
- Hybrid:Dual-powertrain architectures face extended type-approval timelines with Germany's KBA, delaying commercial availability in European markets.
Diesel retains dominant share; electric prototypes show the steepest expansion trajectory.
Load Capacity:
Axle ratings and frame reinforcement levels align with payload frequency and road classification access.
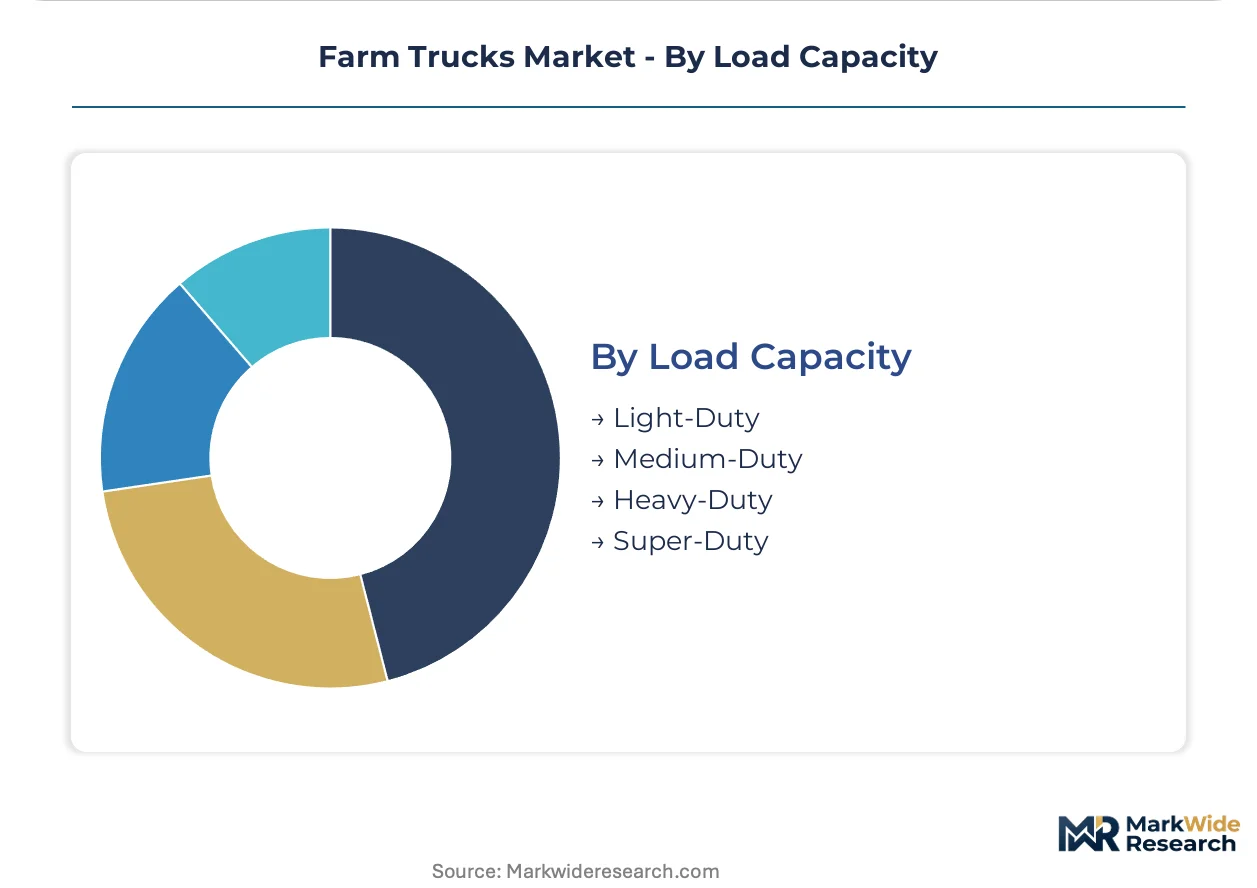
- Light-Duty:Gross vehicle weight ratings below 8,500 pounds serve hobby farms and vineyard operations with paved road predominance.
- Medium-Duty:Class 4-6 ratings accommodate daily grain hauling and equipment transport for mid-scale corn and soybean operations.
- Heavy-Duty:Class 7-8 configurations with reinforced frames and dual rear axles dominate commercial elevator fleets and livestock logistics in Nebraska Sandhills.
- Super-Duty:Specialized mining and quarry applications in Australian and Canadian prairie operations exceed standard highway weight limits.
Heavy-Duty configurations generate the strongest margin pools; Super-Duty orders are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in Germany and the United States supply chassis architectures to consumption centers across the Corn Belt and European mixed-farming regions. Brazil and India manufacture compact utility platforms for domestic smallholder operations. Australia imports heavy-duty configurations for broadacre grain logistics.
United States
EPA Tier 4 Final mandates force grain operations in Iowa and Illinois to retire pre-2015 engines ahead of schedule. USDA conservation programs indirectly subsidize fleet upgrades through equipment cost-sharing provisions. Nebraska Sandhills livestock logistics clusters absorb heavy-duty stake truck configurations with biosecurity washdown protocols.
Germany
KBA type-approval processes for diesel-electric hybrid architectures delay commercial launches by eight to fourteen months. Euro VI emission standards push manufacturers toward cleaner diesel redesigns and early electric prototyping. Bavarian agricultural machinery districts around Munich anchor chassis engineering for European export markets.
Brazil
Soybean export logistics drive demand for heavy-duty dump configurations in Mato Grosso and Goiás. ANVISA biosecurity regulations for livestock transport reshape stake body specifications in southern cattle feedlots. São Paulo state industrial corridors manufacture compact utility platforms for Mercosur distribution.
India
Maharashtra and Gujarat smallholder operations favor sub-ton payload ratings for multi-crop harvesting cycles. BIS certification requirements for commercial vehicle safety slow electric prototype deployment. Punjab grain procurement cooperatives consolidate fleet purchasing through state agricultural marketing boards.
Australia
Western Australian wheatbelt stations require extended-wheelbase flatbeds for combine header transport. State-level fatigue management regulations for long-distance grain hauls mandate electronic logging device integration. Queensland livestock logistics corridors drive refrigerated stake truck demand for meatpacking plant supply chains.
Farm Trucks Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across modular chassis-and-body configurations. Tier 1 suppliers with integrated precision-ag ecosystems anchor premium positioning in dealer networks. Mid-scale regional fabricators compete on acquisition cost and service proximity. Consolidation pressure accelerates around cooperative procurement consortia demanding unified parts inventories.
Within the diversified industrial tier, CNH Industrial and AGCO Corporation occupy positions spanning multiple powertrain architectures and geographic markets. John Deere exemplifies ecosystem-anchored premium positioning through integrated telematics and precision-ag data convergence. Kubota Corporation anchors compact utility specialization across East Asian and Australian broadacre segments.
| Leading Market Players |
|---|
| CNH Industrial |
| JCB |
| John Deere |
| International Tractors Ltd. |
| Tractors and Farm Equipment's Ltd. |
| Mahindra and Mahindra |
| Kubota Corporation |
| Iseki & Co., Ltd. |
| AGCO Corporation |
| Others |
Supply Flow & Price Mechanics
Cooperative procurement consortia across Iowa and Nebraska grain belts command volume-based pricing leverage that compresses dealer margins while rewarding standardized platform commitments with fleet-scale discounts.
Pricing Analysis
Cost-down pressure on mid-scale equipment dealers accelerates because EPA Tier 4 Final after-treatment systems add fifteen to twenty-five percent to powertrain unit costs. Three-tier pricing structure across premium, standard, and economy levels separates John Deere's precision-ag ecosystem bundles from AGCO's specialized configurations and regional fabricators' acquisition-cost plays. Price differentiation hinges on telematics integration depth and dealer service proximity. Individual farmers in Kansas and Ohio exhibit highest price sensitivity; enterprise-scale cooperatives prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Freight cost volatility from hot-rolled coil suppliers in Germany and the United States ripples through reinforced frame manufacturing timelines. Chassis engineering concentrates in Bavarian machinery districts around Munich and Corn Belt production corridors near Moline, Illinois. Steel and aluminum input costs rest on scrap metal flows from construction demolition cycles. Single-source vulnerability looms in selective catalytic reduction system components sourced from Tier 1 exhaust after-treatment specialists. Distribution runs through farm supply cooperative networks that create path dependency for diesel refueling infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-treatment system manufacturing capacity constraints prop pricing power for Tier 1 suppliers while compressing margin pools for mid-scale dealers unable to secure volume commitments.
For Market Incumbents: Anchor dealer network loyalty through captive telematics subscription revenue streams that lock in multi-year service contracts. Invest in backward integration into high-voltage battery maintenance training centers to offset technician scarcity in rural Kansas and Ohio service territories. Defend against electric prototype disruptors by accelerating modular chassis platform standardization across cooperative procurement committees. For New Entrants and Emerging Players: Begin with compact utility electric prototypes for East Asian rice-growing prefectures where Kubota's dominance leaves white space in sub-ton payload ratings. Target Australian broadacre stations with extended-wheelbase flatbed configurations for combine header transport. Pursue direct sales to cooperative-owned grain elevators in Iowa and Illinois bypassing traditional dealer markups. For Investors and Strategic Acquirers: The window for entry favors precision-ag data platform specialists with proven yield mapping software integration. Long-term viability hinges on subscription revenue durability rather than equipment sales cyclicality. Monitor CARB in-use performance standard phase-ins as inflection indicator for accelerated electric prototype capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Chassis Platform Standardization | Enables cooperative procurement consortia to unify parts inventories across distributed elevators in Nebraska and Iowa. |
| Precision-Ag Data Integration | Telematics-enabled payload monitoring converges with John Deere's yield mapping software for subscription revenue. |
| Electric Prototype Depot Trials | Iowa grain elevators pilot battery-electric configurations for sub-50-mile radius hauls with centralized charging. |
| After-Treatment System Backward Integration | Captive supply of diesel particulate filters and selective catalytic reduction components secures margin control. |
| Autonomous Convoy Regulatory Partnership | Saskatchewan and Manitoba provincial approvals for self-driving grain truck trials create first-mover positioning. |
Methodological Framework
Independent corroboration across OEM platform engineering directors, cooperative procurement committee chairs, and Tier 1 after-treatment system suppliers underwrites the qualitative findings. Primary interviews with farm equipment dealer principals, USDA conservation program administrators, and EPA compliance officers combined with secondary validation from SEC 10-K filings, EPA certification databases, and USDA equipment cost-sharing provisions. Bottom-up unit shipment estimates triangulated against top-down agricultural logistics expenditure models.
Rate-of-change decomposition across the analysis window isolates powertrain electrification velocity from emission compliance cycle compression. Segmentation dimensions modeled include product type, end user procurement centralization, fuel architecture, and load capacity tier alongside regional regulatory cluster divergence. CAGRs derived from installed fleet replacement timing analysis and cooperative capital expenditure survey data. Forecast inputs incorporate EPA Tier 4 Final grandfathered exemption phase-outs and EU Stage V type-approval timelines.
Underlying measurement precision varies by segment; heavy-duty stake and dump truck configurations carry tighter precision than compact utility pickup segments due to concentrated enterprise buyer visibility. Forecasts reflect assumptions regarding cooperative procurement committee consolidation velocity and electric charging infrastructure capital deployment rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle Steering Column Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Industrial Truck Market
Commercial Vehicles
Automated Truck Market
Commercial Vehicles
Electric Truck Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
Middle East Vacuum Truck Market
Commercial Vehicles
France Light Commercial Vehicles Market
Commercial Vehicles
Global Fuel Cell Commercial Vehicle Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle Foundation Brakes Market