
 Air Springs Market | 2026-2036
Air Springs Market Size, Share, and Industry Trends Forecast 2026-2036
Air Springs Market Analysis
Multi-source procurement among Tier-1 suspension suppliers is hardening as OEMs diversify away from single-continent dependency. Continental AG leverages its integrated rubber compounding and electronics portfolio to control cost structures across passenger and commercial vehicle programs. Vibracoustic SE anchors European luxury sedan air spring supply through captive manufacturing in Germany and Czechia. Hendrickson Holdings, L.L.C. dominates North American heavy-duty truck air suspension with specialized axle-integrated systems.
Air springs are elastomeric bellows—typically reinforced with textile plies of nylon, rayon, or aramid—pressurized with compressed air to provide load-bearing suspension and vibration isolation in vehicles and industrial machinery. Fabric-reinforced rubber constructions withstand cyclic fatigue across temperature ranges from minus forty to plus one hundred degrees Celsius, making them essential for commercial trucking and rail bogie applications. The automotive application segment leads absolute volume, though railway deployments are recording the fastest specification upgrades as operators replace steel coil suspensions for passenger comfort gains. Composite material formulations are capturing margin pools from conventional rubber compounds where weight reduction justifies premium positioning.
The EPA's Phase 3 greenhouse gas standards and the EU F-Gas Regulation are reshaping air spring specifications by pressuring manufacturers toward lighter, lower-leakage designs that reduce vehicle mass and refrigerant escape paths. NHTSA's underride protection rules for commercial trailers indirectly expand air spring addressable market by mandating suspension height adjustability. ISO 9001 and IATF 16949 certification requirements function as de facto market access gates for suppliers seeking OEM qualification. Stakeholders must monitor how active and semi-active damping technologies redefine the competitive boundary between pure air spring suppliers and integrated chassis electronics providers.
Market Dynamics
EPA Phase 3 greenhouse gas standards and EU F-Gas Regulation are compressing design cycles across commercial vehicle programs, forcing air spring manufacturers to integrate lighter textile-reinforced constructions with electronic height management systems.
Growth Catalysts
- Heavy-duty fleet modernization:North American trucking operators are retrofitting air suspension for cargo protection and driver retention.
- REACH compliance pressure:European rubber compounders are reformulating elastomer blends to eliminate restricted plasticizers, opening specification windows for advanced textile-ply constructions.
- Railway comfort mandates:Passenger rail operators in Germany and Japan are replacing steel coil suspensions with air spring bogies to meet vibration standards.
Market Restraints
- Aramid fiber cost volatility:Ballistic-grade textile ply inputs fluctuate with defense sector demand, squeezing margin on high-performance air springs.
- Single-source rubber dependency:Southeast Asian natural latex concentration creates supply vulnerability for European compounders.
- Steel coil substitution persistence:Cost-sensitive emerging market bus manufacturers retain mechanical suspension for price-competitive fleet procurement.
Strategic Opportunities
- Indian commercial vehicle electrification:PLI scheme incentives for electric buses create specification openings for lightweight air suspension modules.
- Active damping convergence:Integration of magnetorheological valves with textile-reinforced bellows enables semi-autonomous chassis control.
- Aftermarket digital channels:Direct-to-fleet e-procurement platforms are disintermediating traditional distributor networks for replacement air spring kits.
Industry Challenges
- IATF 16949 certification timelines:New compound formulations require 18-24 month OEM validation cycles before production approval.
- Embedded electronics integration:Pressure sensor and ECU sourcing from non-automotive semiconductor suppliers creates qualification bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Springs Market |
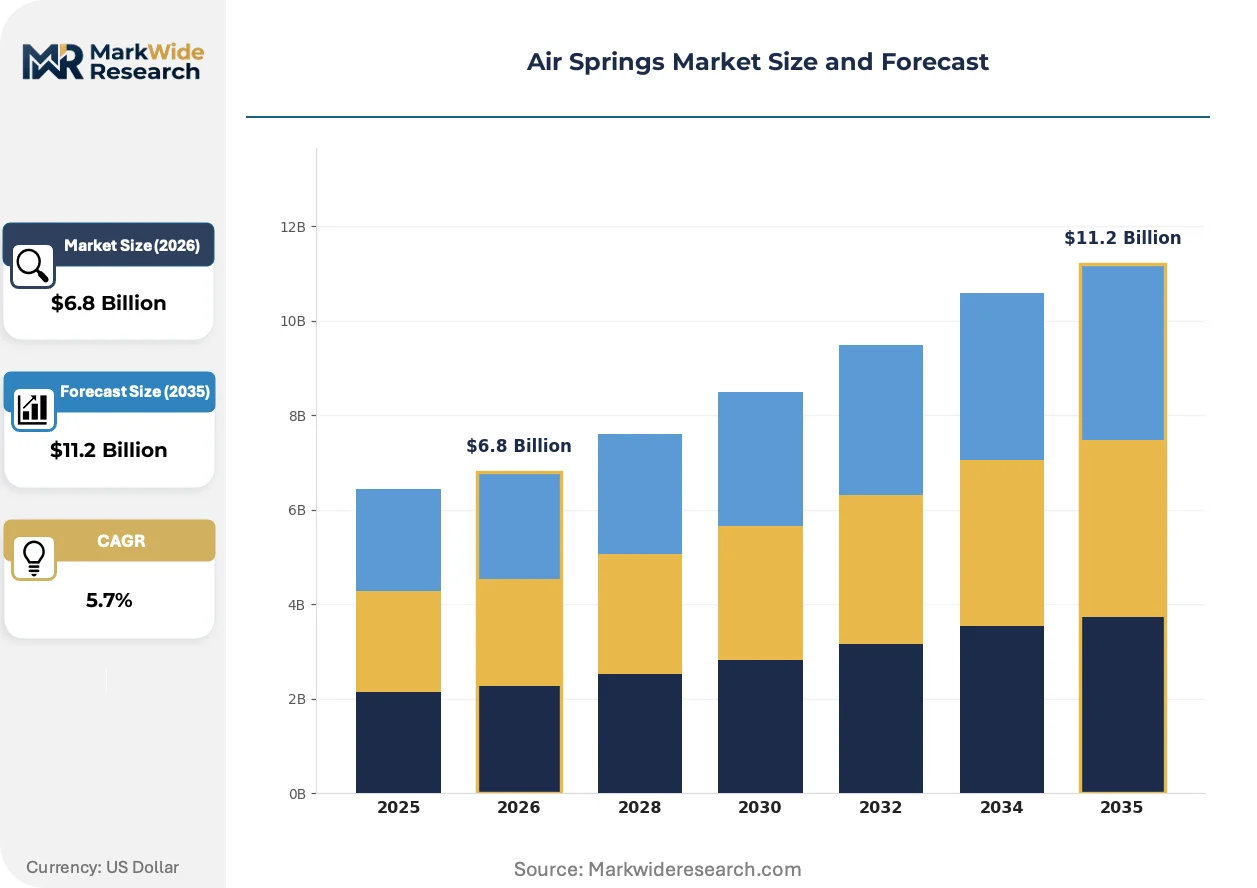
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber, Fabric, Polyurethane, Composite Application: Automotive, Aerospace, Industrial, Railway Technology: Passive, Active, Semi-Active, Adjustable End User: OEMs, Aftermarket Providers, Distributors, Tier-1 Suppliers |
| Companies Covered | Vibracoustic SE, Air Lift Company, Continental AG, ITT Inc., Hendrickson Holdings, L.L.C., Bridgestone Industrial Limited, Trelleborg Group, BWI Group, Firestone Industrial Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Springs Market Emerging Trajectories
Material science advances and regulatory pressure on vehicle mass are converging to redefine air spring construction methods and system integration architectures across commercial and rail applications.
Textile-reinforced composite bellows using hybrid aramid-nylon ply configurations are electrifying the competitive landscape for heavy-duty truck air springs. Fleet operators in Germany and the United States are specifying these constructions for 15% mass reduction over conventional rubber-steel assemblies. The technology is electrifying procurement criteria by collapsing the historical separation between mechanical suspension and electronic chassis control suppliers.
The EU F-Gas Regulation's leakage-rate thresholds are mandating redesigned bead-ring seals and crimp interfaces for climate-controlled commercial vehicles. European OEMs are consolidating supplier qualification around dual-compound constructions that maintain elasticity across minus forty to plus one hundred degrees Celsius operating windows. Refrigerated trailer manufacturers in the Netherlands and Poland are accelerating specification shifts to comply with 2027 enforcement milestones.
Fleet procurement departments are consolidating suspension purchasing through outcome-based total-cost-of-ownership contracts rather than component-level transactions. Large North American trucking operators are unbundling installation and maintenance services from hardware supply, pressuring Tier-1 suppliers to establish captive service networks. This restructuring is most pronounced in California and Texas, where mega-fleets operate centralized specification authority over regional maintenance providers.
Air Springs Market Segmentation
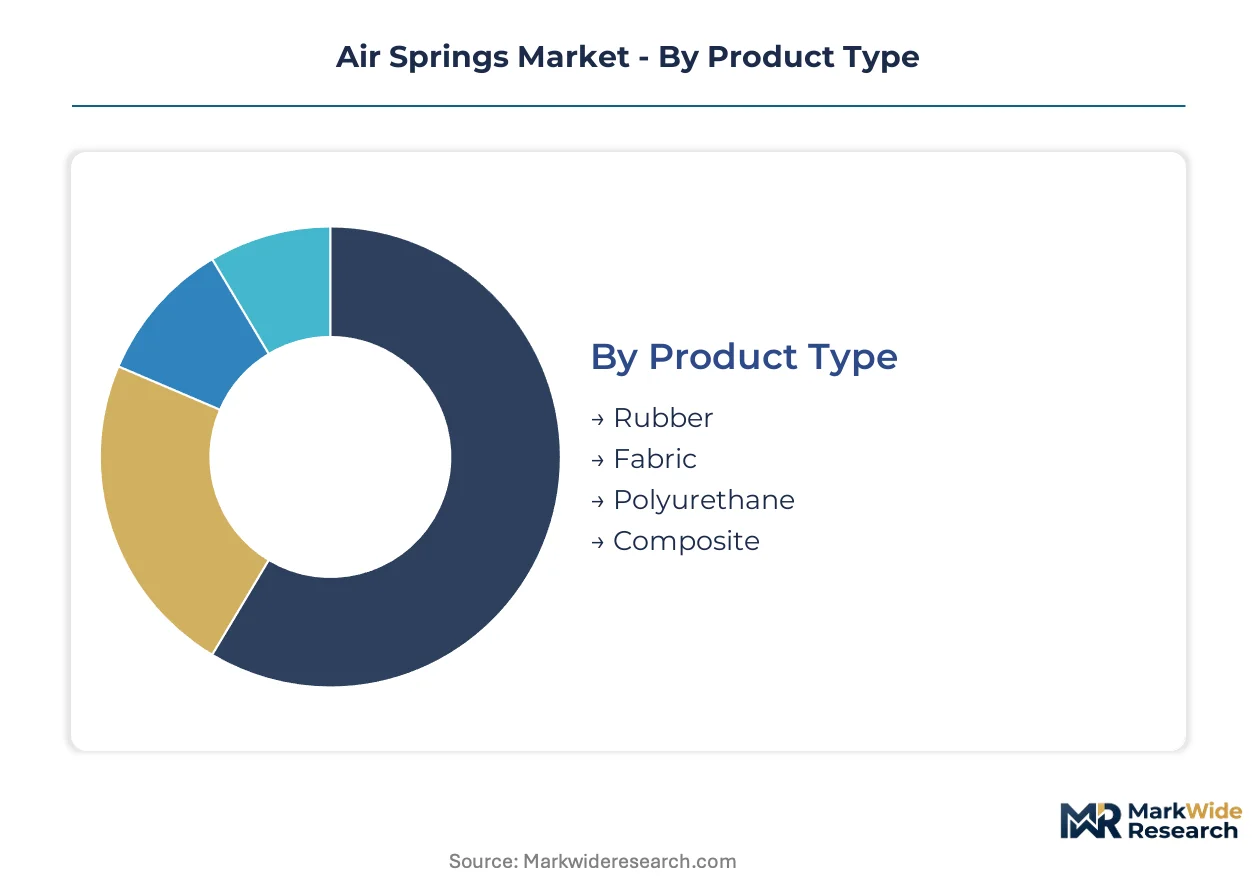
Air spring procurement decisions cascade through material selection, application requirements, and system integration complexity. Each segmentation dimension carries distinct capital intensity profiles and qualification timelines that reshape supplier economics across commercial vehicle and rail programs.
Product Type:
Capital intensity peaks with composite formulations requiring specialized curing presses and textile-impregnation lines, while rubber compounding demands lower upfront tooling but higher raw material working capital.
- Rubber:Natural and synthetic elastomer bellows reinforced with nylon or rayon plies dominate heavy-duty truck suspensions for their fatigue resistance across temperature extremes. Demand concentrates in North American fleet retrofit programs where operators prioritize replacement part availability over mass reduction.
- Fabric:Hybrid textile-reinforced constructions using aramid-nylon ply configurations achieve 15% mass reduction over conventional rubber-steel assemblies. German and United States fleet operators are specifying these for refrigerated trailers facing EU F-Gas Regulation leakage thresholds.
- Polyurethane:Thermoplastic elastomer formulations offer simplified molding cycles for industrial machinery isolation mounts.
- Composite:Carbon fiber-reinforced bellows command premium positioning in aerospace landing gear where weight reduction justifies qualification costs.
Most installed capacity flows through rubber constructions. Expansion is steepest in fabric-reinforced segments.
Application:
Volume concentration and margin structure diverge sharply across mobility modes, with rail and aerospace applications requiring extended validation cycles that lock in supplier relationships for decade-long platform lives.
- Automotive:Passenger vehicle air springs integrate with electronic height management for luxury sedan and SUV platforms. European OEMs in the German supplier corridor specify dual-compound constructions maintaining elasticity from minus forty to plus one hundred degrees Celsius.
- Railway:Passenger rail operators in Germany and Japan are replacing steel coil bogie suspensions with air spring systems to meet vibration comfort mandates. The specification shift is accelerating as operators modernize rolling stock for competitive intercity service.
- Industrial:Vibration isolation for manufacturing equipment and material handling systems follows cyclical capital expenditure patterns.
- Aerospace:Landing gear and cabin isolation applications demand ballistic-grade aramid reinforcement with defense-sector supply competition.
Automotive applications absorb the largest production volumes. Railway deployments are climbing the fastest as operators retire mechanical suspensions.
Technology:
System architecture decisions determine whether suppliers compete as pure component vendors or integrated chassis electronics providers, with electronics integration multiplying program development costs by factors of three to five.
- Passive:Mechanical bellows with fixed damping characteristics serve cost-sensitive emerging market bus manufacturers retaining steel coil substitution for price-competitive procurement.
- Semi-Active:Magnetorheological valve integration with textile-reinforced bellows enables real-time damping adjustment without full active system cost. North American mega-fleets in California and Texas are consolidating procurement around these systems through outcome-based total-cost-of-ownership contracts.
- Active:Fully electronic height and damping control with embedded pressure sensors and ECUs creates qualification bottlenecks when sourcing semiconductors from non-automotive suppliers.
- Adjustable:Manual or pneumatically switched stiffness settings serve specialized trailer applications requiring suspension height variability for NHTSA underride compliance.
Passive systems retain the broadest installed base. Semi-active architectures are gaining share fastest as fleets unbundle hardware from service contracts.
End User:
Channel structure and pricing power vary dramatically by customer type, with OEM direct supply requiring IATF 16949 certification investments that exclude smaller compounders from platform access.
- OEMs:Original equipment manufacturers impose 18-24 month validation cycles for new compound formulations before production approval. EPA Phase 3 greenhouse gas standards are compressing these timelines as commercial vehicle programs accelerate toward lighter suspension technologies.
- Tier-1 Suppliers:Continental AG and Vibracoustic SE leverage integrated rubber compounding and captive manufacturing to control cost structures across passenger and commercial vehicle programs. These suppliers anchor specification authority for European luxury sedan air spring supply.
- Aftermarket Providers:Direct-to-fleet e-procurement platforms are disintermediating traditional distributor networks for replacement air spring kits in North American trucking corridors.
- Distributors:Regional maintenance providers face consolidation pressure as mega-fleets centralize specification authority over service networks.
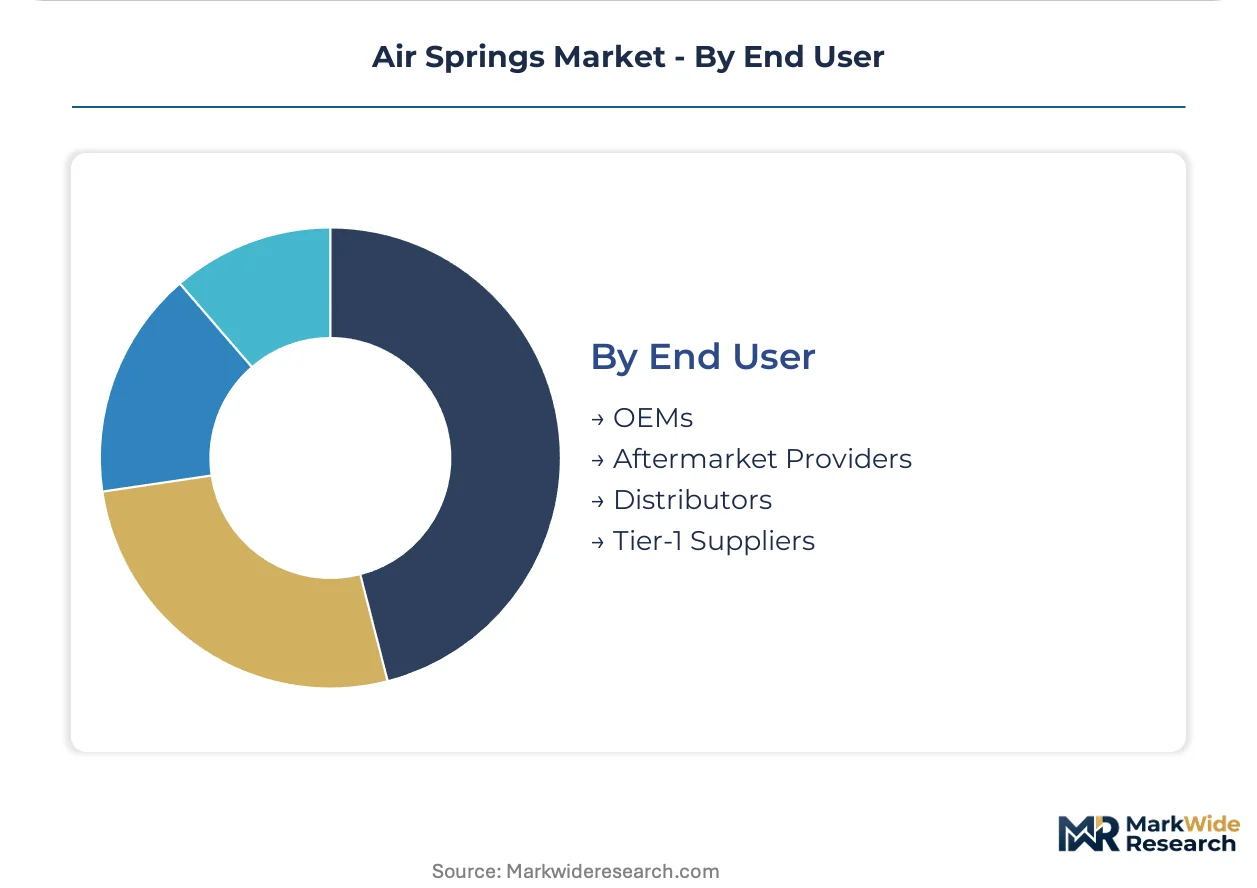
Tier-1 suppliers command the largest production allocations. Aftermarket digital channels are expanding most quickly as procurement departments consolidate purchasing authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The German automotive supplier corridor anchors air spring manufacturing density, with Tier-1 compounders and captive electronics integrators clustering around Stuttgart, Munich, and Hanover. Production networks radiate from this core to serve commercial vehicle programs across multiple continents.
United States
Heavy-duty fleet operators in California and Texas are consolidating procurement around semi-active suspension systems through outcome-based service contracts. NHTSA underride protection rules mandate trailer height adjustability, expanding specification windows for electronic air management. Detroit and Chicago anchor North American production for axle-integrated commercial vehicle systems.
Germany
EU F-Gas Regulation leakage thresholds are forcing redesigns of bead-ring seals and crimp interfaces for refrigerated transport. REACH compliance pressure drives reformulation of elastomer blends toward advanced textile-ply constructions. The Stuttgart-Munich corridor hosts captive manufacturing for European luxury sedan air spring supply.
China
Commercial vehicle electrification programs under MIIT guidance are creating specification openings for lightweight suspension modules in electric bus platforms. Dual carbon goals press manufacturers toward mass-reduced composite constructions. Yangtze River Delta industrial zones concentrate domestic compounder capacity for regional OEM qualification.
Japan
Passenger rail operators under METI vibration comfort mandates are replacing steel coil bogie suspensions with air spring systems for intercity service modernization. JIS standards govern textile reinforcement specifications for rolling stock applications. Nagoya and Osaka industrial zones concentrate rail suspension manufacturing for domestic and export programs.
India
PLI scheme incentives for electric commercial vehicles are opening procurement windows for lightweight air suspension modules in bus and truck platforms. BIS certification requirements function as market access gates for compounders seeking OEM supply contracts. Maharashtra and Gujarat anchor domestic production clusters for commercial vehicle component supply.
Air Springs Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue electronics integration and active damping convergence. The vendor base stratifies between integrated chassis systems providers and pure component fabricators, with qualification timelines creating defensible positions for incumbent compounders. Three archetypes dominate: captive rubber-electronics integrators, specialized heavy-duty axle suppliers, and regional aftermarket distributors. Consolidation pressure operates through M&A activity targeting electronics capabilities and geographic expansion into Indian and Southeast Asian commercial vehicle corridors.
Within the captive integration tier, Continental AG and Vibracoustic SE exemplify compounders controlling cost structures through in-house rubber formulation and electronics portfolio leverage. Hendrickson Holdings, L.L.C. occupies a distinct position as a North American heavy-duty specialist with axle-integrated system architecture. These three anchors represent divergent strategic positions: European integrated supply, North American commercial vehicle focus, and multi-continent platform coverage.
| Leading Market Players |
|---|
| Vibracoustic SE |
| Air Lift Company |
| Continental AG |
| ITT Inc. |
| Hendrickson Holdings, L.L.C. |
| Bridgestone Industrial Limited |
| Trelleborg Group |
| BWI Group |
| Firestone Industrial Products |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap compounders across Southeast Asia anchor raw material sourcing for European and North American air spring manufacturers, translating rubber price volatility into contract renegotiation leverage every 12-18 months. Their concentrated ownership structure feeds pricing discipline through inventory hoarding during latex harvest disruptions, while simultaneously constraining Tier-1 suppliers' ability to squeeze input costs.
Pricing Analysis
Aramid fiber and natural latex cost pass-through dominates contract structures, with three-tier pricing separating ballistic-grade textile-reinforced systems from standard nylon-ply constructions and economy rubber bellows. Certification tier creates the steepest price differentiation, as IATF 16949-qualified suppliers command 20-30% premiums over non-certified compounders for OEM direct supply. Pricing pressure stems from fleet procurement departments consolidating around outcome-based total-cost-of-ownership contracts that unbundle hardware from service. Emerging market bus manufacturers show highest price sensitivity, while refrigerated trailer operators in Germany and the Netherlands absorb premiums for F-Gas-compliant seal designs.
Supply Chain Analysis
Natural latex supply rests on Thai and Indonesian plantation networks, with Malaysian processing facilities concentrating refined material for global compounders. Aramid fiber draws from DuPont and Teijin production in the United States and Japan, while synthetic rubber feeds from South Korean and Chinese petrochemical complexes. Single-source vulnerability concentrates in Southeast Asian latex harvesting, where climate disruption and labor migration create episodic shortages. Distribution runs through Tier-1 captive manufacturing networks in Germany and the Czech Republic, with aftermarket channels fragmenting across regional maintenance providers in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
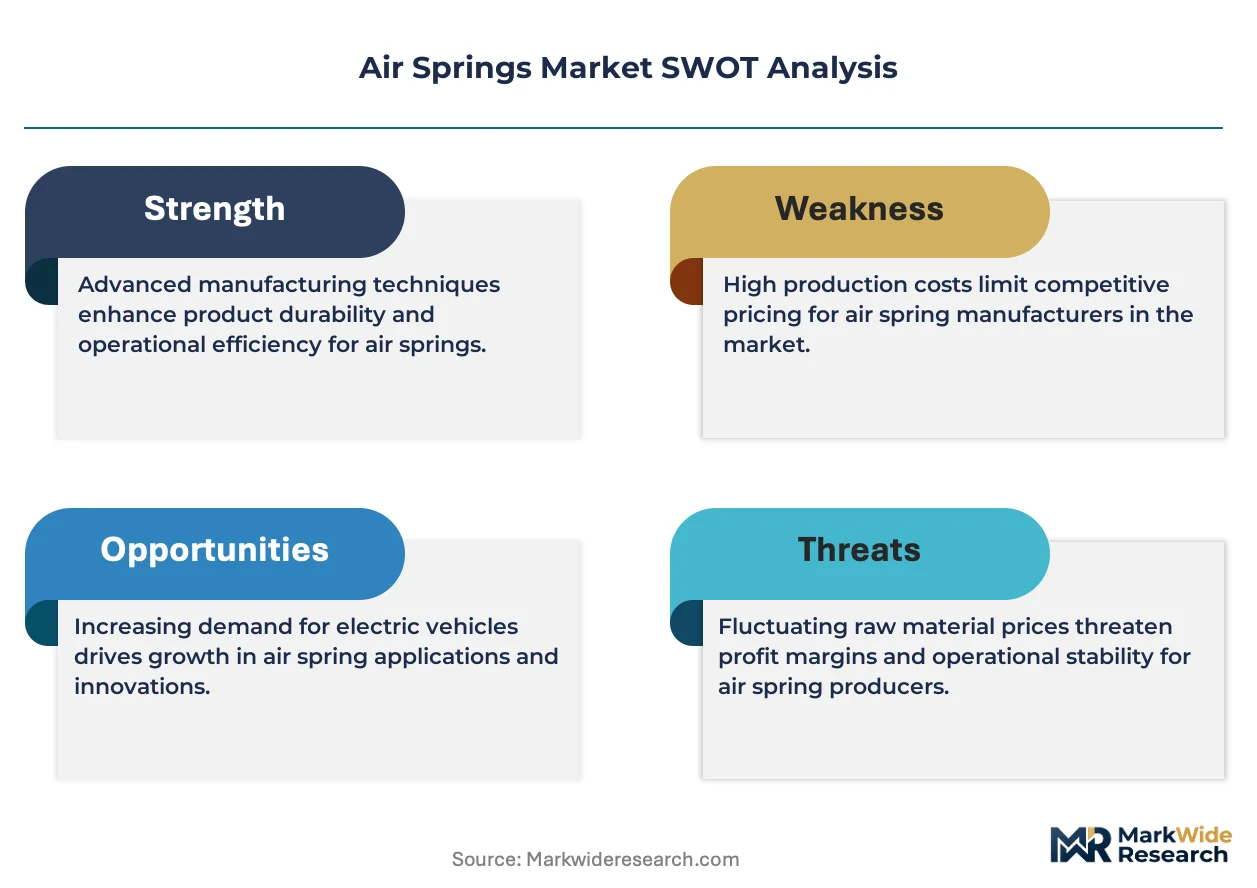
Margin expansion in air springs hinges on composite material substitution and electronics integration, as fabric-reinforced constructions capture premium positioning from conventional rubber compounds while active damping systems collapse the boundary between mechanical and electronic chassis suppliers.
For Market Incumbents: Hedge against aramid fiber cost volatility through backward integration into textile-impregnation capabilities or long-term offtake agreements with Japanese specialty fiber producers. Defensive consolidation of electronics sourcing relationships mitigates semiconductor qualification bottlenecks threatening active system development timelines. Prioritize captive service network buildout in California and Texas to capture fleet unbundling trends. For New Entrants and Emerging Players: Capture specification openings in Indian electric commercial vehicle programs under PLI scheme incentives, where domestic compounders lack IATF 16949 certification for OEM direct supply. Target railway bogie modernization in Germany and Japan as the fastest-penetrating application segment. Pursue magnetorheological valve integration partnerships to bypass full active system development costs. For Investors and Strategic Acquirers: Valuations sit cheapest among regional aftermarket distributors facing consolidation pressure from mega-fleet procurement centralization. Long-term viability favors compounders with in-house rubber formulation and captive electronics integration, positioned for active damping convergence. Watch semi-active suspension adoption rates among North American mega-fleets as the inflection signal for electronics-capable supplier premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Textile-Reinforced Composite Formulation | Enables 15% mass reduction for EPA Phase 3 compliance in heavy-duty trucking. |
| Magnetorheological Valve Integration | Collapses cost barrier to semi-active damping for fleet outcome-based contracts. |
| Captive Service Network Expansion | Captures unbundled maintenance revenue from California and Texas mega-fleets. |
| Aramid Fiber Backward Integration | Insulates margin from defense sector demand volatility and supply disruption. |
| Electronic Height Management System Development | Addresses NHTSA underride protection mandates for trailer height adjustability. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and fleet maintenance managers with secondary validation. Trade data from customs authorities, vehicle production databases, IHS Markit registration figures, and SEC filings from listed automotive suppliers anchor quantitative foundations. Bottom-up segment sizing triangulates against top-down macroeconomic absorption models.
Rate-of-change decomposition across the projection horizon isolates volume drivers from mix-shift and pricing effects. Segmentation dimensions modeled include material formulation tier, application mode, technology architecture, and end-user channel structure. CAGRs derive from elasticity-adjusted demand curves incorporating EPA Phase 3 compliance timelines, EU F-Gas Regulation enforcement milestones, and railway operator modernization capex cycles.
Aramid fiber supply disruption, semiconductor sourcing bottlenecks for embedded electronics, and REACH compliance reformulation delays are the dominant revision risks to modeled outputs. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Russia Automotive Hydraulic Actuators Market
Automotive Parts
Global Bevel Gearbox Market
Automotive Parts
Middle East Automotive Engine Oils Market
Automotive Parts
Poland Passenger Vehicles Lubricants Market
Automotive Parts
North America Automotive Parts Zinc Die Casting Market
Automotive Parts
Apron Bus Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Automotive Suspension System Market
Automotive Parts
High Speed Rolling Bearings Market
Automotive Parts
Automotive Steel Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
Automotive AC Compressor Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
Automotive Electric Water Pump Market
Automotive Parts
Automotive Filter Paper Market