
 Struts System Market | 2026-2036
Struts System Market Size, Share, and Industry Trends Forecast 2026-2036
Struts System Market Analysis
Multi-source procurement for coil spring and damper modules is recalibrating how tier-one suppliers contract with strut system integrators. Eaton Corporation Inc. leverages its hydraulics heritage to anchor positions in heavy-duty commercial vehicle strut channels. Unistrut Corporation sustains dominance across architectural and industrial support strut applications through standardized channel product lines. Hilti Corporation competes on fastening and channel integration systems that reduce installation labor in modular construction environments.
A strut system combines a shock-absorbing damper with a structural load-bearing member, typically manufactured through seam-welded steel tube forming or aluminum extrusion with integrated coil spring perches, to maintain wheel alignment while supporting vehicle or equipment mass. MacPherson strut configurations retain the largest production volume across passenger vehicle platforms due to packaging efficiency and lower part count, while multi-link strut architectures command premium positioning in performance and luxury segments where adjustable camber geometry justifies higher system cost. Aluminum material grades are displacing steel in strut housings where unsprung mass reduction directly improves ride quality and energy efficiency targets.
NHTSA Federal Motor Vehicle Safety Standards govern strut structural integrity and corrosion resistance for US-market vehicles, while EPA tailpipe emissions rules indirectly shape demand through weight-reduction mandates that favor aluminum and composite strut materials. The EU Green Deal and REACH chemical restrictions constrain surface coating chemistries used in European strut manufacturing, pushing suppliers toward water-based pretreatment and powder coating alternatives. Stakeholders must monitor how OEM platform consolidation toward electric vehicle skateboard architectures alters load-path requirements and strut mounting geometries across vehicle classes.
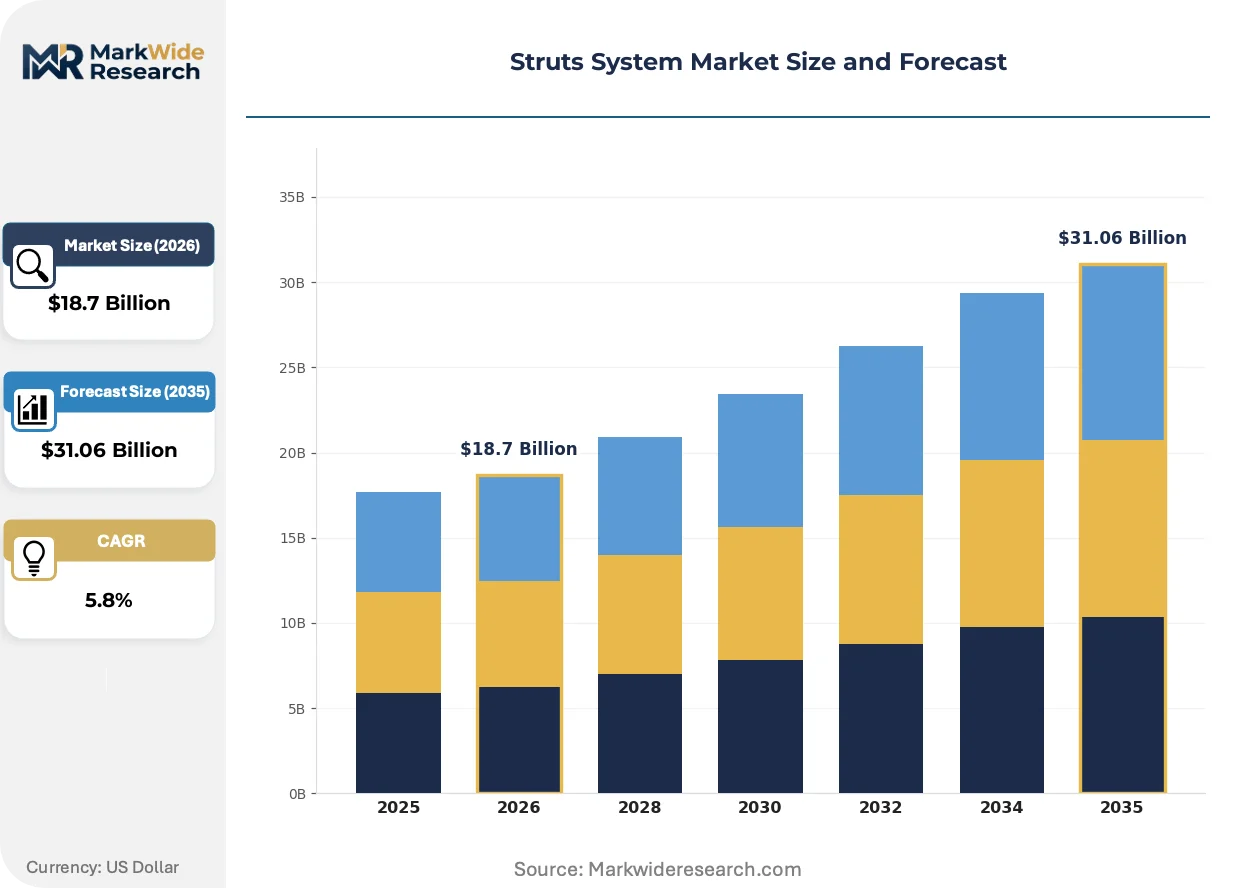
Market Dynamics
Aluminum material substitution in strut housings is compressing legacy steel supply chains while forcing tier-one integrators to requalify welding and surface treatment processes for lighter alloy grades. EPA fuel-economy mandates and NHTSA safety standards are accelerating this transition across passenger vehicle platforms.
Growth Catalysts
- EPA Fuel-Economy Mandates:Stringent tailpipe emissions rules are compelling automakers to reduce unsprung mass through aluminum strut adoption, directly expanding addressable demand for lightweight suspension architectures.
- EV Skateboard Platforms:Electric vehicle chassis designs with centralized battery packs are redistributing load paths and requiring redesigned strut mounting geometries that accommodate higher vehicle mass.
- Germany Premium Passenger Sector:MacPherson and multi-link strut configurations dominate platform engineering decisions among luxury OEMs, sustaining premium pricing for adjustable camber systems.
Market Restraints
- Aluminum Price Volatility:LME aluminum price swings compress margin predictability for extruded strut housing manufacturers locked into annual supply contracts with automotive OEMs.
- REACH Chemical Restrictions:EU surface coating regulations are forcing conversion from solvent-based pretreatments to water-based alternatives, adding capital expense and process validation timelines.
- Steel Supply Concentration:Seam-welded steel tube forming capacity concentrates in East Asian mill networks, exposing North American tier suppliers to tariff and logistics cost uncertainty.
Strategic Opportunities
- Modular Construction Channel:Architectural strut applications in prefabricated building systems offer expansion paths beyond automotive cyclicality, with fastening-integrated channel products reducing on-site labor hours.
- Heavy-Duty Commercial Vehicles:Hydraulics-anchored strut designs for vocational trucks and buses represent underpenetrated demand relative to saturated passenger car segments.
- EU Green Deal Alignment:Carbon border adjustment mechanisms and embodied emissions tracking favor regional aluminum sourcing with renewable energy provenance, rewarding European extrusion investments.
Industry Challenges
- Alloy Welding Certification:Transitioning production lines from steel to aluminum seam welding requires requalification under NHTSA structural integrity standards, extending new product introduction timelines.
- Coating Chemistry Reformulation:REACH-compliant powder coating alternatives demand reformulation of corrosion resistance specifications, complicating OEM validation cycles for European-market strut assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Struts System Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MacPherson Strut, Double Wishbone Strut, Multi-Link Strut, Torsion Beam Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Performance Cars Material: Steel, Aluminum, Carbon Fiber, Composite Materials End User: Automobile Manufacturers, Aftermarket Providers, Automotive Suppliers, OEMs |
| Companies Covered | Eaton Corporation Inc., Unistrut Corporation, Cooper Industries, Hilti Corporation, Aetna Plastics Corp., Enduro Pipeline Services Inc., Atlas Supply Co., ERICO Products Inc., Guenther Supply Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Struts System Market Emerging Trajectories
Active material substitution and digital manufacturing methods are compressing traditional development cycles while expanding performance differentiation between mass-market and premium suspension tiers. These shifts are reshaping supplier capability requirements.
Aluminum extrusion with integrated coil spring perches is integrating damper and load-bearing functions into single-piece housings that reduce part count and assembly labor. Premium German OEMs are adopting these designs fastest for multi-link rear architectures. The technology is integrating formerly separate stamping and welding operations into continuous extrusion lines, consolidating tier-two supplier tiers.
REACH chemical restrictions are constraining hexavalent chromium surface treatments across European strut manufacturing, pushing suppliers toward trivalent chrome and zirconium-based pretreatment chemistries. Coating line retrofits absorb twelve to eighteen months of capital deployment. Aftermarket strut remanufacturers in Eastern Europe face the steepest compliance cost escalation, accelerating consolidation toward OEM-captive rebuild operations.
Automotive OEMs are consolidating damper and coil spring procurement under single-source strut system integrators, compressing the multi-vendor contracting models that historically separated shock absorber and spring suppliers. Tier-one integrators with captive aluminum extrusion capacity are capturing expanded bill-of-material scope. This concentration is most visible in North American light truck platforms where platform sharing across OEMs amplifies volume leverage for qualified suppliers.
Struts System Market Segmentation
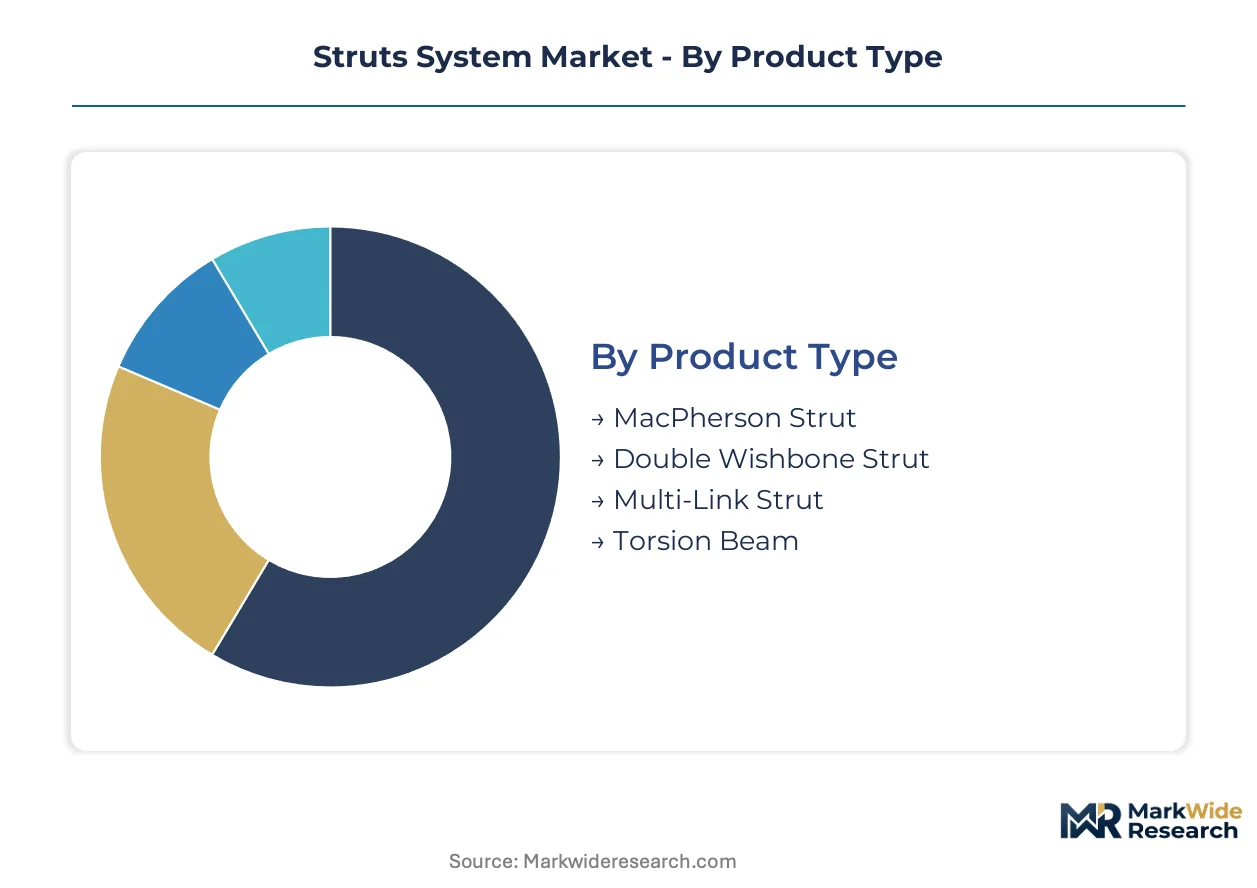
Platform architecture decisions and material substitution cycles create distinct competitive arenas across strut system categories. Each segmentation dimension carries different margin profiles, certification requirements, and supplier capability thresholds that shape procurement strategies.
Product Type:
Upgrade cycles in suspension architectures follow platform redesign timelines, with OEMs requalifying strut configurations every five to seven years to capture weight and packaging advantages.
- MacPherson Strut:Integrates shock absorber and structural member into a single assembly with coil spring perch, dominating front suspension layouts for transverse-engine vehicles. Demand concentrates in compact and mid-size passenger vehicles across US and German OEM portfolios, driven by packaging efficiency that maximizes engine bay space for thermal management hardware.
- Multi-Link Strut:Separates damper function from multiple control arms to enable independent camber and toe adjustment through suspension travel. German premium OEMs specify these architectures for rear axles, where adjustable geometry justifies higher system cost against ride quality benchmarks.
- Double Wishbone Strut:Employs upper and lower control arms to maintain tire contact patch geometry under heavy lateral loads.
- Torsion Beam:Semi-independent rear suspension using a cross-member twist beam with integrated trailing arms, common in cost-optimized compact platforms.
MacPherson Strut sits at the top of the volume ranking, with Multi-Link Strut climbing the fastest as premium segment electrification demands refined ride control.
Application:
Cost tier differentiation separates mass-market platforms from specialized architectures where performance specifications command material premiums.
- Passenger Vehicles:Encompasses sedans, hatchbacks, crossovers, and SUVs for personal transportation, representing the foundational demand base for aluminum strut substitution. US EPA fuel-economy mandates accelerate lightweight material adoption in this segment as OEMs pursue fleet-average compliance.
- Performance Cars:Requires adjustable damping, magnetic ride control, and carbon-ceramic integration with strut assemblies. German and Italian OEMs concentrate development resources here, where track-day capability validates technology transfer to volume platforms.
- Commercial Vehicles:Heavy-duty trucks and vocational equipment with load-rated strut capacities exceeding passenger car specifications.
- Off-Road Vehicles:Specialized suspension travel and sealing requirements for agricultural, mining, and recreational applications.
Passenger Vehicles anchor production scale economics, while Performance Cars deliver the steepest expansion trajectory as electrification amplifies chassis tuning differentiation.
Material:
Supply concentration in primary metal processing determines regional cost competitiveness and carbon intensity credentials for strut housing production.
- Aluminum:Extruded 6xxx-series alloys with integrated spring seats and mounting bosses, displacing steel where unsprung mass reduction directly improves energy efficiency metrics. North American OEM procurement expansion favors domestic extrusion capacity with renewable electricity provenance.
- Steel:Seam-welded high-strength low-alloy tubing formed into telescoping housings with stamped spring perches, retaining cost advantage in price-sensitive vehicle classes.
- Carbon Fiber:Wound or braided composite strut towers for ultra-low-mass racing applications.
- Composite Materials:Glass-reinforced polymer and hybrid metal-composite constructions for specialized damping integration.
Steel maintains volume leadership in absolute units, with Aluminum gaining share fastest as platform electrification redistributes mass budgets toward battery protection structures.
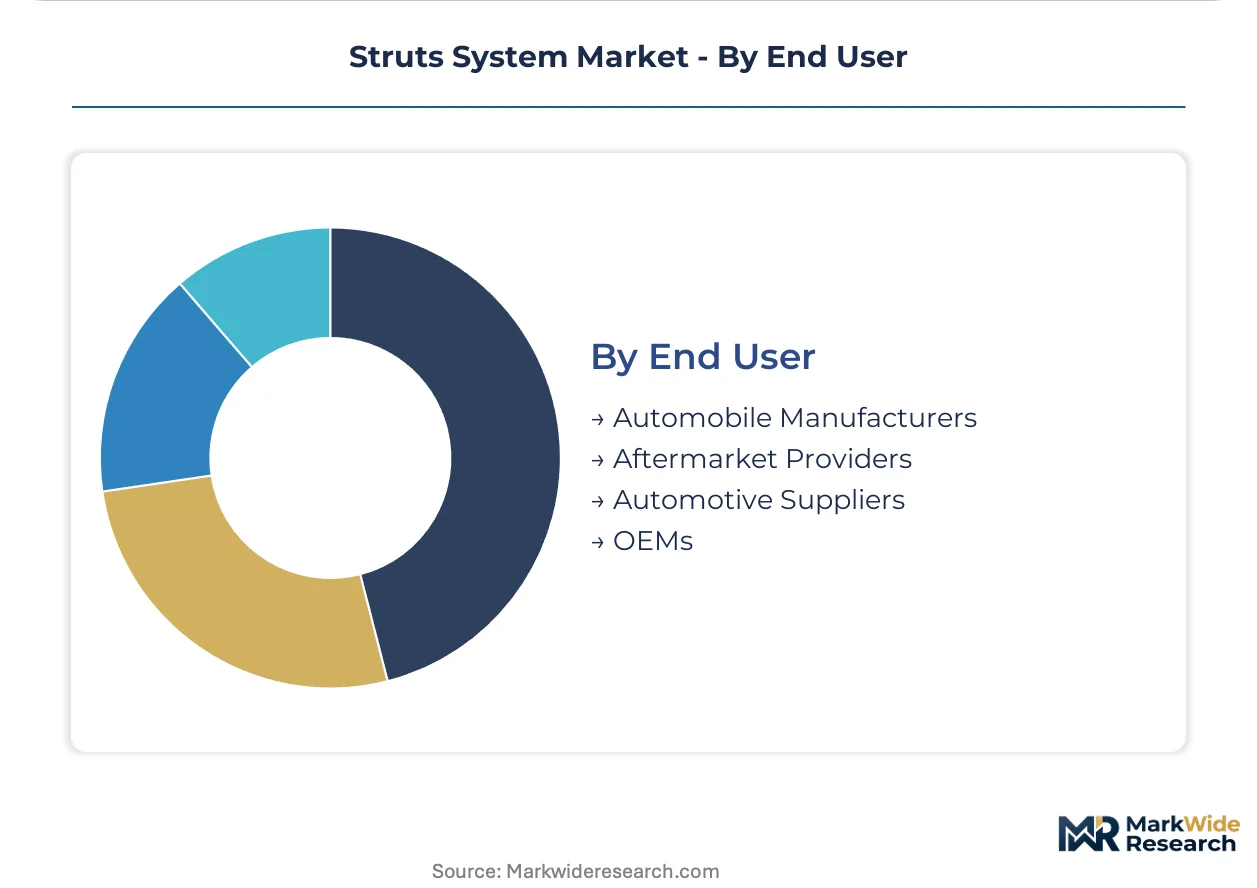
End User:
Customer type fragmentation separates captive OEM supply from independent aftermarket channels with divergent warranty and certification requirements.
- Automobile Manufacturers:Vehicle OEMs specifying complete strut modules for original equipment installation, consolidating damper and spring procurement under tier-one integrators. German and US automakers drive aluminum adoption through platform-sharing agreements that amplify volume leverage.
- OEMs:Captive component divisions and wholly-owned subsidiaries producing strut assemblies for parent-brand vehicles, controlling critical suspension intellectual property in-house.
- Automotive Suppliers:Independent tier-one and tier-two component manufacturers selling to multiple OEM customers.
- Aftermarket Providers:Remanufacturers and replacement part distributors serving vehicle service life extension.
Automobile Manufacturers represent the dominant procurement volume, with Aftermarket Providers expanding most quickly as average vehicle age extends across developed markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's premium automotive cluster anchors strut system engineering standards worldwide. Material substitution cycles and regulatory pressure vary sharply across manufacturing regions. Each geography presents distinct procurement patterns and compliance requirements.
United States
EPA fuel-economy mandates and NHTSA safety standards accelerate aluminum strut adoption among Detroit OEMs. The Inflation Reduction Act's domestic content provisions favor extrusion investments with renewable electricity sourcing. Michigan and Ohio house concentrated tier-one assembly capacity serving light-truck platform sharing.
Germany
MacPherson and multi-link architectures dominate platform decisions at luxury OEMs headquartered in Stuttgart and Munich. EU Green Deal carbon border adjustments and REACH chemical restrictions constrain coating chemistries. Baden-Württemberg's supplier corridor hosts specialized extruders serving adjustable camber rear suspension programs.
China
Dual carbon goals and MIIT new energy vehicle mandates reshape load-path requirements for battery-heavy skateboard platforms. Yangtze River Delta manufacturing clusters scale seam-welded steel tube forming for cost-optimized domestic brands. GB standards for structural integrity govern NHTSA-equivalent validation protocols.
Japan
METI energy efficiency regulations push unsprung mass reduction through 6xxx-series aluminum adoption. Kanto region OEMs integrate strut modules with hybrid powertrain packaging constraints. JIS welding certification requirements extend supplier qualification timelines relative to North American benchmarks.
Mexico
USMCA regional value content rules position Nuevo León and Bajío extrusion plants for North American automotive supply. Nearshoring momentum accelerates captive aluminum capacity investments. Mexican suppliers bridge steel legacy volumes and aluminum transition programs for cross-border OEM platforms.
Struts System Market Vendor Landscape
Global majors compete with regional champions across material processing and integration capabilities. The supplier base stratifies into tier-one system integrators with captive extrusion, specialized channel fabricators, and component-focused damper manufacturers. Three archetypes dominate: hydraulics-heritage diversified industrials, construction-channel standardization leaders, and automotive-captive suspension specialists. Competitive moves center on backward integration into aluminum extrusion and strategic partnerships for coating chemistry reformulation.
Among diversified industrial conglomerates, Eaton Corporation Inc. occupies a position exemplifying hydraulics-anchored expansion into heavy-duty commercial vehicle channels. Unistrut Corporation and Hilti Corporation represent contrasting archetypes within architectural and industrial support applications—standardized channel dominance versus fastening-integrated installation systems. These three entities illustrate how capability heritage shapes competitive positioning across automotive and construction end markets.
| Leading Market Players |
|---|
| Eaton Corporation Inc. |
| Unistrut Corporation |
| Cooper Industries |
| Hilti Corporation |
| Aetna Plastics Corp. |
| Enduro Pipeline Services Inc. |
| Atlas Supply Co. |
| ERICO Products Inc. |
| Guenther Supply Inc. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon border adjustment mechanisms gate qualified supply for European-market strut assemblies while simultaneously filtering premium-tier pricing access to OEMs with renewable-provenance aluminum sourcing. Tier-one integrators with verified low-carbon extrusion capacity capture pricing power as compliance costs escalate for legacy coating and material suppliers.
Pricing Analysis
Input-cost pass-through from LME aluminum volatility compresses margin predictability for extruded strut housing manufacturers locked into annual automotive OEM contracts. Three-tier pricing structure across premium, standard, and economy levels separates multi-link adjustable camber systems from MacPherson assemblies and steel legacy designs. Pricing pressure stems from REACH-compliant coating line retrofits absorbing twelve to eighteen months of capital deployment. Aftermarket remanufacturers exhibit highest price sensitivity due to compliance cost escalation, while German premium OEMs demonstrate lowest sensitivity for performance-validated architectures.
Supply Chain Analysis
Regional distribution centers in Michigan, Ohio, and Nuevo León operate hub-and-spoke patterns serving North American light-truck platform sharing. Primary aluminum extrusion concentrates in Germany, China, and Mexico, with seam-welded steel tube forming anchored in East Asian mill networks. Raw material dependencies draw from 6xxx-series aluminum billet, high-strength low-alloy steel coil, and trivalent chrome pretreatment chemistries. Tariff exposure on cross-border steel shipments presents structural risk to tier-two stampers. Distribution runs through OEM-captive assembly plants and independent aftermarket channels with divergent certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Struts System Market margin expansion rests on aluminum substitution economics as platform electrification redistributes mass budgets toward unsprung mass reduction. Premium-tier pricing access concentrates with integrators possessing captive extrusion and validated coating chemistry reformulation.
For Market Incumbents: Extend backward integration into aluminum extrusion capacity with renewable electricity provenance to defend against carbon border adjustment cost passthrough. Consolidate tier-two stamping and welding operations into continuous extrusion lines before multi-source procurement contracts expire. Lock long-term offtake agreements with Yangtze River Delta steel mills to hedge tariff volatility on legacy platform volumes. For New Entrants and Emerging Players: Direct-to-industrial procurement platforms offer white-space entry for architectural strut channel applications beyond automotive cyclicality. Heavy-duty commercial vehicle hydraulics integration remains underpenetrated relative to saturated passenger segments. Target fastening-integrated installation systems for prefabricated construction channels where labor-hour reduction commands specification premiums. For Investors and Strategic Acquirers: Roll-up economics work for regional extrusion specialists because EU Green Deal alignment rewards carbon-intensity differentiation with OEM volume concentration. Five-to-ten year viability favors European and North American assets with renewable energy sourcing over East Asian legacy steel exposure. Monitor carbon border adjustment implementation timelines as inflection indicator for qualified supply scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive 6xxx-series capacity secures margin control against LME volatility and carbon border adjustments. |
| Coating Chemistry Reformulation Partnership | REACH-compliant trivalent chrome and zirconium pretreatment validation accelerates European market access. |
| Platform Standardization Agreement | OEM skateboard architecture sharing amplifies volume leverage for qualified strut mounting geometries. |
| Geographic Manufacturing Footprint Expansion | USMCA-compliant Nuevo León extrusion plants capture nearshoring momentum for Detroit OEM procurement. |
| Aftermarket Channel Consolidation | OEM-captive rebuild operations absorb Eastern European remanufacturer compliance cost escalation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, coating chemistry specialists, and aluminum extrusion plant managers with secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from diversified industrial conglomerates, and EU ETS carbon intensity disclosures. Bottom-up bill-of-material buildups and top-down OEM platform sharing analysis triangulated volume and value estimates.
Comparable-period anchoring aligned the projection horizon against historical platform redesign cycles and material substitution adoption curves. Segmentation modeling spanned product type, application, material grade, and end-user archetype with propulsion architecture and regional production cluster overlays. CAGRs derived from weighted average of OEM procurement expansion scenarios and coating compliance cost trajectories. Key inputs included EPA fuel-economy mandate stringency pathways and NHTSA structural integrity requalification timelines.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery platform architectures would alter load-path requirements and strut mounting geometries across vehicle classes. Forecasts reflect assumptions regarding aluminum price stabilization and REACH enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Brake Actuator Market
Automotive Parts
Mexico Passenger Vehicles Lubricants Market
Automotive Parts
France Automotive Actuators Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Automotive Winches System (AWS) Market
Automotive Parts
Automotive Steering System Market
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
Colombia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
Brass Synchronizer Ring Market
Automotive Parts
Automotive Roller Bearing Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Autonomous Forklift Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market