
 South Africa Automotive Hydraulic Actuators Market | 2026-2036
South Africa Automotive Hydraulic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Automotive Hydraulic Actuators Market Analytics
Aftermarket parts distribution is narrowing as OEM-certified service networks consolidate control over replacement hydraulic actuator flows in South Africa. Robert Bosch GmbH leverages its technical training infrastructure to lock in workshop loyalty across the Gauteng and Eastern Cape corridors. Continental AG sustains direct supply relationships with major vehicle assemblers, bypassing fragmented import channels. Nidec Corporation specializes in compact electro-hydraulic units for steering applications, occupying a defensible niche against conventional cylinder suppliers.
Automotive hydraulic actuators are electromechanical devices that convert fluid pressure into linear or rotary mechanical motion, typically operating at working pressures between 70 and 210 bar using mineral oil-based hydraulic fluids. Their primary industrial purpose is to deliver precise, high-force motion control in vehicle subsystems where electric motors cannot match torque density or fail-safe requirements. Electro-hydraulic actuator technology leads in steering system applications due to its integration with electronic stability control architectures, while conventional hydraulic cylinders dominate brake system retrofits where fleet operators prioritize unit cost over smart functionality. Compact actuators represent the fastest-expanding product category as engine bay packaging tightens and thermal management demands intensify.
South Africa's National Regulator for Compulsory Specifications enforces SABS automotive standards that mandate durability testing for hydraulic components, while the Department of Trade, Industry and Competition administers local content requirements under the Automotive Production and Development Programme. These frameworks compel Tier-1 suppliers to maintain domestic assembly or face exclusion from OEM procurement lists. Stakeholders must monitor how carbon border adjustment mechanisms in export destination markets reshape the cost calculus for locally manufactured actuators.
Market Dynamics
The Gauteng industrial corridor's concentration of OEM assembly plants and Tier-1 supplier parks is compressing procurement timelines and forcing hydraulic actuator suppliers to co-locate technical support and inventory buffers within 50 kilometers of Pretoria and Johannesburg.
Growth Catalysts
- Automotive Production and Development Programme:South Africa's Department of Trade, Industry and Competition administers local content requirements that compel Tier-1 suppliers to maintain domestic actuator assembly or face exclusion from OEM procurement lists.
- Electro-hydraulic steering integration:Electronic stability control architectures in light commercial vehicles are pulling demand for compact electro-hydraulic units that deliver precise torque density where electric motors fail.
- Eastern Cape corridor expansion:Vehicle assemblers serving export markets are extending supplier park requirements into Port Elizabeth and East London, creating secondary demand clusters beyond Gauteng.
Market Restraints
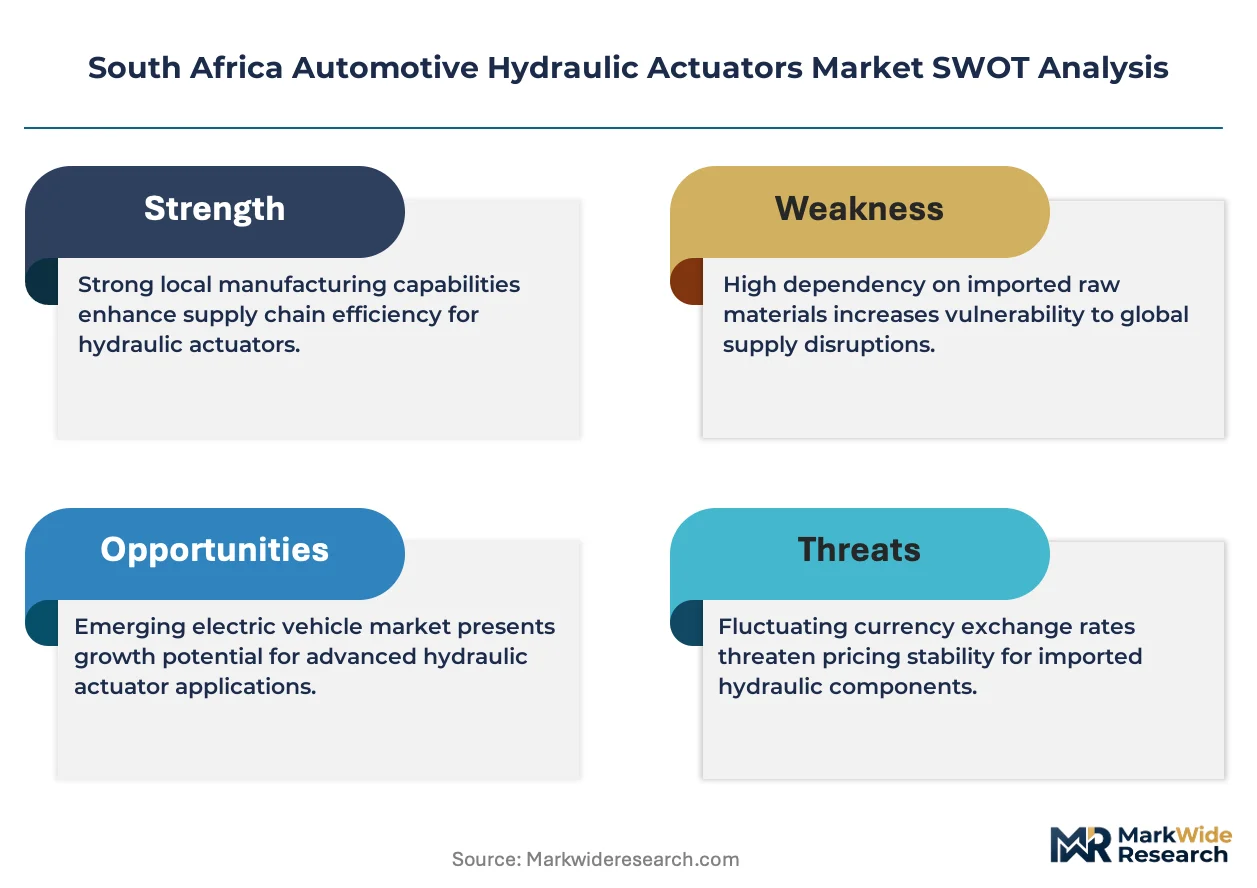
- Mineral oil fluid dependency:Conventional hydraulic actuators require petroleum-based hydraulic fluids operating between 70 and 210 bar, exposing manufacturers to crude price volatility and import duty exposure on specialty lubricants.
- Single-province supply concentration:Over 70 percent of domestic actuator demand concentrates in Gauteng province, creating geographic vulnerability to logistics disruptions on the N1 and N3 freight corridors.
- Electric power steering substitution:Full-electric steering systems are penetrating passenger vehicle segments, eroding the addressable market for hydraulic steering actuators in volume car platforms.
Strategic Opportunities
- KwaZulu-Natal supplier park development:The Richards Bay industrial zone and Durban automotive logistics hub remain underpenetrated by hydraulic actuator assemblers despite Toyota's expanding presence in Prospecton.
- Brake system retrofit aftermarket:Fleet operators prioritizing unit cost over smart functionality are sustaining demand for conventional hydraulic cylinders in heavy commercial brake retrofits.
- Carbon border adjustment alignment:South African manufacturers can capture preferential access to EU export markets by certifying actuator production under emerging carbon intensity standards tied to the EU Green Deal implementation timeline.
Industry Challenges
- SABS durability certification timelines:South Africa's National Regulator for Compulsory Specifications mandates extended testing protocols for hydraulic components, stretching product approval cycles and freezing inventory capital.
- Electro-mechanical integration skill scarcity:The convergence of hydraulic systems with electronic stability control architectures demands technicians fluent in both fluid power and embedded software diagnostics, a combination scarce in Gauteng technical colleges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Automotive Hydraulic Actuators Market |
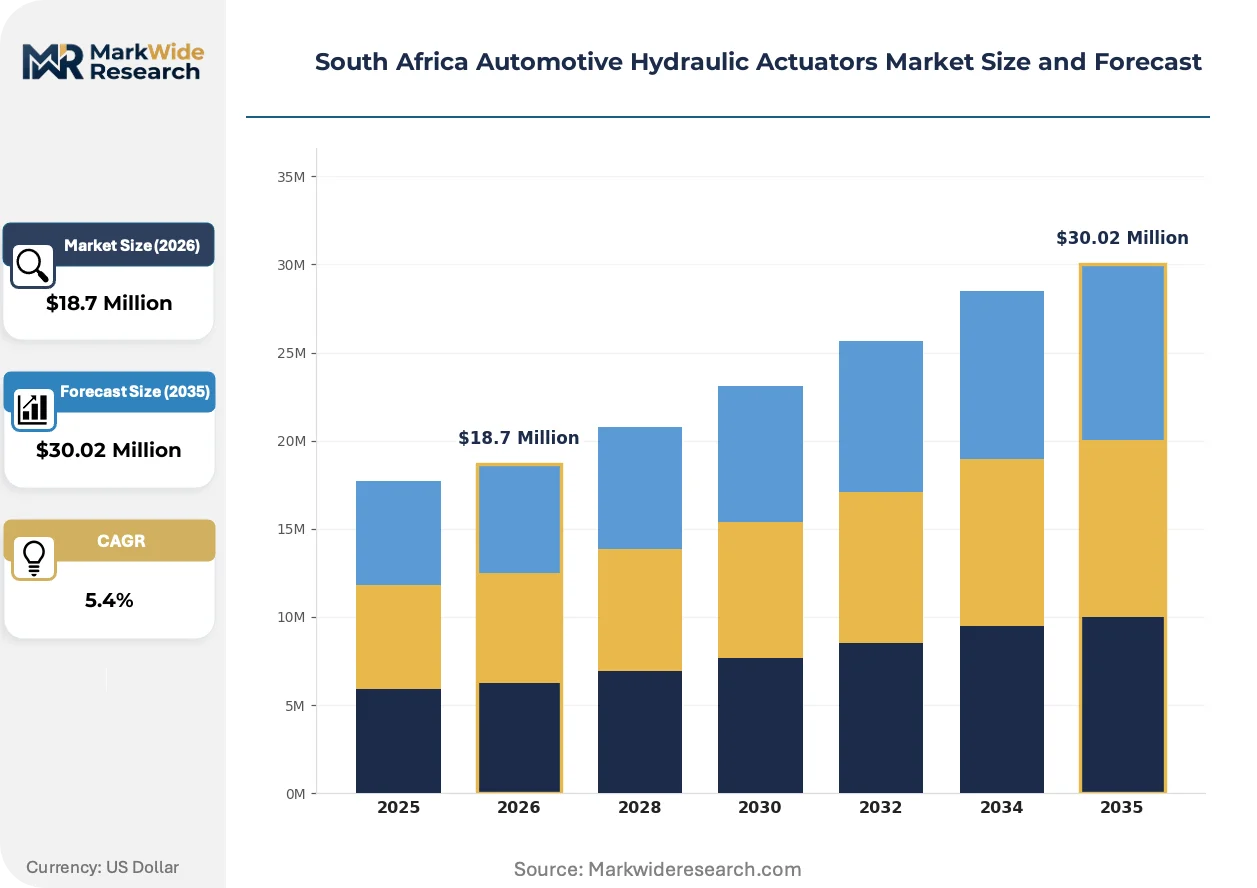
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $30.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Actuator Cylinder, Electro-Hydraulic, Compact Actuator, Rotary Actuator Application: Steering Systems, Brake Systems, Suspension Systems, Powertrain Systems End User: Original Equipment Manufacturers, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Conventional Hydraulic, Smart Hydraulic, Pneumatic Assistance, Hybrid Actuation |
| Companies Covered | Denso Corporation, Nidec Corporation, Mitsubishi Electric Corporation, Hitachi Ltd, Continental AG, Robert Bosch GmbH, BorgWarner Inc, Aptiv Plc, ZF Friedrichshafen AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Automotive Hydraulic Actuators Market Evolving Landscape
Compact packaging requirements and thermal management intensification in engine bays are accelerating product architecture shifts across South Africa's automotive hydraulic actuator supply base.
Electro-hydraulic actuator technology is rendering obsolete conventional hydraulic cylinders in steering applications. Light commercial vehicle assemblers serving the Gauteng corridor are adopting compact electro-hydraulic units at pace, integrating them with electronic stability control architectures. This convergence is compressing the market for standalone hydraulic steering components and forcing traditional cylinder suppliers to retrain engineering teams or exit steering segments entirely.
South Africa's National Regulator for Compulsory Specifications enforces SABS automotive standards that mandate durability testing for hydraulic components. These frameworks compel Tier-1 suppliers to maintain domestic assembly capabilities or face exclusion from OEM procurement lists. Compact actuator categories face the steepest compliance burden, as thermal cycling and pressure-fatigue tests must validate performance in engine bay configurations with reduced cooling airflow.
Fleet procurement patterns are compressing replacement cycles for brake system actuators. Heavy commercial operators in the Johannesburg-Pretoria freight corridor are unbundling after-sales service contracts and sourcing hydraulic cylinders directly from certified distributors, bypassing traditional parts aggregators. This channel disintermediation is most visible in the long-haul trucking segment, where uptime guarantees now override historical loyalty to OEM service networks.
South Africa Automotive Hydraulic Actuators Market Segmentation
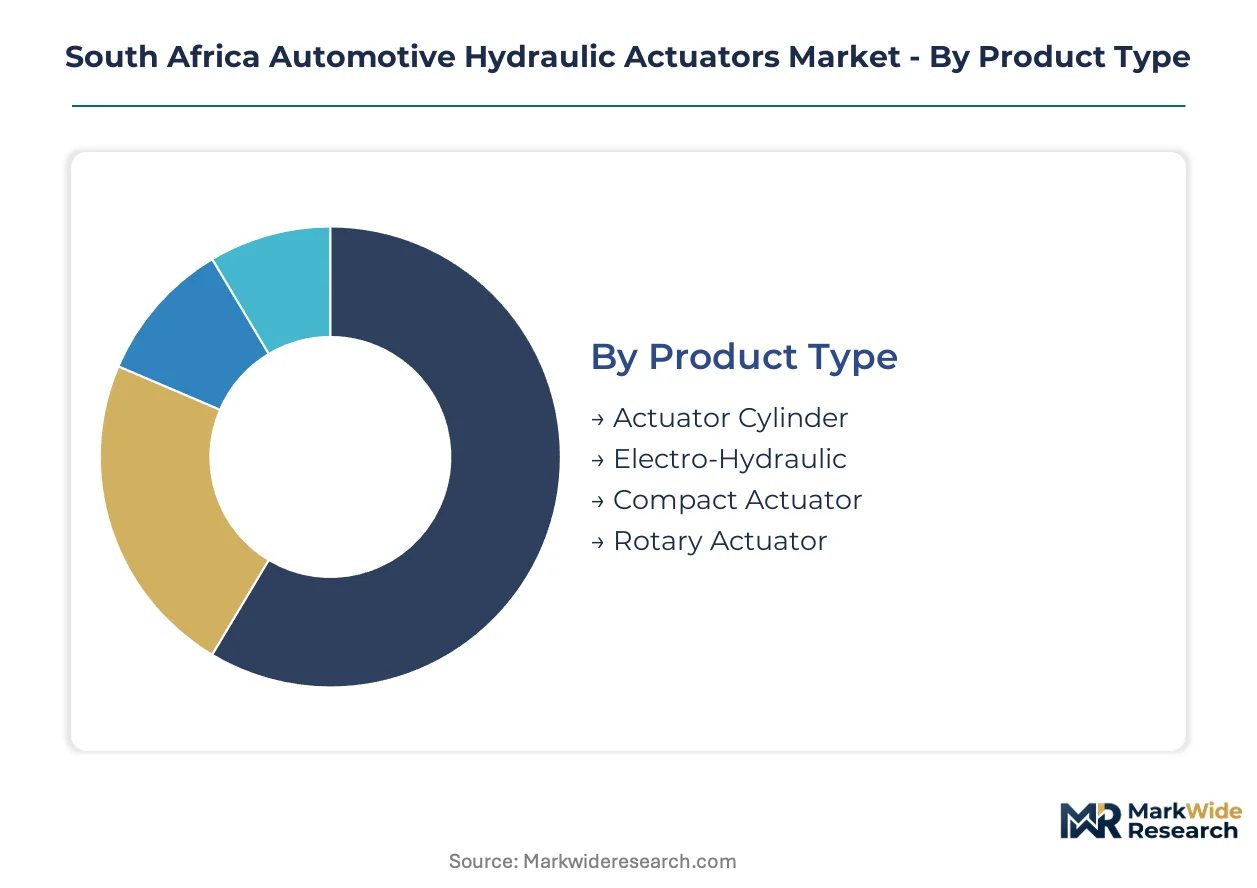
Segmentation in South Africa's automotive hydraulic actuator market reveals how after-sales service intensity varies dramatically across product categories and customer channels. Suppliers must align inventory depth and technical support resources with segment-specific replacement frequencies and diagnostic complexity.
Product Type:
After-sales service intensity escalates with electronic integration levels, creating divergent support models across the Gauteng supplier base.
- Actuator Cylinder:Conventional single-rod and double-rod cylinders dominate brake retrofits in Johannesburg's heavy commercial fleet sector. Demand concentrates among independent workshops serving long-haul operators who prioritize unit cost over smart functionality and accept higher replacement frequencies.
- Electro-Hydraulic:Integrated servo-valve architectures with embedded position sensors command premium service contracts from OEM-certified networks. Pretoria-based assemblers specify these units for electronic stability control integration in light commercial platforms, where precise torque density outweighs electric motor alternatives.
- Compact Actuator:Miniaturized units with reduced cooling surface area serve engine bay packaging constraints in Gauteng's tightest thermal envelopes.
- Rotary Actuator:Vane and gear-type rotary units occupy niche powertrain applications with limited aftermarket penetration.
By volume, Actuator Cylinder leads. By growth pace, Electro-Hydraulic is ahead.
Application:
Cost tier stratification separates premium OEM-specified systems from economy retrofit alternatives across the Eastern Cape export corridor.
- Steering Systems:Rack-and-pinion electro-hydraulic units integrate with vehicle stability architectures in Port Elizabeth-assembled light commercials. East London vehicle assemblers specify these for export markets where EU safety mandates demand fail-safe redundancy.
- Brake Systems:Master cylinder and ABS modulator actuators sustain the highest replacement velocities in Johannesburg-Pretoria freight corridors. Fleet operators unbundle service contracts and source directly from certified distributors, compressing channel margins.
- Suspension Systems:Self-leveling and active damping actuators serve premium commercial platforms with limited aftermarket replication.
- Powertrain Systems:Clutch and transmission actuators face displacement by full-electric alternatives in passenger vehicle segments.
Brake Systems generates the highest unit volume. Steering Systems shows the steepest expansion trajectory as electronic integration deepens.
End User:
Customer type determines procurement leverage, with captive OEM networks extracting stricter local content compliance than independent channels.
- Original Equipment Manufacturers:Ford, Toyota, and Isuzu operations in Pretoria and Port Elizabeth mandate SABS-certified domestic assembly. Their procurement lists exclude suppliers lacking in-country technical support within 50 kilometers of assembly plants.
- Aftermarket Providers:Fragmented distributors in Gauteng's Malvern and Denver industrial zones serve independent workshops with non-certified alternatives. These channels bypass OEM service networks but face narrowing product availability as certified networks consolidate control.
- Tier-1 Suppliers:Bosch and Continental direct supply relationships dominate steering and brake system integration.
- Vehicle Assemblers:Contract manufacturers for export markets face carbon border adjustment exposure on actuator embedded emissions.
Aftermarket Providers move the highest unit count. Tier-1 Suppliers capture margin concentration through direct OEM relationships.
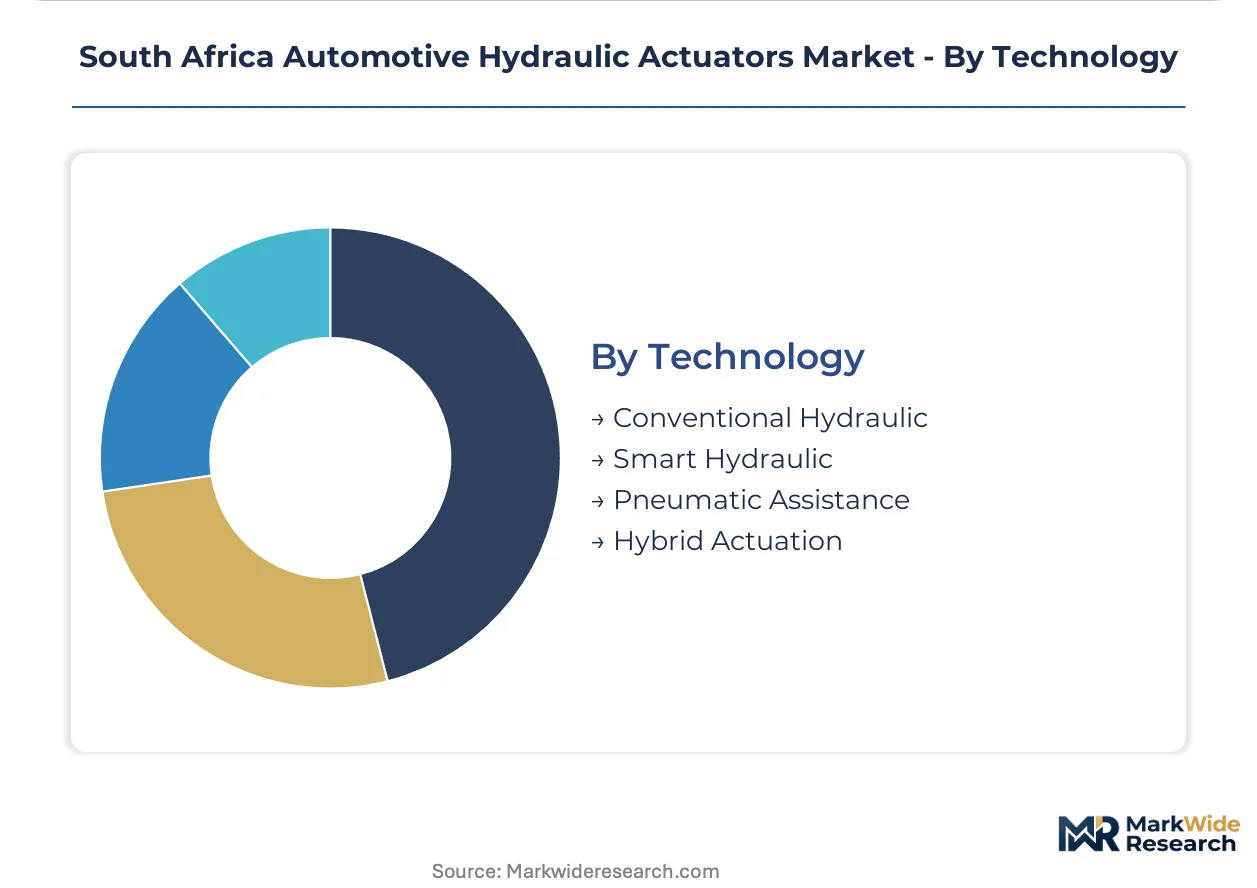
Technology:
Supply concentration in Gauteng's Tier-1 supplier parks favors integrated smart systems over conventional alternatives.
- Conventional Hydraulic:Open-loop systems with fixed displacement pumps retain cost advantage in heavy commercial brake retrofits. Mineral oil fluid dependency between 70 and 210 bar exposes operators to crude price volatility and specialty lubricant import duties.
- Smart Hydraulic:Closed-loop architectures with pressure feedback and predictive maintenance algorithms command OEM specification. These systems integrate with fleet telematics platforms serving Johannesburg-based logistics operators who monetize uptime guarantees.
- Pneumatic Assistance:Air-over-hybrid units serve limited heavy-duty applications with compressed air infrastructure.
- Hybrid Actuation:Electric-hydraulic combinations face technical college skill scarcity in embedded software diagnostics.
Conventional Hydraulic retains volume dominance. Smart Hydraulic is climbing the fastest as electronic stability control architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Durban-Gauteng freight corridor and Richards Bay port infrastructure anchor South Africa's hydraulic actuator distribution network, channeling mineral oil-based components into the country's densest automotive assembly zones.
Gauteng Province
Pretoria and Johannesburg host Ford, Toyota, and Isuzu assembly operations that specify electro-hydraulic steering units for light commercial platforms. The National Regulator for Compulsory Specifications enforces SABS durability testing that stretches approval timelines for suppliers. Tier-1 supplier parks in Rosslyn and Silverton compress procurement windows, forcing actuator assemblers to maintain technical support within 50 kilometers.
Eastern Cape
Port Elizabeth and East London vehicle assemblers serving EU export markets drive demand for fail-safe redundant steering actuators. The Automotive Production and Development Programme mandates local content thresholds that compel domestic actuator assembly. Supplier park expansion into Coega IDZ is pulling hydraulic component distributors eastward from Gauteng.
KwaZulu-Natal
Toyota's Prospecton assembly plant generates concentrated demand for brake system actuators in heavy commercial configurations. The province's underpenetrated supplier infrastructure creates procurement bottlenecks for Tier-1 hydraulic integrators. Richards Bay industrial zone development is attracting actuator warehousing investments to reduce N3 corridor dependency.
Western Cape
Cape Town's limited automotive assembly footprint constrains hydraulic actuator demand to aftermarket channels serving long-haul freight operators. The region's port infrastructure handles specialty lubricant imports for mineral oil-based systems operating at 70-210 bar. Independent workshops in Epping industrial precinct source conventional cylinders directly from certified distributors.
South Africa Automotive Hydraulic Actuators Market Competitive Landscape
On the supply side, the industry is consolidating around OEM-certified networks that bypass fragmented import channels. Tier-1 integrators dominate steering and brake system specification through direct assembler relationships, while conventional cylinder suppliers compete on unit cost in heavy commercial retrofits. Two strategic archetypes define positioning: electro-hydraulic specialists capturing electronic stability control integration, and mineral oil-based fabricators serving price-sensitive fleet operators. Competitive moves center on technical training infrastructure deployment and domestic assembly capacity expansion to satisfy local content requirements.
Within the integrated systems tier, Continental AG and Robert Bosch GmbH exemplify the direct OEM supply model that dominates Gauteng and Eastern Cape corridors. Nidec Corporation occupies a position among electro-hydraulic specialists, anchoring the compact actuator segment where electronic stability control architectures drive specification. These three entities represent the spectrum from full-system integration to component specialization, with each archetype facing distinct compliance burdens under SABS certification protocols.
| Leading Market Players |
|---|
| Denso Corporation |
| Nidec Corporation |
| Mitsubishi Electric Corporation |
| Hitachi Ltd |
| Continental AG |
| Robert Bosch GmbH |
| BorgWarner Inc |
| Aptiv Plc |
| ZF Friedrichshafen AG |
| Others |
Value Network & Pricing Analysis
Mineral oil fluid import duty exposure on specialty lubricants operating between 70 and 210 bar determines both three-tier pricing spreads across premium electro-hydraulic, standard conventional cylinder, and economy brake retrofit segments, and the Gauteng-centric supply chain shape that forces inventory buffers within 50 kilometers of Pretoria assembly plants.
Pricing Analysis
Volume-discount tiering structures separate OEM-certified electro-hydraulic units with embedded stability control integration from non-certified conventional cylinders sold through independent distributors. Price differentiation rests on SABS certification grade and after-sales service bundling rather than raw component quality. Cost compression in economy brake retrofit tiers is intensifying because fleet operators unbundle service contracts and source directly from certified distributors. Heavy commercial fleet operators in Johannesburg-Pretoria corridors exhibit highest price sensitivity; OEM-specified steering system buyers show lowest.
Supply Chain Analysis
Export-control regimes limiting electro-hydraulic servo-valve technology flows from Germany and Japan constrain Tier-1 supplier access to smart actuator architectures. Geographic supply concentration centers on Germany for precision valve components, China for steel castings and machined housings, and Japan for compact electro-hydraulic integration modules. Raw material dependencies draw from specialty steel alloys, high-grade mineral oil formulations, and rare-earth magnets for position sensing. Single-source vulnerability on N1 and N3 freight corridors creates logistics chokepoint risk. Distribution runs through OEM-certified technical support networks rather than fragmented import channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM-certified service network consolidation is shifting buyer power toward Ford, Toyota, and Isuzu procurement teams in Pretoria and Port Elizabeth, compressing margins for independent aftermarket distributors in Gauteng's Malvern and Denver industrial zones.
For Market Incumbents: Build technical training infrastructure moats by expanding Bosch-style workshop certification programs across Eastern Cape corridors to lock out emerging electro-hydraulic specialists. Deepen backward integration into domestic actuator assembly to satisfy Automotive Production and Development Programme local content thresholds and exclude import-dependent competitors from OEM procurement lists. Electric power steering substitution in passenger segments threatens hydraulic steering actuator volumes; counter by capturing light commercial platform specifications where torque density requirements persist. For New Entrants and Emerging Players: Build out KwaZulu-Natal supplier park presence in Richards Bay industrial zone and Durban automotive logistics hub, territories where Toyota's Prospecton expansion has outpaced hydraulic actuator assembler penetration. Target brake system retrofit aftermarket serving heavy commercial fleet operators who prioritize unit cost over smart functionality and accept higher replacement frequencies. Pursue direct distributor relationships with Johannesburg-Pretoria long-haul operators who have unbundled OEM service contracts. For Investors and Strategic Acquirers: Electro-hydraulic component specialists with SABS certification capabilities and existing OEM technical support infrastructure within 50 kilometers of Gauteng assembly plants represent prime acquisition targets. Long-term viability hinges on carbon border adjustment alignment for EU export market access as the EU Green Deal implementation timeline tightens embedded emissions standards. Watch for SABS durability certification timeline extensions as inflection indicators that would freeze inventory capital and favor incumbent suppliers with established testing relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Capacity Expansion | Satisfies Automotive Production and Development Programme local content requirements for Ford, Toyota, and Isuzu procurement lists. |
| Electro-Hydraulic Steering Integration | Captures light commercial platform specifications where electronic stability control architectures demand precise torque density. |
| Technical Training Infrastructure Deployment | Locks workshop loyalty across Gauteng and Eastern Cape corridors through Bosch-style certification programs. |
| Carbon Border Adjustment Certification | Secures preferential EU export market access under emerging carbon intensity standards tied to EU Green Deal timelines. |
| KwaZulu-Natal Supplier Park Development | Reduces N3 corridor dependency and captures Toyota Prospecton demand in underpenetrated Richards Bay industrial zone. |
Research Methodology
A standing panel of Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors in Gauteng's industrial zones, and SABS certification specialists provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against vehicle production databases, IHS Markit registration data, customs and trade records for mineral oil fluid imports, and Automotive Production and Development Programme compliance filings. Bottom-up segment sizing triangulated against top-down production forecasts.
Scenario-bracketing framed demand projections across the analysis window, modeling vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from production volume trajectories, technology substitution curves for electric power steering penetration, and local content requirement enforcement intensity. Industry-specific inputs included SABS durability certification timeline data and fleet operator contract unbundling patterns in Johannesburg-Pretoria freight corridors.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by electro-hydraulic specialists or accelerated EU carbon border adjustment implementation would shift outcomes. Material shifts in Automotive Production and Development Programme local content thresholds or SABS testing protocol extensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Stampings Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Air Filter Cartridges Market
Automotive Parts
Automotive Brake Fluid Market
Automotive Parts
India Automotive Hydraulic Actuators Market
Automotive Parts
Automobile Muffler Market
Automotive Parts
Automotive Fluids Market
Automotive Parts
Automotive Valve Stem Seal Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
Industrial Roller Chain Drives Market
Automotive Parts
Global Passenger Vehicles Lubricants Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
ASEAN Automotive Bearings Market
Automotive Parts
Automotive Air Conditioning Electric Scroll Compressors Market
Automotive Parts
Variable Valve Timing (VVT) Market