
 Automotive Variable Valve Timing Market | 2026-2036
Automotive Variable Valve Timing Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Variable Valve Timing Market Outlook
A capital-intensity divergence between integrated camshaft producers and component specialists is rotating competitive advantage toward manufacturers with captive foundry and precision machining capabilities. BorgWarner Inc. leverages its powertrain systems integration to bundle VVT with turbocharger packages. Schaeffler AG anchors European supply through its valve train component specialization and proximity to German OEM headquarters. DENSO Corporation dominates Asian sourcing channels with vertically controlled electromagnetic actuator production.
Automotive Variable Valve Timing comprises electro-hydraulic systems that modulate camshaft phasing relative to crankshaft position, typically operating within 0-60 degrees of angular adjustment authority to optimize intake and exhaust valve events across engine speed load maps. The technology reduces pumping losses and enables Atkinson-cycle operation, directly serving fuel economy mandates in both spark-ignition and compression-ignition engines. Cam phaser hardware claims the largest installed base among technology segments, though electromagnetic actuator configurations are gaining share in hybrid powertrains demanding faster response transients. Passenger car applications generate the dominant revenue pool, while commercial vehicle adoption remains constrained by diesel engine lifecycle amortization schedules and simpler valvetrain architectures.
EPA tailpipe standards, Euro 7 emissions frameworks, and China's MIIT fuel consumption regulations collectively mandate CO2 and particulate reductions that VVT hardware directly enables through combustion optimization. NHTSA corporate average fuel economy enforcement in the United States and REACH substance restrictions on hydraulic fluids in Europe further shape material selection and actuator design specifications. Stakeholders must monitor regulatory phase-in calendars against electrification timelines to calibrate internal combustion investment horizons and hybrid system content decisions.
Market Dynamics
Electrification timelines are compressing internal combustion engine investment horizons, forcing suppliers to extract maximum efficiency from remaining ICE platforms while pivoting actuator architectures toward hybrid powertrain compatibility.
Growth Catalysts
- EPA Tier 3 tailpipe standards:These regulations mandate NOx and particulate reductions that cam phaser hardware enables through optimized valve timing. OEMs in the United States upgrade valvetrain systems to avoid fleet-wide penalties.
- Passenger car OEM procurement:Volume manufacturers in China, Japan, and Germany source integrated VVT modules to meet corporate average fuel economy targets. Engine production clusters concentrate demand in these geographies.
- Electromagnetic actuator technology:Faster response transients suit hybrid powertrains with frequent engine stop-start cycles. This configuration gains share against electro-hydraulic alternatives in electrified architectures.
Market Restraints
- Neodymium and dysprosium price volatility:Rare earth magnet costs in electromagnetic actuators fluctuate with Chinese export quotas. Supply concentration in Inner Mongolia creates input cost instability for precision component manufacturers.
- Diesel engine lifecycle amortization:Commercial vehicle operators extend service intervals on compression-ignition platforms, delaying VVT hardware retrofits. Simpler valvetrain architectures persist in heavy-duty segments.
- REACH hydraulic fluid restrictions:ECHA substance limitations on traditional actuator oils force reformulation investments. European suppliers absorb compliance costs without proportional pricing power recovery.
Strategic Opportunities
- India's MIIT-equivalent fuel consumption regulations:Stricter efficiency mandates for passenger vehicles create first-fit demand as domestic engine production scales. Local assembly of cam phaser modules avoids import duty exposure.
- Turbocharger-VVT bundling:Powertrain system integration contracts combine variable valve timing with forced induction hardware. This convergence captures share from standalone component sourcing.
- 48V mild-hybrid architectures:Belt-driven starter-generator systems require rapid valve event adjustment during torque-fill operations. Electromagnetic configurations penetrate this emerging application segment.
Industry Challenges
- Precision machining talent scarcity:Cam phaser manufacturing requires sub-micron tolerance grinding expertise. German and Japanese suppliers compete for limited pools of specialized technicians.
- Legacy engine controller integration:New actuator protocols must communicate with existing ECU software stacks without full powertrain redesign. Validation timelines extend development cycles.
- Foundry capacity allocation:Ductile iron casting for phaser housings competes with brake rotor and suspension component demand. Automotive tier-one suppliers prioritize electrification-related castings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Variable Valve Timing Market |
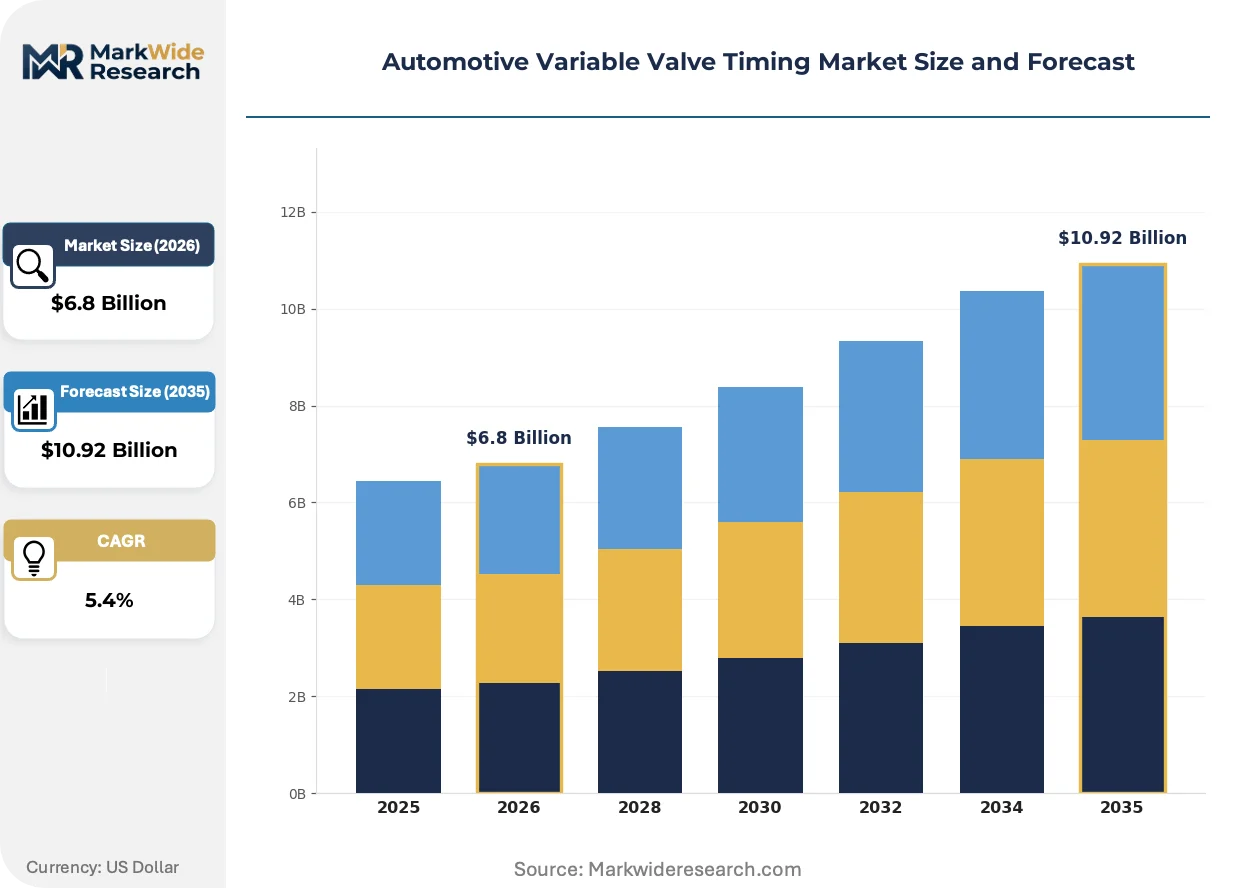
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: VVT Solenoid, Cam Phaser, Hydraulic Actuator, Electromagnetic Actuator Product Type: Passenger Car, Commercial Vehicle, Heavy-Duty Truck, Two-Wheeler Fuel Type: Gasoline, Diesel, Ethanol, Hybrid End User: OEM, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Eaton Corporation, Robert Bosch GmbH, DENSO Corporation, Mitsubishi Electric Corporation, Hitachi Automotive, BorgWarner Inc., Aisin Seiki Co. Ltd, Valeo, Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Variable Valve Timing Market Strategic Shifts
Actuator architecture is bifurcating between evolutionary electro-hydraulic refinement and electromagnetic disruption, with material selection and control software emerging as differentiation vectors rather than mechanical design alone.
Electromagnetic cam phaser technology is decomposing the traditional electro-hydraulic installed base in hybrid powertrain applications. Premium OEMs in Germany and Japan specify electromagnetic configurations for 48V mild-hybrid engines requiring sub-100-millisecond valve event adjustments. The shift is compressing demand for precision-machined hydraulic valve bodies while expanding rare-earth magnet procurement requirements.
China's MIIT fuel consumption regulations are tightening enforcement thresholds for passenger vehicle fleets. Domestic OEMs accelerate VVT content per engine to avoid corporate penalties. The policy pressure concentrates hardware demand in Shanghai, Beijing, and Guangzhou manufacturing corridors where engine assembly plants cluster.
Powertrain procurement teams now specify integrated valve train modules rather than discrete cam phaser components. Tier-one suppliers with captive machining and assembly capabilities capture share from component specialists. This consolidation is most visible in Japanese keiretsu sourcing structures where system-level accountability reduces supplier management overhead.
Automotive Variable Valve Timing Market Segmentation
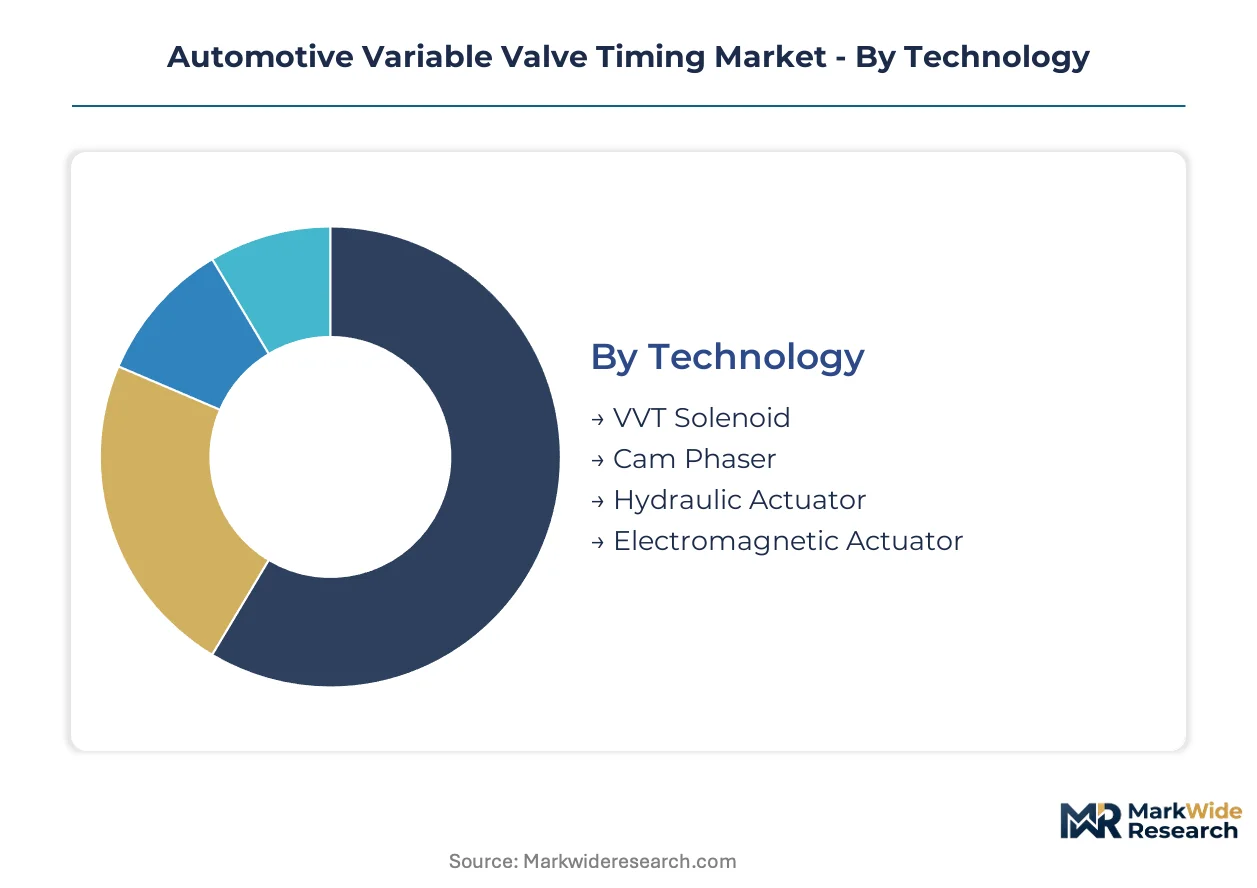
VVT hardware specifications diverge sharply across powertrain architectures, with regulatory stringency in specific countries dictating technology selection and procurement channel preferences. Segment boundaries reflect these compliance-driven hardware upgrades rather than simple vehicle classification.
Technology:
EPA Tier 3 and Euro 7 thresholds create divergent adoption curves across actuator architectures, with electromagnetic configurations gaining regulatory preference for hybrid compatibility.
- Cam Phaser:Electro-hydraulic cam phasers modulate intake and exhaust valve events through oil-pressure-driven rotor-vane mechanisms, achieving 0-60 degree authority ranges. Passenger car OEMs in Germany and Japan specify this hardware for volume gasoline engines where proven durability meets cost targets. Established volume favors cam phaser hardware; emerging adoption favors electromagnetic actuators.
- Electromagnetic Actuator:Rare-earth magnet configurations eliminate hydraulic fluid dependencies while enabling sub-100-millisecond response transients. China's MIIT fuel consumption regulations accelerate procurement for 48V mild-hybrid powertrains manufactured in Shanghai and Beijing corridors.
- VVT Solenoid:Precision-wound electromagnetic coils control oil flow routing to phaser mechanisms, with EPA Tier 3 compliance driving replacement demand in United States aftermarket channels.
- Hydraulic Actuator:Piston-and-sleeve architectures persist in commercial vehicle applications where extended service intervals amortize hardware costs across diesel engine lifecycles.
Established volume favors cam phaser hardware; emerging adoption favors electromagnetic actuators.
Product Type:
Vehicle weight classifications and duty cycles determine valvetrain complexity, with corporate average fuel economy penalties concentrating hardware investment in light-duty segments.
- Passenger Car:Four-cylinder and V6 architectures dominate VVT content per engine, with dual-overhead-cam configurations requiring separate intake and exhaust phasers. Japanese keiretsu sourcing structures concentrate procurement in Toyota City and Hiroshima manufacturing basins where engine plants cluster.
- Commercial Vehicle:Diesel powertrains in heavy-duty segments retain simpler valvetrain architectures due to lifecycle amortization schedules and lower RPM operating envelopes. Euro 7 particulate standards are forcing hardware upgrades in German and French fleet vehicles.
- Heavy-Duty Truck:Compression-ignition platforms in long-haul applications prioritize durability over valve event precision, with VVT penetration lagging passenger car adoption by multiple product cycles.
- Two-Wheeler:Single-cylinder engines in Indian and Southeast Asian markets adopt simplified cam phaser designs where cost constraints limit actuator sophistication.
Passenger car procurement absorbs the dominant hardware volume; commercial vehicle segments present retrofit opportunity as emissions phase-ins tighten.
Fuel Type:
Combustion chemistry and thermal efficiency targets reshape VVT calibration requirements across spark-ignition and compression-ignition architectures.
- Gasoline:Port and direct-injection spark-ignition engines leverage variable valve timing for Atkinson-cycle operation, with EPA corporate average fuel economy enforcement driving content proliferation in United States passenger fleets.
- Hybrid:Power-split and P2 architectures demand rapid valve event adjustment during engine restart sequences, with electromagnetic actuators penetrating 48V mild-hybrid systems specified by German premium OEMs.
- Diesel:Compression-ignition valvetrains prioritize exhaust gas recirculation compatibility over intake phasing range, with simpler hardware configurations prevailing in commercial vehicle duty cycles.
- Ethanol:Flex-fuel engines in Brazilian and United States Midwest markets require hardened valve seat materials and modified phaser oil specifications to accommodate alcohol combustion byproducts.
Gasoline applications anchor current installed base; hybrid powertrains are climbing the fastest adoption trajectory.
End User:
Procurement authority and validation responsibility determine supplier relationship structures, with system-level accountability consolidating toward integrated powertrain providers.
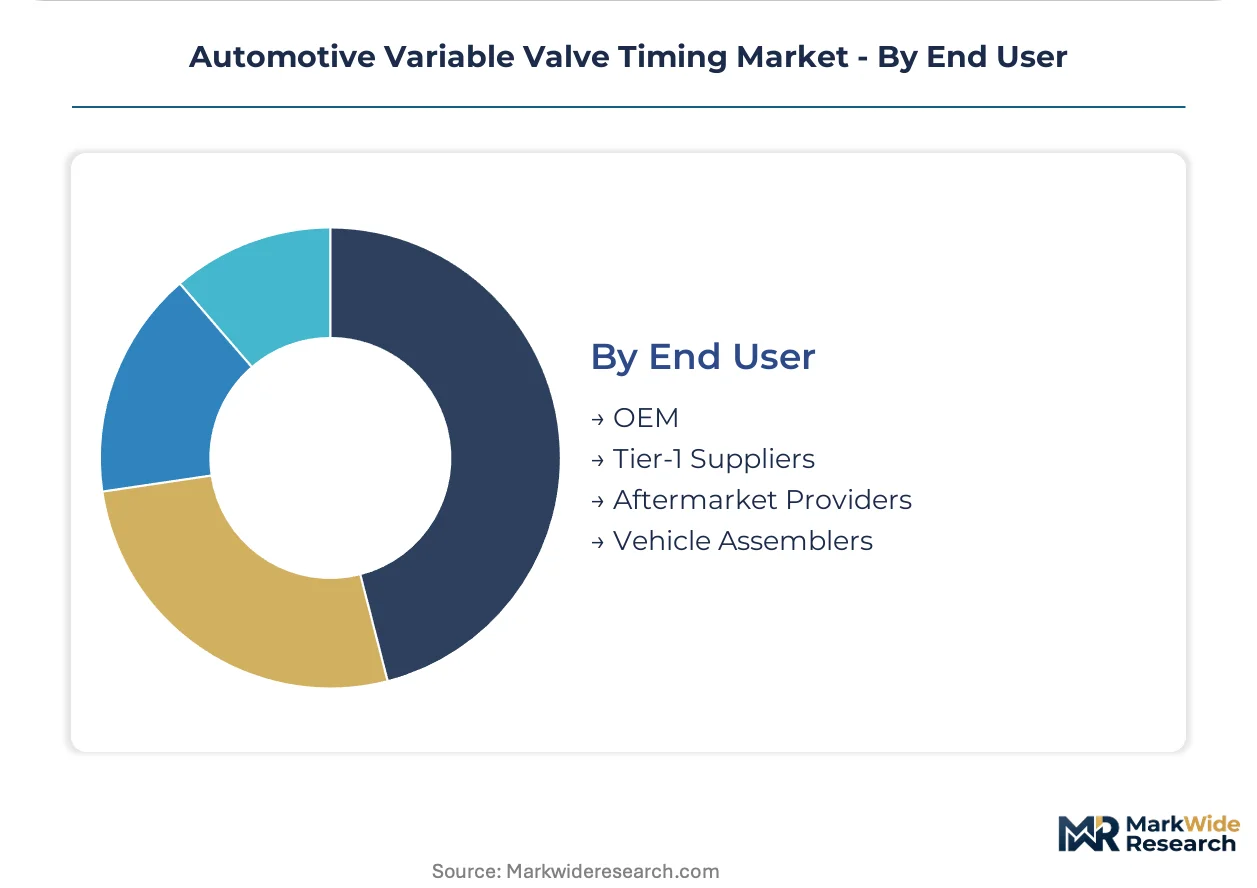
- OEM:Volkswagen Group, Toyota Motor Corporation, and Hyundai Motor Group specify complete valve train modules rather than discrete components, capturing engineering integration value in-house.
- Tier-1 Suppliers:BorgWarner, Schaeffler, and DENSO bundle VVT with turbocharger or transmission hardware, leveraging powertrain system integration contracts to displace standalone component sourcing.
- Aftermarket Providers:Independent distributors serve replacement demand for cam phaser solenoids and seals in aging United States and European vehicle parcs.
- Vehicle Assemblers:Contract manufacturers in emerging markets source pre-calibrated VVT modules from tier-one suppliers to avoid proprietary engine controller development costs.
Direct OEM procurement commands premium pricing; tier-1 system integration captures volume growth in electrified architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds that in China by a substantial margin, reflecting divergent regulatory enforcement timelines and captive machining capabilities. Japanese suppliers command intermediate premiums through keiretsu sourcing structures. The geographic distribution of VVT hardware procurement tracks engine production clustering and emissions mandate phase-in calendars.
China
Domestic OEMs accelerate VVT content per engine to avoid MIIT corporate penalties on passenger vehicle fleets. The ministry tightens enforcement thresholds annually, forcing hardware upgrades in Shanghai, Beijing, and Guangzhou manufacturing corridors. Engine assembly plants cluster in these coastal cities where tier-one suppliers operate captive machining facilities.
Germany
Premium OEMs specify electromagnetic configurations for 48V mild-hybrid engines requiring sub-100-millisecond valve adjustments. Euro 7 particulate standards force valvetrain upgrades across Volkswagen Group and BMW production lines. Bavaria and Baden-Württemberg house concentrated supplier engineering centers serving Stuttgart and Munich headquarters.
United States
EPA Tier 3 tailpipe mandates drive cam phaser retrofits to avoid fleet-wide NOx penalties. NHTSA corporate average fuel economy enforcement concentrates procurement in Detroit and Southeast assembly corridors. Tier-one suppliers bundle VVT with turbocharger packages to capture powertrain integration contracts.
Japan
Toyota City and Hiroshima manufacturing basins concentrate keiretsu sourcing for dual-overhead-cam VVT modules. METI fuel efficiency standards push content proliferation in four-cylinder and V6 architectures. Domestic suppliers control electromagnetic actuator production through vertically integrated rare-earth magnet supply chains.
India
MIIT-equivalent fuel consumption regulations create first-fit demand as domestic engine production scales. Local assembly of cam phaser modules avoids import duty exposure for Maruti Suzuki and Hyundai Motor India. Tamil Nadu and Maharashtra engine corridors attract tier-one supplier machining investments.
Automotive Variable Valve Timing Market Competitive Environment
Concentration sits with integrated powertrain specialists possessing captive foundry and precision grinding capabilities. The vendor base separates into three tiers: global system integrators bundling VVT with forced induction hardware, regional component specialists supplying discrete cam phasers, and captive in-house producers at major OEMs. Strategic moves center on M&A to secure machining talent and capacity expansion in electrification-adjacent actuator architectures.
Within the system integrator tier, BorgWarner Inc., Schaeffler AG, and DENSO Corporation exemplify divergent geographic anchoring strategies. BorgWarner represents North American powertrain bundling approaches. Schaeffler occupies a position as a European valve train specialist with proximity to German OEM headquarters. DENSO anchors Asian sourcing channels through electromagnetic actuator production control. These three entities collectively illustrate how regional regulatory calendars and industrial clustering shape competitive positioning without requiring uniform technology strategies.
| Leading Market Players |
|---|
| Eaton Corporation |
| Robert Bosch GmbH |
| DENSO Corporation |
| Mitsubishi Electric Corporation |
| Hitachi Automotive |
| BorgWarner Inc. |
| Aisin Seiki Co. Ltd |
| Valeo |
| Schaeffler AG |
| Others |
Value Chain & Pricing Dynamics
EPA Tier 3 and Euro 7 certification gates simultaneously qualify suppliers and stratify price tiers, with compliance investment separating configured-to-order electromagnetic actuator producers from standard cam phaser catalog vendors. This dual-gating concentrates pricing power among foundry-integrated manufacturers while compressing margins for component specialists lacking captive machining.
Pricing Analysis
Configured-to-order pricing for electromagnetic actuators commands a 15-25% premium over standard electro-hydraulic cam phaser catalogs, with customization depth and certification grade as primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels reflects vertical integration depth and geographic delivery cost. Price erosion runs through the standard tier as Chinese suppliers expand machining capacity. Fleet procurement teams at volume OEMs exhibit highest price sensitivity; German premium OEMs demonstrate lowest sensitivity due to performance specifications.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Yokohama ports to European assembly plants have intensified working capital requirements for just-in-time cam phaser delivery. Ductile iron casting concentrates in China, Germany, and Japan; rare-earth magnet processing draws from Inner Mongolia and Sichuan provinces. Single-source vulnerability in neodymium supply creates exposure to Chinese export quota adjustments. Distribution runs through tier-one supplier hubs co-located with engine assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket solenoid and seal replacement demand expands faster than original equipment hardware, creating a recurring-revenue layer that outpaces unit production growth. Service-attach opportunities in calibration software updates and remanufactured phaser modules warrant dedicated investment.
For Market Incumbents: Compound defensive positioning through captive rare-earth magnet sourcing and precision grinding capacity additions in Tamil Nadu. Electromagnetic actuator specialists threaten electro-hydraulic installed base; backward integration into neodymium procurement secures input cost stability against Chinese quota volatility. For New Entrants and Emerging Players: Aftermarket calibration software for legacy ECU integration represents an underserved layer where incumbents cede ground to independent diagnostic tool providers. India's domestic engine corridors offer the most penetrable geography; partner with Maruti Suzuki authorized service networks for validated installation protocols. For Investors and Strategic Acquirers: Euro 7 particulate standard enforcement reshapes the acquisition landscape toward electromagnetic actuator capabilities and hybrid-compatible response architectures. Five-to-ten year viability hinges on supplier positioning for 48V mild-hybrid content proliferation. Target machining specialists with sub-micron tolerance grinding expertise and existing German OEM qualification. Monitor MIIT enforcement threshold announcements as inflection signal for Chinese demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Rare-Earth Magnet Supply Agreement | Secures dysprosium and neodymium access from Inner Mongolia processors against quota volatility. |
| Precision Machining Capacity Expansion | Adds sub-micron grinding capability in Tamil Nadu to serve Hyundai Motor India and Maruti Suzuki. |
| Electromagnetic Actuator Platform Launch | Targets 48V mild-hybrid architectures specified by German premium OEMs for sub-100ms response. |
| Aftermarket Calibration Software Development | Enables legacy ECU compatibility without full powertrain redesign, extending hardware replacement cycles. |
| Keiretsu Sourcing Partnership | Integrates into Toyota City and Hiroshima manufacturing basins for dual-overhead-cam module supply. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA certification filings, Euro 7 technical documentation, MIIT fuel consumption databases, and IHS Markit vehicle production data. Interviews with tier-one supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership service operations informed demand calibration. Bottom-up unit volume estimates triangulated against top-down powertrain content projections.
Segmentation dimensions modeled include propulsion architecture, actuator technology type, vehicle weight classification, and regional production cluster across the analysis window. CAGRs derived from regression analysis of historical content-per-vehicle trends against regulatory phase-in calendars. Forecast inputs incorporated rare-earth price volatility indices and foundry capacity utilization rates.
Forecasts assume regulatory continuity in EPA Tier 3, Euro 7, and MIIT enforcement regimes; material policy shifts would require re-modeling. Electrification timeline acceleration or extended ICE platform lifecycles represent primary forecast revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Windshield Washer Fluid Market
Automotive Parts
Motorcycle Aluminum Casting Market
Automotive Parts
Automotive Spacer Ring Market
Automotive Parts
Automotive Parts Aluminum Die Casting Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
Electric Power Steering System (EPS) Market
Automotive Parts
Two Wheeler Chain Sprocket Kit Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
Vehicle Transfer Case Market
Automotive Parts
Poland Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Central Lubrication System Market
Automotive Parts
Automotive Air Conditioning Electric Scroll Compressors Market
Automotive Parts
Automotive Electric Fuel Pumps Market