
 Air Suspension Systems Market | 2026-2036
Air Suspension Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Air Suspension Systems Market Analysis
ISO 26262 functional safety qualification is collapsing the supplier base for electronic air suspension modules. Continental AG leverages captive semiconductor sourcing to sustain control over ECU firmware development. ZF Friedrichshafen AG anchors European OEM supply through integrated air compressor and damper manufacturing. ThyssenKrupp AG competes on steel-grade bellows specialization for heavy-truck durability cycles.
Air suspension systems integrate pressurized rubber-and-fabric bellows with height-adjustable shock absorbers to maintain constant chassis clearance under variable loads, typically operating at 5–10 bar supply pressure from engine-driven or electric compressors. Active and semi-active configurations now lead product mix as fleet operators prioritize real-time damping adjustment for cargo protection and fuel efficiency. Electronic control technology commands the fastest expansion trajectory, displacing manual lever systems in medium-duty and heavy-vehicle installations where sensor feedback enables predictive load compensation.
NHTSA FMVSS standards and EU Whole Vehicle Type Approval frameworks govern ride-height stability and emergency handling performance, compelling OEMs to spec electronically governed air management units. EPA Phase 3 greenhouse gas regulations for heavy trucks indirectly accelerate air suspension penetration by rewarding weight-optimized chassis designs that depend on pneumatic leveling. Stakeholders must monitor how pending updates to UN ECE R13 braking compatibility rules reshape electronic control architecture requirements for multi-axle commercial vehicles.
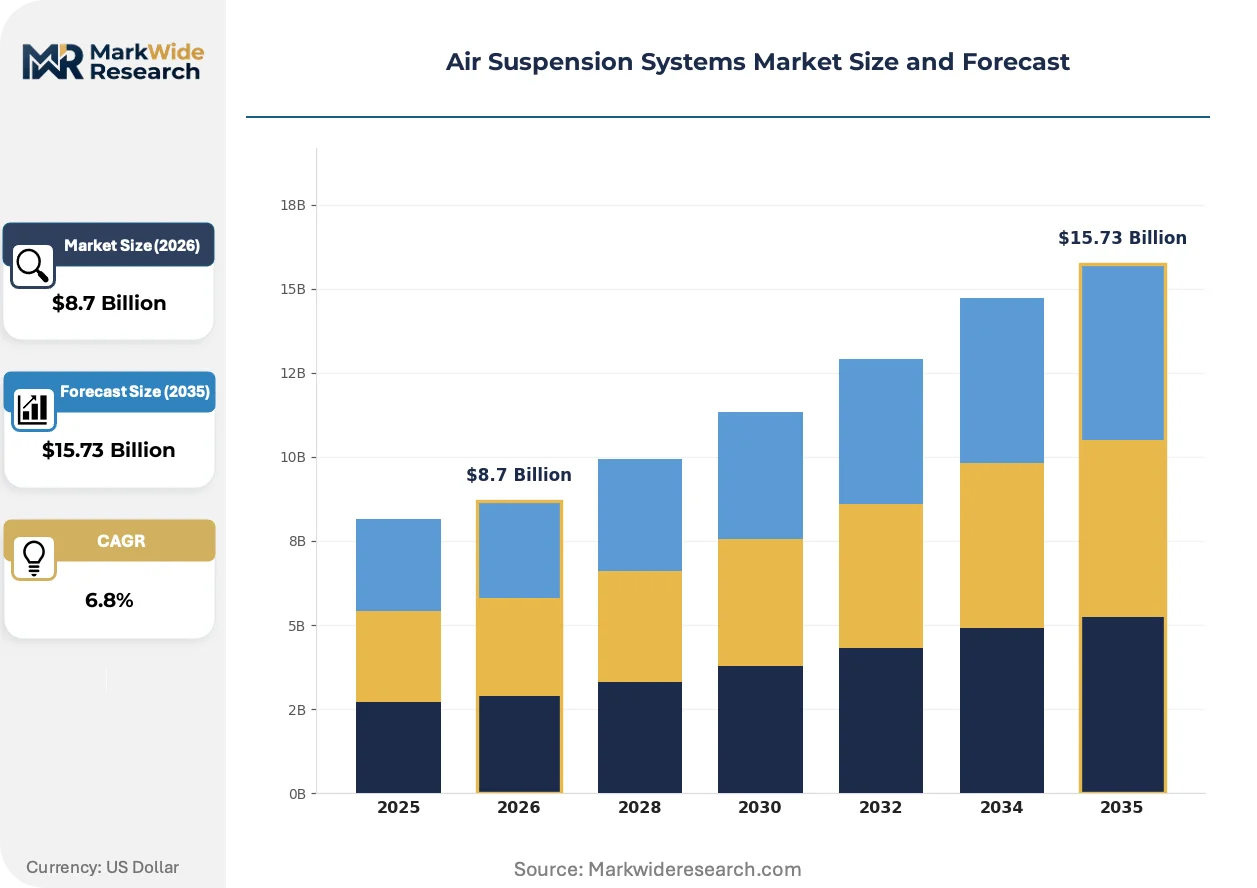
Market Dynamics
ISO 26262 functional safety mandates are compressing the supplier base for electronic air suspension modules, forcing tier-1 integrators to consolidate semiconductor sourcing and firmware development capabilities under unified control architectures.
Growth Catalysts
- FMVSS ride-height mandates:NHTSA regulations governing chassis stability under variable loads compel North American commercial fleets to spec electronically governed air management units on medium and heavy-duty trucks.
- Semi-active damper adoption:Real-time damping adjustment technology protects high-value cargo and reduces fuel consumption, driving fleet operator preference for sensor-integrated configurations.
- German production clustering:Premium automotive OEMs and heavy-duty truck manufacturers anchor regional capacity for advanced semi-active and full-active suspension systems.
Market Restraints
- Specialized steel-grade input costs:Bellows fabrication depends on high-cycle fatigue-resistant alloys subject to commodity volatility and mill capacity constraints.
- Semiconductor supply concentration:ECU production relies on captive or contracted chip sourcing vulnerable to foundry allocation disruptions.
- Pneumatic compressor durability limits:Engine-driven and electric compressor systems face operational lifespan trade-offs between weight optimization and maintenance intervals.
Strategic Opportunities
- EPA Phase 3 tailwind:Greenhouse gas regulations for heavy trucks reward weight-optimized chassis designs that leverage pneumatic leveling systems.
- Multi-axle commercial vehicle expansion:Pending UN ECE R13 braking compatibility updates create specification windows for integrated electronic control architectures.
- Sensor fusion convergence:Integration of predictive load compensation algorithms with fleet telematics platforms enables outcome-based suspension performance contracts.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL qualification cycles for electronic control modules extend product validation schedules and compress launch windows.
- Legacy mechanical system integration:Manual lever and passive damper architectures in existing fleet vehicles create retrofit complexity and training burdens for service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Suspension Systems Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active, Passive, Semi-Active, Full-Active End User: Light Vehicles, Heavy Vehicles, Commercial Trucks, Buses Technology: Electronic Control, Manual Control, Air Compressor, Sensors Application: Agriculture, Transportation, Construction, Industrial |
| Companies Covered | ZF Friedrichshafen AG, Continental AG, ThyssenKrupp AG, Hendrickson International Corporation, SAF Holland, Vibracoustic SE, Hitachi Astemo Ltd., HL Mando Corporation, Firestone Industrial Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Suspension Systems Market Emerging Trajectories
Active and semi-active configurations now dominate product development roadmaps as real-time damping adjustment becomes the baseline expectation across commercial vehicle specifications.
Solenoid valve manifolds for electronic height control is miniaturizing component footprints while maintaining 5–10 bar operating pressure ratings. Commercial truck OEMs in Germany and the United States are specifying these compact modules for cab and chassis installations where packaging space is constrained. This miniaturization is compressing the physical envelope for integrated air management units, enabling mounting locations previously inaccessible to larger pneumatic assemblies.
EU Whole Vehicle Type Approval frameworks governing emergency handling performance are tightening test protocols for ride-height stability under lateral load transfer. OEMs must now demonstrate consistent chassis clearance across full payload variance, compelling specification of closed-loop electronic control rather than open-loop mechanical systems. Heavy-duty tractor-trailer configurations serving cross-border European routes face the most acute compliance pressure.
Fleet procurement departments are consolidating supplier relationships around vertically integrated tier-1s capable of delivering unified compressor, damper, and ECU packages. This consolidation displaces fragmented sourcing of discrete pneumatic components through aftermarket distributors. The shift is most visible among North American for-hire trucking fleets operating more than 500 power units, where total cost of ownership modeling favors single-source warranty and service accountability.
Air Suspension Systems Market Segmentation
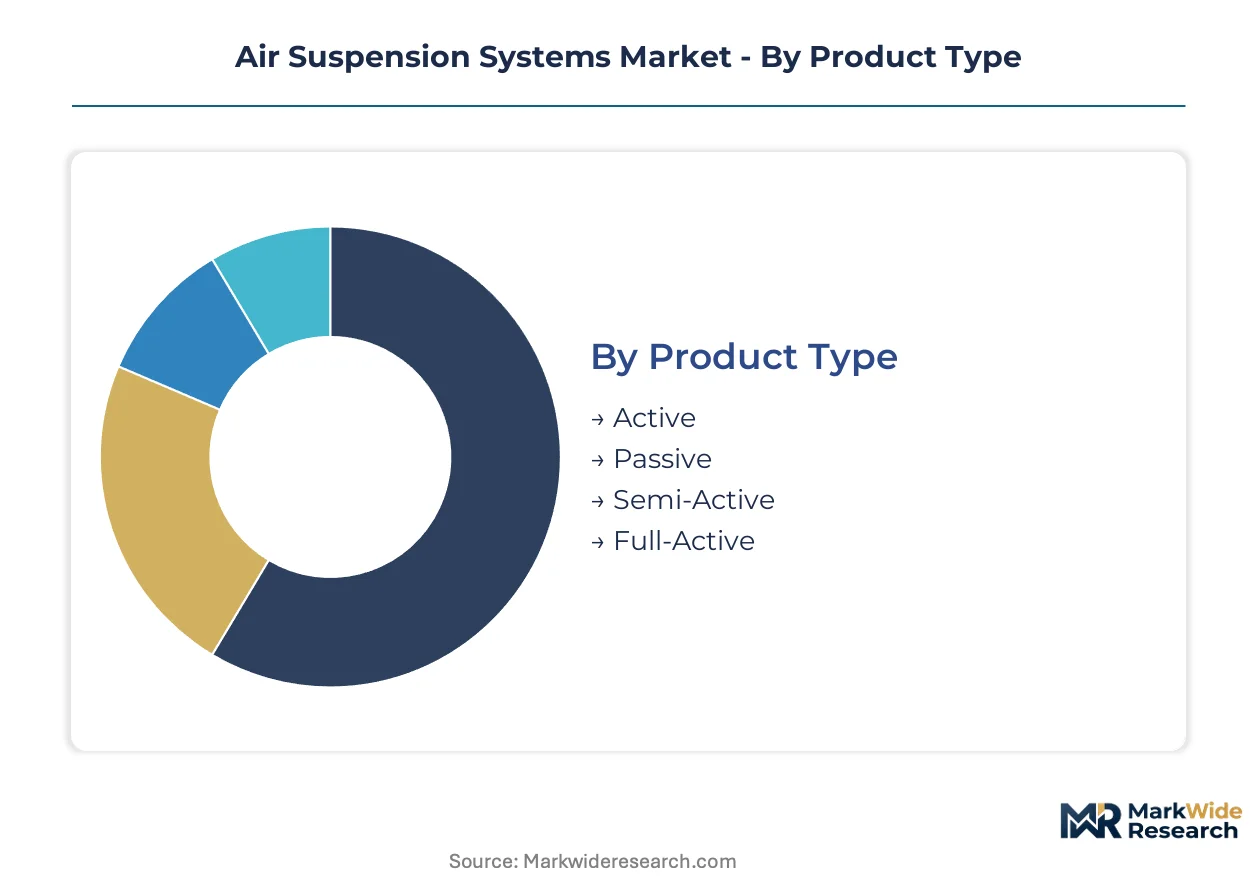
Segmentation in air suspension systems reveals how electronic control architectures displace mechanical alternatives across vehicle classes. Channel dynamics vary sharply between OEM specification and aftermarket retrofit, with technology tier determining margin structure and supplier consolidation patterns.
Product Type:
Channel flow splits between fleet procurement of active systems through tier-1 integrators and aftermarket distribution of passive units for legacy vehicle maintenance.
- Active:Real-time damping adjustment via solenoid valve manifolds enables predictive load compensation. Demand concentrates in German premium automotive OEMs and North American heavy-duty tractor-trailer fleets under FMVSS ride-height mandates.
- Full-Active:Independent wheel control with continuous variable damping represents the performance ceiling. German production clusters anchor supply for luxury passenger vehicles and cross-border European commercial routes facing EU Whole Vehicle Type Approval protocols.
- Passive:Fixed-rate pneumatic bellows without electronic feedback serve cost-sensitive retrofit applications.
- Semi-Active:Discrete damping modes switched by vehicle speed or load sensors bridge price-performance gaps in medium-duty trucks.
Passive systems dominate installed base. Full-Active is where expansion concentrates.
End User:
Cost tier stratification separates premium electronic configurations in heavy vehicles from economy passive systems in light vehicle aftermarket.
- Heavy Vehicles:Multi-axle tractor-trailers require closed-loop height control for cargo protection and fuel efficiency. North American for-hire fleets above 500 power units specify integrated compressor-damper-ECU packages from single-source tier-1s.
- Commercial Trucks:Medium and heavy-duty cab-chassis installations face packaging constraints driving miniaturization of electronic height control modules. EPA Phase 3 greenhouse gas regulations reward weight-optimized pneumatic leveling designs.
- Light Vehicles:Passenger car and light truck applications favor semi-active configurations for ride comfort differentiation.
- Buses:Transit and coach operators prioritize durability cycles and kneeling capability for accessibility compliance.
Commercial Trucks anchor current revenue. Heavy Vehicles is climbing the fastest as fleet operators consolidate supplier relationships.
Technology:
Application context determines whether sensor-integrated electronic control or mechanical manual systems prevail in specification decisions.
- Electronic Control:ECU firmware with ISO 26262 ASIL qualification enables predictive algorithms and fleet telematics integration. Semiconductor supply concentration and foundry allocation disruptions constrain tier-1 production schedules.
- Sensors:Height, pressure, and accelerometer arrays feed closed-loop algorithms for real-time chassis clearance maintenance. Miniaturization trends compress physical envelopes for mounting in space-constrained cab installations.
- Manual Control:Lever-actuated pneumatic valves persist in legacy fleet vehicles and developing market retrofits.
- Air Compressor:Engine-driven and electric compressor systems face operational lifespan trade-offs between weight optimization and maintenance intervals.
Manual Control retains legacy fleet share. Electronic Control is gaining share fastest as NHTSA FMVSS mandates displace open-loop architectures.
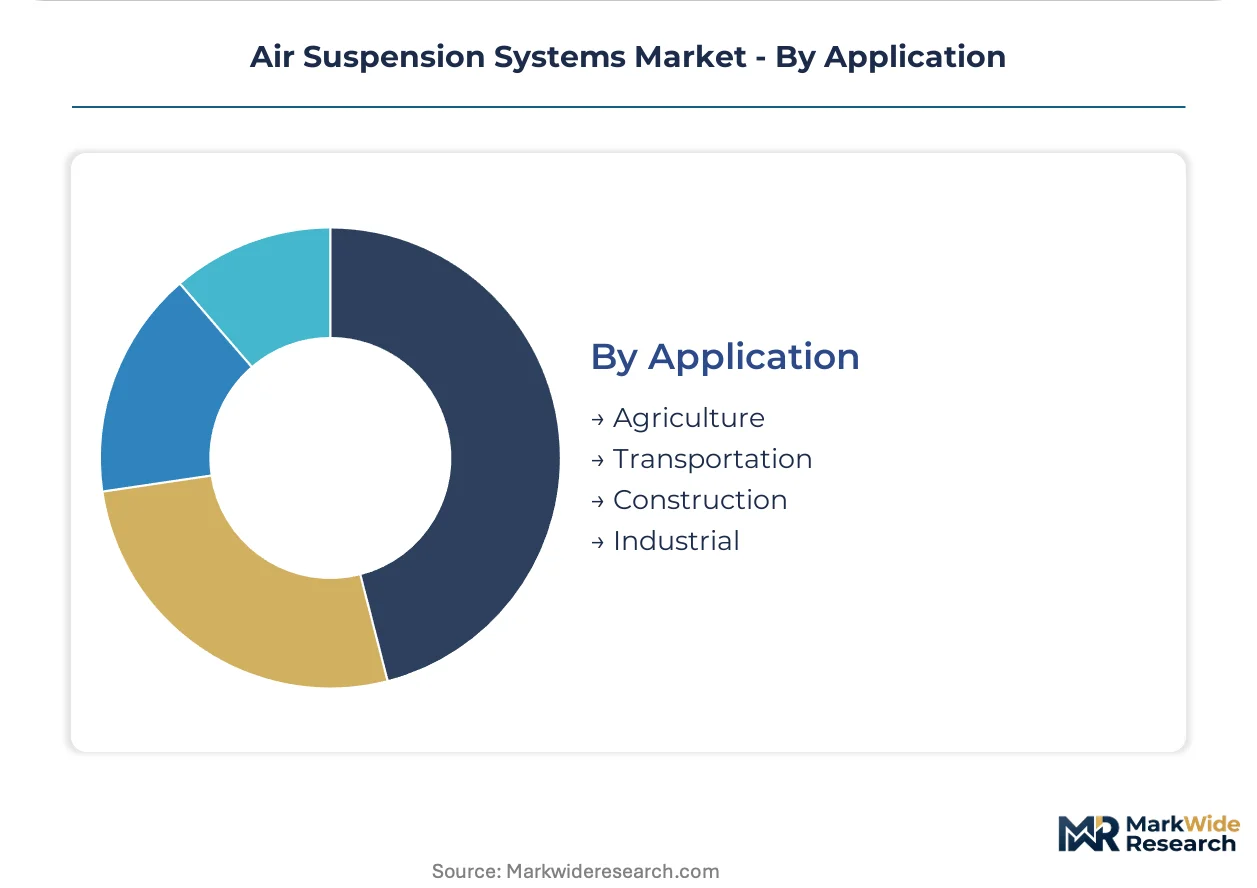
Application:
Volume concentration in transportation fleets contrasts with specialized industrial requirements for corrosion resistance and extreme duty cycles.
- Transportation:For-hire trucking and logistics fleets drive standardization around electronically governed air management units. Cross-border European routes face acute compliance pressure under tightening EU Whole Vehicle Type Approval test protocols.
- Construction:Off-highway equipment demands high-cycle fatigue-resistant steel-grade bellows for uneven terrain durability. Specialized alloys subject to commodity volatility constrain supplier margin stability.
- Agriculture:Tractor and implement suspensions prioritize cost efficiency and field-serviceability over electronic sophistication.
- Industrial:Material handling and specialty vehicle applications require customized pneumatic configurations for load variance extremes.
Transportation commands the largest specification volume. Construction shows the steepest expansion trajectory as infrastructure investment drives heavy equipment replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Phase 3 greenhouse gas regulations and NHTSA FMVSS ride-height mandates are accelerating specification of electronically governed air management units across major commercial vehicle markets. Fleet operators in Germany, the United States, China, Japan, and India face distinct compliance pressures and supply chain configurations that reshape regional competitive dynamics.
United States
North American for-hire trucking fleets above 500 power units drive consolidation around single-source tier-1 suppliers. NHTSA FMVSS standards mandate electronically controlled ride-height stability for medium and heavy-duty commercial vehicles. Detroit and Indiana manufacturing corridors anchor integrated compressor-damper-ECU production for domestic OEM specification.
Germany
Premium automotive OEMs and heavy-duty truck manufacturers anchor European capacity for semi-active and full-active suspension systems. KBA type approval protocols under EU Whole Vehicle Type Approval frameworks enforce closed-loop electronic control for cross-border commercial routes. Stuttgart and Munich production clusters specialize in steel-grade bellows fabrication and ECU firmware development.
China
Domestic commercial vehicle manufacturers expand local sourcing of electronic height control modules to reduce import dependency. MIIT fuel consumption standards for heavy trucks indirectly favor pneumatic leveling designs that enable weight-optimized chassis configurations. Yangtze River Delta manufacturing bases concentrate solenoid valve manifold production for regional OEM supply.
Japan
Precision component suppliers advance miniaturization of electronic height control modules for space-constrained cab installations. METI energy efficiency regulations for commercial vehicles create specification pressure for real-time damping adjustment technology. Nagoya industrial corridor maintains specialized capacity for high-cycle fatigue-resistant alloy bellows.
India
Domestic heavy commercial vehicle producers adopt semi-active configurations to differentiate export offerings for Middle East and African markets. BIS automotive safety standards are converging toward electronic stability requirements that favor sensor-integrated architectures. Tamil Nadu and Maharashtra manufacturing zones attract tier-1 investments for localized air compressor assembly.
Air Suspension Systems Market Vendor Landscape
Listed leaders compete with private specialists across functional safety certification and semiconductor sourcing capabilities. The supplier base compresses as ISO 26262 ASIL qualification requirements force consolidation of firmware development and captive chip procurement under unified control architectures. Three archetypes dominate: vertically integrated tier-1s with in-house semiconductor relationships, steel-grade bellows specialists leveraging metallurgical expertise, and regional fabricators serving cost-sensitive retrofit demand. Competitive moves center on backward integration into ECU production and strategic partnerships for foundry capacity allocation.
Within the integrated tier-1 tier, ZF Friedrichshafen AG and Continental AG exemplify European-origin market anchors that occupy positions spanning compressor, damper, and electronic control manufacturing. ThyssenKrupp AG represents the steel-grade specialization archetype, with its corporate structure indicating industrial conglomerate positioning in high-cycle fatigue component supply. These three entities collectively illustrate how functional safety mandates are reshaping competitive positioning toward unified control architecture dominance.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Continental AG |
| ThyssenKrupp AG |
| Hendrickson International Corporation |
| SAF Holland |
| Vibracoustic SE |
| Hitachi Astemo Ltd. |
| HL Mando Corporation |
| Firestone Industrial Products Company |
| Others |
Supply Flow & Price Mechanics
ISO 26262 ASIL functional safety qualification gates both supplier eligibility and price stratification simultaneously, compressing the vendor base toward tier-1 integrators while opening premium pricing bands for certified electronic control architectures.
Pricing Analysis
Certification level creates the primary spread between ISO 26262 ASIL-qualified electronic modules and uncertified mechanical alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects firmware sophistication, semiconductor content, and warranty bundling. Cost compression in economy passive systems is intensifying because fleet operators consolidate procurement around single-source tier-1s. Aftermarket retrofit channels show highest price sensitivity; OEM specification through integrated compressor-damper-ECU packages commands lowest.
Supply Chain Analysis
Foundry capacity allocation for automotive-grade semiconductors concentrates in Taiwan, South Korea, and Germany, tethering ECU production to contracted chip sourcing vulnerable to allocation disruptions. High-cycle fatigue-resistant steel-grade alloys for bellows fabrication draw from German and Japanese mill capacity. Single-source vulnerability runs through captive semiconductor relationships at tier-1 integrators. Distribution runs through OEM direct specification for active systems and fragmented aftermarket distributors for legacy mechanical components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation above 500 power units shifts buyer power toward volume-discount extraction and single-source accountability demands, fragmenting pricing power among undifferentiated component suppliers.
For Market Incumbents: Compound firmware development capabilities with captive semiconductor sourcing to defend against emerging Asian ECU specialists. Deepen backward integration into solenoid valve manifold production to capture miniaturization-driven packaging premiums. Prioritize ISO 26262 ASIL-D qualification cycles as a barrier against mid-tier competitors lacking validation infrastructure. For New Entrants and Emerging Players: Certification fast-track partnerships with German KBA-notified bodies enable accelerated EU Whole Vehicle Type Approval compliance for cross-border commercial route specifications. Target medium-duty truck segments in India and Southeast Asia where BIS standards are converging toward electronic stability requirements but local tier-1 capacity remains thin. Lead with sensor-integrated semi-active configurations priced between passive retrofits and full-active premium systems. For Investors and Strategic Acquirers: EPA Phase 3 and NHTSA FMVSS regulatory convergence reshapes the acquisition landscape toward vertically integrated tier-1s with unified compressor-damper-ECU control architectures. Long-term viability favors targets with in-house firmware development and foundry allocation contracts rather than assembly-only operations. Watch UN ECE R13 braking compatibility updates as the signal for multi-axle commercial vehicle specification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Captive chip procurement insulates Continental AG and ZF Friedrichshafen AG from foundry allocation disruptions. |
| ISO 26262 ASIL-D Certification Investment | Functional safety qualification collapses supplier base and enables premium pricing for electronic control modules. |
| Regional Manufacturing Footprint Expansion | Tamil Nadu and Maharashtra assembly investments localize air compressor production for Indian domestic heavy commercial vehicle demand. |
| Sensor Fusion Algorithm Development | Predictive load compensation integration with fleet telematics platforms enables outcome-based performance contracts. |
| Steel-Grade Bellows Specialization | ThyssenKrupp AG's metallurgical expertise in high-cycle fatigue alloys defends position in heavy-truck durability applications. |
Methodological Framework
Cross-validation between OEM procurement director interviews and tier-1 supplier production data anchors the qualitative findings on specification trends. Primary fieldwork engaged fleet maintenance directors at North American for-hire trucking operations, German heavy-duty truck platform engineers, and aftermarket distribution channel heads. Secondary sources incorporated NHTSA FMVSS regulatory filings, EU Whole Vehicle Type Approval test protocols, EPA Phase 3 technical documentation, and vehicle production databases. Bottom-up triangulation across compressor, damper, and ECU component volumes reconciled with top-down OEM specification rates.
Sensitivity analysis across semiconductor supply scenarios and steel alloy price volatility bands stress-tested volume and value outputs. Segmentation dimensions modeled include suspension architecture tier, vehicle class, technology control type, and regional regulatory cluster. CAGRs derived from logistic curve fitting to OEM specification penetration rates, weighted by fleet replacement cycle timing. Industry-specific inputs incorporated EPA Phase 3 weight-optimization incentives and UN ECE R13 braking compatibility timelines.
Underlying assumptions cover continued NHTSA and EPA regulatory enforcement, with deviation risk concentrated in semiconductor foundry allocation disruptions and steel-grade alloy mill capacity constraints. Practitioners should keep alternative scenarios live as EU Whole Vehicle Type Approval test protocol updates and BIS automotive safety standard convergence timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
AC Electromagnetic Brakes Market
Automotive Parts
Automotive All Wheel Drive Market
Automotive Parts
Air Filter Cartridges Market
Automotive Parts
Poland Passenger Vehicles Lubricants Market
Automotive Parts
Global Windshield Wiper Blades Market
Automotive Parts
Electric Brake Booster Market
Automotive Parts
Indonesia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Weatherstrips Market
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
Spare Wheel Carrier Market
Automotive Parts
Electric Parking Brake Actuator Components Market
Automotive Parts
Two Wheeler Chain Sprocket Kit Market
Automotive Parts
Japan Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Bellows Market