
 Argentina Commercial Vehicles Lubricants Market | 2026-2036
Argentina Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Commercial Vehicles Lubricants Market Outlook
A widening capital-intensity gap between integrated refiners and regional blenders is rotating competitive advantage toward upstream-integrated suppliers. Royal Dutch Shell PLC leverages its global base oil supply network to secure feedstock cost advantages in Argentina. YPF sustains dominant channel control through its nationwide retail and direct-to-fleet infrastructure. Fercol Lubricantes competes by specializing in customized formulations for agricultural and construction equipment segments where service flexibility outweighs scale economies.
Commercial vehicles lubricants encompass formulated oils and greases engineered with viscosity grades, additive packages, and base oil stocks designed to reduce friction, dissipate heat, and prevent wear in diesel engines, transmissions, and hydraulic systems operating under severe load cycles. Engine oil formulations dominate volume consumption due to shorter drain intervals in heavy-duty diesel applications across Argentine trucking and bus fleets. Synthetic formulations command expanding share among fleet operators prioritizing extended oil-change intervals and fuel economy gains, while mineral oils retain price-sensitive construction and agriculture segments. Wholesale distribution channels anchor volume throughput to large fleet accounts, though direct sales relationships are deepening with logistics providers seeking technical service bundling.
Argentina's Instituto Argentino de Normalización y Certificación (IRAM) sets lubricant performance benchmarks aligned with API and ACEA specifications, while the Secretaría de Energía monitors fuel economy claims tied to lubricant marketing. The country's national environmental regulator enforces waste oil handling protocols that elevate compliance costs for smaller blenders without integrated collection infrastructure. Stakeholders must monitor pending alignment between domestic standards and evolving Euro VI-equivalent emissions regulations, as tighter particulate limits will redirect formulation investments toward low-SAPS and high-TBN diesel engine oils.
Market Dynamics
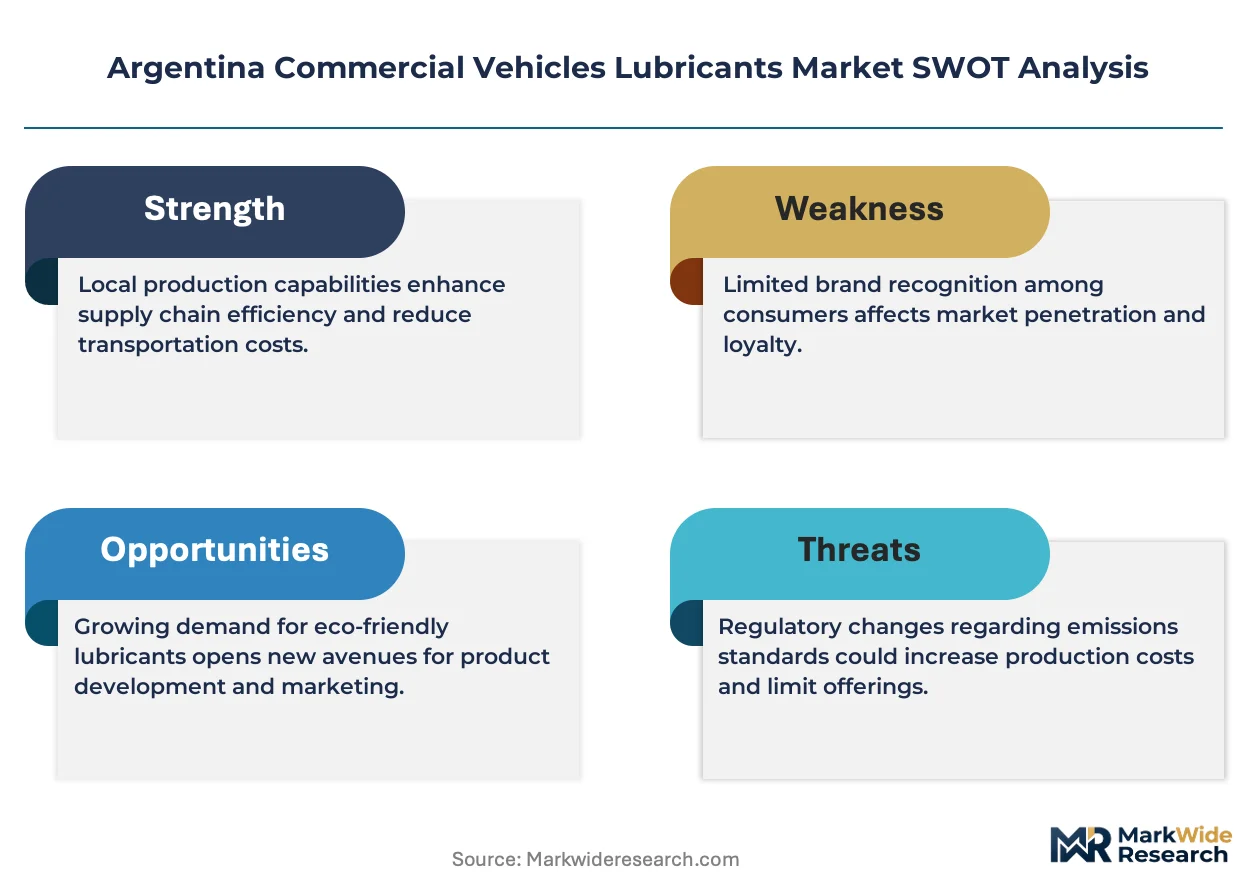
Argentina's IRAM standards are compressing formulation flexibility while elevating compliance costs, forcing blenders to choose between capital-intensive upgrading or channel exit as Euro VI-equivalent emissions rules approach.
Growth Catalysts
- Fleet Utilization Surge:Long-haul trucking routes across the Rosario-Santa Fe corridor are extending vehicle operating hours, shortening drain intervals and expanding lubricant throughput to logistics providers.
- IRAM Quality Mandates:The Instituto Argentino de Normalización y Certificación's alignment with API and ACEA specifications is filtering substandard mineral formulations from formal channels, concentrating demand among certified suppliers.
- Synthetic Formulation Adoption:Heavy-duty diesel engine oils with extended drain capabilities are capturing fleet operator preference as fuel economy optimization becomes a procurement priority.
Market Restraints
- Base Oil Import Dependency:Argentina's limited domestic Group II/III base oil production creates feedstock cost volatility tied to international refining margins and currency fluctuation.
- Waste Oil Handling Compliance:The national environmental regulator's collection infrastructure mandates impose fixed-cost burdens on regional blenders lacking integrated reverse logistics networks.
- Price-Sensitive Segment Retention:Mineral oil formulations retain lock-in among agricultural equipment operators in interior provinces where total cost of ownership calculations favor lower unit prices over extended service intervals.
Strategic Opportunities
- Direct Fleet Contracting:Logistics providers in Buenos Aires province are unbundling technical service from product supply, creating white space for formulation specialists to embed diagnostic capabilities.
- Low-SAPS Prepositioning:Pending Euro VI-equivalent particulate limits will redirect R&D investment toward low-sulfated-ash formulations before mandatory adoption deadlines.
- Construction Equipment Specialization:Hydraulic system lubricants for infrastructure projects in Córdoba and Mendoza provinces remain underserved by standardized product portfolios.
Industry Challenges
- Additive Package Sourcing:Formulation houses face lead-time compression for dispersant and detergent chemistries as global additive suppliers prioritize larger contract volumes.
- Certification Timeline Compression:IRAM's evolving test protocols require re-validation of existing product registrations, straining technical documentation resources at mid-scale blenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Commercial Vehicles Lubricants Market |
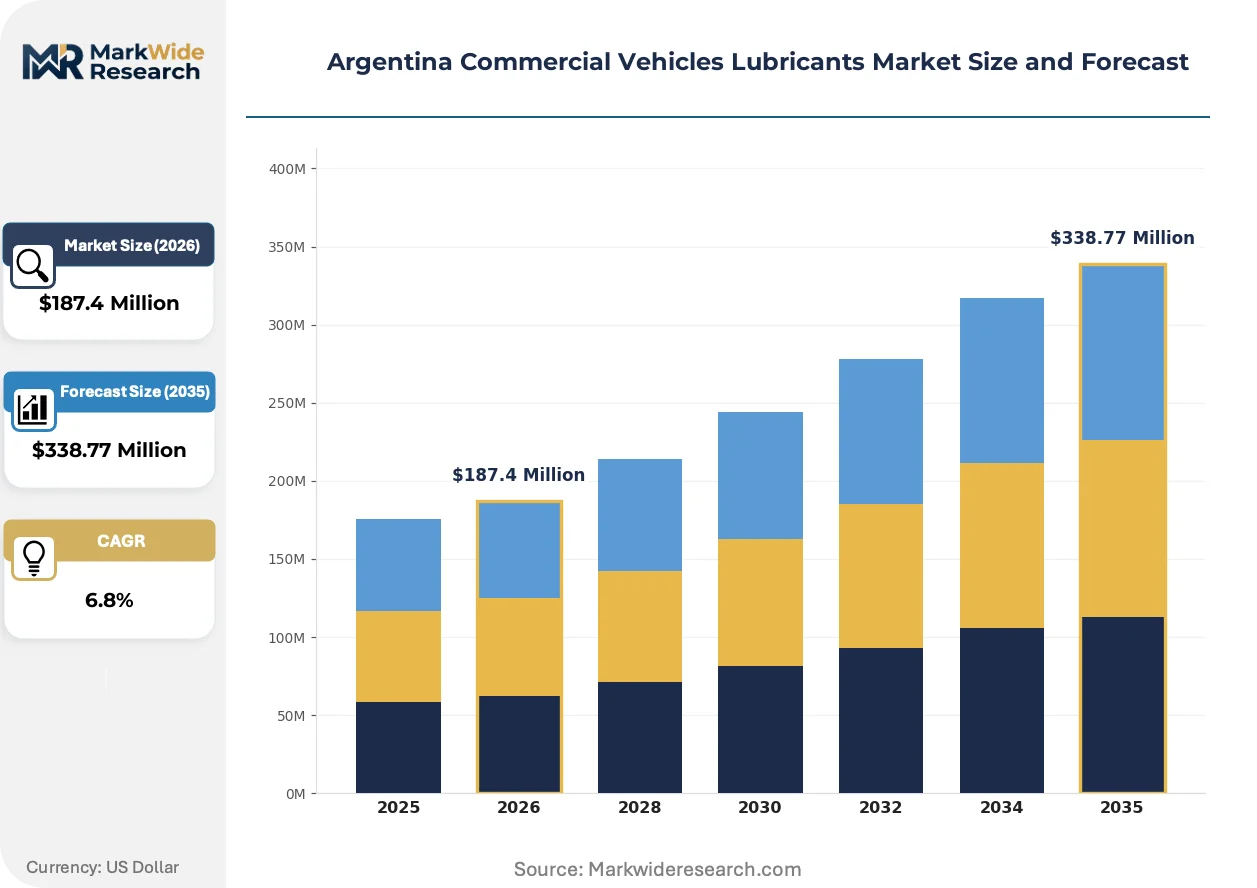
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Grease, Hydraulic Oil Formulation: Synthetic, Mineral, Semi-Synthetic, Bio-Based End User: Fleet Operators, Logistics Providers, Construction Companies, Agriculture Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | BP PLC (Castrol), ExxonMobil Corporation, Royal Dutch Shell PLC, TotalEnergies, YPF, Chevron Corporation, Fercol Lubricantes, Petrobras, Gulf Oil International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Commercial Vehicles Lubricants Market Strategic Shifts
Formulation chemistry and procurement architecture are diverging simultaneously, with synthetic base stocks gaining technical preference while distribution channels fragment between consolidated fleet accounts and specialized service bundling.
Synthetic Group III and PAO base stocks are bifurcating the product mix between premium extended-drain formulations and conventional mineral oils. Fleet operators operating Mercedes-Benz and Scania powertrains across the Pampas grain corridor are specifying synthetic 5W-30 and 10W-40 grades to maximize uptime. This technology split is compressing mid-tier semi-synthetic positioning and forcing blenders to commit fully to either premium or economy formulation strategies.
Argentina's Secretaría de Energía is tightening fuel economy claim verification for lubricant marketing, requiring third-party test documentation for friction-reduction assertions. The industrial consequence is elevated R&D documentation burden and longer product launch cycles. Heavy-duty diesel engine oil suppliers serving Buenos Aires-based logistics fleets are pre-emptively adopting SAE J1321 fuel consumption test protocols to secure competitive positioning.
Channel disintermediation is restructuring how lubricants reach fleet maintenance bays. Large transport operators in the Santa Fe-Rosario axis are consolidating procurement through direct technical service agreements, bypassing traditional wholesale distributors. Agricultural cooperatives in Entre Ríos province retain counter-based purchasing, preserving the two-channel structure. This divergence is most visible in volume contracting patterns, where logistics providers negotiate integrated fluid management programs while construction segments remain transaction-oriented.
Argentina Commercial Vehicles Lubricants Market Segmentation
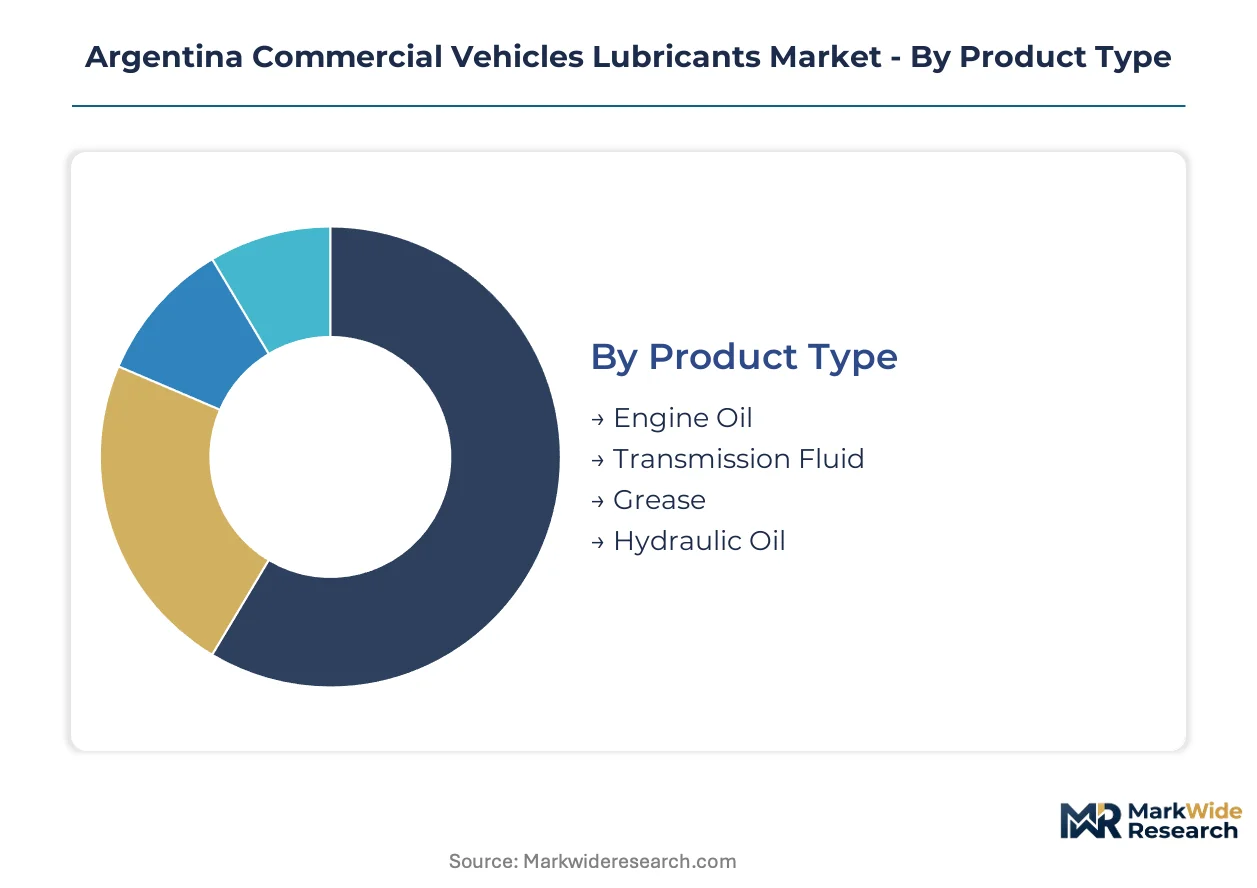
Segmentation in Argentina's commercial vehicles lubricants market reveals how formulation chemistry, procurement channels, and end-use intensity create distinct competitive battlegrounds. Each dimension carries different margin profiles and regulatory exposure, shaping where blenders concentrate technical investment versus price competition.
Product Type:
Substitution pressure from extended-drain synthetics and alternative fluid technologies varies sharply across product categories, with some segments facing imminent formulation displacement while others retain defensive moats.
- Engine Oil:Formulated with detergent-dispersant additive packages and viscosity index improvers to manage soot loading in heavy-duty diesel cycles. Demand concentrates among Buenos Aires-based logistics fleets operating Mercedes-Benz and Scania powertrains, where shorter drain intervals in high-utilization routes expand throughput volume. Fleet operators here prioritize TBN retention and oxidation stability over unit cost.
- Transmission Fluid:ATF and manual transmission formulations engineered with friction modifiers and anti-wear chemistries for synchronized gearboxes. Demand clusters in the Rosario-Santa Fe corridor's long-haul trucking operations, where automated manual transmissions from ZF and Eaton are penetrating fleet specifications and requiring OEM-approved lubricant compliance.
- Grease:Thickener-stabilized lubricants for chassis, wheel bearings, and fifth-wheel applications. Mining and construction equipment in Córdoba province drives consumption.
- Hydraulic Oil:Anti-wear and rust-inhibited formulations for loader and excavator hydraulic systems. Infrastructure projects in Mendoza generate specialized viscosity-grade demand.
Engine oil anchors the volume base while transmission fluid gains share at the steepest rate as automated drivetrain penetration accelerates among Argentine fleet operators.
Formulation:
Cost tier stratification separates premium synthetic positioning from mineral economy plays, with mid-market semi-synthetics facing compression from both directions.
- Synthetic:Group III and PAO base stocks delivering extended drain intervals and fuel economy verification under SAE J1321 protocols. Fleet operators across the Pampas grain corridor specify 5W-30 and 10W-40 grades to maximize uptime and reduce maintenance bay congestion.
- Mineral:Solvent-refined Group I base oils retaining lock-in among agricultural cooperatives in Entre Ríos province, where total cost of ownership calculations favor lower unit prices over service interval extension.
- Semi-Synthetic:Blended formulations occupying narrowing middle positioning as procurement bifurcates toward premium synthetics or economy minerals.
- Bio-Based:Ester and vegetable-derived stocks targeting environmental compliance niches in sensitive watershed operations.
Mineral formulations retain the largest installed base while synthetic grades expand most quickly as IRAM quality mandates filter substandard products from formal channels.
End User:
Customer type determines technical service bundling requirements and contract structure, with volume concentration diverging sharply between consolidated fleet accounts and fragmented equipment operators.
- Fleet Operators:Large transport companies managing 50-plus vehicle fleets with centralized maintenance programs. Buenos Aires province accounts concentrate procurement through direct technical service agreements, bypassing wholesale distributors and demanding integrated fluid management programs.
- Logistics Providers:Third-party freight operators with variable route intensity across the Santa Fe-Rosario axis. These stakeholders prioritize fuel economy claims verified by Argentina's Secretaría de Energía.
- Construction Companies:Project-based hydraulic system demand in Córdoba and Mendoza provinces, where equipment utilization cycles differ from over-the-road trucking.
- Agriculture:Seasonal equipment operators in interior provinces with counter-based purchasing patterns and price-sensitive procurement timing tied to harvest cycles.
Fleet operators command the highest per-account volumes while logistics providers are shifting procurement fastest toward direct contracting models.
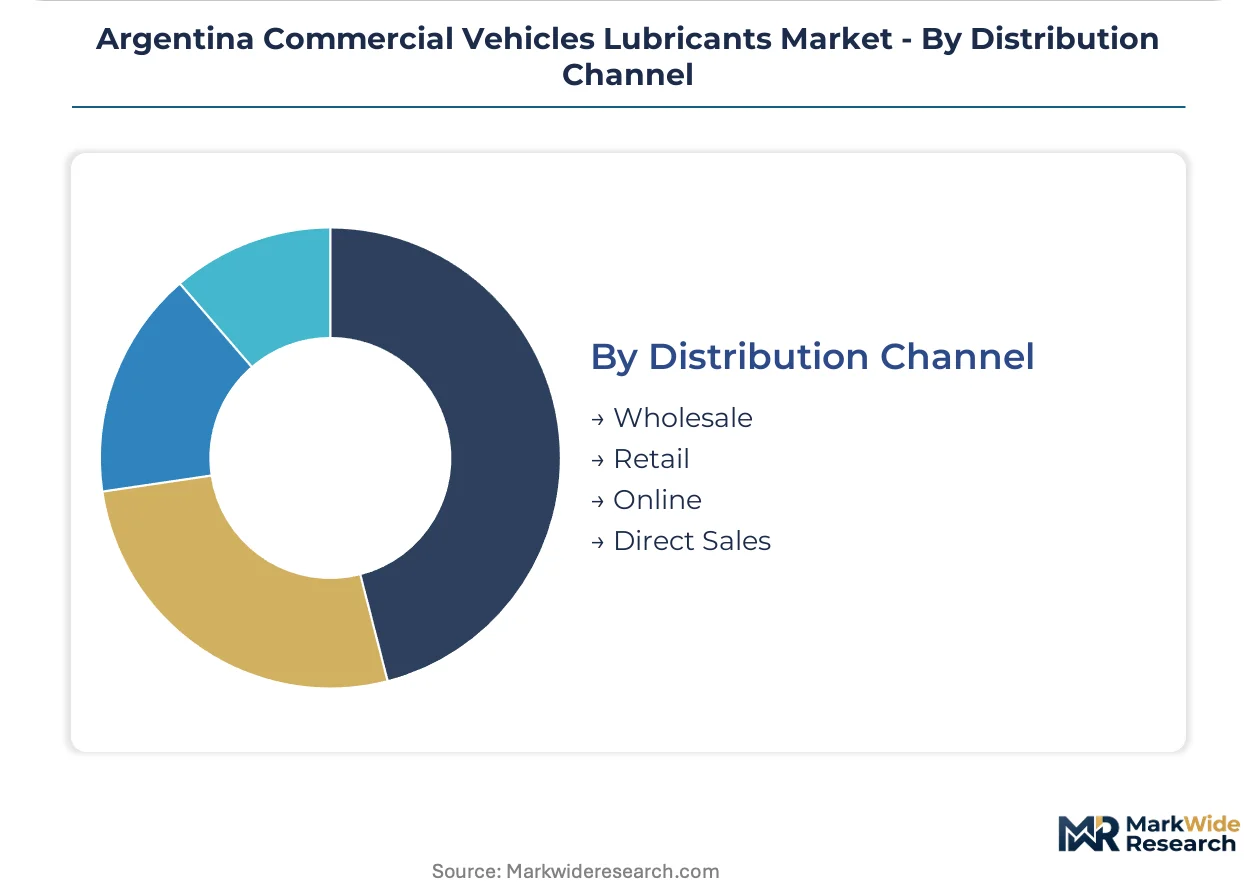
Distribution Channel:
Channel margin structure and customer touchpoint intensity separate high-volume wholesale throughput from relationship-based direct sales.
- Wholesale:Volume distribution to service stations and independent workshops serving fragmented agricultural and construction segments. The channel retains dominance in interior provinces where fleet density remains thin.
- Retail:Counter sales through lubricant specialty shops and agricultural supply cooperatives. Entre Ríos province maintains this pattern for seasonal equipment servicing.
- Online:Emerging procurement route for standardized product specifications with documented IRAM certification, gaining traction among smaller fleet operators seeking price transparency.
- Direct Sales:Technical service-integrated contracts with large fleet accounts in Buenos Aires province, where diagnostic capabilities and fluid analysis bundling create switching costs.
Wholesale channels handle the greatest product volume while direct sales climb the fastest as logistics providers consolidate procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Buenos Aires province while interior provinces absorb cost volatility through mineral formulation lock-in. This asymmetry shapes procurement architecture and distributor margin structures across Argentine sub-markets.
Buenos Aires Province
Fleet density exceeds all other provinces, with logistics operators managing 50-plus vehicle fleets through centralized maintenance programs. IRAM quality mandates filter substandard products from formal channels, elevating certified supplier concentration. The Greater Buenos Aires corridor anchors synthetic formulation demand as Mercedes-Benz and Scania powertrains dominate fleet specifications.
Rosario-Santa Fe Corridor
Long-haul trucking routes extend vehicle operating hours, shortening drain intervals and expanding lubricant throughput. The Secretaría de Energía monitors fuel economy claims tied to lubricant marketing, requiring third-party test documentation. Automated manual transmission penetration from ZF and Eaton accelerates transmission fluid specification complexity among corridor operators.
Córdoba Province
Mining and construction equipment drives grease consumption for chassis, wheel bearings, and fifth-wheel applications. The national environmental regulator enforces waste oil handling protocols that elevate compliance costs for regional blenders. Infrastructure projects in the provincial capital generate specialized hydraulic system demand underserved by standardized portfolios.
Mendoza Province
Loader and excavator deployment for infrastructure development creates viscosity-grade specialization requirements. Agricultural cooperatives retain counter-based purchasing patterns with price-sensitive procurement timing tied to harvest cycles. Provincial distributors maintain wholesale dominance where fleet density remains thin relative to coastal corridors.
Entre Ríos Province
Seasonal equipment operators favor mineral oil formulations where total cost of ownership calculations prioritize lower unit prices over extended service intervals. IRAM standards compress formulation flexibility while elevating compliance costs for smaller blenders. Agricultural supply cooperatives preserve transaction-oriented channel structures distinct from direct fleet contracting models.
Argentina Commercial Vehicles Lubricants Market Competitive Environment
Concentration sits with upstream-integrated refiners commanding feedstock cost advantages and nationwide distribution infrastructure. The vendor base separates into three strategic tiers: global majors with captive base oil supply, national champions controlling retail and direct-to-fleet channels, and regional specialists occupying agricultural and construction equipment niches. Dominant competitive moves include backward integration into additive package sourcing and technical service bundling to create switching costs among large fleet accounts.
Within the integrated refiner tier, Royal Dutch Shell PLC and YPF exemplify divergent strategic positioning. Shell leverages global base oil supply networks to secure feedstock advantages in import-dependent markets, while YPF sustains dominant channel control through captive retail infrastructure and direct fleet relationships. Fercol Lubricantes occupies the specialist archetype, competing through customized formulation flexibility where service intensity outweighs scale economies in agricultural and construction segments.
| Leading Market Players |
|---|
| BP PLC (Castrol) |
| ExxonMobil Corporation |
| Royal Dutch Shell PLC |
| TotalEnergies |
| YPF |
| Chevron Corporation |
| Fercol Lubricantes |
| Petrobras |
| Gulf Oil International |
| Others |
Value Chain & Pricing Dynamics
IRAM certification tiers gate both supplier qualification and price differentiation simultaneously, compressing uncertified blenders into commodity segments while elevating formulation premiums for API-aligned products. Fleet procurement teams in Buenos Aires province negotiate volume contracts that embed technical service costs, fragmenting pricing architecture across direct and wholesale channels.
Pricing Analysis
Configured-to-order pricing for customized additive packages commands substantial premiums over standard catalog formulations, with logistics providers paying differential rates for SAE J1321 fuel economy verification. Three-tier pricing structure across premium synthetic, certified mineral, and unbranded economy levels segments buyer segments by total cost of ownership sophistication. Cost compression in the economy tier is intensifying because agricultural cooperatives prioritize unit price over drain interval extension. Construction equipment operators in Córdoba province exhibit highest price sensitivity, while integrated fleet operators in Greater Buenos Aires absorb premium positioning for uptime guarantees.
Supply Chain Analysis
Strait of Magellan transit and Atlantic port congestion at Buenos Aires and Rosario create chokepoints for Group II/III base oil imports from the United States, Brazil, and Singapore. Formulation houses draw from global additive suppliers for detergent-dispersant chemistries, viscosity index improvers, and friction modifiers, with lead-time volatility concentrated in zinc dialkyldithiophosphate sourcing. Single-source vulnerability runs through the limited domestic base oil refining footprint, exposing blenders to currency-driven cost swings. Distribution runs through YPF's captive retail network for interior provinces, while direct technical service agreements dominate coastal fleet corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemistry expertise sits in short supply relative to procurement sophistication, creating asymmetric returns for blenders that bridge technical service capabilities with certified product supply. The capability gap between integrated refiners and regional operators is widening fastest in low-SAPS prepositioning and waste oil reverse logistics.
For Market Incumbents: Fortify backward integration into additive package sourcing to compress lead times as global suppliers prioritize larger contract volumes. Deepen direct fleet relationships in Buenos Aires province through embedded diagnostic capabilities and fluid analysis bundling that creates switching costs against emerging technical service competitors. For New Entrants and Emerging Players: IRAM certification fast-track for Euro VI-equivalent low-SAPS formulations opens white space before mandatory adoption deadlines. Target hydraulic system specialization for infrastructure projects in Mendoza and Córdoba provinces, where standardized portfolios underserve viscosity-grade requirements. Pursue agricultural cooperative relationships in Entre Ríos through counter-based technical support that outmaneuvers scale-dependent national distributors. For Investors and Strategic Acquirers: Pending Euro VI-equivalent emissions alignment reshapes the acquisition landscape toward blenders with pre-positioned low-SAPS R&D pipelines and integrated waste oil collection infrastructure. Long-term viability centers on upstream-integrated or specialist-formulation archetypes with defensible channel control. Monitor IRAM test protocol evolution as the signal indicating which mid-scale blenders face forced exit versus upgrade investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Low-SAPS Formulation Prepositioning | Anticipates Euro VI-equivalent mandates and redirects R&D investment ahead of regulatory deadlines. |
| Direct Fleet Technical Service Integration | Creates switching costs among Buenos Aires logistics providers through diagnostic bundling. |
| Waste Oil Reverse Logistics Buildout | Elevates compliance cost barriers for regional blenders lacking integrated collection infrastructure. |
| Construction Equipment Hydraulic Specialization | Captures underserved demand in Mendoza and Córdoba infrastructure projects. |
| Base Oil Supply Diversification | Reduces import dependency volatility from United States and Brazilian refining margins. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs import records, IRAM certification registries, and Secretaría de Energía fuel economy claim filings. Fleet maintenance directors, lubricant procurement managers at logistics providers, regional blender operations heads, and YPF channel managers contributed structured interviews. Bottom-up volume estimates from product-type and end-user segmentation triangulate against top-down market sizing from trade flow analysis and refinery output data.
Segmentation dimensions modeled include formulation chemistry tier, product type, end-user category, and distribution channel across the projection horizon. CAGRs derive from utilization-driven drain interval compression, synthetic substitution elasticity, and regulatory compliance cost pass-through assumptions. Forecast inputs incorporate fleet operator consolidation rates in Buenos Aires province and agricultural equipment seasonal demand patterns in interior provinces.
Underlying assumptions cover IRAM certification timeline adherence and base oil import cost pass-through rates, with deviation risk concentrated in currency volatility and Euro VI-equivalent mandate timing. Practitioners should keep alternative scenarios live as emissions regulation alignment and fleet electrification pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Wiping Systems Market
Automotive Parts
Diesel Oxidation Catalyst Market
Automotive Parts
Automotive Engine Cam Cover Market
Automotive Parts
Automotive AC Compressor Market
Automotive Parts
Air Brake Market
Automotive Parts
Asia Pacific Automotive Parts Die Casting Market
Automotive Parts
Electric Parking Brake Market
Automotive Parts
ASEAN Automotive Bearings Market
Automotive Parts
Automotive Thermal Systems Market
Automotive Parts
Automotive Weatherstrips Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Automotive Vents Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
Automotive All Wheel Drive Market
Automotive Parts
Industrial Roller Chain Drives Market