
 Automotive Electric HVAC Compressor Market | 2026-2036
Automotive Electric HVAC Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electric HVAC Compressor Market Intelligence
China is narrowing the supply gap for high-voltage electric compressors through dedicated manufacturing zones serving the domestic EV supply chain. Denso Corporation leverages its integrated thermal systems portfolio to anchor premium OEM contracts across Asia. MAHLE GmbH competes on R&D intensity with dedicated e-compressor test facilities in Stuttgart. BorgWarner, Inc positions its power electronics expertise to extend into compressor motor control integration.
An automotive electric HVAC compressor converts electrical energy into refrigerant pressure cycles using a sealed scroll or piston mechanism driven by a brushless DC motor, typically operating at 400-800V in modern EV architectures to enable cabin conditioning without engine load. The device serves the essential commercial purpose of decoupling climate control from internal combustion, preserving battery range in electric drivetrains. Scroll compressors dominate installed value due to superior efficiency at variable speeds, while variable displacement designs capture expanding share as OEMs demand precise thermal load matching. The electric-driven technology segment leads volume, though thermal management integration is reshaping competitive positioning as suppliers bundle compressors with battery cooling loops.
The EPA oversees refrigerant transition timelines under SNAP rules that directly shape compressor compatibility requirements for vehicles sold in the United States. EMA and REACH jointly govern chemical safety and type-approval standards for European automotive HVAC components, creating dual compliance burdens for exporters. China's MIIT enforces GB standards for electric vehicle thermal system efficiency that compressors must satisfy for domestic market access. Stakeholders must monitor how refrigerant chemistry standards diverge across jurisdictions and decide whether to platform single architectures or develop region-specific compressor variants.
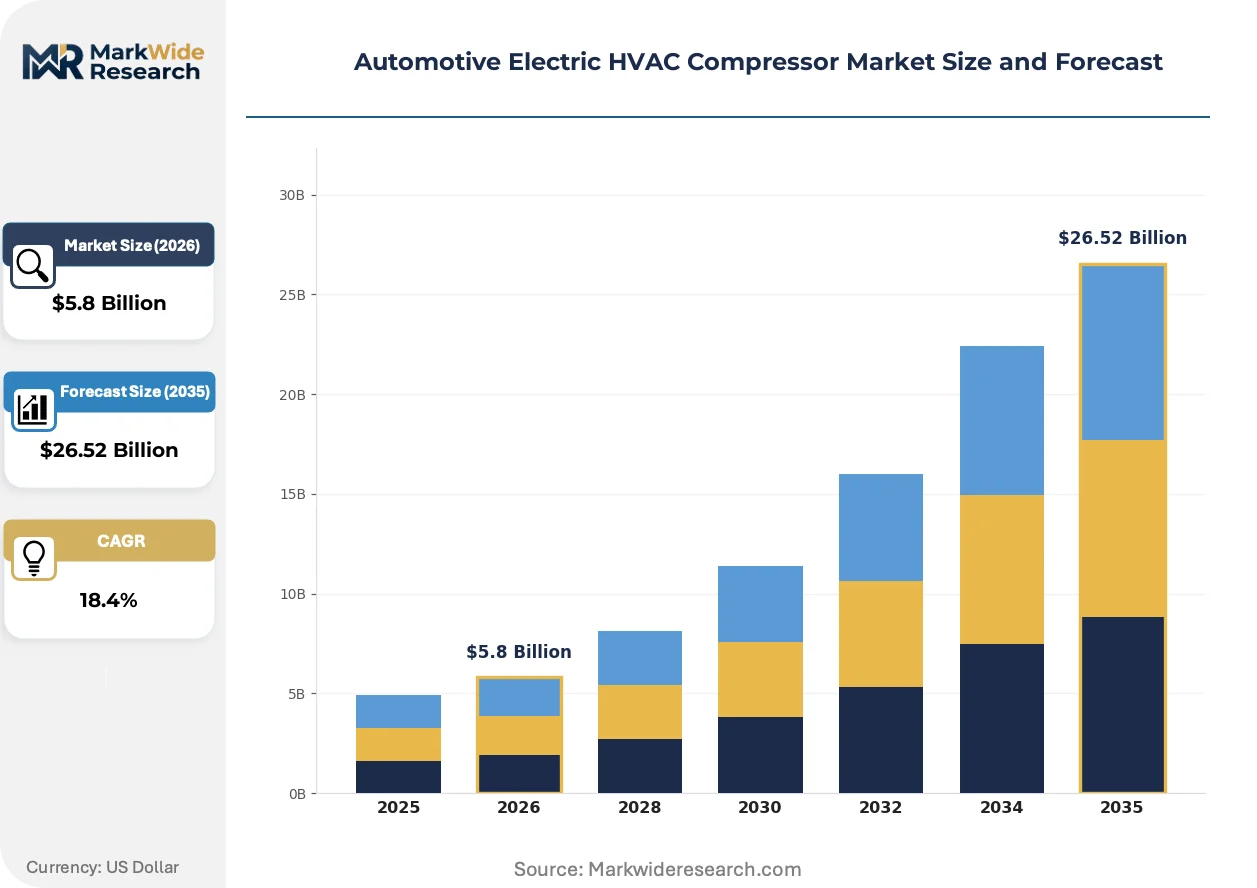
Market Dynamics
High-voltage platform proliferation is compressing development cycles as OEMs demand 800V-compatible compressors that integrate with battery thermal loops rather than standalone cabin units.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants under EU F-Gas rules is mandating compressor redesigns compatible with CO2 and HFO alternatives, forcing technology refresh across European vehicle programs.
- Multi-zone cabin architectures:Premium EV platforms now specify independent front and rear climate zones, doubling compressor unit counts per vehicle and expanding addressable component value.
- China:Domestic manufacturing clusters in Jiangsu and Zhejiang provinces are achieving scale economies that compress export pricing for global OEM supply programs.
Market Restraints
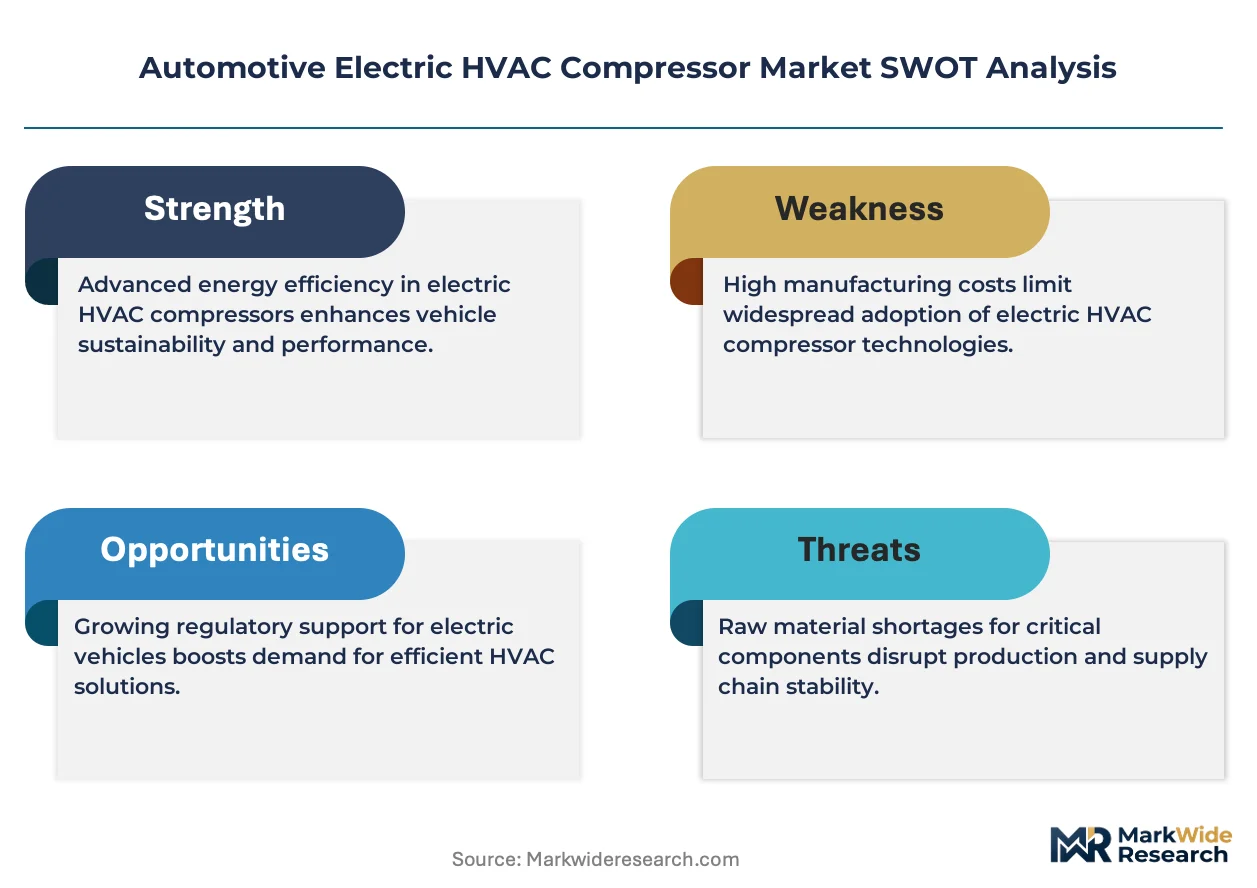
- Rare earth magnet dependency:Neodymium and dysprosium supply concentration in Chinese processing facilities creates input cost volatility and geopolitical exposure for brushless DC motor production.
- High-voltage safety certification:IEC 60664 insulation coordination standards for 800V systems extend validation timelines and raise non-recurring engineering costs for new compressor platforms.
- Thermal management integration:OEMs are bundling compressors with battery cooling circuits into single supplier contracts, compressing standalone component margins and raising barrier to entry.
Strategic Opportunities
- India:The PLI scheme for automotive components and accelerating EV adoption under FAME III create first-mover advantage for localized compressor assembly serving domestic two-wheeler and four-wheeler electrification.
- Refrigerant convergence:CO2 transcritical systems compatible with electric compressors are gaining traction in cold-climate markets, opening technology licensing opportunities for scroll mechanism specialists.
- Service channel digitization:Predictive compressor health monitoring via CAN bus integration enables aftermarket subscription revenue streams and reduces warranty exposure for fleet operators.
Industry Challenges
- Power electronics integration:In-house inverter design capability is becoming mandatory as OEMs specify compressor-motor-controller as a single procurement unit, forcing tier-one suppliers to acquire or develop semiconductor competency.
- Cross-regional refrigerant fragmentation:Divergent EPA SNAP, EU F-Gas, and China GB standards on allowable chemistries are forcing suppliers to maintain parallel compressor architectures rather than global platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electric HVAC Compressor Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $26.52 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Variable Displacement, Fixed Displacement, Scroll, Centrifugal Technology: Electric Driven, Hybrid, Thermal Management, Advanced Control End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Aftermarket Application: Heating, Cooling, Defrosting, Ventilation |
| Companies Covered | Denso Corporation, Hanon Systems, MAHLE GmbH, Valeo, Sanden Corporation, BorgWarner, Inc, Toyota Industries Corporation, Brose Fahrzeugteile SE & Co. KG, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electric HVAC Compressor Market Strategic Shifts & Innovations
Scroll mechanism optimization and refrigerant chemistry transitions are converging to redefine compressor efficiency benchmarks, while thermal system integration is collapsing traditional component boundaries.
Variable displacement scroll technology is migrating from fixed-speed operation to continuous modulation, enabling precise matching of refrigerant mass flow to cabin and battery cooling loads. Luxury EV platforms are adopting these mechanisms first, prioritizing range preservation over unit cost. The technology shift is compressing demand for binary on-off compressor designs and rewarding suppliers with mechatronic control expertise.
EPA SNAP refrigerant phase-down rules are accelerating R-1234yf adoption while restricting higher-GWP alternatives, directly shaping compressor seal materials and lubricant compatibility requirements for vehicles sold in the United States. The regulatory pressure is most acute for suppliers serving light-duty truck platforms where cooling loads are highest. Compressor manufacturers are responding with dual-chemistry seal validation programs that extend development timelines but preserve market access.
Fleet procurement departments are consolidating thermal system sourcing under single-supplier vehicle-level contracts rather than component-by-component bidding, compressing the addressable market for standalone compressor vendors. This concentration is most visible in North American commercial vehicle electrification programs where total cost of ownership dominates selection criteria. Surviving suppliers are embedding compressors within integrated battery cooling modules to retain contract relevance.
Automotive Electric HVAC Compressor Market Segmentation
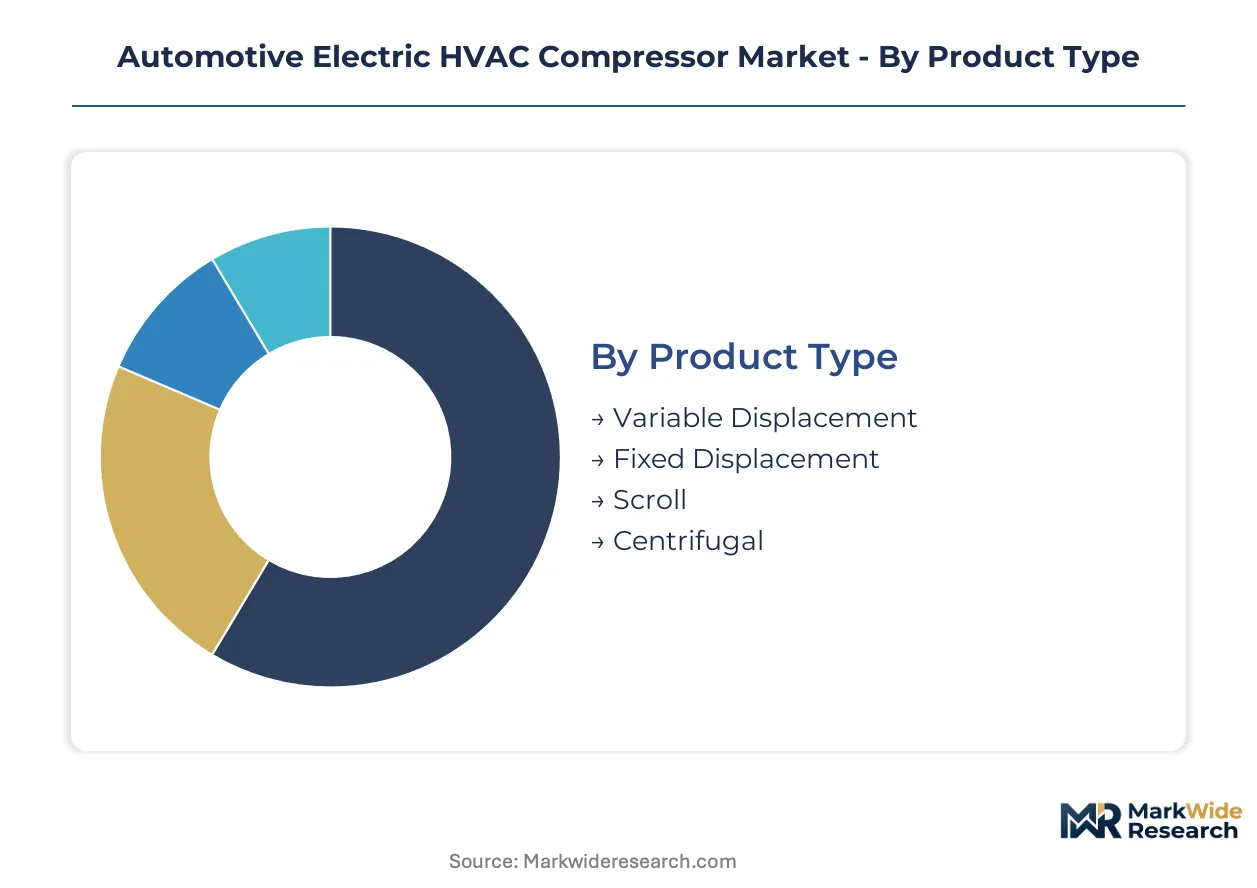
Electric HVAC compressor architectures diverge sharply by thermal load profile and voltage platform compatibility. Segmentation reveals how scroll mechanisms dominate premium battery electric vehicle programs while fixed displacement units retain cost-sensitive segments.
Product Type:
Use-case spectrum spans high-efficiency variable modulation in luxury electric SUVs to binary fixed-output units in economy electric two-wheelers.
- Scroll:Sealed orbital scroll mechanisms achieve superior isentropic efficiency across 30-100% speed modulation ranges. Demand concentrates in Tesla, BYD, and premium European OEM platforms where range preservation mandates precise thermal load matching.
- Variable Displacement:Continuous capacity modulation via swashplate angle adjustment enables single-compressor multi-zone cabin architectures. German and Korean OEMs specify these for flagship electric sedans with independent front and rear climate control.
- Fixed Displacement:Piston or scroll designs with binary on-off operation serve cost-optimized electric commercial vehicles and entry-level passenger EVs in India and Southeast Asia.
- Centrifugal:High-speed impeller designs target heavy-duty electric buses and thermal management integration with battery cooling loops in Chinese electric truck platforms.
Established volume favors fixed displacement; emerging adoption favors scroll.
Technology:
Cost tier separation runs from commodity electric motor-inverter packages to semiconductor-intensive integrated thermal systems.
- Electric Driven:Brushless DC motors operating at 400-800V with silicon carbide inverters dominate new platform development. MIIT efficiency mandates in China and EPA refrigerant rules in the United States accelerate deployment across OEM supply chains.
- Thermal Management:Compressor-battery cooling circuit integration collapses component boundaries into single procurement units. European OEMs led by Volkswagen Group and Stellantis specify these bundled architectures first.
- Hybrid:Dual-mode compressors compatible with both electric and belt-driven operation serve plug-in hybrid transition platforms in Japan and Europe.
- Advanced Control:CAN bus-integrated predictive health monitoring and AI-driven load forecasting command premium pricing in fleet electric vehicle contracts.
Volume concentration sits with electric driven; steepest expansion trajectory belongs to thermal management integration.
End User:
Application maturity separates mass-market passenger electrification from nascent commercial vehicle thermal system redesign.
- Electric Vehicles:Purpose-built 800V architectures from dedicated EV platforms generate the highest per-unit compressor value. Chinese domestic brands and Tesla absorb the majority of high-voltage scroll compressor output.
- Passenger Vehicles:Conventional internal combustion platforms with electric compressor retrofits for mild hybrid systems retain significant installed base in Europe and North America.
- Commercial Vehicles:Electric bus and truck fleets in California, Germany, and China drive demand for heavy-duty centrifugal and large-displacement scroll units.
- Aftermarket:Replacement compressor modules for first-generation EVs entering warranty expiration create service channel revenue in the United States and Western Europe.
Current revenue weight rests with electric vehicles; commercial vehicle electrification offers the fastest volume climb.
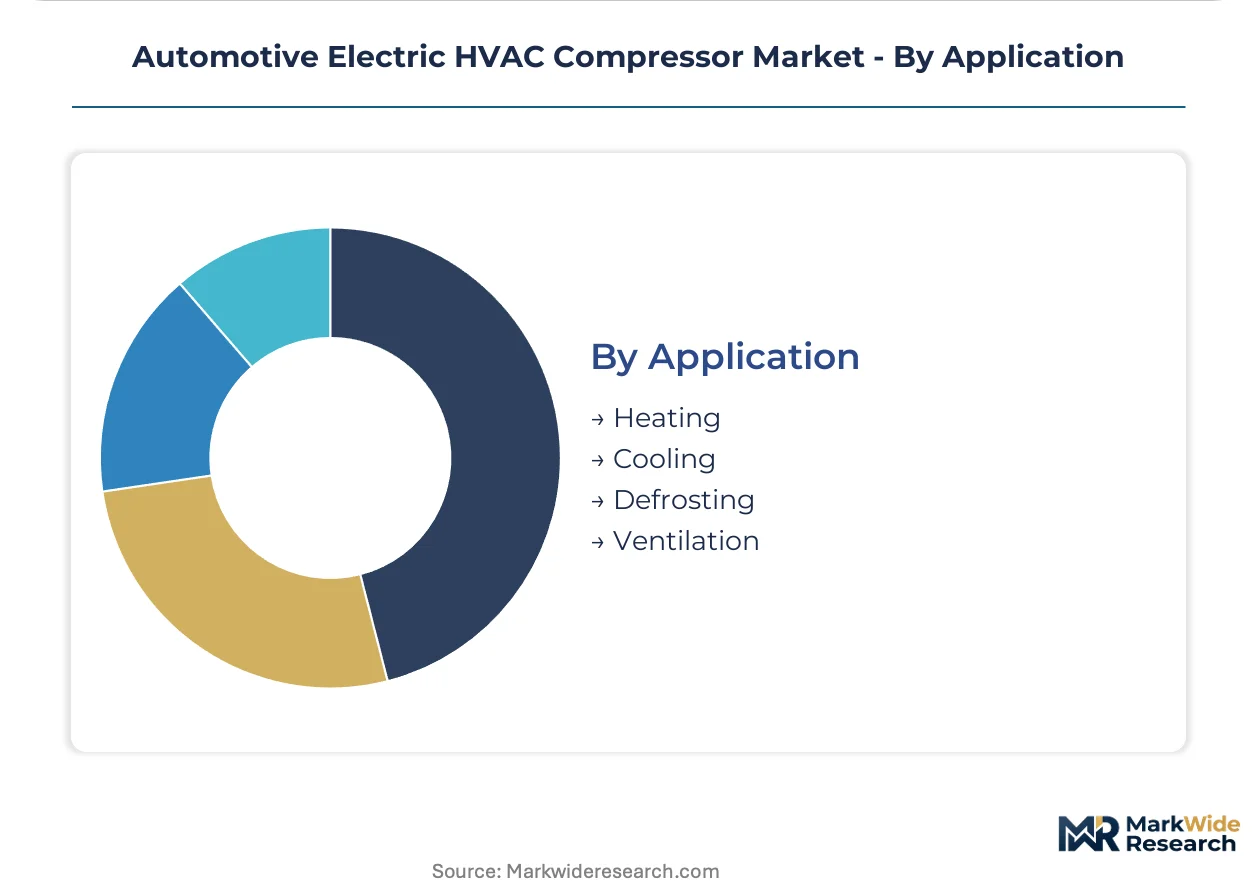
Application:
Functional priority dictates compressor specification—cabin comfort demands precise modulation while battery thermal safety requires continuous operation.
- Cooling:Peak load operation during fast-charging events and summer ambient conditions stresses compressor durability. Variable displacement scroll designs capture premium positioning for this stress-intensive function.
- Heating:Heat pump integration with compressor reversal or dedicated heating circuits expands addressable system value in cold-climate markets including Norway, Canada, and northern China.
- Defrosting:Rapid windshield clearing demands burst compressor capacity coordinated with PTC heater elements in safety-critical winter scenarios.
- Ventilation:Minimal compressor engagement for cabin air circulation serves lowest-margin applications in economy vehicle segments.
Cooling commands installed value priority; heating via heat pump integration gains share fastest in high-latitude markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys electric HVAC compressors primarily for battery thermal management integration, while the United States and Germany emphasize cabin multi-zone architectures with independent rear climate control. This consumption-mix differential shapes distinct supplier qualification requirements across major automotive manufacturing hubs.
China
Jiangsu and Zhejiang provinces host dedicated manufacturing clusters scaling high-voltage scroll compressor output for domestic EV brands and export programs. MIIT enforces GB standards for electric vehicle thermal system efficiency that compressors must satisfy for market access. Denso and local suppliers anchor production in these eastern coastal zones.
United States
EPA SNAP refrigerant phase-down rules accelerate R-1234yf adoption, directly shaping compressor seal materials and lubricant compatibility requirements. California's Advanced Clean Trucks regulation drives heavy-duty electric commercial vehicle thermal system demand. Detroit-area OEM engineering centers specify integrated compressor-battery cooling architectures.
Germany
EU F-Gas Regulation mandates compressor redesigns compatible with CO2 and HFO alternatives, forcing technology refresh across European vehicle programs. Stuttgart anchors MAHLE's dedicated e-compressor test facilities. Bavaria-based OEMs led by Volkswagen Group specify bundled thermal management systems first.
Japan
METI oversees automotive component efficiency standards that compressors must meet for domestic type approval. Toyota Industries Corporation and Denso leverage integrated thermal systems portfolios to anchor premium OEM contracts. Aichi Prefecture manufacturing corridors concentrate brushless DC motor production.
South Korea
Hanwha Solutions and Hanon Systems scale 800V-compatible compressor platforms for Hyundai-Kia dedicated EV architectures. The national industrial policy prioritizes localized supply chain development for electric vehicle thermal components. Gyeonggi-do production zones serve both domestic OEMs and export programs to North America.
Automotive Electric HVAC Compressor Market Key Industry Players
Capability concentration sits with integrated thermal system specialists; scale advantage sits with diversified automotive component conglomerates. The vendor base stratifies across three tiers: full-system integrators bundling compressors with battery cooling loops, standalone compressor specialists defending component margins, and emerging Asian manufacturers achieving cost parity through dedicated EV supply chain integration. Dominant competitive moves include strategic partnerships for refrigerant chemistry co-development and geographic expansion into India under PLI scheme incentives.
Within the integrated-system tier, Denso Corporation and MAHLE GmbH occupy positions exemplifying full thermal management portfolio breadth. BorgWarner, Inc represents the power electronics integration archetype, extending semiconductor competency into compressor motor control. These three anchors demonstrate how tier-one suppliers are repositioning around bundled procurement units rather than standalone component sales.
| Leading Market Players |
|---|
| Denso Corporation |
| Hanon Systems |
| MAHLE GmbH |
| Valeo |
| Sanden Corporation |
| BorgWarner, Inc |
| Toyota Industries Corporation |
| Brose Fahrzeugteile SE & Co. KG |
| Robert Bosch GmbH |
| Others |
Cost & Logistics Intelligence
Overcapacity in Jiangsu Province manufacturing clusters is compressing export pricing for Chinese electric compressor suppliers while simultaneously eroding margin buffers for European and Japanese incumbents serving premium OEM contracts.
Pricing Analysis
Long-term offtake agreements dominate procurement between Tier 1 suppliers and OEM platform engineering centers, locking in volume commitments across multi-year vehicle program cycles. Pricing stratifies across premium scroll mechanisms with 800V silicon carbide inverters, standard 400V fixed-displacement units for economy EVs, and economy-tier piston compressors for commercial vehicle retrofits. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers are achieving scale economies that undercut incumbent landed costs. Fleet procurement departments exhibit the highest price sensitivity, while luxury OEM platform engineering teams prioritize thermal efficiency metrics over unit cost.
Supply Chain Analysis
Export control regimes on semiconductor manufacturing equipment are restricting flows of advanced silicon carbide wafer processing technology to Chinese compressor inverter suppliers, creating technology access gaps. Manufacturing concentration rests in China, South Korea, and Germany, with Jiangsu Province hosting the densest cluster of scroll compressor final assembly. Neodymium and dysprosium rare earth magnets, high-voltage insulation materials, and precision-machined scroll sets constitute critical input dependencies. Single-source vulnerability around Chinese rare earth processing facilities poses structural supply risk. Distribution runs through OEM direct procurement channels and Tier 1 thermal system integrators rather than aftermarket wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around 800V safety certification and refrigerant chemistry standards creates durable barriers against unqualified entrants.
For Market Incumbents: Pre-empt margin erosion in the scroll compressor segment by acquiring captive capacity in silicon carbide inverter design rather than sourcing from merchant semiconductor suppliers. Accelerate certification investment for CO2 transcritical refrigerant compatibility ahead of EU F-Gas enforcement timelines to lock out latecomers from European OEM supply programs.
For New Entrants and Emerging Players: India's electric commercial vehicle aftermarket under FAME III incentives represents the most penetrable entry point for localized compressor assembly serving domestic bus and truck electrification. Two-wheeler thermal management in Southeast Asia offers secondary white-space with lower certification barriers. A service-channel-first go-to-market angle via predictive health monitoring subscriptions bypasses entrenched OEM supply relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compressor suppliers with integrated thermal management portfolios bundling battery cooling loops. Long-term viability favors targets with in-house power electronics competency and established 800V platform qualifications. Watch for inflection signals in Indian PLI scheme disbursement rates as early indicators of manufacturing relocation momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| 800V Platform Standardization | Denso and MAHLE are consolidating inverter-motor architectures to capture multi-OEM supply contracts. |
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts with Chinese processors reduce input cost volatility for brushless DC production. |
| CO2 Transcritical System Licensing | Scroll mechanism specialists are monetizing cold-climate heat pump technology through OEM royalty structures. |
| Predictive Health Monitoring Integration | CAN bus-enabled compressor diagnostics create aftermarket subscription revenue streams for fleet operators. |
| Indian Manufacturing Footprint Expansion | PLI scheme incentives are attracting compressor assembly investments to serve domestic EV electrification. |
Research Approach
Desk research of customs trade databases, MIIT vehicle type-approval filings, and EPA SNAP regulatory dockets preceded structured interviews with OEM platform thermal engineers, Tier 1 supplier procurement directors, aftermarket fleet maintenance managers, and rare earth materials traders. Primary fieldwork combined telephone interviews and facility observations in Jiangsu and Zhejiang manufacturing corridors with secondary validation against IHS Markit vehicle production data and company SEC disclosures. Bottom-up compressor shipment estimates triangulated against top-down EV platform thermal system content valuations.
Assumptions around 800V platform penetration rates and refrigerant chemistry transition timelines were held fixed across baseline scenarios while OEM thermal system integration preferences and rare earth supply chain disruptions were stress-tested as sensitivity variables. The analytical framework modeled volume and value across vehicle class, propulsion architecture, compressor mechanism type, and regional production cluster dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical platform adoption curves calibrated to OEM engineering release schedules and regulatory phase-in deadlines.
Practitioners should monitor EU F-Gas enforcement actions, EPA refrigerant rulemaking revisions, and Chinese export license restrictions on rare earth processing as early signals requiring forecast reassessment. Material shifts in OEM procurement consolidation toward single-supplier thermal system contracts or breakthroughs in rare earth-free motor magnet technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Universal Joint Shafts Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Nigeria Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Radiator Hose Market
Automotive Parts
Poland Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Remanufactured Parts Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
North America Ceramic Ball Bearings Market
Automotive Parts
North America Automotive AHSS Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
Automotive Steering Knuckle Market
Automotive Parts
Global Inductive Loop Vehicle Detector Market
Automotive Parts
Latin America Electric Power Steering Market