
 X-Arm Type Window Regulator Market | 2026-2036
X-Arm Type Window Regulator Market Size, Share, and Industry Trends Forecast 2026-2036
X-Arm Type Window Regulator Market Analytics
Europe's F-Gas Regulation is expanding the cost-of-entry calculus for X-arm type window regulator suppliers by mandating fluorinated-gas audits across automotive component supply chains. Bosch leverages captive manufacturing in Germany to sustain compliance advantages across electric window-lift systems. Brose anchors European OEM relationships through specialized door-module integration that bundles regulator, motor, and control electronics.
An X-arm type window regulator is a scissor-linkage mechanism that converts rotary motion into linear vertical displacement, typically fabricated from stamped steel or die-cast aluminum arms with polymer slide bushings, and engineered to support glass panels weighing 3-8 kilograms across 150,000+ operational cycles in passenger vehicles. Electric product types now dominate OEM fitment as automakers eliminate manual cranks to reduce cabin weight and assembly complexity. Steel material grades still occupy the aftermarket channel where cost sensitivity overrides mass-reduction priorities, while aluminum variants lead premium OEM programs targeting fleet efficiency standards. Repair shops represent a concentrated margin pool within the aftermarket end-user segment due to part failure rates concentrated in vehicles exceeding seven years of service life.
FDA oversight of automotive-grade polymer additives intersects with EPA material-recovery mandates in the United States, compelling suppliers to document full substance inventories across regulator subassemblies. ECHA's REACH restrictions on hexavalent chromium coatings directly affect corrosion-protection protocols for steel X-arm mechanisms sold into Europe. Japan's METI energy-efficiency guidelines for vehicle components create parallel compliance obligations for Aisin Seiki and HI-LEX Corporation in their domestic production. Stakeholders must monitor diverging regional substance restrictions when selecting base materials and surface treatments for next-generation regulator platforms.
Market Dynamics
Automotive electrification is compressing the window regulator supply chain as OEMs eliminate mechanical linkages in favor of integrated door-module architectures, forcing stampers and motor suppliers to consolidate their Tier-2 positioning.
Growth Catalysts
- Lightweighting mandates:Corporate Average Fuel Economy standards in the United States and CO2 fleet targets in the European Union are accelerating aluminum substitution in scissor-linkage arms. Die-cast aluminum grades now penetrate mid-range vehicle segments previously reserved for stamped steel.
- REACH compliance:ECHA's restrictions on hexavalent chromium surface treatments are redirecting European supplier R&D toward trivalent chrome and zinc-nickel alloy coatings. This regulatory pressure is creating first-mover advantages for finishing houses with certified alternative processes.
- Door-module integration:Automakers in Germany and Japan are bundling regulators with latch mechanisms, control electronics, and sealing systems into pre-tested subassemblies. This architectural shift reduces assembly-line labor content and warranty exposure for OEM final-assembly plants.
Market Restraints
- Steel price volatility:Hot-rolled coil input costs fluctuate with energy-intensive European smelter output and scrap-metal flows from construction demolition. Stamped-steel arm producers face margin compression when contract pricing resets lag spot-market spikes by 6-9 months.
- Supply concentration:Polyamide slide-bushing formulations depend on caprolactam feedstocks concentrated in Belgian and German chemical complexes. Any force majeure event at these facilities propagates through window-lift mechanism lead times within 4-6 weeks.
- Manual-crank obsolescence:Base-model vehicle trims in emerging markets still specify hand-cranked regulators, but OEM product planners are deleting these variants to simplify BOM complexity. Aftermarket demand for replacement manual mechanisms is contracting faster than electric-motor supply can reabsorb the volume.
Strategic Opportunities
- India vehicle production:Domestic OEMs and joint-venture assemblers are localizing door-system sourcing to qualify for PLI scheme incentives. X-arm regulator suppliers with stamping and motor-winding capabilities can capture platform awards for compact SUV and entry-sedan programs.
- Repair-channel digitization:Independent garages in the United States are migrating parts procurement to integrated shop-management platforms that aggregate demand and negotiate landed-cost pricing. Specialist distributors with real-time inventory visibility can displace traditional jobber networks.
- F-Gas audit services:Europe's fluorinated-gas tracking requirements create adjacent revenue streams for component suppliers willing to document supply-chain refrigerant exposure. Door-module integrators can bundle compliance documentation with regulator shipments to reduce OEM audit burden.
Industry Challenges
- Multi-material welding certification:Aluminum-steel hybrid arm constructions require friction-stir or laser-brazing qualifications that extend prototype-to-production timelines by 8-12 months. Tier-1 suppliers must maintain parallel welding-lab capabilities or outsource to qualified sub-tier partners.
- Embedded software validation:Electric regulators with anti-pinch and obstacle-detection algorithms require ISO 26262 functional-safety assessments. Smaller mechanical-component houses lack in-house embedded-systems teams and face talent-acquisition competition from semiconductor and EV-powertrain sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Arm Type Window Regulator Market |
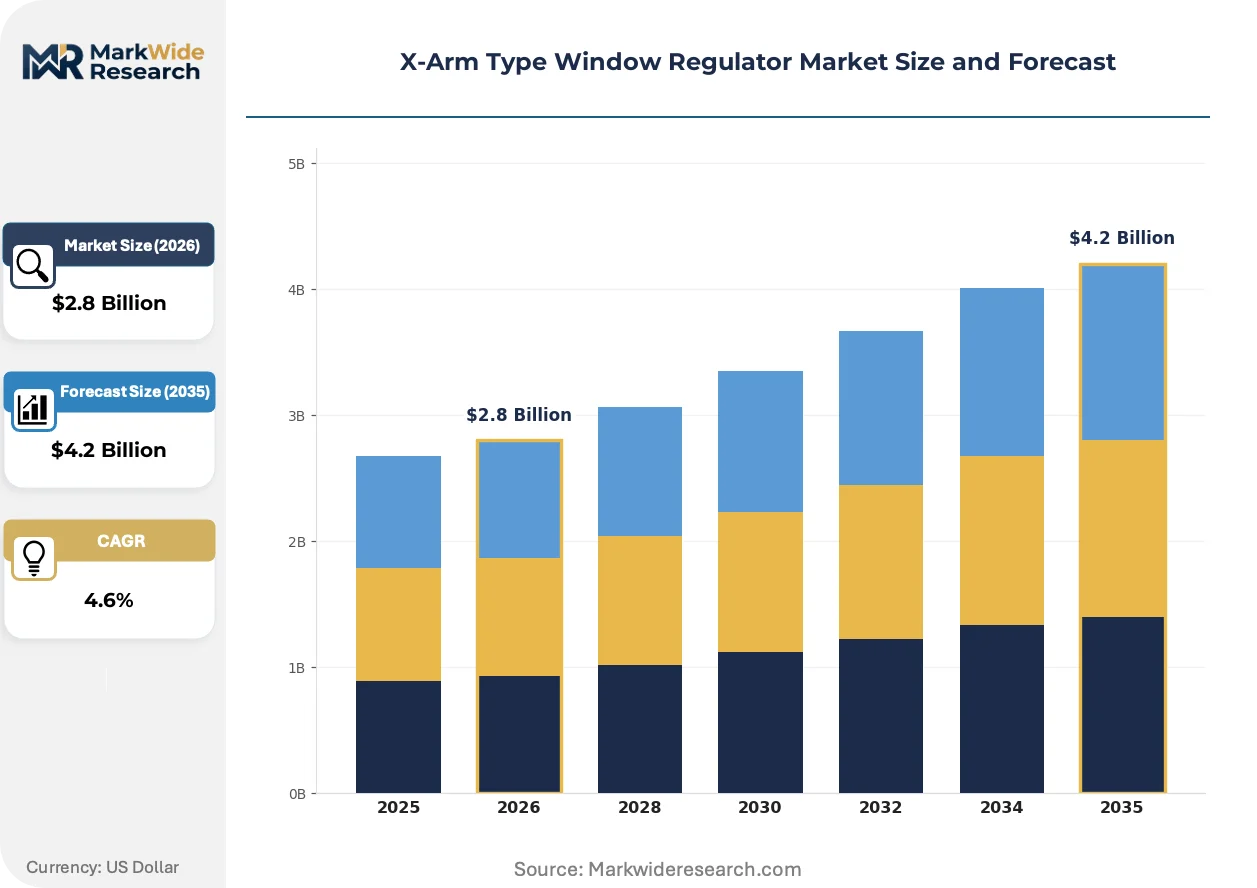
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Hydraulic, Pneumatic End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Material: Aluminum, Steel, Plastic, Composite Installation Type: Direct Fit, Universal Fit, Custom Fit, Modular |
| Companies Covered | Bosch, Shiroki, Brose, Johnan Manufacturing Inc., HI-LEX Corporation, Valeo, Aisin Seiki, F.tech Inc., Grupo Antolin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Arm Type Window Regulator Market Evolving Landscape
Window-lift mechanisms are converging with door-electronics architectures, compressing the traditional boundary between mechanical component supply and mechatronic system integration.
Brushless DC motor technology is electrifying the powertrain within electric window regulators. These motors eliminate carbon-brush wear debris that contaminates gearboxes over 150,000-cycle lifespans. German and Japanese OEMs are specifying brushless architectures for premium vehicle lines where warranty exposure extends to 10 years. The technology is electrifying supplier investment priorities as motor houses retool winding and control-assembly lines.
Europe's F-Gas Regulation is mandating supply-chain audits for fluorinated greenhouse gases used in polymer processing and surface-treatment cleaning. Component suppliers must document refrigerant inventories across tier-2 and tier-3 inputs. Door-module integrators serving Stuttgart-based OEMs are absorbing compliance costs to defend long-term platform relationships.
Fleet procurement departments are consolidating aftermarket parts sourcing through integrated maintenance-management platforms. Large rental and commercial-fleet operators in the United States now specify OE-equivalent regulators with documented cycle-testing rather than economy-grade alternatives. This specification tightening is visible most acutely in airport shuttle and last-mile delivery vehicle segments where window-failure downtime carries direct revenue penalties.
X-Arm Type Window Regulator Market Segmentation
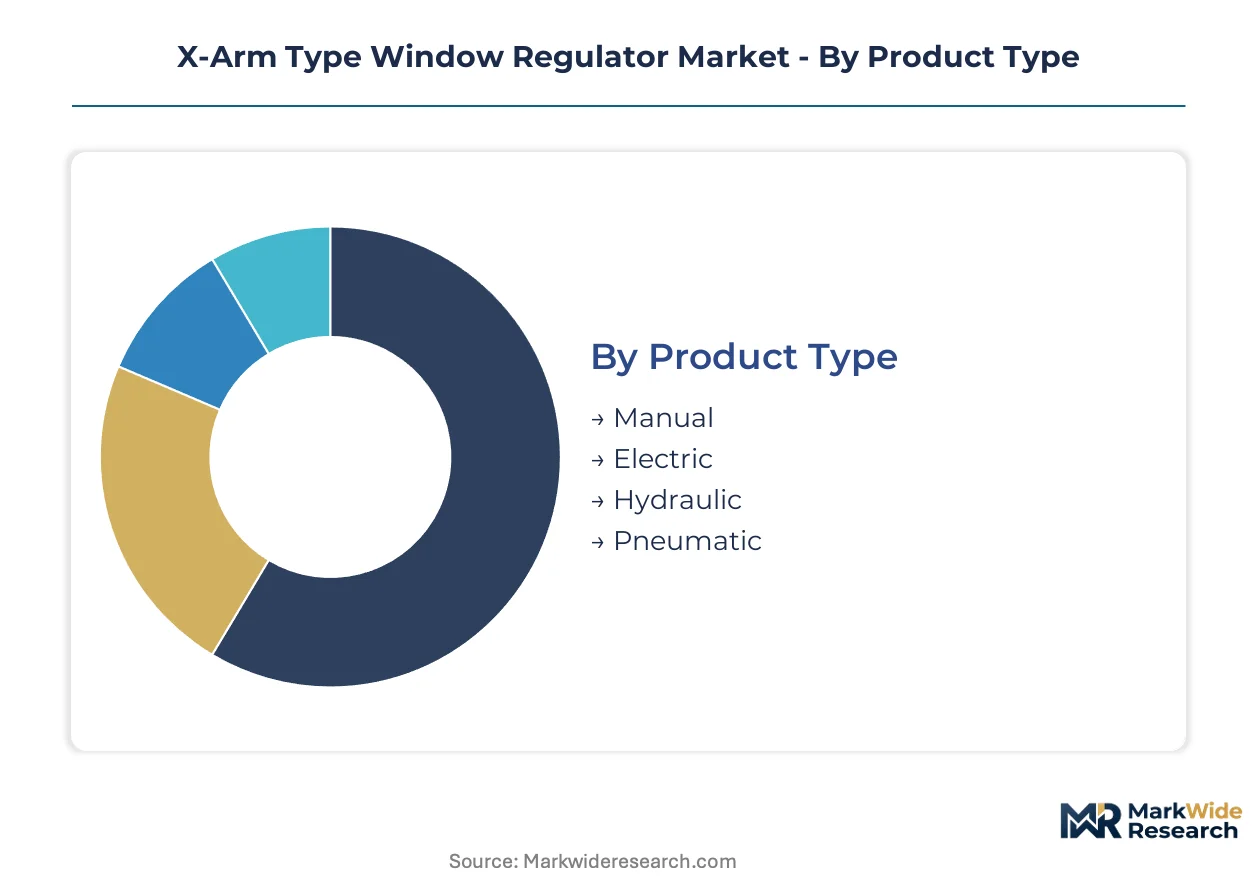
X-arm type window regulator segmentation reveals how mechanical component suppliers must align their architectures with divergent OEM integration strategies. Each dimension—powertrain, procurement channel, material substrate, and mounting protocol—carries distinct margin profiles and certification burdens that reshape competitive positioning across automotive supply tiers.
Product Type:
Standalone manual mechanisms persist in cost-engineered platforms, while embedded electric systems dominate integrated door-module architectures where motor, gearbox, and control electronics merge into single supplier accountability.
- Manual:Hand-cranked scissor-linkage mechanisms fabricated from stamped steel with polymer bushings. Demand concentrates in emerging-market base trims where OEMs delete electric motors to protect entry-price positioning; volume contracts as automakers simplify BOM complexity across all segments.
- Electric:Motor-driven X-arm assemblies with integrated anti-pinch sensors and CAN-bus communication. German and Japanese OEMs specify these for premium vehicle lines where door-module bundling reduces assembly-line labor content; brushless DC architectures are displacing brushed motors in warranty-sensitive applications.
- Hydraulic:Fluid-actuated lift systems for heavy commercial glass panels in specialty vehicles.
- Pneumatic:Compressed-air mechanisms deployed in industrial and off-highway equipment with available shop-air infrastructure.
Volume placements concentrate in Electric; the faster expansion belongs to brushless sub-variants.
End User:
Procurement authority fragments across direct OEM platform awards, aftermarket parts distribution, and repair-channel service billing, each with distinct specification rigor and price elasticity.
- OEMs:Original equipment manufacturers specifying regulators within integrated door-system contracts. Stuttgart-based premium brands and Toyota City assemblers demand 150,000-cycle validation and REACH-compliant surface treatments; platform-award durations now extend 7-10 years to amortize tooling investment.
- Aftermarket Providers:Distributors and private-label suppliers serving independent jobber networks. Steel-grade mechanisms dominate this channel where cost sensitivity overrides mass-reduction priorities; digitized procurement platforms are displacing traditional warehouse-based distribution.
- Vehicle Assemblers:Contract manufacturers and joint-venture operations localizing content to qualify for PLI scheme incentives in India.
- Repair Shops:Independent garages and dealership service departments billing parts and labor to vehicle owners. Margin concentrates here due to failure rates in vehicles exceeding seven years of service life; fleet maintenance contracts now specify OE-equivalent cycle-testing documentation.
Revenue concentration sits with OEMs; repair-channel digitization is gaining share fastest.
Material:
Mass-reduction imperatives collide with aftermarket cost floors, forcing suppliers to maintain parallel production lines across substrate grades with incompatible welding and finishing protocols.
- Aluminum:Die-cast alloy arms specified for CAFE compliance and EU CO2 fleet targets. Mid-range vehicle segments previously reserved for stamped steel now adopt aluminum grades; friction-stir welding qualifications extend prototype-to-production timelines.
- Steel:Hot-rolled and cold-rolled stampings with hexavalent-chrome or trivalent-chrome corrosion protection. Aftermarket demand anchors this segment where spot-price volatility in European smelter output compresses margins during contract reset lags.
- Plastic:Glass-reinforced polymer arms for weight-critical applications in electric vehicle architectures.
- Composite:Hybrid fiber-reinforced structures emerging in concept-phase door modules.
Steel retains volume leadership; aluminum climbs the fastest on regulatory pressure.
Installation Type:
Mounting protocol selection determines whether suppliers capture standalone component revenue or cede margin to door-module integrators bundling regulator, latch, and sealing systems.
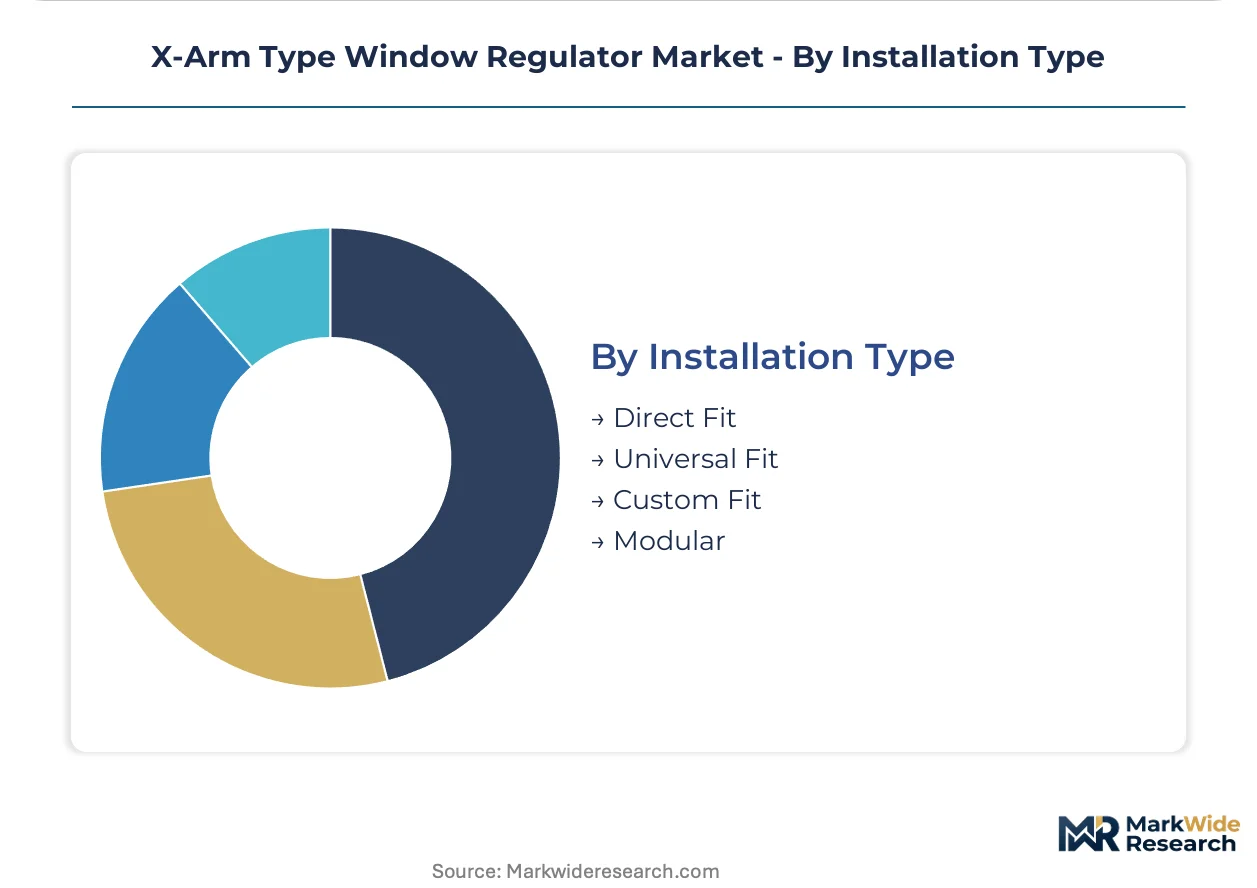
- Direct Fit:Vehicle-specific designs with pre-drilled mounting points and calibrated travel stops. OEM final-assembly plants in Detroit and Stuttgart favor these for line-speed efficiency; suppliers must maintain tooling libraries across 200+ platform variants.
- Universal Fit:Adjustable-length mechanisms serving aftermarket replacement demand. Independent garages in the United States specify these for inventory reduction; documentation burden falls on installers for travel-limit calibration.
- Custom Fit:Bespoke architectures for limited-production specialty vehicles and coachbuilt applications.
- Modular:Pre-tested subassemblies integrating regulator, motor, control electronics, and sealing systems. Brose and Bosch leverage these to defend European platform relationships; architectural compression forces stampers to accept Tier-2 positioning.
Direct Fit commands current volume; Modular is expanding most quickly through door-system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive zones in India and Mexico's shelter maquiladora programs are concentrating X-arm regulator assembly capacity near OEM final-assembly plants. Stuttgart, Toyota City, and Detroit anchor premium vehicle demand clusters. Regulatory divergence across REACH, EPA, and METI frameworks forces suppliers to maintain parallel material-certification libraries.
Germany
Premium OEM platform awards from Stuttgart-based manufacturers drive specification intensity for 150,000-cycle validated mechanisms. ECHA's REACH restrictions on hexavalent chromium coatings compel suppliers to adopt trivalent chrome and zinc-nickel finishing protocols. Brose and Bosch maintain captive manufacturing in Baden-Württemberg to defend door-module integration contracts.
United States
Detroit-area OEMs specify aluminum-grade regulators for CAFE compliance across light-truck and SUV platforms. EPA material-recovery mandates intersect with FDA oversight of polymer additives, forcing full substance inventory documentation. Midwest stamping houses supply aftermarket steel variants to independent repair channels concentrated in Texas and Florida fleet maintenance networks.
Japan
METI energy-efficiency guidelines for vehicle components create compliance obligations for domestic suppliers serving Toyota City and Nagoya assemblers. Aisin Seiki and HI-LEX Corporation anchor production in Chubu region. Brushless DC motor architectures penetrate premium lines where 10-year warranty exposure demands extended cycle durability.
India
PLI scheme incentives for automotive component localization attract door-system suppliers to Tamil Nadu and Maharashtra joint-venture operations. Domestic OEMs and Suzuki-Maruti assemblers specify cost-engineered steel mechanisms for compact SUV and entry-sedan programs. Stampers with motor-winding capabilities capture platform awards previously sourced from ASEAN suppliers.
Mexico
Maquiladora shelter programs near Nuevo León and Bajío Region assembly plants concentrate regulator production for US-bound light-truck exports. OEMs leverage tariff-advantaged sourcing to supply Detroit and Southeast US final-assembly operations. Suppliers maintain steel-grade stamping for aftermarket channels serving 7+ year vehicle populations across border states.
X-Arm Type Window Regulator Market Competitive Landscape
German producers anchor one tier; Japanese specialists hold another. The market structures around door-module integrators, standalone mechanism suppliers, and diversified automotive component houses. Three archetypes dominate: captive Tier-1 systems integrators, independent stamping specialists, and diversified global suppliers with multi-product automotive portfolios. Consolidation pressure manifests through door-module bundling and strategic partnerships for welding-lab certification.
Among diversified global suppliers, Bosch, Brose, and Valeo exemplify the integrated systems tier. These entities occupy positions spanning electric powertrain, door electronics, and mechanical linkage domains. Japanese specialists including Aisin Seiki and HI-LEX Corporation represent the precision-mechanism archetype with concentrated domestic OEM relationships. Grupo Antolin sits within the diversified component supplier category with broader interior-systems exposure. The competitive terrain rewards entities with parallel steel and aluminum production qualifications alongside embedded software validation capabilities.
| Leading Market Players |
|---|
| Bosch |
| Shiroki |
| Brose |
| Johnan Manufacturing Inc. |
| HI-LEX Corporation |
| Valeo |
| Aisin Seiki |
| F.tech Inc. |
| Grupo Antolin |
| Others |
Value Network & Pricing Analysis
Captive door-module integration anchors supply position and pricing power for Tier-1 suppliers bundling regulator, motor, and control electronics. This architectural consolidation compresses margins for standalone stampers while rewarding integrators with platform-award premiums and long-term contract visibility.
Pricing Analysis
Short lead-time premiums apply to brushless DC motor architectures specified by Stuttgart and Toyota City OEMs for 10-year warranty programs, while spot inventory discounts concentrate in aftermarket steel-grade mechanisms serving cost-sensitive repair channels. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant aluminum systems from trivalent-chrome steel variants and economy-grade manual mechanisms. Cost compression in stamped-steel arms intensifies because hot-rolled coil contract pricing resets lag spot-market spikes by 6-9 months. Aftermarket distributors exhibit highest price sensitivity; OEM platform engineers prioritize cycle-validation documentation over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Stuttgart, Detroit, and Toyota City final-assembly plants, while independent jobber networks distribute universal-fit mechanisms to Texas and Florida repair shops. Supply concentrates in Germany, Japan, and Mexico, with maquiladora operations near Nuevo León serving US-bound light-truck exports. Raw material dependencies center on Belgian and German caprolactam for polyamide bushings, European hot-rolled coil for stamped arms, and rare-earth magnets for brushless motor assemblies. Single-source vulnerability at Belgian chemical complexes propagates through window-lift lead times within 4-6 weeks. Distribution runs through door-module integrators capturing Tier-1 platform awards and aftermarket specialists with digitized inventory platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a vertical-integration race where motor-winding capabilities and welding-lab certifications determine who captures platform awards versus accepting Tier-2 stamping margins.
For Market Incumbents: Deepen captive production of brushless DC motors and friction-stir welding qualifications to defend against door-module bundlers absorbing standalone regulator suppliers. Invest in REACH-compliant finishing protocols at Baden-Württemberg facilities to sustain European OEM relationships. Control channel access through integrated shop-management platform partnerships that displace traditional jobber networks in US aftermarket. For New Entrants and Emerging Players: Brushless motor control algorithms offer a technology-first wedge into premium electric vehicle programs where ISO 26262 functional-safety validation creates certification barriers for mechanical-component houses. Target India's PLI scheme localization requirements for compact SUV platform awards previously sourced from ASEAN stampers. Pursue joint-venture structures with domestic OEMs to qualify for production-linked incentives in Tamil Nadu. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified automotive component houses seeking door-system integration capabilities. Long-term viability favors suppliers with parallel steel and aluminum qualifications alongside embedded software teams. Watch for brushless DC motor adoption inflection in mid-range vehicle segments as the signal that technology leadership is consolidating among integrated Tier-1s.| Strategic Initiative | Industry Significance |
|---|---|
| Door-Module Integration | Brose and Bosch bundle regulators with latch mechanisms to reduce OEM assembly-line labor content. |
| Brushless DC Motor Transition | Eliminates carbon-brush debris contamination, extending cycle durability for 10-year warranty programs. |
| REACH-Compliant Finishing | Trivalent chrome and zinc-nickel coatings defend European platform awards against hexavalent chromium restrictions. |
| India PLI Localization | Stampers with motor-winding capabilities capture platform awards for Maruti Suzuki compact SUV programs. |
| Aftermarket Digitization | Specialist distributors with real-time inventory displace jobber networks in US fleet maintenance channels. |
Research Methodology
Document review covered vehicle production databases, IHS Markit registration data, and SEC filings from diversified automotive suppliers, complemented by interviews with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership service operations. Secondary validation drew from ECHA REACH substance restrictions, EPA material-recovery mandates, and METI energy-efficiency guidelines. Bottom-up segment sizing triangulated against top-down OEM platform-award analysis.
Unit shipment and value projections across the analysis window applied segmentation by powertrain type, material substrate, procurement channel, and regional production cluster. CAGRs derived from regression analysis against vehicle production forecasts and content-per-vehicle assumptions for electric versus manual architectures. Model inputs included OEM door-module bundling trends, brushless DC motor penetration curves, and aluminum substitution rates in mid-range segments.
Several conditions sit outside the modeled scope, including force majeure events at Belgian caprolactam facilities, abrupt shifts in steel spot pricing, and regulatory acceleration of hexavalent chromium bans. Forecasts reflect assumptions about platform-award durations and warranty-period extensions that may revise under competitive or macroeconomic stress. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
United States Automotive Glass Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Automotive Wiper System Market
Automotive Parts
Industrial Roller Chain Drives Market
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
Global Automotive Flywheel Market
Automotive Parts
Automotive Performance Parts Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Asia Pacific Automotive Parts Die Casting Market
Automotive Parts
Global Intelligent All-Wheel Drive System Market