
 AC Electromagnetic Brakes Market | 2026-2036
AC Electromagnetic Brakes Market Size, Share, and Industry Trends Forecast 2026-2036
AC Electromagnetic Brakes Market Insights
Elevator and crane applications are consolidating as the dominant demand vertical for AC electromagnetic brakes, displacing traditional textile machinery placements. Altra Industrial Motion leverages its broad industrial automation portfolio to anchor North American supply relationships. Kendrion competes through specialized electromagnetic solutions for safety-critical lifting equipment. Ogura Clutch differentiates via compact brake designs tailored for Asian OEM machine builders.
AC electromagnetic brakes are electromechanical friction devices that engage or disengage rotating shafts through coil-energized magnetic fields, typically operating at voltages between 24V and 460V AC with torque ratings spanning fractional to several thousand newton-meters; they serve primarily as holding, stopping, or safety braking elements in industrial machinery. Spring Applied technology dominates installed base volumes due to its fail-safe engagement characteristic, while Disc configurations capture expanding share in precision positioning equipment where axial space constraints matter. Multiple-Face designs sustain premium positioning in high-torque crane and hoist applications where single-plate solutions prove inadequate.
FCC electromagnetic compatibility standards constrain coil design and switching circuit architectures for US-sourced equipment, while CE marking under the EU Machinery Directive mandates documented braking performance validation for European market access. China's GB standards through SAMR establish torque consistency testing protocols that shape product certification pathways for domestic and imported units. Stakeholders must monitor evolving efficiency regulations across multiple jurisdictions to align R&D investment with compliance-ready product architectures.
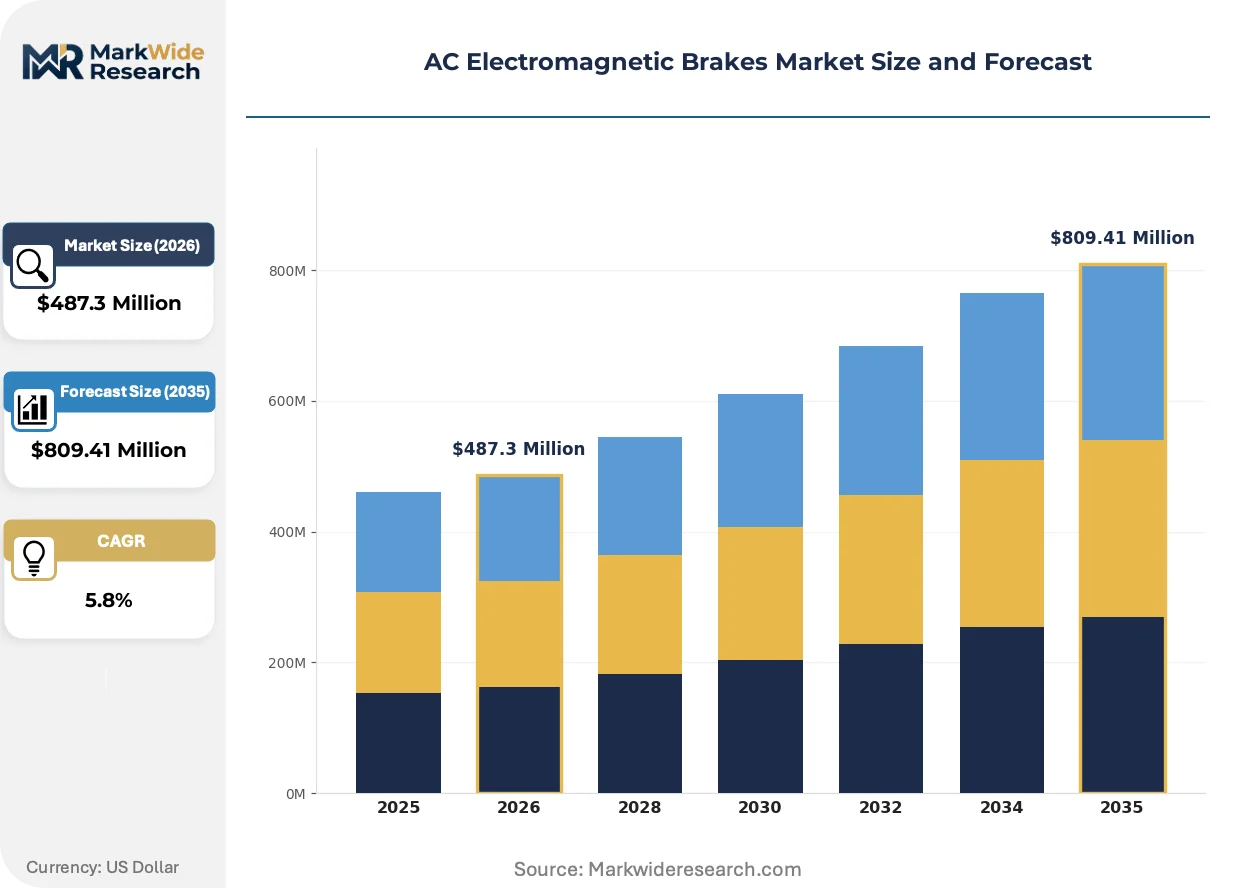
Market Dynamics
Spring-applied electromagnetic brake technology is consolidating its installed base dominance as fail-safe requirements harden across automated manufacturing and vertical transport systems. China's MIIT efficiency mandates for industrial motor systems are compressing product development cycles and forcing coil redesigns to meet stricter energy consumption thresholds.
Growth Catalysts
- Elevator Infrastructure Scaling:Urban vertical construction in Chinese megacities and Southeast Asian commercial hubs is generating sustained demand for precision holding brakes in traction machine systems.
- EU Machinery Directive CE Marking:Documented braking performance validation requirements are locking in technical specifications that favor established electromagnetic brake architectures over pneumatic alternatives.
- Industrial Motor Efficiency Standards:China's GB standards through SAMR are mandating torque consistency testing that accelerates replacement cycles in legacy factory automation equipment.
Market Restraints
- Copper and Rare Earth Input Volatility:Coil winding materials and permanent magnet components face price instability that compresses margin structures for brake assembly manufacturers.
- Supply Concentration in Precision Machining:Friction plate and hub manufacturing clusters in Germany and Japan create geographic vulnerability for non-integrated brake suppliers.
- Permanent Magnet Motor Substitution:Direct-drive motor systems with integrated holding functions are displacing separate electromagnetic brake units in low-torque precision positioning applications.
Strategic Opportunities
- Underpenetrated Indian Manufacturing Base:Domestic production incentives through the PLI scheme are attracting automated machinery investment that requires fail-safe braking systems for compliance.
- Regenerative Braking Convergence:Integration of electromagnetic friction brakes with energy recovery electronics is creating hybrid architectures for crane and hoist electrification projects.
- Digital Distribution Channels:Component marketplaces serving Asian OEM machine builders are compressing procurement cycles and enabling direct specification of compact brake designs.
Industry Challenges
- Electromagnetic Compatibility Certification:FCC standards for US-sourced equipment require extended validation timelines for coil switching circuit architectures that delay product launches.
- Legacy System Integration Complexity:Retrofit installations in aging European industrial infrastructure demand custom mounting adaptations that strain engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AC Electromagnetic Brakes Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring Applied, Power Applied, Hydraulically Released, Mechanically Released Technology: Single-Face, Multiple-Face, Drum, Disc, Friction Plate Application: Cranes, Textile Machinery, Printing Machines, Elevators, Packaging Equipment End User: OEMs, Aftermarket Suppliers, Industrial Machinery Builders, Maintenance Providers |
| Companies Covered | Altra Industrial Motion, Kendrion, Ogura Clutch, Mayr, KEB Automation, Miki Pulley, Precima Magnettechnik, OSAKI, Ortlinghaus Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AC Electromagnetic Brakes Market Trends and Innovations
Intelligent brake monitoring systems are penetrating safety-critical lifting equipment as real-time torque feedback becomes a specification requirement. Coil energization electronics and sensor integration are converging to enable predictive maintenance architectures.
Integrated torque sensing is automating condition monitoring in automated manufacturing lines. Automotive and aerospace component suppliers are adopting these systems at accelerating rates to satisfy unplanned downtime reduction targets. The technology is automating maintenance scheduling decisions that previously relied on calendar-based replacement intervals.
REACH substance restrictions on friction material formulations are forcing reformulation of brake pad compositions across European supply chains. Industrial consequences include extended qualification periods for new material certifications and elevated R&D expenditure for compliant architectures. Precision positioning equipment manufacturers in Germany are responding by accelerating supplier audits and dual-sourcing friction components.
Specification authority is migrating from maintenance departments to corporate procurement functions with centralized technical standards. Industrial distributors serving North American factory automation are losing influence to direct OEM relationships and consolidated national account structures. This concentration is most visible in elevator manufacturing where global procurement platforms now dictate brake performance specifications across multiple production facilities.
AC Electromagnetic Brakes Market Segmentation
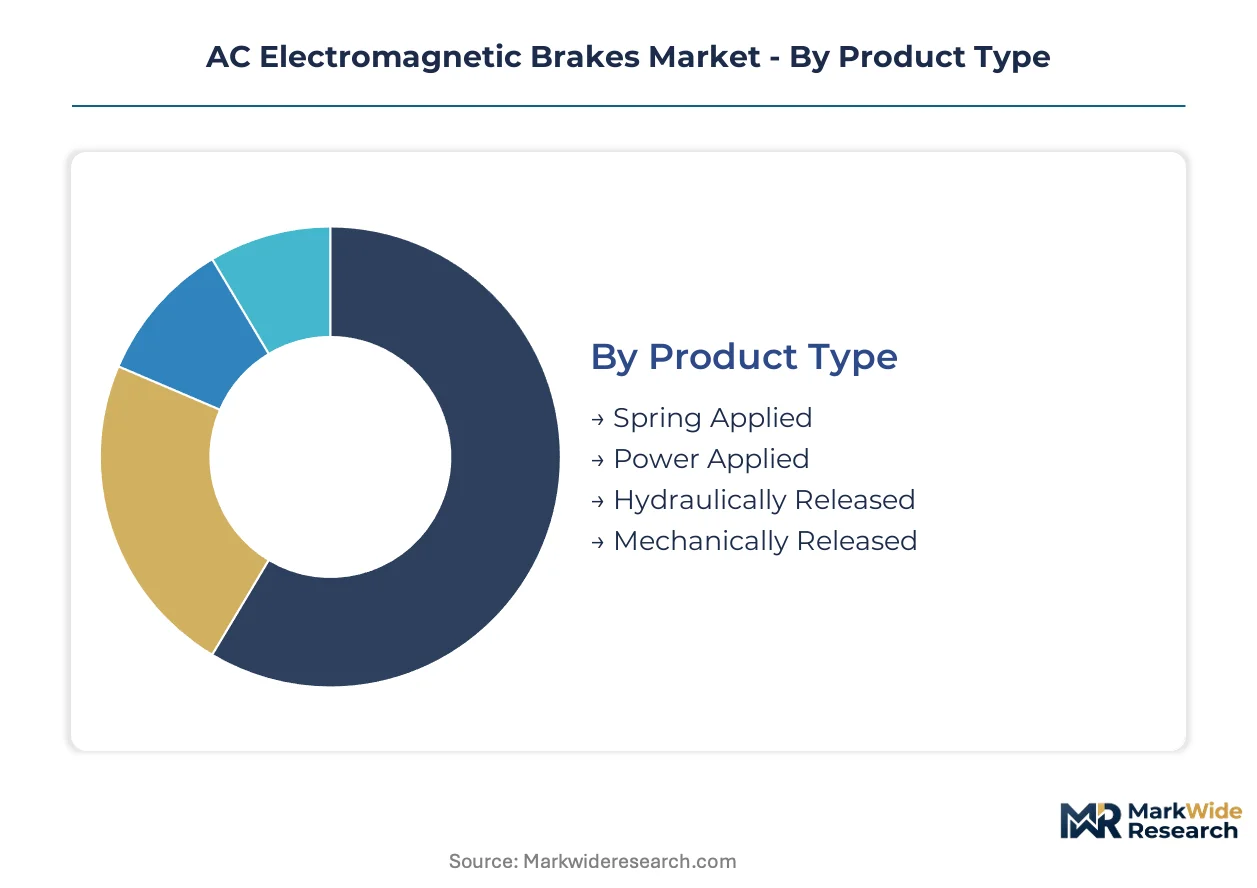
AC electromagnetic brake procurement patterns diverge sharply across technical architectures and customer types. Specification authority concentrates differently in safety-critical lifting equipment versus precision manufacturing systems, reshaping how suppliers configure product portfolios and channel strategies.
Product Type:
Volume deployment favors fail-safe mechanisms, while premium positioning attaches to specialized release configurations.
- Spring Applied:Coil-deenergized designs engage friction surfaces through mechanical spring force when power drops, ensuring automatic stopping in elevator traction machines and crane hoists. Chinese MIIT efficiency mandates are accelerating coil redesigns to reduce holding current consumption in these high-volume installations.
- Power Applied:Magnetic force directly compresses friction elements when energized, suited for controlled cycling in printing presses and packaging lines where intentional slip is operationally necessary. German automated manufacturing clusters specify these for precision torque modulation in indexing applications.
- Hydraulically Released:Fluid pressure overcomes spring force for controlled disengagement in heavy-lift port cranes. Demand concentrates in Chinese and Southeast Asian port infrastructure expansion.
- Mechanically Released:Manual or linkage-actuated release supports maintenance override functions. Maintenance providers in aging European industrial bases specify these for retrofit compatibility.
Mature deployment sits with Spring Applied. Newer deployment is concentrated in Hydraulically Released configurations for electrified heavy-lift systems.
Technology:
Axial space constraints and torque density requirements fragment technical adoption across equipment categories.
- Multiple-Face:Stacked friction surfaces multiply torque output within constrained diameters, essential for overhead crane bridge drives and mine hoist drums. Japanese precision equipment manufacturers specify these where single-plate solutions prove dimensionally inadequate.
- Disc:Flat friction geometry enables thin-profile integration in servo motor brake modules and robotic joint actuators. Indian PLI-scheme manufacturing investments are expanding specification volume for compact automated machinery.
- Single-Face:Simplified architecture dominates cost-sensitive textile machinery replacements in Southeast Asian production facilities.
- Drum:Cylindrical friction surfaces suit legacy industrial motor retrofits in Eastern European manufacturing plants.
- Friction Plate:Modular wear-component design supports maintenance-provider procurement in North American distribution channels.
Multiple-Face configurations dominate premium crane specifications. Disc technology is climbing the fastest in precision positioning equipment where envelope constraints tighten.
Application:
Safety regulation intensity and automation penetration create divergent growth trajectories across end-equipment types.
- Elevators:Traction machine holding brakes must satisfy CE marking under the EU Machinery Directive and China's GB standards through SAMR, locking in electromagnetic architectures over pneumatic alternatives. Urban vertical construction in Chinese megacities sustains specification volume.
- Cranes:Overhead, gantry, and port crane systems require documented braking performance validation for operator safety compliance. REACH substance restrictions on friction materials are extending qualification timelines for European-sourced equipment.
- Packaging Equipment:High-cycle indexing drives specify power-applied designs for controlled acceleration profiles. North American food and beverage automation investments are expanding demand.
- Printing Machines:Web tension control applications specify precise torque modulation. Japanese commercial printing equipment manufacturers anchor regional specification authority.
- Textile Machinery:Traditional loom and spinning frame applications face displacement by integrated servo systems in high-wage manufacturing economies.
Elevator applications command the steepest expansion trajectory. Textile machinery placements are contracting in advanced manufacturing regions.
End User:
Procurement centralization and technical specification authority are migrating toward consolidated purchasing functions.
- OEMs:Original equipment manufacturers in elevator and crane production specify brake performance across global production platforms, compressing supplier diversity. Altra Industrial Motion and Kendrion anchor North American and European supply relationships respectively.
- Industrial Machinery Builders:Asian OEM machine builders in China and India specify compact brake designs through digital distribution channels, bypassing traditional industrial distributors.
- Aftermarket Suppliers:Replacement brake procurement serves aging European and North American installed bases. REACH-compliant friction material sourcing is elevating R&D expenditure for these channels.
- Maintenance Providers:Calendar-based replacement intervals are yielding to predictive maintenance architectures with integrated torque sensing, automating procurement timing decisions.
Specification authority concentrates with OEMs. Direct procurement from Industrial Machinery Builders is gaining share fastest in Asian manufacturing expansion zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate AC electromagnetic brake fabrication, drawing component suppliers into clustered manufacturing corridors. German precision machining districts anchor European supply security for friction plate subsystems. Japanese industrial automation corridors sustain premium specification authority for servo-integrated brake modules.
China
Elevator traction machine demand from Shanghai and Shenzhen construction projects sustains brake procurement volume. MIIT efficiency mandates for industrial motor systems compress product development cycles for coil redesigns. Yangtze River Delta manufacturing clusters host concentrated brake assembly operations serving domestic OEMs.
Germany
Automated manufacturing investments in Bavaria and Baden-Württemberg specify precision positioning brakes for robotic integration. CE marking under the EU Machinery Directive mandates documented braking performance validation. Stuttgart industrial automation corridor anchors specification authority for European machine builders.
Japan
Commercial printing equipment manufacturers in Tokyo and Osaka drive demand for torque-modulation brake systems. METI industrial efficiency guidelines shape product certification pathways for domestic and export markets. Nagoya precision equipment district concentrates multiple-face brake fabrication for crane applications.
United States
Food and beverage automation investments across Midwest manufacturing states expand power-applied brake specifications. FCC electromagnetic compatibility standards constrain coil design architectures for industrial equipment. Great Lakes industrial corridor sustains aftermarket replacement demand from aging installed bases.
India
Domestic machinery production incentives through the PLI scheme attract automated equipment investment requiring fail-safe braking. BIS torque consistency testing protocols shape product certification for imported and locally manufactured units. Gujarat and Maharashtra industrial zones concentrate emerging brake specification volume from OEM machine builders.
AC Electromagnetic Brakes Market Competitive Landscape
Top-tier vendors anchor consolidated supply relationships with multinational elevator and crane OEMs, while mid-tier specialists occupy niche precision positioning segments. The vendor base stratifies across three strategic archetypes: broad industrial automation portfolio holders, electromagnetic component specialists, and compact design innovators targeting Asian OEM channels. Competitive positioning hardens through backward integration into friction material supply and direct specification relationships that bypass traditional distribution.
Within the specialist tier, Kendrion and Ogura Clutch exemplify divergent geographic anchoring strategies, while Altra Industrial Motion occupies a position representing broad portfolio consolidation. These three names illustrate how competitive positioning fragments across European precision engineering, Japanese compact design heritage, and North American industrial automation integration. Each represents an archetype rather than a definitive market share claim, with their collective presence indicating where specification authority concentrates across regional manufacturing corridors.
| Leading Market Players |
|---|
| Altra Industrial Motion |
| Kendrion |
| Ogura Clutch |
| Mayr |
| KEB Automation |
| Miki Pulley |
| Precima Magnettechnik |
| OSAKI |
| Ortlinghaus Group |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up industrial automation specialists anchor supply relationships that compress procurement cycles for elevator OEMs while enforcing pricing discipline on friction material inputs. This ownership pattern concentrates specification authority with consolidated national accounts that demand volume-scaled contract terms from coil winding and precision machining suppliers.
Pricing Analysis
Premium pricing attaches to sub-four-week lead times for spring-applied brake modules serving Chinese elevator traction machine manufacturers, while spot inventory in Southeast Asian distribution channels trades at discounted levels. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked precision positioning units from general industrial grades and cost-optimized textile machinery replacements. Pricing pressure stems from copper and rare earth input volatility that compresses margin structures for non-integrated brake assembly manufacturers. Aftermarket maintenance providers exhibit the highest price sensitivity, while global elevator OEMs with consolidated procurement platforms demonstrate the least.
Supply Chain Analysis
Copper coil winding supply rests on Chinese and German specialty wire producers, while friction plate manufacturing clusters concentrate in Japan and Bavarian precision machining districts. Permanent magnet components for power-applied designs draw from Chinese rare earth processing facilities and Japanese sintered magnet specialists. Single-source vulnerability in precision-ground friction surfaces creates geographic risk for brake suppliers lacking backward integration into hub manufacturing. Distribution runs through direct OEM relationships for elevator and crane producers, bypassing traditional industrial distributors in North American and European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from China's MIIT efficiency mandates and REACH substance restrictions is forcing smaller brake specialists into distressed positioning, creating acquisition opportunities for integrated industrial automation portfolios.
For Market Incumbents: Extend specification authority through captive friction material supply and in-house coil winding capacity in Yangtze River Delta manufacturing corridors. Permanent magnet motor substitution in low-torque positioning applications threatens standalone brake unit demand, requiring accelerated R&D investment in integrated torque sensing architectures. CE marking documentation and SAMR certification pathways serve as defensive moats against mid-tier competitors lacking compliance infrastructure. For New Entrants and Emerging Players: Asian OEM machine builders in Gujarat and Maharashtra industrial zones represent the most penetrable demand channel, bypassing established distributor relationships through digital procurement platforms. Compact disc brake designs for Indian PLI-scheme automated machinery investments offer specification entry points against entrenched European suppliers. Direct technical engagement with elevator component sourcing teams in Shenzhen and Shanghai accelerates qualification timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap electromagnetic component specialists with SAMR-certified product lines and established relationships with Chinese elevator OEMs. Five-to-ten-year viability hinges on backward integration into friction material supply and regenerative braking hybrid architectures. The signal to watch is MIIT efficiency mandate acceleration forcing coil redesign expenditure that strains undercapitalized competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Friction Material Supply | REACH-compliant pad formulations reduce European qualification timelines for crane OEMs. |
| Coil Redesign for MIIT Efficiency Compliance | Holding current reduction meets Chinese industrial motor system mandates in elevator applications. |
| Integrated Torque Sensing Development | Predictive maintenance architectures automate procurement timing for maintenance providers. |
| Direct OEM Relationship Expansion | Bypassing distributors captures specification authority in consolidated national accounts. |
| Regenerative Braking Hybrid Architectures | Energy recovery electronics convergence serves crane and hoist electrification projects. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with elevator procurement directors, crane OEM specification engineers, industrial maintenance providers, and friction material R&D leads. MIIT efficiency mandate documentation, SAMR torque consistency testing protocols, CE marking validation records, and FCC electromagnetic compatibility filings provided regulatory pathway validation. Bottom-up demand modeling across application segments triangulated against top-down industrial automation investment tracking.
Data-stream reconciliation across shipment volumes, installed base replacement cycles, and OEM specification databases generated consistent trajectory outputs across the analysis window. Segmentation modeling incorporated product type, technology architecture, application intensity, and end-user procurement centralization patterns. CAGRs derived from weighted average of historical replacement demand, regulatory-driven upgrade cycles, and emerging market machinery investment intensity. Coil energization efficiency trends and friction material qualification timelines served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt rare earth export restrictions, sudden tariff regime shifts on precision-machined components, and breakthrough permanent magnet motor displacement in mid-torque applications. Forecasts reflect documented assumptions regarding regulatory implementation timelines and OEM procurement consolidation trajectories. A small set of named triggers warrants ongoing watch: MIIT mandate acceleration, REACH substance restriction expansion, and Indian PLI scheme machinery investment disbursement rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Windshield Washer System Market
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
Air Filter Cartridges Market
Automotive Parts
Automotive Remanufactured Parts Market
Automotive Parts
RV Gear Reducer Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Global Windshield Wiper Blades Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market