
 Insert Drive for Torque Wrench Market | 2026-2036
Insert Drive for Torque Wrench Market Size, Share, and Industry Trends Forecast 2026-2036
Insert Drive for Torque Wrench Market Insights
Precision-grade calibration is rotating demand toward higher-specification insert drives as manufacturers reject tolerance drift in critical assemblies. Atlas Copco AB leverages its pneumatic tool ecosystem to dominate industrial channel access. Snap-on Incorporated anchors its position through proprietary drive geometry patents and mobile technician loyalty programs. Norbar Torque Tools specializes in ultra-heavy duty configurations for subsea and energy infrastructure.
An insert drive for torque wrench is the interchangeable square or hexagonal output head that mates with sockets and adapters, typically manufactured from chrome-molybdenum or chrome-vanadium steel through drop forging and CNC hardening to achieve Rockwell hardness ratings of 58-62 HRC; its primary purpose is to transmit calibrated rotational force to threaded fasteners in controlled-torque applications. Digital torque wrenches command premium positioning due to data-logging requirements in aerospace compliance chains, while hydraulic variants capture margin pools in oil and gas field bolting where pneumatic power proves unreliable. Compact sizes face commoditization pressure from Asian manufacturing entrants, whereas heavy duty segments sustain pricing power through metallurgical certification barriers.
ISO 6789 calibration mandates and FAA airworthiness directives for traceable fastening records are elevating replacement cycles and documentation requirements across North American and European maintenance operations. Germany's KBA and France's ANSM enforce tool-certification protocols that restrict market access for uncertified imports. Stakeholders must monitor evolving dual-carbon material standards and battery-electric vehicle assembly torque specifications as these will redefine drive-head durability benchmarks and dimensional requirements.
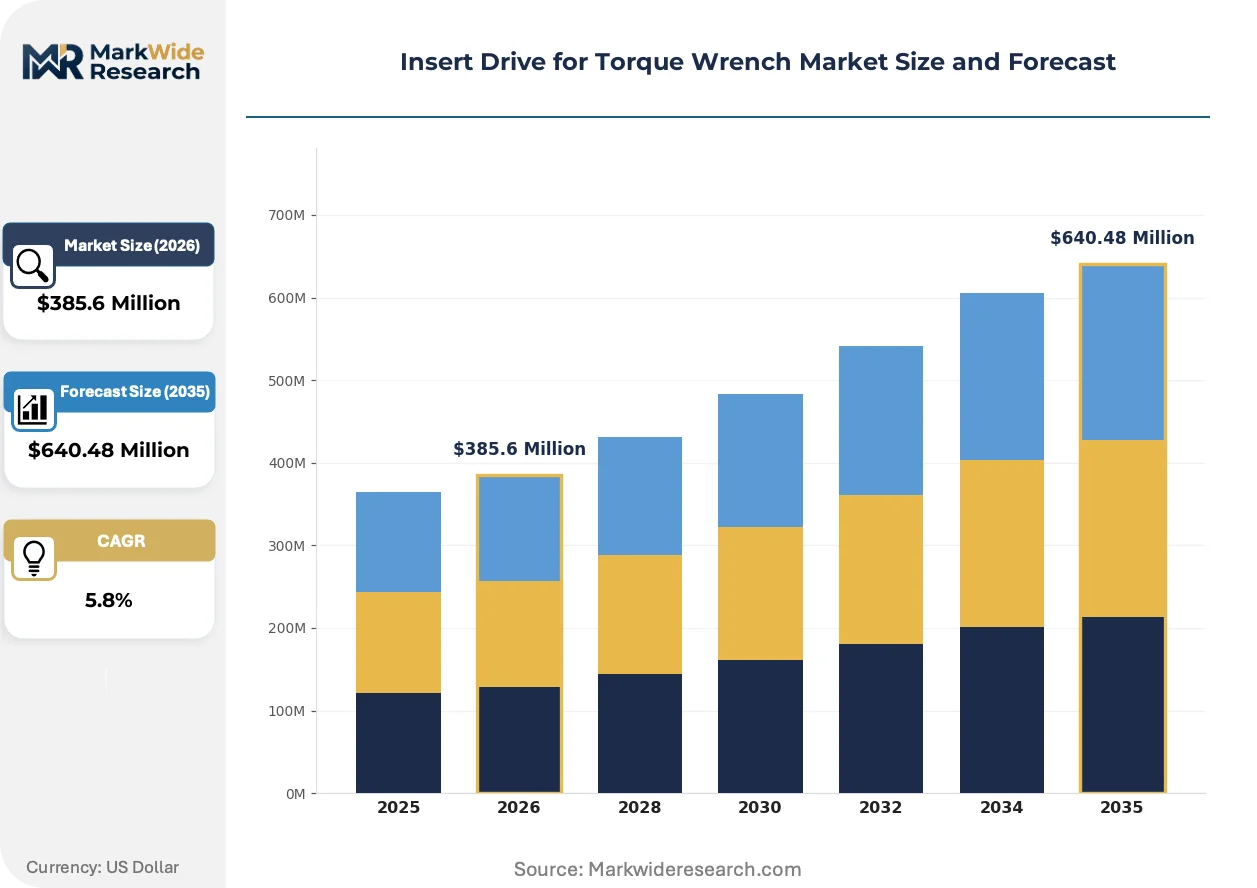
Market Dynamics
ISO 6789 traceability mandates are compressing replacement cycles and forcing documentation infrastructure upgrades across maintenance operations, while aerospace assembly expansion in North America pulls precision-grade inventory through calibrated distribution channels.
Growth Catalysts
- FAA airworthiness directives:Traceable fastening records for commercial aviation maintenance operations mandate calibrated tool replacement, elevating demand for certified insert drives in US MRO facilities.
- Battery-electric vehicle assembly:New torque specifications for aluminum-intensive chassis and battery pack enclosures require higher-precision fastening protocols across Germany's automotive manufacturing corridor.
- Subsea energy infrastructure:Ultra-heavy duty configurations for offshore wind turbine foundation bolting create specification pull through corrosion-resistant metallurgical grades.
Market Restraints
- Chrome-vanadium steel price volatility:Alloy input cost swings compress margin pools for drop-forged drive head manufacturers without captive metallurgical supply.
- Asian manufacturing concentration:Compact-size commoditization pressure from uncertified imports restricts pricing power in economy-tier segments lacking ISO 6789 documentation.
- Hydraulic torque wrench substitution:Pneumatic power unreliability in remote oil field environments drives bolt tensioner adoption, displacing conventional socket-and-drive configurations in specific energy applications.
Strategic Opportunities
- India automotive component manufacturing:BIS certification requirements and PLI scheme incentives for precision tool localization create channel access for documented calibration service providers.
- Digital torque wrench convergence:Bluetooth-enabled data logging integrated with MES platforms enables predictive maintenance contracts and recurring software revenue attachment.
- EU Green Deal circularity mandates:Remanufacturing and recalibration service models gain regulatory preference over disposable tool replacement in French and German industrial procurement frameworks.
Industry Challenges
- Metallurgical certification timelines:Rockwell hardness verification and batch traceability documentation extend production lead times for aerospace-qualified drive heads.
- Legacy tool integration:Digital torque wrench retrofit compatibility with existing socket inventories requires dimensional standardization negotiation across multi-brand maintenance fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insert Drive for Torque Wrench Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Torque Wrenches, Digital Torque Wrenches, Pneumatic Torque Wrenches, Hydraulic Torque Wrenches Application: Aerospace, Automotive Manufacturing, Construction, Oil & Gas Size: Compact, Standard, Heavy Duty, Ultra-Heavy Duty End User: Manufacturers, Maintenance Providers, DIY Enthusiasts, Retailers |
| Companies Covered | Atlas Copco AB, Apex Tool Group, Stanley Black & Decker, Robert Bosch GmbH, Ingersoll Rand, Desoutter Industrial Tools, Snap-on Incorporated, Mountz, Norbar Torque Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insert Drive for Torque Wrench Market Trends and Innovations
Active materials substitution and compliance architecture evolution are reconfiguring specification hierarchies, while procurement centralization in tier-one manufacturing concentrates demand around integrated calibration-service bundles.
Composite-reinforced drive heads are supplanting conventional chrome-molybdenum configurations in aerospace line assembly applications where weight reduction intersects with fatigue resistance requirements. Boeing and Airbus tier suppliers are piloting carbon-fiber hybrid inserts for wing-skin fastening stations. This material transition is compressing traditional metal-forging capacity utilization while opening premium pricing tiers for certified composite manufacturing.
EU F-Gas Regulation phase-down schedules are accelerating pneumatic tool replacement with electric torque wrench platforms in European automotive plants, forcing insert drive geometry adaptation for brushless motor torque curves. Germany's KBA enforces tool-certification protocols that restrict market access for imports lacking CE-marked calibration documentation. French ANSM-aligned maintenance operations are consolidating supplier lists around dual-certified calibration houses.
Buyer consolidation through integrated MRO procurement platforms is displacing distributor-fragmented purchasing in North American commercial aviation. Airlines now mandate single-source calibration accountability across hub-and-spoke maintenance networks. This channel compression is most visible in US Southeast aerospace clusters where Delta and American Airlines have centralized tooling contracts around FAA-registered calibration providers.
Insert Drive for Torque Wrench Market Segmentation
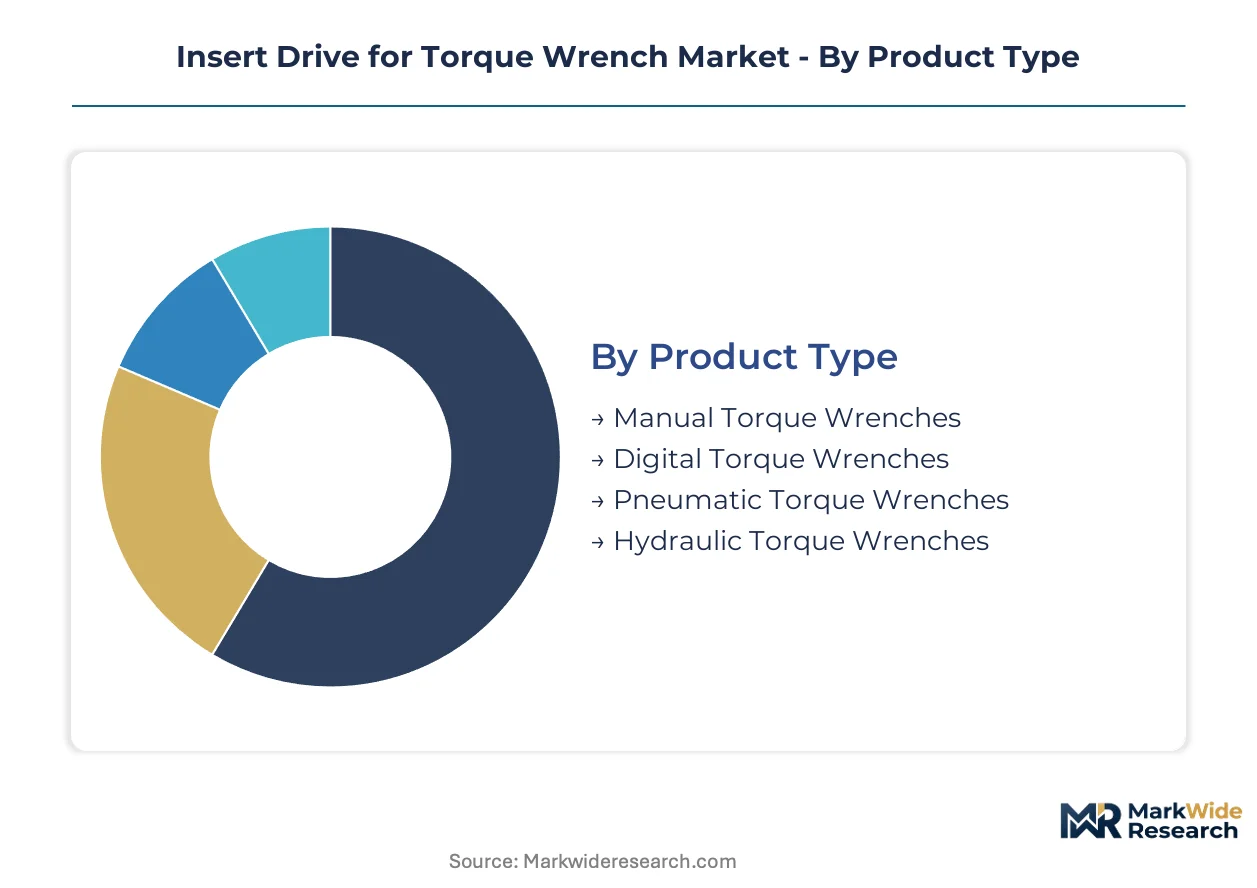
Segmentation in the insert drive market reflects divergent pressure from substitute technologies and certification requirements. Each dimension captures distinct procurement logic across aerospace compliance chains, automotive volume manufacturing, and energy infrastructure specifications.
Product Type:
Hydraulic torque wrench configurations face the strongest substitution threat from bolt tensioner systems in offshore environments, reshaping investment priorities across pneumatic and electric alternatives.
- Manual Torque Wrenches:Mechanical click-type and beam-style mechanisms dominate MRO toolboxes where portability outweighs data-logging needs. Demand concentrates in Germany's KBA-certified automotive service networks facing ISO 6789 recalibration mandates that compress replacement cycles.
- Digital Torque Wrenches:Strain-gauge sensors with Bluetooth MES integration command premium positioning in FAA-traceable aerospace fastening operations. US Southeast maintenance hubs for Delta and American Airlines mandate single-source calibration accountability through these platforms.
- Pneumatic Torque Wrenches:Air-motor driven units retain cost advantages in high-volume assembly lines despite EU F-Gas Regulation phase-down pressures.
- Hydraulic Torque Wrenches:Ultra-high torque output for subsea wind foundation bolting competes directly with bolt tensioners in corrosion-resistant specification tiers.
Manual configurations retain volume leadership; digital platforms hold the steepest expansion curve.
Application:
Margin concentration follows certification intensity, with aerospace and oil & gas commanding metallurgical documentation premiums over construction commodity tiers.
- Aerospace:Wing-skin and landing-gear fastening stations require Rockwell 58-62 HRC certified drive heads with batch traceability documentation. Boeing and Airbus tier suppliers in the US Southeast and Germany's manufacturing corridor drive specification pull through FAA and EASA compliance chains.
- Automotive Manufacturing:Battery-electric vehicle aluminum chassis assembly demands higher-precision torque protocols across Germany's automotive corridor, with new specifications for battery pack enclosure fastening.
- Construction:Structural steel bolting applications face price compression from uncertified imports lacking ISO 6789 documentation.
- Oil & Gas:Remote field environments drive hydraulic substitution where pneumatic reliability fails, constraining conventional socket-and-drive adoption.
Automotive manufacturing anchors volume scale; aerospace captures the premium pricing tier.
Size:
Metallurgical certification barriers stratify competitive intensity, with heavy-duty segments sustaining pricing power against commoditized compact alternatives.
- Compact:1/4-inch and 3/8-inch drive heads for electronics and light assembly face severe commoditization from Asian manufacturing entrants lacking CE-marked calibration documentation.
- Standard:1/2-inch drive configurations dominate general industrial maintenance with established dimensional standards.
- Heavy Duty:3/4-inch and 1-inch forged chrome-molybdenum heads for industrial machinery assembly sustain margin pools through drop-forging capacity constraints and hardness verification protocols.
- Ultra-Heavy Duty:1.5-inch and larger drives for offshore wind turbine foundation bolting require corrosion-resistant grades with extended batch traceability, creating specification moats around certified European forges.
Standard sizes retain volume leadership; ultra-heavy duty configurations hold the steepest expansion curve.
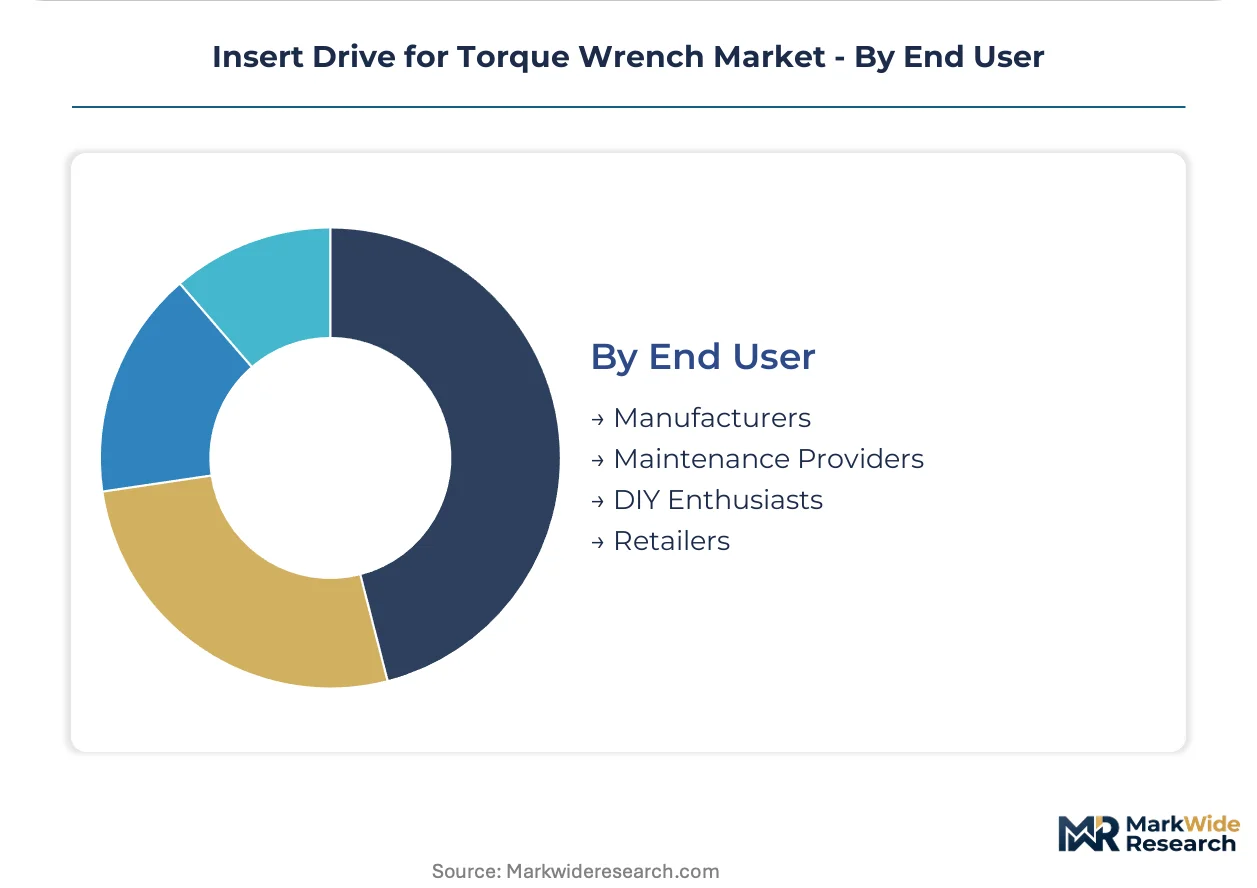
End User:
Procurement centralization through integrated MRO platforms is fragmenting traditional distributor relationships while concentrating demand around calibration-service bundles.
- Manufacturers:Tier-one automotive and aerospace OEMs mandate dual-certified calibration houses with CE-marked and FAA-registered documentation, consolidating supplier lists in France's ANSM-aligned operations.
- Maintenance Providers:Hub-and-spoke airline networks in the US Southeast have centralized tooling contracts around single-source calibration accountability, displacing fragmented distributor purchasing.
- DIY Enthusiasts:Price-sensitive retail channels absorb compact-size commoditization pressure from uncertified imports.
- Retailers:Big-box and industrial supply distributors face margin compression as manufacturers bypass channels for direct calibration-service relationships.
Maintenance providers retain volume leadership; manufacturers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows favor established manufacturing bases with captive metallurgical supply chains over emerging assembly operations dependent on imported certified drive heads. The United States maintains a structural deficit in precision-grade aerospace-qualified units, sourcing from German and Swedish forges while exporting commodity compact sizes to Latin American maintenance markets.
United States
FAA airworthiness directives for traceable fastening records drive replacement demand across Delta and American Airlines maintenance hubs in the US Southeast. The country's national aviation regulator enforces single-source calibration accountability through hub-and-spoke networks. Boeing tier suppliers in Seattle and Charleston concentrate specification pull for Rockwell-certified drive heads with batch traceability documentation.
Germany
Battery-electric vehicle assembly lines for aluminum-intensive chassis require higher-precision torque protocols across the automotive manufacturing corridor. The KBA enforces tool-certification protocols that restrict market access for imports lacking CE-marked calibration documentation. Stuttgart and Munich industrial clusters anchor demand for ISO 6789-traceable insert drives through BMW and Mercedes-Benz assembly operations.
China
Domestic automotive component manufacturing scales precision tool localization under national industrial policy incentives. The country's national standardization administration enforces GB standards for torque tool certification that parallel ISO 6789 requirements. Yangtze River Delta fabrication centers in Shanghai and Suzhou concentrate compact-size production for export to Southeast Asian maintenance markets.
India
Automotive component manufacturing expansion under the PLI scheme creates channel access for documented calibration service providers. The Bureau of Indian Standards mandates BIS certification requirements for precision tool imports that elevate entry barriers. Tamil Nadu and Maharashtra industrial corridors concentrate demand from Maruti Suzuki and Tata Motors assembly operations seeking localized supply chains.
Japan
Aerospace subcontractor networks for Boeing and Airbus programs sustain demand for ultra-heavy duty configurations with extended batch traceability. The Ministry of Economy, Trade and Industry oversees JIS standards alignment with ISO 6789 for export-qualified production. Nagoya and Osaka manufacturing basins concentrate precision forging capacity for corrosion-resistant metallurgical grades serving subsea energy applications.
Insert Drive for Torque Wrench Market Competitive Landscape
Concentration sits with diversified industrial tool conglomerates possessing captive distribution networks and proprietary calibration service infrastructures. The vendor base stratifies across three tiers: premium specialists holding aerospace certification moats, mid-scale industrial manufacturers serving automotive volume contracts, and price-competitive fabricators supplying compact sizes to retail channels. Two dominant competitive moves define current positioning: backward integration into drop-forging capacity to secure metallurgical certification timelines, and geographic expansion through FAA-registered calibration houses in US Southeast aerospace clusters.
Within the premium specialist tier, Norbar Torque Tools and Snap-on Incorporated exemplify archetypes built on proprietary drive geometry and mobile technician loyalty programs. Among diversified industrial conglomerates, Atlas Copco AB and Stanley Black & Decker occupy positions anchored by pneumatic tool ecosystem dominance and multi-brand portfolio breadth. Robert Bosch GmbH represents the precision manufacturing archetype with electric platform integration capabilities. These groupings illustrate how certification documentation, distribution density, and metallurgical process control separate sustainable margin pools from commoditized compact-size competition.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Apex Tool Group |
| Stanley Black & Decker |
| Robert Bosch GmbH |
| Ingersoll Rand |
| Desoutter Industrial Tools |
| Snap-on Incorporated |
| Mountz |
| Norbar Torque Tools |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day lead times for aerospace-qualified drive heads concentrate pricing power with German and Swedish forges possessing captive drop-forging capacity, while compact-size inventory cycles below thirty days expose Asian manufacturers to margin compression from uncertified imports lacking ISO 6789 documentation.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, where FAA-registered calibration documentation and Rockwell hardness certification drive price differentiation between aerospace-grade and construction-tier segments. Pricing pressure stems from Asian manufacturing entrants flooding compact-size channels with uncertified 1/4-inch and 3/8-inch drives lacking CE-marked documentation. DIY enthusiasts and retail distributors exhibit highest price sensitivity, whereas maintenance providers in US Southeast aerospace clusters accept premium positioning for single-source calibration accountability.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes amplify inbound logistics costs for chrome-vanadium and chrome-molybdenum alloy inputs sourced from Chinese and Indian metallurgical suppliers. Manufacturing gravity centers on Germany, Sweden, and Japan, where batch traceability documentation and hardness verification protocols feed from specialized forging capacity. Single-source vulnerability concentrates in corrosion-resistant grades for ultra-heavy duty configurations. Distribution runs through calibrated industrial distributors and direct OEM procurement channels bypassing fragmented retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity because predictive maintenance contracts and recalibration service models expand faster than hardware unit sales, particularly where FAA and KBA mandates compress replacement cycles.
For Market Incumbents: Shield aerospace certification moats through backward integration into drop-forging capacity, securing metallurgical supply chains against chrome-vanadium price volatility while consolidating FAA-registered calibration house networks in US Southeast clusters to defend against bolt tensioner substitution in offshore energy applications. For New Entrants and Emerging Players: Differentiate on Bluetooth-enabled data logging platforms integrated with MES systems, targeting India's PLI-scheme automotive component corridors where BIS certification requirements create white-space for documented calibration service providers lacking established presence in Maruti Suzuki and Tata Motors supply chains. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because ISO 6789 traceability mandates and FAA airworthiness directives structurally elevate replacement demand and documentation requirements across maintenance operations, with acquisition value concentrating in dual-certified calibration houses possessing CE-marked and FAA-registered documentation; watch for EU Green Deal circularity mandates accelerating remanufacturing service model adoption as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drop-Forging Capacity | Captive metallurgical supply secures Rockwell certification timelines against alloy price volatility. |
| FAA-Registered Calibration House Expansion | US Southeast aerospace clusters demand single-source accountability through Delta and American Airlines networks. |
| Bluetooth MES Platform Integration | Digital torque wrench convergence enables predictive maintenance contracts with recurring software revenue. |
| Composite-Reinforced Drive Head Development | Boeing and Airbus tier suppliers pilot carbon-fiber hybrid inserts for wing-skin fastening weight reduction. |
| India PLI Localization Partnership | BIS certification requirements and automotive component incentives create channel access for documented providers. |
Research Methodology
Cross-validation between maintenance director interviews at US Southeast airline hubs and OEM procurement data from Germany's automotive corridor anchors the qualitative findings, with secondary validation drawing from FAA airworthiness directives, KBA tool-certification protocols, SEC filings of diversified industrial tool conglomerates, and ISO 6789 calibration standards. Bottom-up demand modeling across manual, digital, pneumatic, and hydraulic torque wrench configurations triangulates with top-down metallurgical capacity assessments.
Sensitivity analysis spans the projection horizon across product type, application intensity, size classification, and end-user procurement centralization dimensions. CAGRs derive from segmented unit economics and replacement cycle compression observed under traceability mandates. Forecast inputs incorporate battery-electric vehicle assembly torque specifications and subsea wind foundation bolting demand curves.
The analysis sits within stated boundaries; outcomes outside sustained aerospace assembly expansion and continued ISO 6789 enforcement would require recalibration. Forecasts reflect documented assumptions regarding alloy input cost trajectories and certification timeline stability. Practitioners should keep alternative scenarios live as EU F-Gas Regulation phase-down schedules and dual-carbon material standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market
Automotive Parts
Needle Roller Bearings Market
Automotive Parts
Two Speed Gearbox Market
Automotive Parts
Singapore Automotive Engine Oils Market
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
Global Automotive Ignition Market
Automotive Parts
Windshield Washer Fluid Market
Automotive Parts
High Level Brake Lamp Market
Automotive Parts
Automotive Ignition Coil Market
Automotive Parts
North America Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
Russia Automotive Hydraulic Actuators Market
Automotive Parts
Malaysia Brake Pads Market
Automotive Parts
North America Passenger Vehicles Lubricants Market