
 Car Polisher Market | 2026-2036
Car Polisher Market Size, Share, and Industry Trends Forecast 2026-2036
Car Polisher Market Analysis
Mobile detailing services is pivoting toward cordless equipment fleets, reshaping procurement patterns across the supply chain. TORQ Tool Company leverages direct-to-consumer channels to capture DIY enthusiast spending. Meguiar's, Inc. sustains brand authority through professional training certifications. Bosch dominates cordless motor technology, extending its power-tool ecosystem into automotive finishing.
A car polisher is a rotary, orbital, or dual-action machine that spins a foam or wool pad at controlled speeds to abrade clear coat microscopically and restore gloss. The device operates between 600 and 3,000 RPM depending on pad diameter and paint hardness, with forced-rotation mechanisms now standard for defect removal. Dual action polishers lead consumer adoption due to lower swirl risk, while rotary units retain professional share for severe correction. Cordless power source segments are gaining fastest as lithium-ion energy density improves runtime to match corded equivalents. Professional detailers command the highest tool replacement frequency, creating durable recurring revenue for manufacturers serving fleet operators.
OSHA guidelines on workplace vibration exposure shape ergonomic design requirements for daily-use equipment in the United States. The EPA oversees volatile organic compound limits in polishing compounds, pushing reformulation toward water-based carriers. ISO 5349 vibration measurement standards influence product testing protocols for international distribution. Stakeholders must monitor battery chemistry substitution timelines as cobalt supply constraints alter cordless platform economics.
Market Dynamics
Cordless lithium-ion platforms are rewriting procurement logic across mobile detailing fleets, compressing replacement cycles as runtime parity with corded units eliminates operational trade-offs.
Growth Catalysts
- Ceramic Coating Prep Protocols:Professional shops in the United States face tightening surface preparation standards that demand higher-precision defect removal, accelerating tool refresh rates among fleet operators.
- OSHA Vibration Guidelines:Workplace exposure limits for hand-arm vibration syndrome are forcing ergonomic redesigns that differentiate compliant equipment from commodity alternatives.
- Lithium-Ion Energy Density Gains:Cell chemistry improvements are extending cordless runtime to match corded equivalents, eliminating the primary barrier to fleet electrification.
Market Restraints
- Cobalt Supply Concentration:Battery cathode chemistry relies on supply chains concentrated in Central African mining regions, exposing cordless platform economics to geopolitical disruption and price volatility.
- EPA VOC Limits:Polishing compound reformulation toward water-based carriers increases manufacturing complexity and extends product development timelines for compound suppliers.
- Paint Hardness Variability:Clear coat formulations differ across OEM specifications, limiting universal pad-and-speed recommendations and complicating training standardization.
Strategic Opportunities
- DIY Enthusiast Channel Expansion:Direct-to-consumer platforms are capturing spending from amateur detailers seeking professional-grade results without shop labor costs.
- Training Certification Ecosystems:Branded education programs create switching costs and recurring revenue streams through consumable tie-ins and equipment upgrades.
- Dual-Action Safety Positioning:Lower swirl-risk mechanics are penetrating consumer segments previously intimidated by rotary learning curves.
Industry Challenges
- Skill Transfer Bottlenecks:Rotary technique mastery requires months of supervised practice, constraining workforce scalability for high-volume correction shops.
- ISO 5349 Testing Burden:Vibration measurement compliance for international distribution adds certification costs and delays product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Polisher Market |
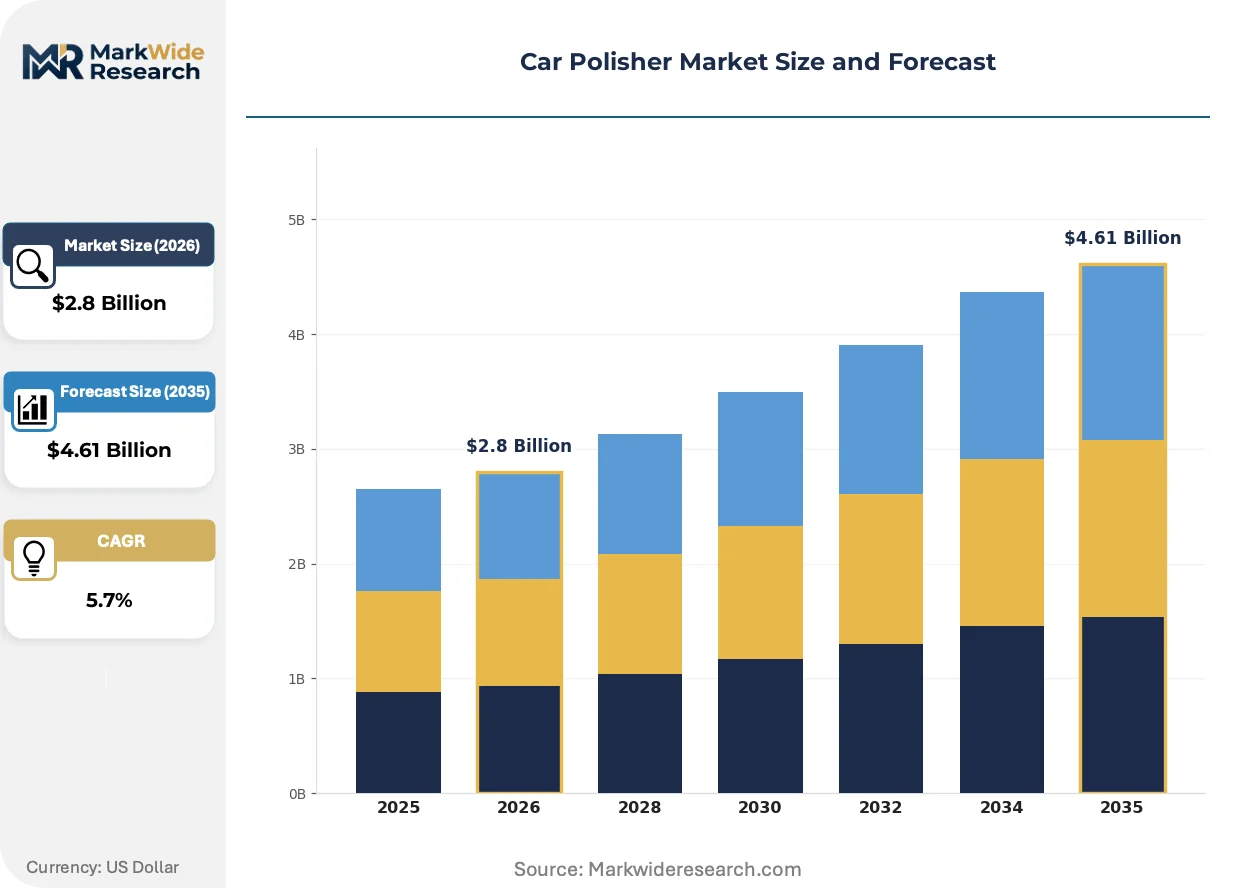
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Polishers, Dual Action Polishers, Orbital Polishers, Handheld Polishers Power Source: Electric, Cordless, Pneumatic, Manual Application: Detailing, Restoration, Pre-delivery Inspection, Maintenance End User: Professional Detailers, Automotive OEMs, Aftermarket Providers, DIY Enthusiasts |
| Companies Covered | TORQ Tool Company, Griot's Garage, Inc., 3M Company, Adam’s Polishes, Inc., Chemical Guys, Meguiar's, Inc., RUPES S.p.A., Bosch, Shurhold Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Polisher Market Emerging Trajectories
Equipment intelligence and powertrain electrification are converging to redefine performance benchmarks and ownership economics across both professional and consumer segments.
Brushless DC motor architectures paired with smart speed governors are rewriting the precision-defect removal trade-off. Professional detailers adopting forced-rotation dual-action units are cutting correction times by half on severe clear coat damage. The technology is compressing the performance gap between amateur-accessible and expert-grade equipment categories.
EPA oversight of volatile organic compounds in automotive finishing chemicals is compelling compound manufacturers to abandon solvent-based carriers. Water-based reformulations are altering pad compatibility requirements and extending cure times. United States-based detailers are responding with heated application bays and humidity-controlled environments to maintain throughput.
Mobile service fleets are consolidating equipment procurement around single-battery platforms to simplify field logistics. Shop owners are replacing mixed-vendor tool collections with unified cordless ecosystems that share chargers and reduce spare parts inventory. This pattern is most pronounced in United States metropolitan markets where van-based operations compete on response speed.
Car Polisher Market Segmentation
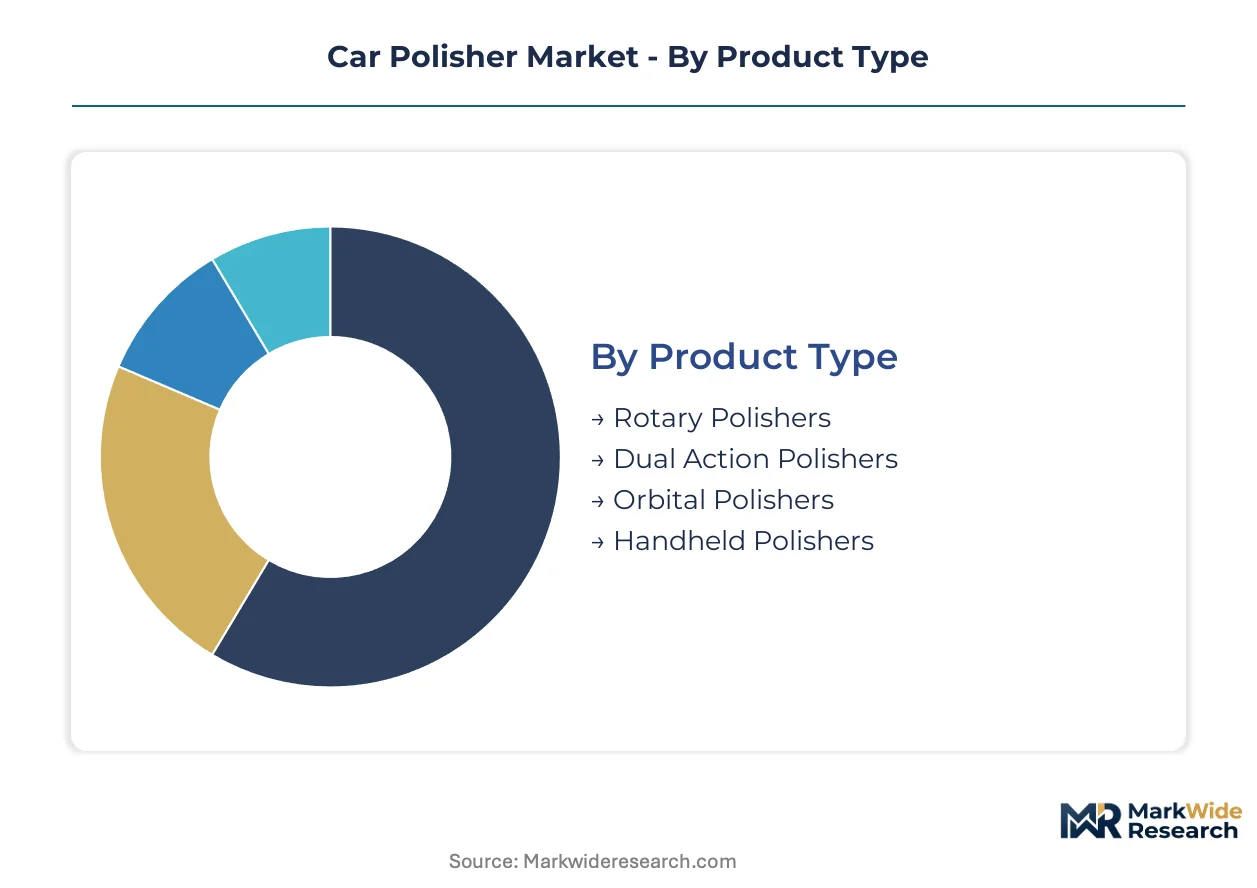
Equipment replacement cycles in automotive finishing vary sharply across user sophistication levels and operational intensity. Segmentation reveals where procurement budgets concentrate and which technology platforms are compressing upgrade timelines.
Product Type:
Tool refresh rates diverge dramatically based on defect removal capability and operator skill requirements, with professional fleets cycling units faster as ceramic coating prep standards tighten.
- Dual Action Polishers:These machines combine orbital motion with forced rotation to abrade clear coat without generating heat-induced swirl marks. Professional detailing shops in the United States are standardizing on these units for daily fleet operations, driven by OSHA vibration exposure limits that favor ergonomic dual-action designs over traditional rotary alternatives.
- Rotary Polishers:Direct-drive spinning mechanisms deliver unidirectional pad rotation at sustained high speeds for severe paint correction. Demand concentrates among restoration specialists tackling deep clear coat damage, though skill transfer bottlenecks constrain workforce scalability for high-volume shops.
- Orbital Polishers:Random orbital motion generates minimal heat, making these entry-grade units suitable for amateur users.
- Handheld Polishers:Compact battery-powered units serve spot-correction needs in mobile detailing vans.
Volume placements concentrate in Dual Action Polishers; the faster expansion belongs to Rotary Polishers as severe correction demand outpaces general maintenance growth.
Power Source:
Energy delivery architecture determines field mobility, runtime economics, and regulatory exposure across installation environments.
- Cordless:Lithium-ion battery platforms are displacing corded units in mobile operations as cell chemistry improvements match runtime parity. Fleet operators in metropolitan United States markets are consolidating procurement around single-battery ecosystems to simplify logistics and reduce spare parts inventory.
- Electric:Mains-powered units retain dominance in fixed-bay installations where uninterrupted runtime outweighs mobility requirements.
- Pneumatic:Compressed-air drive systems serve high-volume production environments with existing shop air infrastructure.
- Manual:Hand-powered applicators persist in budget consumer segments and emergency field kits.
Volume placements concentrate in Electric; the steepest expansion trajectory belongs to Cordless as lithium-ion energy density gains eliminate operational trade-offs.
Application:
Surface preparation protocols dictate equipment specifications, with precision requirements escalating across coating technology generations.
- Detailing:Cosmetic refinement of vehicle exteriors demands variable-speed control and pad compatibility across paint hardness formulations. United States-based professional shops are upgrading tool fleets to meet ceramic coating manufacturer surface prep certifications.
- Restoration:Severe defect removal on aged or damaged clear coats requires sustained high-speed operation and heat management.
- Pre-delivery Inspection:New vehicle finish correction at OEM distribution centers emphasizes speed and consistency.
- Maintenance:Routine gloss restoration in consumer garages favors lower-risk, shorter-runtime equipment.
Volume placements concentrate in Detailing; the fastest share gains belong to Restoration as classic vehicle markets expand.
End User:
Customer sophistication and utilization intensity create distinct procurement patterns across price-performance tiers.
- Professional Detailers:Fleet operators command the highest replacement frequency, creating durable recurring revenue for manufacturers. These users prioritize forced-rotation dual-action units that cut correction times while maintaining OSHA vibration compliance.
- DIY Enthusiasts:Amateur detailers seeking professional-grade results without labor costs are migrating toward direct-to-consumer channels. Lower swirl-risk mechanics are penetrating this segment previously intimidated by rotary learning curves.
- Automotive OEMs:Production-line and distribution-center operations specify industrial-grade durability and standardized maintenance protocols.
- Aftermarket Providers:Independent repair shops and collision centers balance equipment versatility against capital constraints.
Volume placements concentrate in Professional Detailers; the climbing adoption curve belongs to DIY Enthusiasts as training certification ecosystems reduce technique barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in automotive manufacturing corridors concentrate demand for finishing equipment. Tax incentives for vehicle assembly in designated industrial parks accelerate tool procurement cycles among supplier networks. These zones cluster detailing operations near OEM logistics hubs.
United States
Premium auto care culture drives replacement cycles among professional fleets. OSHA workplace vibration exposure guidelines shape ergonomic design requirements for daily-use equipment. Metropolitan detailing corridors in Los Angeles, Dallas, and Miami host mobile service operators consolidating procurement around single-battery cordless platforms.
Germany
Automotive OEM distribution centers emphasize speed and consistency in pre-delivery inspection protocols. REACH chemical regulations push compound manufacturers toward water-based carrier reformulations. Industrial finishing clusters in Stuttgart and Munich integrate forced-rotation dual-action units into ceramic coating preparation workflows.
China
Domestic vehicle sales expansion creates aftermarket service infrastructure buildout. GB standards for power tool safety influence cordless platform design specifications for export markets. Yangtze River Delta manufacturing zones concentrate contract producers supplying lithium-ion battery packs to regional polisher assemblers.
Japan
Classic vehicle restoration markets sustain demand for severe defect removal capability. METI industrial efficiency programs encourage equipment fleet standardization among small-to-medium detailing enterprises. Osaka-based automotive finishing suppliers distribute rotary units to specialty restoration shops nationwide.
United Kingdom
DIY enthusiast channels capture spending from amateur detailers seeking professional-grade results. CE marking requirements for vibration exposure align product testing with continental distribution needs. Southeast England logistics corridors facilitate direct-to-consumer fulfillment for branded equipment specialists.
Car Polisher Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier equipment commanding consolidation around recognized training ecosystems while entry-grade supply fragments across regional fabricators. Three archetypes dominate: power-tool ecosystem extenders leveraging cordless motor platforms, direct-to-consumer specialists capturing enthusiast spending through digital channels, and professional-grade houses sustaining authority through certification programs. Competitive moves concentrate on strategic partnerships with compound manufacturers and geographic expansion into metropolitan mobile service corridors.
Among power-tool ecosystem extenders, Bosch anchors cordless technology transfer from construction equipment into automotive finishing applications. TORQ Tool Company and Meguiar's, Inc. occupy positions on opposite vectors of the specialist spectrum—one representing direct-to-consumer channel innovation, the other exemplifying professional training certification ecosystems that create switching costs through consumable tie-ins. These three collectively illustrate how competitive positioning stratifies across battery platform control, digital-native distribution, and education-based loyalty architectures.
| Leading Market Players |
|---|
| TORQ Tool Company |
| Griot's Garage, Inc. |
| 3M Company |
| Adam's Polishes, Inc. |
| Chemical Guys |
| Meguiar's, Inc. |
| RUPES S.p.A. |
| Bosch |
| Shurhold Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate price volatility cascades through cordless polisher manufacturing into three distinct pricing tiers, with battery pack costs determining whether units compete at premium professional-grade positioning or economy consumer levels.
Pricing Analysis
Lead-time compression commands measurable premiums in professional fleet procurement, with same-week delivery availability adding substantial margin over standard four-week fulfillment windows. The market structures around per-unit transactional pricing with volume-scale differentiation separating single-unit DIY purchases from fleet-quantity professional orders. Price erosion runs through economy cordless tiers as Chinese contract manufacturers expand lithium-ion pack assembly capacity. DIY enthusiasts exhibit highest price sensitivity, while professional detailers prioritize runtime reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Dallas, Rotterdam, and Shenzhen anchor hub-and-spoke fulfillment patterns that position inventory within 48-hour delivery windows of major metropolitan detailing corridors. Manufacturing concentrates in China, Germany, and the United States, with brushless DC motor production anchored in German industrial clusters and final assembly distributed across Guangdong and Michigan. Cobalt cathode chemistry draws from Central African mining regions, exposing cordless platform economics to geopolitical disruption. Distribution runs through authorized dealer networks for professional-grade equipment and direct-to-consumer platforms for enthusiast-tier sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around battery platform control and certification ecosystems, with cobalt supply volatility forcing smaller assemblers without long-term cell contracts toward exit or acquisition.
For Market Incumbents: To counter cordless motor commoditization from Chinese contract manufacturers, prioritize backward integration into battery pack assembly through joint ventures with established cell producers. Anchor professional loyalty through OSHA-compliant ergonomic designs that create switching costs against lower-cost alternatives lacking vibration certification. For New Entrants and Emerging Players: EPA VOC limits in the United States open a window for water-based compound compatibility positioning as a differentiated entry vector. Target DIY enthusiast segments through direct-to-consumer channels with dual-action safety mechanics that reduce technique barriers. Pursue private-label partnerships with established battery platform licensors to bypass R&D capital requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier cordless specialists with established United States distribution footprints but strained working capital from cobalt price spikes. Five-to-ten year viability hinges on lithium-ion chemistry substitution timelines and the pace of professional fleet electrification. Monitor EPA enforcement intensity on VOC limits as an inflection signal for compound reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Consolidating fleet procurement around single-vendor cordless ecosystems reduces spare parts inventory for mobile operators. |
| OSHA Compliance Certification | Ergonomic designs meeting vibration exposure limits differentiate professional-grade equipment from commodity alternatives. |
| Direct-to-Consumer Channel Launch | Digital-native distribution captures enthusiast spending without traditional retail markup structures. |
| Water-Based Compound Compatibility | EPA VOC reformulation requirements alter pad material specifications and application protocols. |
| Training Certification Ecosystem | Branded education programs create recurring revenue through consumable tie-ins and equipment upgrade cycles. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with professional detailing fleet operators, cordless power-tool procurement managers, automotive OEM surface preparation engineers, and ceramic coating manufacturer technical directors. SEC 10-K disclosures, OSHA enforcement databases, EPA chemical registration records, and lithium carbonate price indices provided validation benchmarks. Bottom-up equipment shipment tallies reconciled against top-down automotive service sector expenditure estimates.
Data-stream reconciliation across production volume, import-export flows, and end-user procurement surveys generated consistent baseline estimates. Segmentation modeling incorporated product type, power source architecture, application protocol, and end-user sophistication tier across the projection horizon. CAGRs derived from fitted growth curves applied to equipment replacement cycle data and fleet electrification adoption patterns. Lithium-ion energy density improvement trajectories and ceramic coating prep standard diffusion rates served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for cordless runtime parity assumptions. Forecasts reflect documented assumptions around cobalt supply stability and OSHA enforcement continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
US Car Care Products Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Automotive Repair and Maintenance Services Market
Vehicle Maintenance & Aftermarket
Engine Module-Level Repair and Refurbishment Services Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
Catenary Maintenance Vehicle Market
Vehicle Maintenance & Aftermarket
Heavy-Duty Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
Classic Car Restoration and Restomod Services Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Automotive Cleaner and Degreaser Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market