
 APEJ Automotive Aftermarket Market | 2026-2036
APEJ Automotive Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
APEJ Automotive Aftermarket Market Outlook
Thailand's Eastern Economic Corridor is reconfiguring regional parts distribution networks through upgraded logistics infrastructure and bonded warehousing capacity. Bosch Automotive Aftermarket leverages its Bangkok technical center to localize diagnostic equipment calibration for ASEAN vehicle parc diversity. Denso Corporation sustains dominant compressor and thermal system supply through captive manufacturing in Chachoengsao province. Continental AG anchors premium brake and chassis replacement demand via its Rayong plant's proximity to Thai OEM assembly clusters.
The APEJ Automotive Aftermarket encompasses the full ecosystem of replacement parts, maintenance services, and repair activities serving vehicles post-original sale, spanning components from friction materials and filtration media to lighting assemblies and suspension bushings engineered to OEM or equivalent performance specifications. Brake parts and filters constitute the highest-volume product categories, with filtration experiencing accelerated growth as severe urban particulate conditions shorten replacement intervals across megacity vehicle populations. Repair shops and fleet operators represent the most concentrated end-user demand pool, while online retail channels are capturing incremental share from traditional wholesaler networks as digital procurement platforms penetrate tier-two and tier-three cities.
China's SAMR enforces GB standards compliance for aftermarket components circulating through cross-border e-commerce channels, tightening product traceability requirements. India's BIS mandates compulsory certification for critical safety parts including brake linings and headlamp assemblies, raising market access barriers for uncertified suppliers. Japan's METI coordinates regional harmonization of JIS standards with ASEAN technical regulations through bilateral mutual recognition frameworks. Stakeholders must monitor evolving conformity assessment protocols as regulatory fragmentation across APEJ jurisdictions reshapes sourcing strategies and inventory localization decisions.
Market Dynamics
Fleet electrification across Southeast Asia is fragmenting traditional parts demand as hybrid powertrains require specialized thermal management and braking components that conventional service networks struggle to stock.
Growth Catalysts
- Commercial Transport Intensification:Fleet operators in Indonesia and Vietnam are extending vehicle utilization cycles, accelerating wear-part replacement frequency for brake pads, clutches, and suspension bushings.
- GB Standards Enforcement:China's SAMR cross-border e-commerce compliance mandates are filtering substandard imports, elevating certified supplier margins and consolidating procurement toward traceable channels.
- Urban Particulate Conditions:Severe air quality in Bangkok, Jakarta, and Manila is compressing filtration replacement intervals, expanding addressable volume for cabin and engine air filter categories.
Market Restraints
- Aluminum and Rare Earth Input Volatility:Brake caliper castings and electric motor magnets face cost pressure from concentrate supply concentration in Chinese smelting corridors.
- BIS Certification Timelines:India's compulsory certification for safety-critical brake linings and lighting assemblies extends 14-18 month market entry cycles for new suppliers.
- Remanufactured Component Substitution:Rebuilt starters, alternators, and steering racks from organized remanufacturers in Thailand and Malaysia capture price-sensitive fleet demand.
Strategic Opportunities
- Philippines Archipelago Logistics:Fragmented island geography creates white space for hub-and-spoke distribution models serving Visayas and Mindanao repair corridors.
- EV Thermal System Convergence:Battery cooling loops and heat pump architectures are merging component categories, opening integrated module supply positions for climate-system specialists.
- ASEAN METI Harmonization:Japan's bilateral mutual recognition frameworks with Indonesia and Thailand are simplifying JIS-to-local standard conversion for precision-engineered chassis parts.
Industry Challenges
- Diagnostic Equipment Calibration:ASEAN vehicle parc diversity spanning Japanese, Korean, Chinese, and European OEM architectures strains technician certification breadth and workshop capital allocation.
- Cross-Border Inventory Synchronization:Multi-country bonded warehousing in Thailand's Eastern Economic Corridor demands real-time tax-status tracking across Indonesia, Malaysia, and Vietnam customs protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APEJ Automotive Aftermarket Market |
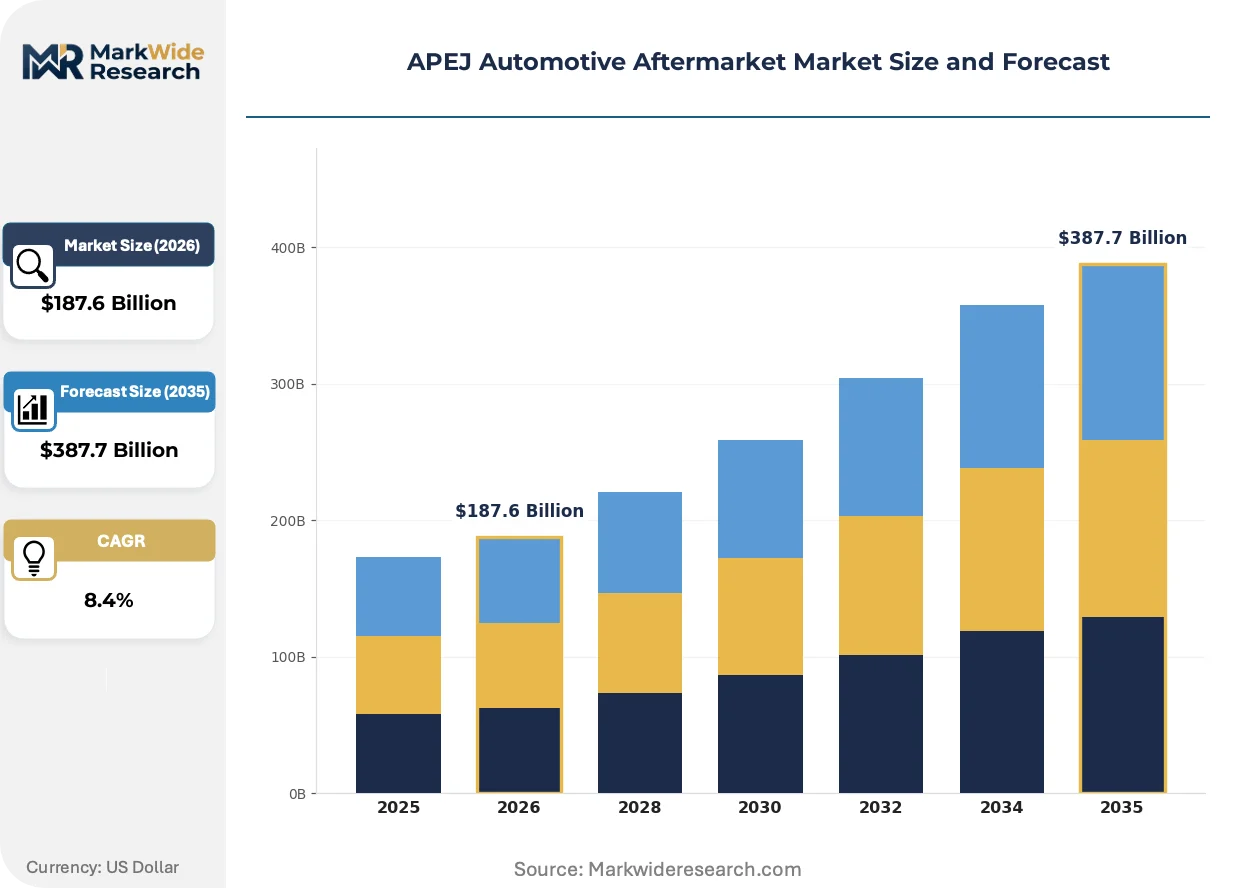
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $387.7 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brake Parts, Filters, Lighting, Suspension End User: DIY Consumers, Repair Shops, Fleets, Dealerships Sales Channel: Online Retail, Wholesalers, Distributors, Brick-and-Mortar Stores Technology: Smart Tools, Diagnostic Equipment, Telematics, Traditional Tools |
| Companies Covered | Bosch Automotive Aftermarket, Denso Corporation, Continental AG, ZF Friedrichshafen AG, Valeo S.A., Aisin Seiki Co., Ltd., Delphi Technologies, Hella GmbH & Co. KGaA, Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APEJ Automotive Aftermarket Market Strategic Shifts
Digital procurement platforms are compressing traditional wholesaler margins while predictive maintenance algorithms embedded in telematics hardware are shifting failure detection from visual inspection to data-triggered pre-emption.
Ceramic brake pad formulations are migrating from European OEM specification tiers into mainstream ASEAN replacement channels. Independent workshops in Kuala Lumpur and Singapore are adopting these formulations for high-performance sedan fleets. The technology is migrating from premium positioning toward volume segments as localized compounding reduces import dependency.
India's BIS compulsory certification scheme for critical safety parts is elevating testing infrastructure requirements across the subcontinent. Domestic laboratories in Pune and Chennai are expanding capacity to handle brake lining and headlamp assembly validation. Tier-two suppliers without captive testing relationships face exclusion from formal distribution networks.
Fleet procurement teams are consolidating supplier relationships around integrated maintenance contracts spanning parts, labor, and uptime guarantees. Large logistics operators in Vietnam and Indonesia are displacing transactional spot-buying with annual framework agreements. This concentration is most visible in Java's dense commercial corridor where single-source contracts now cover 40-vehicle minimum fleets.
APEJ Automotive Aftermarket Market Segmentation
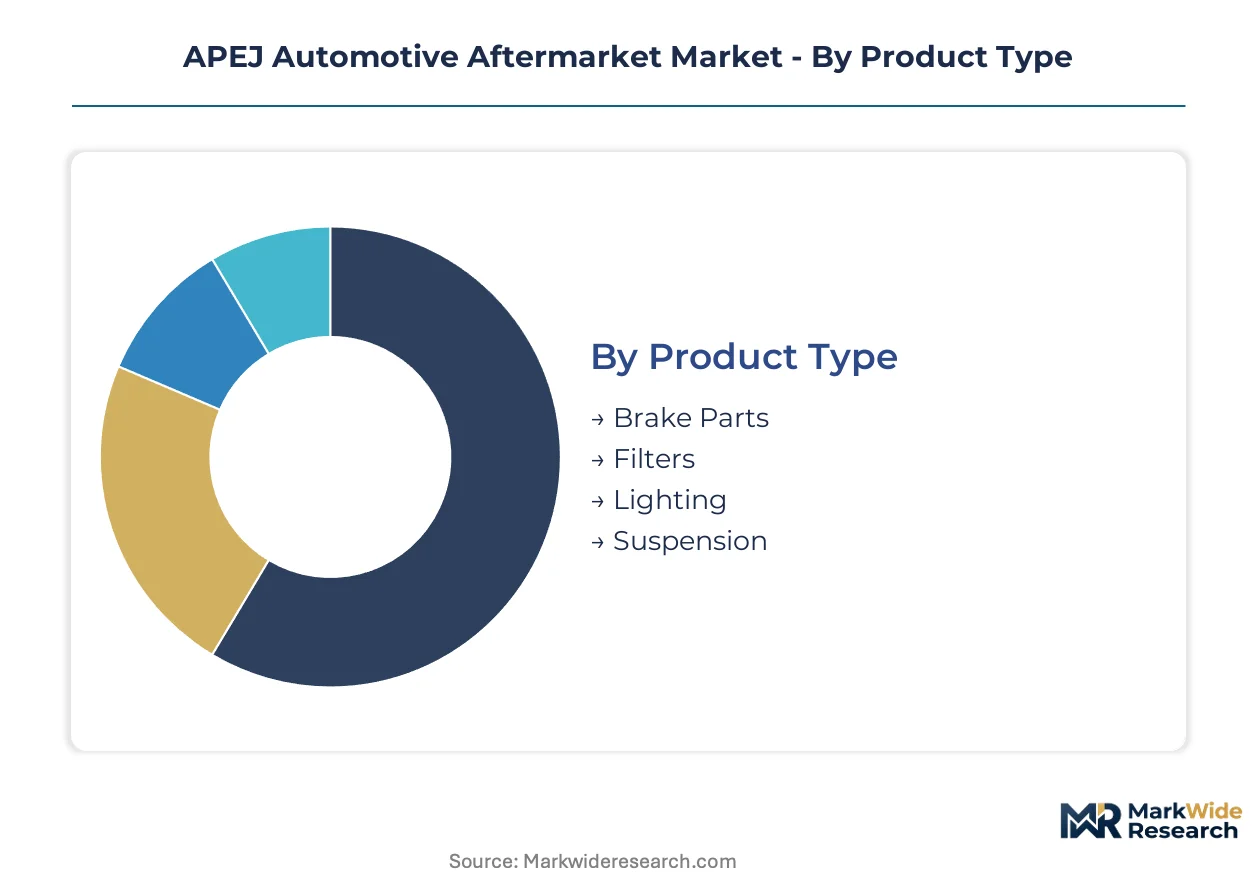
Replacement cycle velocity varies dramatically across the APEJ automotive aftermarket, with friction and filtration components turning over in months while chassis and lighting investments extend across years. Understanding these differential velocities enables inventory positioning and margin capture strategies that align capital deployment with actual consumption patterns.
Product Type:
Brake pads and oil filters rotate through service bays in 6-12 month windows under severe urban duty cycles, while suspension bushings and headlamp assemblies persist for 3-5 year intervals.
- Brake Parts:Friction materials including pads, rotors, and caliper assemblies engineered to OEM thermal specifications. Demand concentrates in Indonesia's Java-based repair corridor where fleet operators maintain 40-vehicle minimum service contracts under compressed replacement intervals. Severe stop-and-go traffic in Jakarta and Surabaya accelerates wear rates beyond temperate-market baselines.
- Filters:Engine oil, air, and cabin filtration media with pleated cellulose or synthetic composite construction. Bangkok, Jakarta, and Manila's particulate-laden atmospheres compress replacement cycles to 5,000-kilometer intervals, expanding addressable volume for premium cabin air categories targeting health-conscious private vehicle owners.
- Lighting:Headlamp, taillight, and indicator assemblies with polycarbonate lens and LED or halogen source configurations. India's BIS compulsory certification for headlamp assemblies extends 14-18 month validation timelines for new suppliers entering formal distribution networks.
- Suspension:Control arms, bushings, shock absorbers, and coil spring assemblies managing chassis dynamics. Thailand's Eastern Economic Corridor bonded warehousing enables just-in-time positioning of premium chassis components for Japanese OEM parc service requirements.
Brake parts anchor the volume base while filters gain share at the steepest rate.
End User:
Procurement sophistication stratifies sharply across customer types, from price-sensitive individual consumers to fleet operators demanding uptime guarantees and integrated maintenance contracts.
- DIY Consumers:Individual vehicle owners purchasing components for self-installation, concentrated in mature markets with high personal vehicle ownership and accessible technical information. Singapore and Kuala Lumpur's digitally literate populations drive online retail penetration for maintenance-grade filtration and lighting categories.
- Repair Shops:Independent and franchise service centers representing the primary volume channel for wear-part replacement. Java's dense commercial corridor sustains high parts turnover through concentrated vehicle populations and limited dealership penetration in tier-two cities.
- Fleets:Commercial transport and logistics operators with centralized procurement and negotiated framework agreements. Vietnam and Indonesia's fleet procurement teams are displacing transactional spot-buying with annual contracts spanning parts, labor, and uptime commitments.
- Dealerships:Authorized service centers leveraging OEM parts certification and warranty coverage to capture premium positioning. China's SAMR cross-border e-commerce compliance mandates are filtering substandard imports, reinforcing dealership channel advantages for safety-critical brake and lighting categories.
Repair shops command absolute transaction volume while fleet procurement is concentrating supplier relationships fastest.
Sales Channel:
Channel economics reflect working capital intensity and technical service bundling, with digital platforms compressing traditional wholesaler margins while physical infrastructure sustains immediate availability requirements.
- Online Retail:Digital procurement platforms penetrating tier-two and tier-three cities through mobile-first interfaces and consolidated logistics. Indonesia's archipelago geography creates white space for hub-and-spoke distribution models serving Visayas and Mindanao repair corridors through centralized fulfillment.
- Wholesalers:Traditional bulk distributors maintaining regional inventory positions and credit relationships with independent workshops. Thailand's Eastern Economic Corridor upgraded logistics infrastructure is reconfiguring regional parts distribution networks through bonded warehousing capacity.
- Distributors:Territory-exclusive intermediaries combining inventory holding with technical support and training delivery. Multi-country bonded warehousing demands real-time tax-status tracking across Indonesia, Malaysia, and Vietnam customs protocols.
- Brick-and-Mortar Stores:Counter-sales operations serving walk-in trade with immediate parts availability and informal technical guidance. Dense urban vehicle populations in Bangkok and Manila sustain high inventory turnover for filtration and brake categories.
Wholesalers retain the installed base while online retail climbs the fastest in penetration metrics.
Technology:
Diagnostic and maintenance technology investment separates premium service positioning from commodity parts replacement, with calibration complexity rising alongside vehicle parc diversity.
- Smart Tools:Connected maintenance equipment with cloud-based specification databases and predictive algorithm integration. ASEAN vehicle parc diversity spanning Japanese, Korean, Chinese, and European OEM architectures strains technician certification breadth and workshop capital allocation.
- Diagnostic Equipment:Scanner and calibration systems interfacing with vehicle ECU networks for fault identification and system reset. Bosch Automotive Aftermarket leverages its Bangkok technical center to localize diagnostic equipment calibration for regional vehicle parc complexity.
- Telematics:Vehicle-mounted sensors transmitting operational data to fleet management platforms enabling predictive maintenance triggers. Predictive maintenance algorithms embedded in telematics hardware are shifting failure detection from visual inspection to data-triggered pre-emption.
- Traditional Tools:Mechanical hand tools and non-electronic measurement equipment serving basic maintenance and repair operations. Price-sensitive segments in tier-three Indonesian cities and Philippine provincial markets sustain demand for conventional tooling.
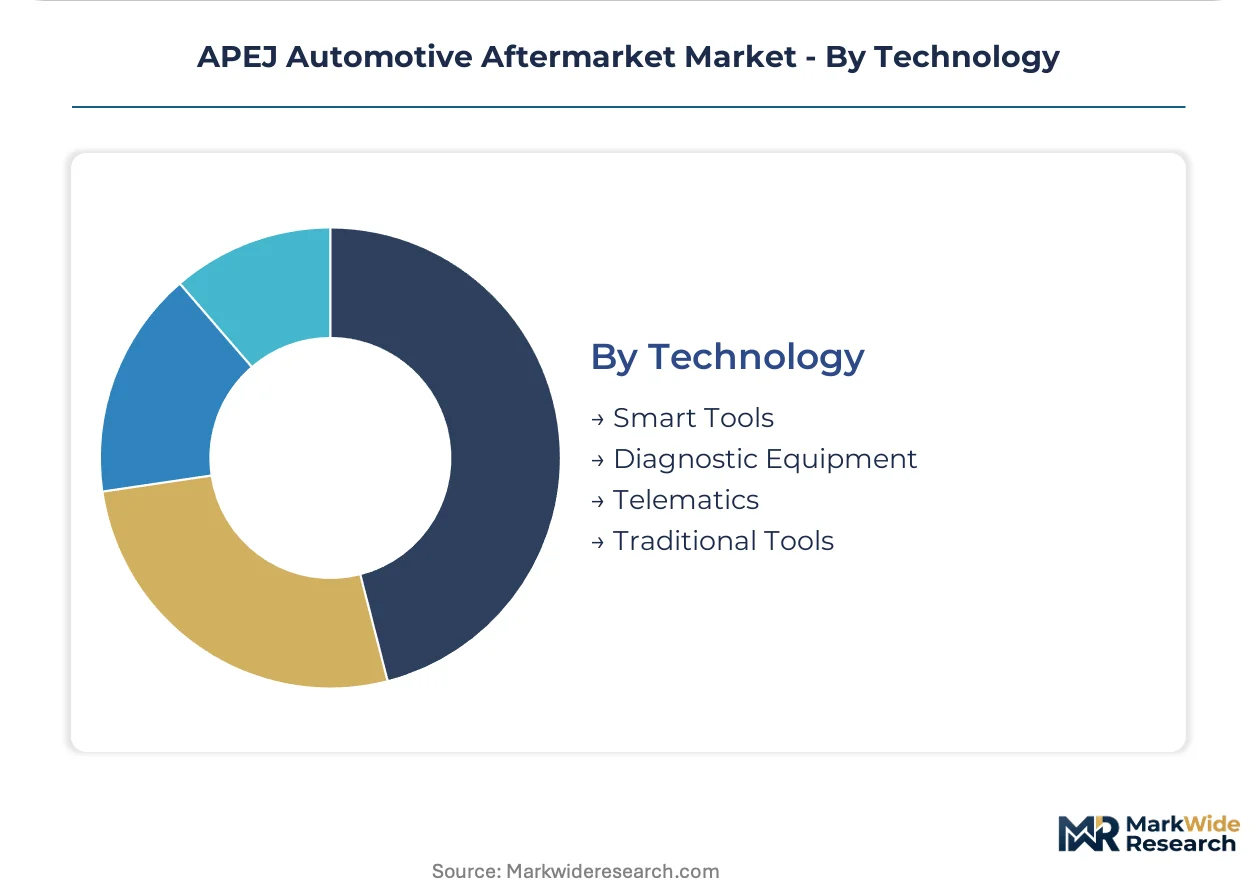
Traditional tools maintain the broadest installed base while telematics demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR anchors regulatory stringency across the dominant geography through GB standards enforcement for cross-border e-commerce channels. India's BIS certification mandates and Japan's METI harmonization frameworks create divergent compliance corridors that reshape sourcing decisions.
China
Cross-border e-commerce volume for replacement parts accelerates through Shenzhen and Guangzhou fulfillment hubs. SAMR's GB standards compliance mandates filter substandard imports, consolidating procurement toward traceable supplier networks. Shanghai's bonded warehousing infrastructure supports just-in-time positioning for premium brake and filtration categories serving the Yangtze River Delta vehicle parc.
India
Compulsory BIS certification for brake linings and headlamp assemblies extends 14-18 month market entry timelines for new suppliers. Pune and Chennai laboratories expand testing capacity to handle validation bottlenecks. Maharashtra's automotive corridor concentrates aftermarket demand as fleet operators in Mumbai-Pune extend vehicle utilization cycles.
Japan
METI coordinates bilateral mutual recognition frameworks with Indonesia and Thailand to simplify JIS-to-local standard conversion. Nagoya-based chassis component specialists leverage technical equivalence agreements to access ASEAN formal distribution networks. Kanto region diagnostic equipment manufacturers localize calibration protocols for regional vehicle parc diversity.
Thailand
The Eastern Economic Corridor reconfigures regional distribution through upgraded logistics infrastructure and bonded warehousing capacity. Rayong's proximity to OEM assembly clusters anchors premium brake and chassis replacement demand. Bangkok technical centers localize diagnostic calibration for ASEAN vehicle architecture complexity spanning Japanese, Korean, and European OEM platforms.
Indonesia
Java's dense commercial corridor sustains high parts turnover through concentrated vehicle populations and limited dealership penetration in tier-two cities. Fleet procurement teams displace transactional spot-buying with annual framework agreements covering 40-vehicle minimum fleets. Surabaya and Jakarta repair networks accelerate wear-part replacement frequency under severe stop-and-go traffic conditions.
APEJ Automotive Aftermarket Market Competitive Environment
Capability concentration sits with integrated system specialists; scale advantage sits with diversified component manufacturers. The vendor base stratifies across three tiers: premium OEM-equivalent suppliers, mid-market certified alternatives, and price-driven uncertified imports. Strategic archetypes include captive manufacturing affiliates of Japanese OEMs, European brake and chassis specialists, and diversified filtration compounders. Dominant competitive moves encompass backward integration into raw material compounding and multi-country bonded warehousing expansion.
Among diversified European system houses, Bosch Automotive Aftermarket, Continental AG, and Schaeffler AG occupy positions spanning diagnostic equipment, brake systems, and precision chassis components respectively. These entities exemplify the premium-tier vector through technical center investments and localized calibration capabilities. Denso Corporation and Aisin Seiki Co., Ltd. represent the Japanese captive manufacturing archetype with thermal system and drivetrain component specializations. The competitive terrain rewards suppliers combining certification breadth across China's SAMR, India's BIS, and Japan's METI frameworks with regional logistics infrastructure in Thailand's Eastern Economic Corridor.
| Leading Market Players |
|---|
| Bosch Automotive Aftermarket |
| Denso Corporation |
| Continental AG |
| ZF Friedrichshafen AG |
| Valeo S.A. |
| Aisin Seiki Co., Ltd. |
| Delphi Technologies |
| Hella GmbH & Co. KGaA |
| Schaeffler AG |
| Others |
Value Chain & Pricing Dynamics
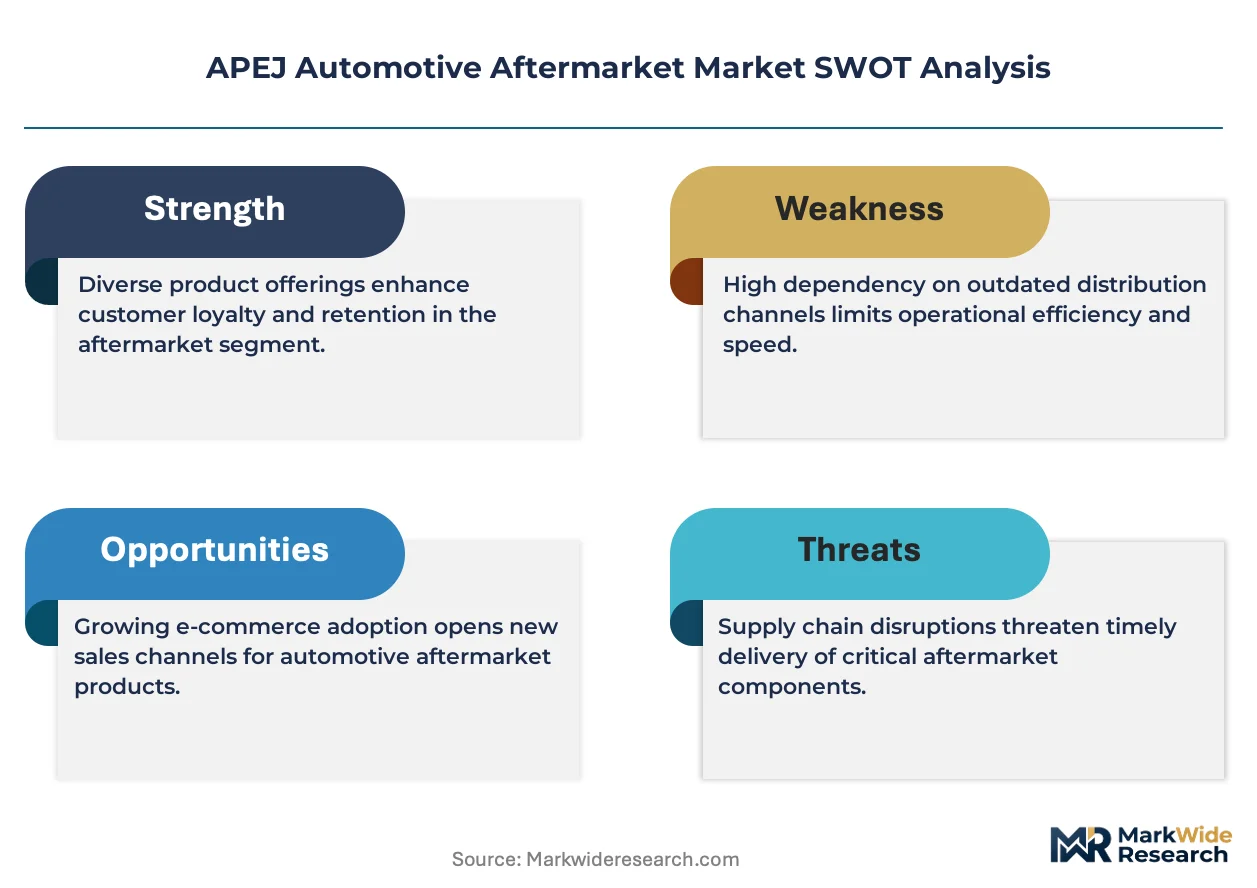
Overcapacity in Thailand's Eastern Economic Corridor bonded warehousing is compressing storage premiums while simultaneously elevating logistics service bundling as a margin source, driving suppliers to recapture value through integrated inventory management rather than pure commodity part markups.
Pricing Analysis
Geographic price spreads between Jakarta's Java-based repair corridor and tier-three Philippine provincial markets exceed 40% for identical brake pad specifications, with pricing stratifies across premium, standard, and economy tiers anchored by certification grade and volume scale. India's BIS compulsory certification for safety-critical components elevates certified supplier margins while filtering uncertified imports from formal channels. Cost compression in economy-tier filtration categories is intensifying because Chinese cellulose media producers are expanding ASEAN direct distribution. Fleet procurement teams demonstrate the lowest price sensitivity due to uptime guarantee requirements, while individual DIY consumers in Philippine provincial markets exhibit extreme elasticity.
Supply Chain Analysis
Upstream aluminum concentrate feedstock draws from Chinese smelting corridors in Shandong and Henan provinces, while rare earth magnet materials for electric motor components rest on processing concentration in Inner Mongolia and Jiangxi. Brake caliper castings and friction material substrates hinge on petroleum-based resin and aramid fiber imports. Single-source vulnerability concentrates in China's rare earth processing infrastructure, with tariff exposure escalating on US-bound remanufactured component flows. Distribution runs through Thailand's Eastern Economic Corridor hub-and-spoke networks serving Indonesia, Malaysia, and Vietnam customs zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This aftermarket functions as a service-attach opportunity where predictive maintenance contracts and telematics-enabled uptime guarantees are expanding faster than hardware replacement revenue, rewarding suppliers who bundle diagnostic calibration with parts supply.
For Market Incumbents: Build certification moats around India's BIS laboratory relationships and Thailand's bonded warehousing tax-status tracking capabilities. Deepen backward integration into friction material compounding to defend against Chinese direct-to-workshop cellulose media imports. Capture channel control through exclusive distributor technical training programs that lock in independent repair shop loyalty.
For New Entrants and Emerging Players: Philippine Visayas and Mindanao island repair corridors offer the most penetrable geographic white space, with fragmented logistics creating entry opportunities for hub-and-spoke fulfillment models. Target fleet procurement teams in Vietnam's emerging logistics corridors with integrated maintenance contracts spanning parts and labor. Pursue digital-first go-to-market angles through mobile procurement platforms that bypass traditional wholesaler credit relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory fragmentation across China's SAMR, India's BIS, and Japan's METI frameworks favors scaled compliance infrastructure over fragmented local suppliers. Acquisition targets should display captive testing laboratory relationships and multi-country bonded warehousing positions. Monitor BIS certification queue lengths as an inflection indicator for supplier exit pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Country Bonded Warehousing Expansion | Thailand's Eastern Economic Corridor tax-status tracking enables just-in-time positioning across ASEAN customs protocols. |
| Diagnostic Equipment Calibration Localization | Bangkok technical centers address Japanese, Korean, and European OEM architecture diversity for regional vehicle parc complexity. |
| BIS Certification Laboratory Investment | Pune and Chennai testing capacity expansion filters uncertified suppliers from India's formal brake and lighting distribution networks. |
| Predictive Maintenance Platform Integration | Telematics-enabled uptime guarantees shift fleet procurement from transactional spot-buying to annual framework agreements. |
| Ceramic Brake Pad Formulation Localization | Kuala Lumpur and Singapore compounding reduces import dependency while migrating premium specifications into mainstream ASEAN channels. |
Study Parameters
Desk research of customs trade databases, OEM technical specification filings, and regulatory certification registries preceded structured interviews with aftermarket distributor operations managers, fleet procurement directors, independent repair shop owners, and Tier 1 supplier regional sales heads. Primary fieldwork across Bangkok, Jakarta, and Mumbai validated secondary findings on channel economics and certification timelines. Bottom-up part-category volume estimates triangulated against top-down vehicle parc replacement cycle models.
Assumptions held fixed across the projection horizon include prevailing GB standards enforcement intensity, BIS certification timeline durations, and ASEAN METI harmonization framework coverage. The analytical framework modeled segmentation across product type, end user procurement sophistication, sales channel working capital intensity, and technology calibration complexity. CAGRs derived from replacement cycle velocity differentials between friction-filtration categories and chassis-lighting investments. Forecast inputs incorporated urban particulate severity indices and fleet electrification penetration curves.
Practitioners should monitor BIS laboratory capacity expansion rates, rare earth concentrate export quota adjustments, and cross-border e-commerce customs enforcement intensity for early signals of forecast revision. Cross-checking against vehicle registration database growth and OEM warranty expiration schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Global Fleet Maintenance Software Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Detailing Products Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
Automotive Repair and Maintenance Services Market
Vehicle Maintenance & Aftermarket
US Car Care Products Market
Vehicle Maintenance & Aftermarket
Engine Module-Level Repair and Refurbishment Services Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Fuel Additives Market
Vehicle Maintenance & Aftermarket
Car Polisher Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
United Kingdom Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
Classic Car Restoration and Restomod Services Market