
 Automotive Cleaner and Degreaser Market | 2026-2036
Automotive Cleaner and Degreaser Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cleaner and Degreaser Market Outlook
Professional fleet maintenance is rebalancing the end-use mix as commercial vehicle operators prioritize downtime reduction over cost-driven DIY solutions. WD-40 Company leverages its aerosol infrastructure to dominate retail channels, while 3M Company sustains R&D intensity around solvent-free formulations for regulated environments. Zep Inc. anchors institutional supply relationships with national fleet operators, competing against specialized regional distributors.
Automotive cleaners and degreasers comprise formulated chemical agents designed to dissolve petroleum residues, road salts, and combustion byproducts from vehicle substrates, typically operating within pH ranges of 9–13 for heavy-duty variants and 6–8 for interior-safe formulations. Biodegradable degreasers are capturing margin pools as regulatory pressure intensifies, while solvent-based cleaners retain volume leadership in industrial fleet bays where flash-point performance outweighs environmental compliance costs. Engine cleaning applications command premium pricing due to thermal-soak tolerance requirements, whereas exterior wash segments face commoditization from private-label competition.
EPA VOC regulations and REACH substance restrictions are forcing reformulation cycles across North American and European supply chains, with California Air Resources Board thresholds serving as de facto national standards for US manufacturers. The EU Green Deal's chemical sustainability targets are compressing approval timelines for new surfactant chemistries, favoring incumbents with established registration dossiers. Stakeholders must monitor pending amendments to OSHA hazard communication standards and decide whether to front-load capital toward aqueous-based production platforms or maintain dual solvent-aqueous capabilities.
Market Dynamics
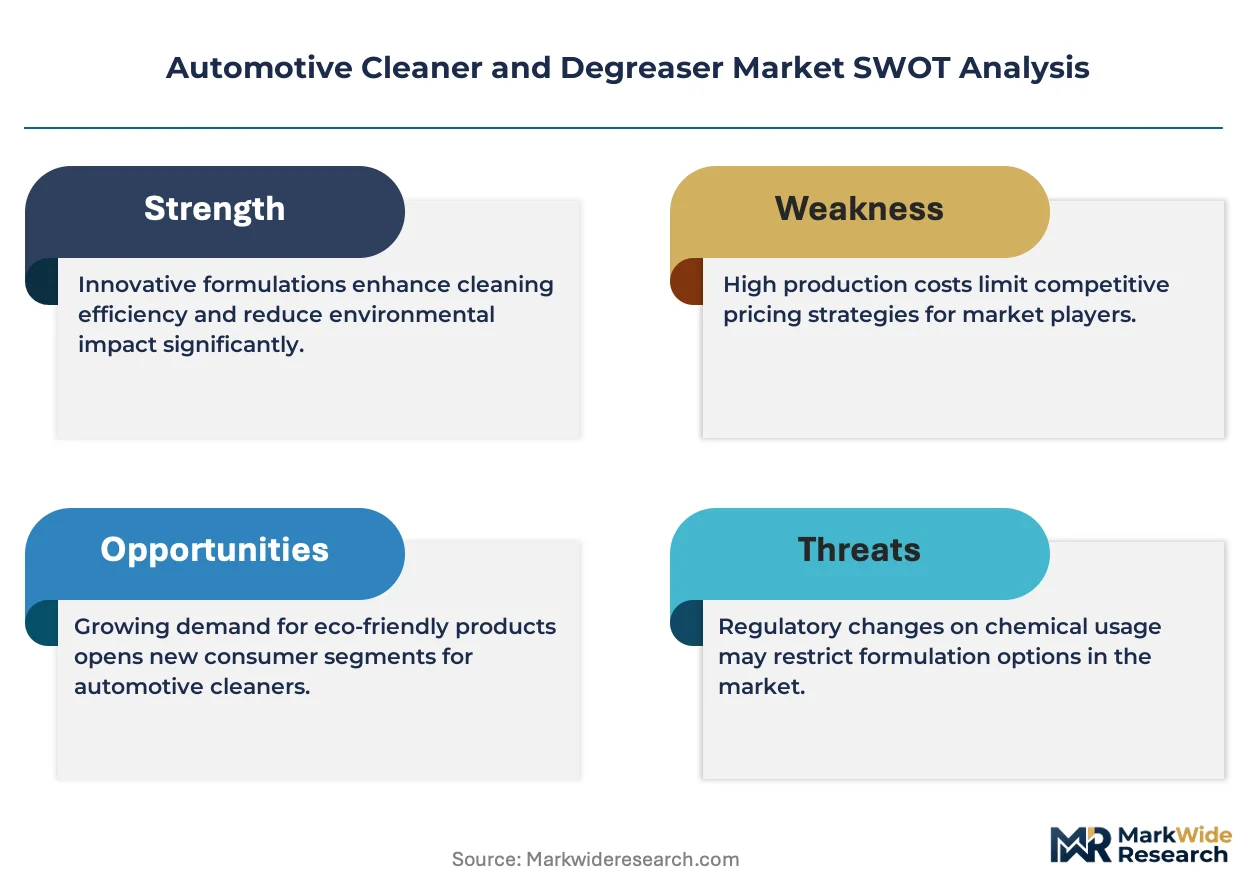
EPA VOC limits and REACH substance restrictions are forcing simultaneous reformulation across North American and European supply chains, compressing product development cycles while elevating compliance costs for mid-tier formulators.
Growth Catalysts
- Fleet uptime mandates:Commercial vehicle operators in Germany and the US are prioritizing heavy-duty degreaser procurement to minimize service bay downtime.
- California Air Resources Board thresholds:These de facto national standards for US manufacturers are accelerating aqueous-based platform investments.
- Biodegradable surfactant chemistries:Formulators with established EU registration dossiers are capturing margin pools as the EU Green Deal compresses approval timelines.
Market Restraints
- Petrochemical feedstock volatility:Solvent-based cleaner producers face margin compression from fluctuating hydrocarbon input costs.
- Specialized surfactant supplier concentration:European chemical intermediates sourcing creates vulnerability for North American formulators lacking backward integration.
- Flash-point performance thresholds:Industrial fleet bays retain solvent dependence where thermal tolerance requirements exceed aqueous formulation capabilities.
Strategic Opportunities
- India fleet modernization:Underpenetrated commercial vehicle maintenance infrastructure creates whitespace for professional-grade degreaser penetration.
- OSHA hazard communication amendments:Pending standard revisions favor early movers with compliant labeling and safety data sheet systems.
- Electrified powertrain cleaning protocols:Battery thermal management residue removal requires novel dielectric-safe formulations absent established standards.
Industry Challenges
- Formulation chemist scarcity:Expertise in surfactant-solvent compatibility at pH extremes is concentrating among legacy specialists.
- Dual-platform capex burdens:Maintaining parallel solvent and aqueous production lines strains mid-cap facility budgets.
- Legacy equipment compatibility:Aqueous cleaner transitions require spray system corrosion audits and nozzle material upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cleaner and Degreaser Market |
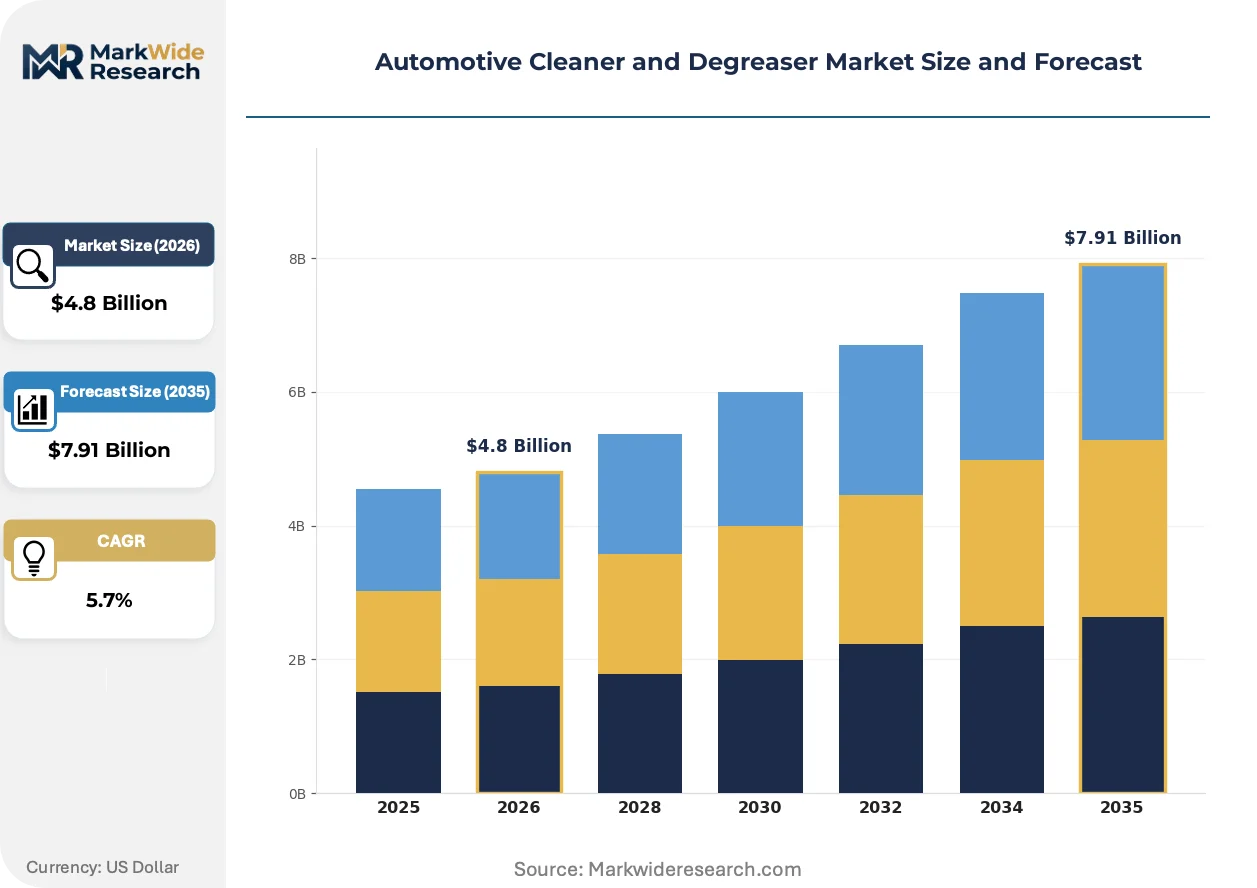
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-based Cleaners, Biodegradable Degreasers, Foaming Sprays, Heavy-duty Cleaners End User: DIY Enthusiasts, Auto Repair Shops, Fleet Maintenance Providers, Car Wash Services Application: Engine Cleaning, Chassis Cleaning, Interior Detailing, Exterior Wash Form: Liquid, Gel, Wipes, Aerosol |
| Companies Covered | Armor All, WD-40 Company, 3M Company, Zep Inc., Chemical Guys, Turtle Wax, Sonax GmbH, CRC Industries, Meguiar's Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cleaner and Degreaser Market Strategic Shifts
Formulation science is pivoting toward water-based chemistries as regulatory thresholds harden, while distribution channels fragment between institutional fleet contracts and retail aerosol volumes.
Alkaline aqueous degreasers with pH stability above 11 are overtaking chlorinated solvent formulations in engine bay applications. Professional auto repair channels in Germany and California are adopting these systems at accelerated rates. This chemistry transition is compressing margins for legacy solvent producers while rewarding surfactant specialists with thermal-soak tolerant portfolios.
REACH Annex XIV authorization requirements are forcing substitution of nonylphenol ethoxylate surfactants across European supply chains. Formulators face dossier resubmission costs and reformulation timelines averaging 18-24 months. Heavy-duty variants for industrial fleet applications bear the greatest compliance burden, with several German suppliers already withdrawing legacy SKUs.
Direct procurement relationships between national fleet operators and formulators are displacing traditional distributor intermediaries. Zep Inc. and comparable institutional suppliers are restructuring territory coverage to capture this volume. This channel compression is most visible in US commercial vehicle maintenance, where cost transparency pressures favor contracted supply over spot purchasing.
Automotive Cleaner and Degreaser Market Segmentation
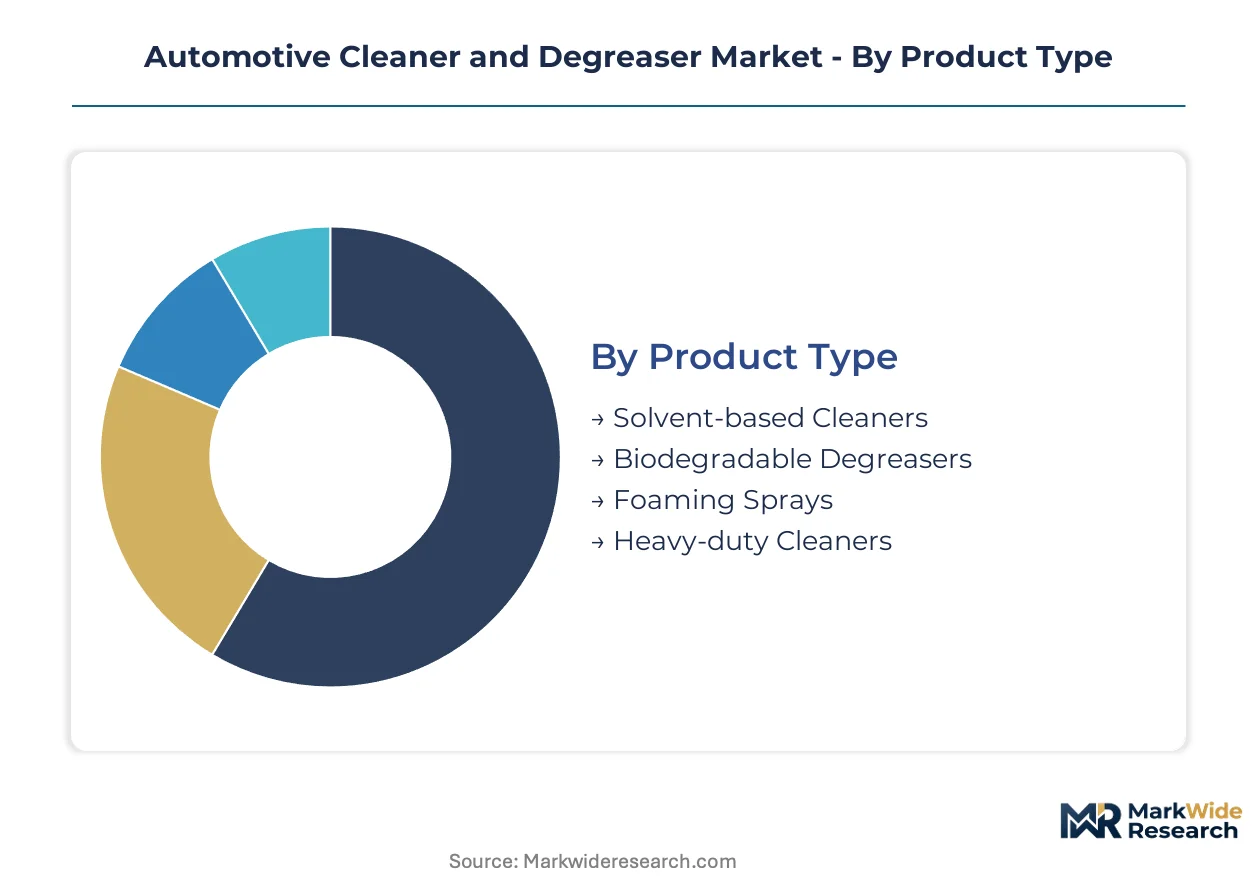
Automotive cleaner and degreaser segmentation reveals divergent capital requirements across chemistry platforms and delivery systems. Formulators must align production infrastructure with distinct regulatory tolerances and end-use performance thresholds rather than pursuing uniform scale economies.
Product Type:
Biodegradable degreasers demand the heaviest upfront capital allocation due to specialized surfactant synthesis equipment and extended EU registration dossier preparation.
- Solvent-based Cleaners:Petroleum-derived formulations with flash-point specifications between 38-60°C dominate industrial fleet bay applications where thermal tolerance outweighs environmental compliance costs. Demand concentrates in German commercial vehicle maintenance corridors where uptime mandates override sustainability preferences.
- Biodegradable Degreasers:Aqueous chemistries with pH stability above 11 and plant-derived surfactant bases require dedicated blending vessels and corrosion-resistant packaging lines. California repair channels are adopting these systems fastest as CARB thresholds harden.
- Foaming Sprays:Aerosol-propelled surfactant systems with controlled expansion ratios for vertical surface adhesion.
- Heavy-duty Cleaners:Alkaline formulations engineered for thermal-soak tolerance in engine bay environments.
Solvent-based cleaners absorb the bulk of installed capacity; biodegradable degreasers are expanding most quickly.
End User:
Procurement scale and contract duration separate institutional buyers from retail channels, with fleet operators commanding the steepest volume discounts.
- Fleet Maintenance Providers:National commercial vehicle operators with centralized procurement functions negotiate direct supply relationships bypassing traditional distributors. German and US long-haul operators prioritize heavy-duty degreaser procurement to minimize service bay downtime.
- Auto Repair Shops:Independent professional channels in Germany source through anchored premium supply chains requiring technical support and training infrastructure.
- DIY Enthusiasts:Cost-driven retail purchasers favor aerosol convenience over performance specifications.
- Car Wash Services:High-throughput exterior wash operations facing commoditization pressure from private-label competition.
Fleet maintenance providers dominate contract value; auto repair shops generate the highest margin per liter.
Application:
Thermal exposure severity and substrate sensitivity create tiered pricing structures across vehicle zones.
- Engine Cleaning:Formulations must withstand thermal-soak cycles above 120°C while dissolving combustion deposits and petroleum residues. Premium pricing reflects pH stability requirements and surfactant-solvent compatibility expertise.
- Interior Detailing:pH-neutral chemistries operating within 6-8 ranges for leather, plastic, and fabric substrate safety.
- Chassis Cleaning:High-pressure spray applications targeting road salt and undercarriage corrosion.
- Exterior Wash:Volume-driven segments facing margin compression from private-label and concentrate dilution systems.
Engine cleaning commands the steepest price premiums; exterior wash segments face the sharpest margin erosion.
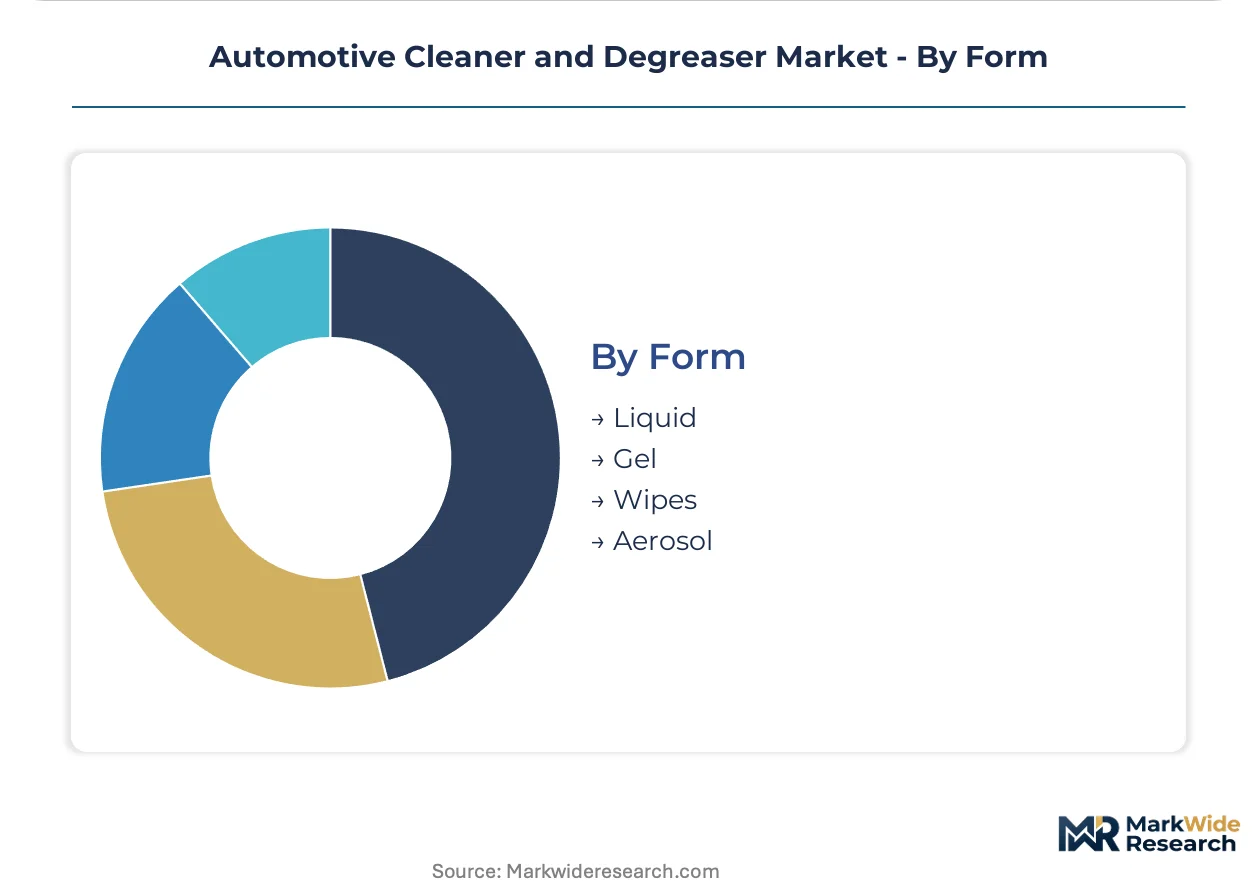
Form:
Packaging technology investment separates aerosol infrastructure owners from liquid bulk suppliers.
- Aerosol:Pressurized propellant systems with specialized filling lines and DOT-compliant logistics infrastructure. Retail channel dominance depends on canister manufacturing partnerships and shelf-space negotiation leverage.
- Liquid:Concentrate and ready-to-use formulations with flexible blending equipment and lower distribution cost per active unit.
- Gel:Thickened rheology for vertical cling applications in engine bay detailing.
- Wipes:Saturated substrate products for convenience-oriented touch-up and spot cleaning.
Liquid formulations carry the broadest installed base; aerosol systems deliver the highest revenue per ounce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation capacity clusters in Germany and the United States while consumption spreads across commercial vehicle corridors. Regulatory divergence between EPA and REACH frameworks creates parallel compliance zones. Fleet uptime mandates concentrate demand in German autobahn-adjacent maintenance hubs and US interstate corridors.
United States
Commercial fleet operators along I-95 and I-10 corridors prioritize heavy-duty degreaser procurement to minimize downtime. California Air Resources Board thresholds function as de facto national standards, forcing aqueous platform investments among domestic formulators. Detroit-area chemical blending facilities supply institutional contracts with national logistics operators.
Germany
Long-haul freight operators in the Rhine-Ruhr and Bavarian industrial zones drive professional-grade cleaner demand. REACH Annex XIV authorization requirements compress surfactant approval timelines, favoring incumbents with established dossiers. Stuttgart and Munich anchor premium supply chains for auto repair channels requiring technical support infrastructure.
China
Commercial vehicle fleet modernization in the Yangtze River Delta and Pearl River Delta generates whitespace for professional degreaser penetration. MEE enforcement of dual carbon goals pressures formulators toward biodegradable chemistries. Shanghai chemical parks host blending operations serving domestic logistics operators.
India
Underpenetrated commercial vehicle maintenance infrastructure in Maharashtra and Gujarat creates demand for professional-grade formulations. BIS standards for industrial chemical safety are tightening, elevating compliance costs for mid-tier suppliers. Pune and Ahmedabad industrial corridors concentrate fleet service bay expansion.
Japan
Precision manufacturing standards in the Kanto and Kansai regions sustain demand for substrate-safe interior formulations. METI chemical management guidelines restrict certain solvent classes in automotive applications. Nagoya-area industrial clusters maintain specialized supply relationships with domestic OEM service networks.
Automotive Cleaner and Degreaser Market Competitive Environment
Top-tier vendors anchor institutional fleet contracts, while mid-cap formulators compete on regional distributor relationships. The vendor base stratifies across aerosol infrastructure owners, aqueous chemistry specialists, and private-label contract manufacturers. Three archetypes dominate: multinational chemical conglomerates with registration dossier depth, aerosol packaging specialists with retail shelf-space leverage, and regional formulators with fleet service bay proximity. Competitive moves center on dual-platform capacity expansion and direct procurement relationship cultivation with national logistics operators.
Within the multinational tier, 3M Company and WD-40 Company exemplify divergent strategic positions—one anchored in solvent-free R&D intensity for regulated environments, the other leveraging aerosol infrastructure for retail channel dominance. Sonax GmbH occupies a position representing premium European supply chain anchoring for professional auto repair channels. Zep Inc. sits within the institutional supplier archetype, restructuring territory coverage to capture direct fleet operator volume.
| Leading Market Players |
|---|
| Armor All |
| WD-40 Company |
| 3M Company |
| Zep Inc. |
| Chemical Guys |
| Turtle Wax |
| Sonax GmbH |
| CRC Industries |
| Meguiar's Inc. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between REACH-compliant biodegradable formulations and legacy solvent systems manifests in parallel pricing ladders and geographically separated supply bases. Fleet operators in Germany pay substantial premia for aqueous chemistries with established EU registration dossiers, while industrial bays in the US retain solvent dependence where CARB thresholds permit, compressing margins for dual-platform suppliers.
Pricing Analysis
Short lead-time premia dominate contract negotiations as fleet operators prioritize uptime over inventory carrying costs. The market operates on a contract-based long-term offtake model for institutional buyers, with price differentiation driven by certification level and volume scale. Cost compression in the exterior wash segment is intensifying because private-label competition erodes branded positioning. DIY enthusiasts demonstrate highest price sensitivity, whereas national fleet operators accept substantial premia for technical support bundling.
Supply Chain Analysis
Workforce availability constraints in German chemical blending hubs and California formulation centers elevate labor costs for specialized surfactant synthesis. Supply concentrates in Germany, the United States, and China, with raw material dependencies on petroleum-derived solvents, plant-based surfactant feedstocks, and corrosion-resistant packaging substrates. Single-source vulnerability persists for European chemical intermediates sourcing, creating exposure for North American formulators lacking backward integration. Distribution runs through direct procurement relationships with national fleet operators, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized surfactant chemist scarcity props pricing power for incumbents with established formulation expertise, constraining rapid capacity expansion across the industry.
For Market Incumbents: Hedge against REACH Annex XIV authorization delays by maintaining parallel solvent-aqueous production capabilities while accelerating EU dossier preparation for biodegradable variants. Backward integration into surfactant synthesis equipment insulates margin pressure from European chemical intermediates concentration. Channel control through direct fleet operator relationships defends against distributor displacement. For New Entrants and Emerging Players: Regional fleet operators in India's Maharashtra and Gujarat industrial corridors represent the most penetrable buyer archetype given underdeveloped professional-grade maintenance infrastructure. Dielectric-safe formulations for electrified powertrain cleaning protocols offer whitespace absent established standards. A technical training bundled go-to-market angle differentiates against commodity importers lacking service capabilities. For Investors and Strategic Acquirers: Re-rating potential sits with aqueous chemistry specialists possessing established EU registration dossiers given accelerating CARB threshold adoption across US states. Long-term viability favors formulators with thermal-soak tolerant portfolios and institutional contract depth over retail-dependent aerosol infrastructure owners. Pending OSHA hazard communication amendments serve as the signal to watch for compliance-driven consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Synthesis | Captures margin pools threatened by European chemical intermediates concentration for REACH-compliant formulations. |
| Long-term Supply Agreement with National Fleet Operators | Secures volume visibility and displaces distributor intermediaries in US commercial vehicle maintenance corridors. |
| Green Manufacturing Transition to Aqueous Platforms | Aligns production with California Air Resources Board thresholds that function as de facto national US standards. |
| Joint Venture for India Fleet Modernization | Establishes local blending capacity to serve underpenetrated commercial vehicle maintenance infrastructure in Maharashtra. |
| Capacity Expansion in German Chemical Parks | Positions near Rhine-Ruhr freight operators while leveraging Stuttgart and Munich technical support infrastructure. |
Study Parameters
Multi-period observation of fleet procurement patterns, regulatory filing timelines, and surfactant chemistry adoption curves anchored the trend analysis, supplemented by interviews with formulation chemists, fleet maintenance procurement directors, automotive aftermarket distributors, and EPA compliance officers. Secondary validation drew from EPA VOC regulatory filings, REACH Annex XIV authorization databases, California Air Resources Board threshold determinations, and customs trade data for surfactant feedstock flows. Bottom-up volume modeling across chemistry platforms and end-use segments triangulated against top-down market sizing from institutional supply contract disclosures.
Segment-weighting approaches applied differential growth assumptions across biodegradable degreasers, solvent-based cleaners, and hybrid formulations throughout the forecast period. The analytical framework incorporated chemistry platform, end-user procurement scale, application thermal exposure severity, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from installed capacity expansion trajectories and fleet uptime mandate intensity. Forecast inputs included surfactant registration approval timelines and electrified powertrain penetration curves affecting cleaning protocol demand.
Revisions become necessary when REACH authorization timelines extend beyond modeled ranges, OSHA hazard communication amendments alter labeling requirements, or petrochemical feedstock volatility disrupts solvent-based formulation economics. Forecasts reflect assumptions about regulatory threshold enforcement consistency and fleet operator sustainability preference evolution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Stolen Vehicle Recovery Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Recycling Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
Catenary Maintenance Vehicle Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Engine Module-Level Repair and Refurbishment Services Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Heavy-Duty Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
US Car Care Products Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market