
 Indirect Tire Pressure Monitoring System Market | 2026-2036
Indirect Tire Pressure Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Indirect Tire Pressure Monitoring System Market Analysis
German automotive component capacity is hardening around integrated chassis electronics. Continental leverages its ESC module dominance to bundle iTPMS algorithms at marginal cost. ZF Friedrichshafen anchors European supply through its braking-system architecture, where wheel-speed data feeds pressure inference. NIRA Dynamics specializes in software-only solutions that retrofit existing sensor networks without hardware additions.
An indirect tire pressure monitoring system estimates tire inflation status through algorithmic analysis of wheel rotational speed variations and ABS sensor inputs, typically detecting pressure differentials of 20-30 percent below nominal. Its primary purpose is to satisfy vehicle safety mandates while avoiding the cost, weight, and maintenance burden of direct pressure sensors. OEM Systems capture the dominant value pool as automakers embed iTPMS within electronic stability control platforms at the design stage. Aftermarket Solutions occupy a narrower but technically demanding niche where independent garages must reconcile incompatible vehicle bus protocols. Wireless Sensors underpin the functional layer, though the true differentiation resides in calibration algorithms that filter road noise and temperature drift.
NHTSA's TREAD Act compliance requirements shape North American product specifications, while the EU General Safety Regulation and UN ECE R141 define the certification pathway for European type approval. China's MIIT enforces GB standards that increasingly reference indirect monitoring as acceptable for domestic passenger vehicle categories. Stakeholders must monitor whether emerging brake-by-wire architectures preserve the wheel-speed signal fidelity that iTPMS algorithms require.
Market Dynamics
Automakers are migrating tire pressure monitoring from direct sensor hardware to software-embedded wheel-speed analytics, compressing component costs while preserving regulatory compliance across vehicle platforms.
Growth Catalysts
- EU General Safety Regulation:Mandates tire pressure monitoring on all new vehicle types, accelerating factory-fit integration of iTPMS with ESC modules.
- China's eastern manufacturing corridor:Domestic automakers in Shanghai, Jiangsu, and Zhejiang provinces are bundling cost-optimized iTPMS with electronic stability control platforms at scale.
- Wheel-speed sensor convergence:ABS and ESC infrastructure already deployed across vehicle fleets enables pressure inference without dedicated hardware additions.
Market Restraints
- Semiconductor input volatility:Wheel-speed sensor ASICs and microcontroller units face pricing instability from foundry capacity constraints in Taiwan and South Korea.
- Detection threshold limitations:iTPMS algorithms require 20-30 percent pressure differential before triggering alerts, creating safety gaps that direct sensors close.
- Calibration complexity:Road surface variation, temperature drift, and tire wear patterns demand continuous algorithm refinement that increases engineering overhead.
Strategic Opportunities
- India's passenger vehicle segment:Low iTPMS penetration among domestic automakers creates first-mover advantage for ESC-integrated software solutions.
- Brake-by-wire convergence:Integration of iTPMS algorithms with electromechanical braking architectures enables real-time pressure feedback loops.
- Aftermarket retrofit channels:Independent garages in Germany and Japan are adopting software-only iTPMS solutions that leverage existing ABS sensor networks.
Industry Challenges
- Algorithm calibration expertise:Shortage of engineers proficient in signal processing and vehicle dynamics modeling constrains development velocity.
- Multi-protocol vehicle bus integration:Reconciling CAN, LIN, and Ethernet architectures across OEM platforms extends certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indirect Tire Pressure Monitoring System Market |
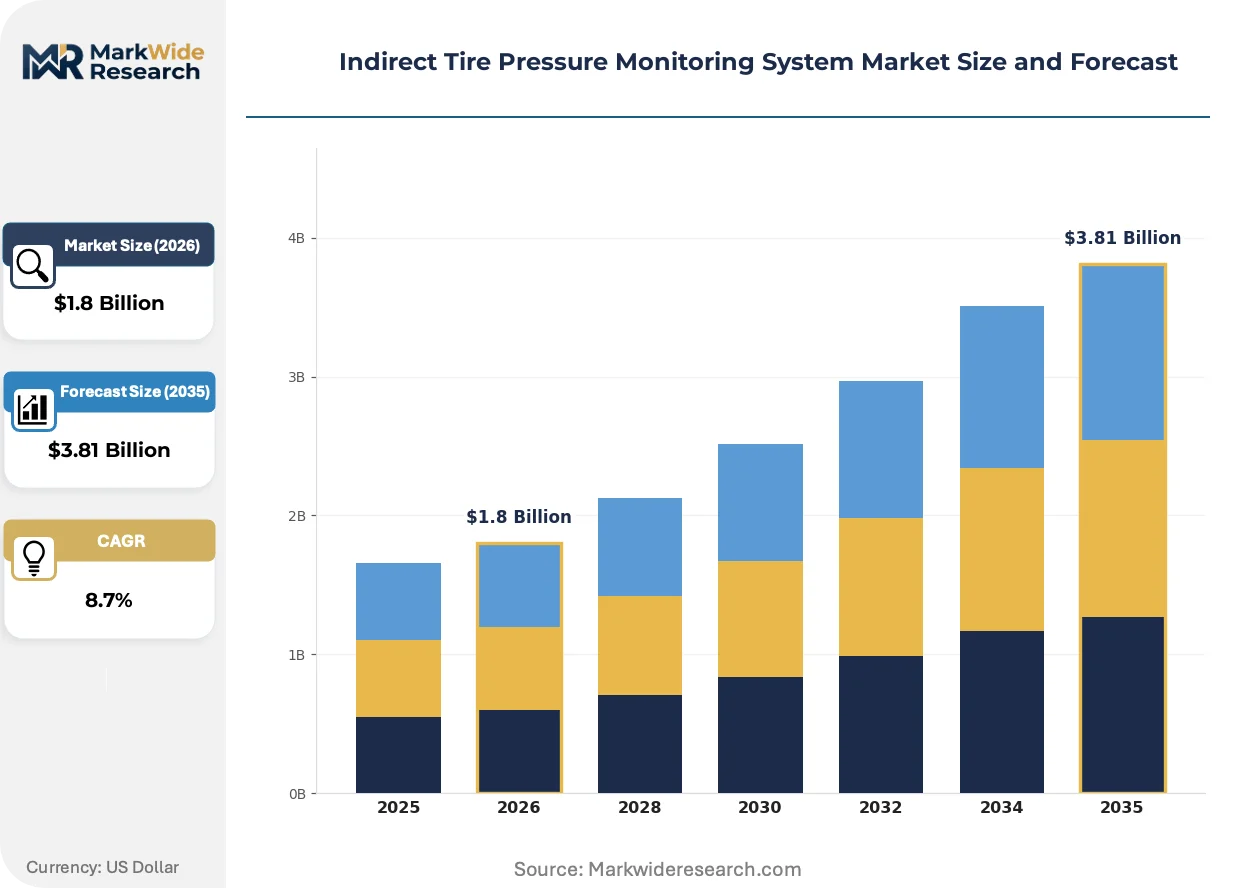
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OEM Systems, Aftermarket Solutions, Integrated Modules, Standalone Devices Technology: Wireless Sensors, Data Analytics, Cloud-Based Solutions, Alert Mechanisms Application: Passenger Vehicles, Commercial Trucks, Motorhomes, Two-Wheelers End User: Vehicle Manufacturers, Fleet Operators, Repair Shops, Consumer Retailers |
| Companies Covered | ZF Friedrichshafen, Pacific Industrial, Continental, NIRA Dynamics, Hella, Denso, NXP Semiconductors, Huf Hülsbeck & Fürst, Sensata Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indirect Tire Pressure Monitoring System Market Emerging Trajectories
Algorithmic inference is replacing hardware sensors as the functional core of tire pressure monitoring, redistributing value from physical components to embedded software and calibration IP.
Machine learning-based pressure estimation is decentralizing detection authority from centralized ABS modules to distributed wheel-speed processing units. Tier 1 suppliers in Germany are embedding neural network inference engines directly into ESC hardware. This architecture is compressing response latency and enabling continuous calibration without service bay visits.
UN ECE R141 harmonization with China's GB standards is creating a unified certification pathway for indirect monitoring systems. European type approval bodies are accepting software-only demonstrations of pressure detection capability. Asian OEMs are leveraging this convergence to accelerate export homologation for vehicles manufactured in domestic plants.
Fleet operators are unbundling tire monitoring from bundled maintenance contracts and sourcing iTPMS-enabled vehicles with standalone pressure analytics. Commercial vehicle leasing companies in Japan are specifying ESC-integrated systems as standard equipment. This specification pattern is propagating through corporate procurement guidelines for light commercial fleets.
Indirect Tire Pressure Monitoring System Market Segmentation
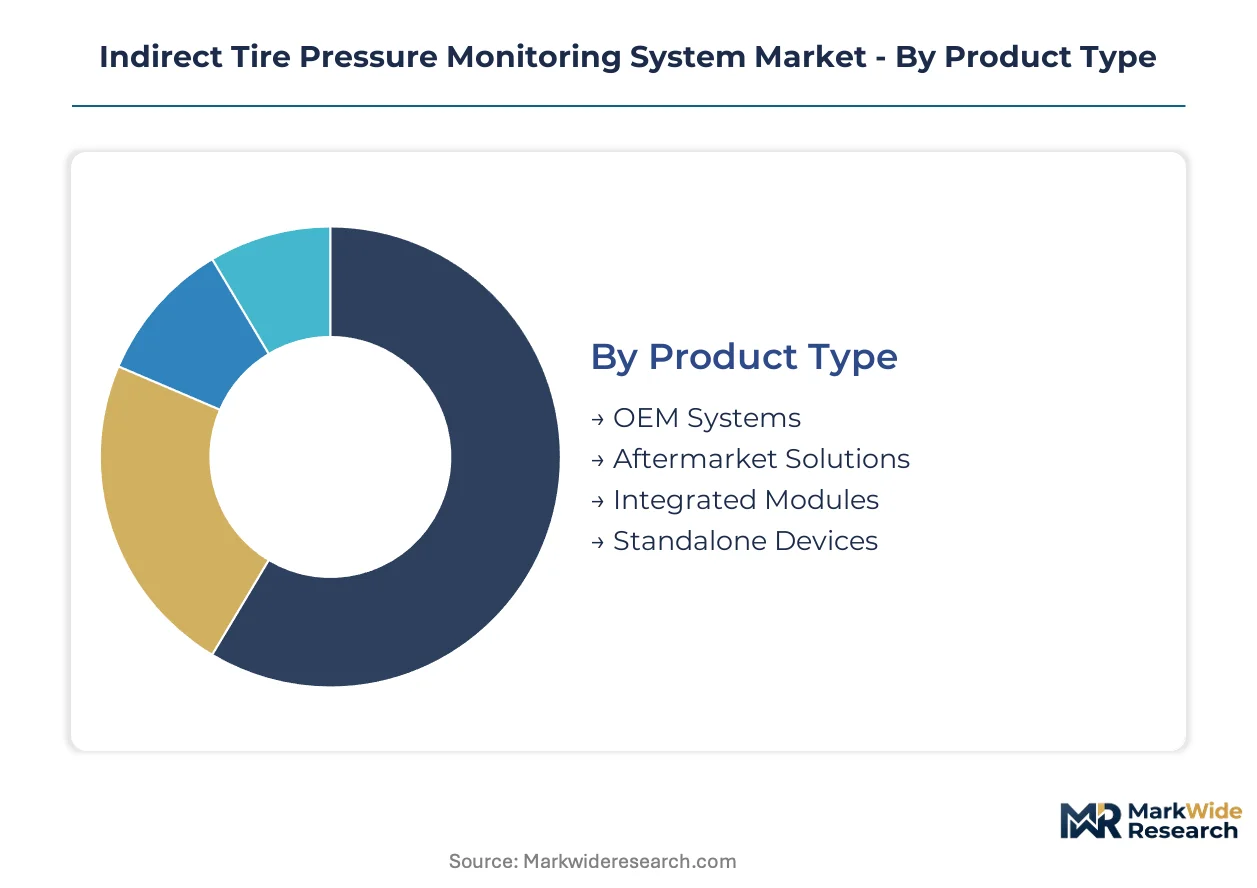
iTPMS value pools concentrate differently across product architectures and customer workflows. Segmentation reveals where software-based pressure inference commands premium pricing versus commoditized hardware bundles.
Product Type:
Volume concentration favors factory-integrated solutions, while premium capture resides in modular retrofit architectures.
- OEM Systems:Factory-calibrated algorithms embedded within ESC platforms dominate commercial value. German and Japanese passenger vehicle manufacturers specify these as standard equipment to satisfy UN ECE R141 mandates without per-unit sensor costs.
- Aftermarket Solutions:Software-only deployments leveraging existing ABS infrastructure address independent garage demand. Installation complexity and protocol fragmentation constrain penetration despite lower hardware requirements.
- Integrated Modules:ESC-bundled units with shared microcontroller resources reduce per-function silicon exposure. Supply concentrates among chassis electronics specialists with braking-system relationships.
- Standalone Devices:Discrete iTPMS hardware for legacy vehicle retrofit occupies a narrowing niche. Price pressure from smartphone-based alternatives erodes addressable market.
Mature deployment sits with OEM Systems. Newer deployment is concentrated in Aftermarket Solutions.
Technology:
Functional differentiation has migrated from sensor hardware to algorithm sophistication and calibration IP.
- Wireless Sensors:Wheel-speed transducers feeding ABS modules constitute the physical layer. Taiwan and South Korean foundry constraints introduce input cost volatility for ASIC-dependent architectures.
- Data Analytics:Signal processing engines filtering road noise and temperature drift represent core value. Machine learning inference at the edge is compressing detection latency.
- Cloud-Based Solutions:Fleet-scale pressure monitoring with centralized calibration updates serves commercial vehicle operators. Data sovereignty requirements fragment platform architecture across jurisdictions.
- Alert Mechanisms:Dashboard integration and mobile notification pathways vary by OEM HMI design. Standardization pressure from regulators is homogenizing warning protocols.
Established functionality centers on Wireless Sensors. Capability investment is concentrating in Data Analytics.
Application:
Regulatory mandate coverage and vehicle electrification intensity reshape segment prioritization.
- Passenger Vehicles:Factory-fit iTPMS penetration approaches saturation in EU and Japanese markets. China's eastern manufacturing corridor is accelerating domestic automaker adoption alongside ESC platform integration.
- Commercial Trucks:Fleet procurement specifications for pressure analytics are unbundling from maintenance contracts. Japanese leasing companies are driving standardization through corporate procurement guidelines.
- Motorhomes:Niche application with aftermarket retrofit concentration. Dual-axle calibration complexity limits algorithm accuracy.
- Two-Wheelers:Minimal ESC infrastructure constrains indirect monitoring viability. Direct sensor architectures dominate where regulation mandates pressure surveillance.
Volume concentration rests with Passenger Vehicles. Regulatory tailwinds are strongest for Commercial Trucks.
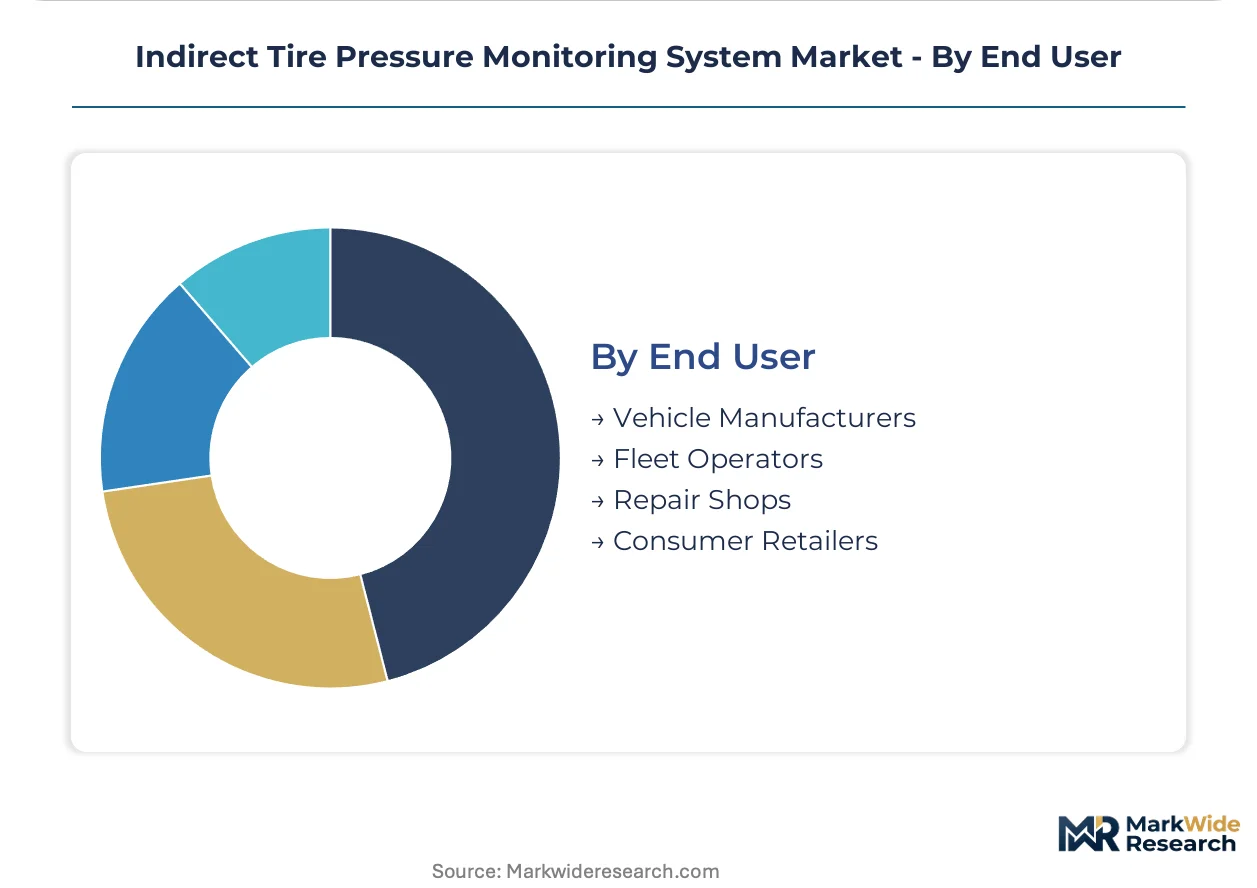
End User:
Procurement authority and technical integration capability determine solution specification patterns.
- Vehicle Manufacturers:Design-stage integration with chassis electronics platforms locks in multi-year supply relationships. Algorithm calibration responsibility sits with Tier 1 braking system suppliers.
- Fleet Operators:Commercial vehicle lessors in Japan are specifying iTPMS-enabled vehicles with standalone analytics. Procurement guidelines are propagating through corporate fleet standards.
- Repair Shops:German and Japanese independent garages are adopting software-only retrofit solutions. Protocol reconciliation across incompatible vehicle buses extends service bay time.
- Consumer Retailers:Narrow channel for enthusiast-grade standalone devices. Smartphone-based pressure monitoring applications capture price-sensitive demand.
Design authority concentrates with Vehicle Manufacturers. Adoption velocity is climbing fastest among Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor foundry capacity in Taiwan and South Korea anchors wheel-speed sensor supply chains for indirect tire pressure monitoring systems. ESC module production clusters in Germany and Japan calibrate algorithms against regional road conditions. Chinese domestic automakers in the Yangtze River Delta integrate cost-optimized iTPMS at factory scale.
Germany
KBA type approval requirements under UN ECE R141 mandate tire pressure surveillance on all new passenger vehicles. Continental and ZF Friedrichshafen leverage established braking-system relationships to embed iTPMS within ESC platforms at design stage. The Baden-Württemberg and Bavaria manufacturing corridors host calibration engineering centers serving European OEM specifications.
China
Domestic automakers in Shanghai, Jiangsu, and Zhejiang provinces specify ESC-integrated iTPMS to satisfy GB standards enforcement by MIIT. The MIIT references indirect monitoring as acceptable compliance pathway for domestic passenger vehicle categories. Yangtze River Delta electronics clusters produce wheel-speed ASICs feeding algorithm development for cost-sensitive platform integration.
Japan
METI industrial standards and corporate fleet procurement guidelines from Tokyo-based leasing companies accelerate iTPMS specification. Commercial vehicle lessors specify ESC-integrated systems as standard equipment in procurement templates. The Kansai and Chubu manufacturing belts concentrate sensor module production for domestic and export vehicle programs.
United States
NHTSA TREAD Act compliance requirements shape product specifications for vehicles sold in the domestic market. The regulation permits indirect monitoring systems where algorithmic detection meets threshold performance criteria. Michigan and Ohio automotive electronics clusters develop calibration protocols for North American road surface variation and temperature extremes.
South Korea
MFDS automotive safety guidelines and domestic OEM platform strategies drive ESC module integration with pressure inference capability. Foundry capacity constraints in Gyeonggi and Chungcheong provinces introduce input cost volatility for wheel-speed sensor ASICs. Seoul Capital Area engineering centers specialize in machine learning-based edge inference for detection latency compression.
Indirect Tire Pressure Monitoring System Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue software-only retrofit channels and aftermarket protocol reconciliation. The supplier base concentrates among chassis electronics specialists with braking-system architecture relationships and semiconductor fabricators with wheel-speed ASIC capabilities. Two strategic archetypes dominate: ESC-integrated platform suppliers leveraging design-stage OEM relationships, and algorithm specialists licensing calibration IP across incompatible vehicle bus architectures. Competitive moves center on strategic partnerships for multi-protocol integration and technology licensing for machine learning-based edge inference.
Among German-based chassis electronics suppliers, ZF Friedrichshafen and Continental exemplify the ESC-integrated archetype, anchoring European supply through braking-system platform dominance. NIRA Dynamics represents the software-only specialist tier, occupying a position where algorithm licensing replaces hardware-dependent value capture. These three entities collectively illustrate how value migrates from physical sensor production toward embedded calibration IP and factory-fit design authority.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Pacific Industrial |
| Continental |
| NIRA Dynamics |
| Hella |
| Denso |
| NXP Semiconductors |
| Huf Hülsbeck & Fürst |
| Sensata Technologies |
| Others |
Supply Flow & Price Mechanics
Algorithm calibration engineers concentrated in Germany's Baden-Württemberg corridor command wage premiums that compress margins on standard-tier iTPMS modules while widening spreads between economy ESC-bundled units and premium standalone retrofit solutions.
Pricing Analysis
Warranty and calibration-service bundling separates OEM factory-fit contracts from aftermarket software-only deployments. Three-tier pricing structure across premium, standard, and economy levels reflects algorithm sophistication and calibration update frequency. Price differentiation hinges on UN ECE R141 certification grade and volume scale commitments from vehicle manufacturers. Pricing pressure stems from semiconductor input volatility in Taiwan and South Korean foundries. Fleet operators exhibit lowest price sensitivity due to unbundled procurement authority, while independent repair shops face acute cost constraints.
Supply Chain Analysis
UN ECE R141 and China's GB standards qualification gating restricts wheel-speed sensor ASIC sourcing to certified semiconductor fabricators. Supply concentrates in Taiwan, South Korea, and Germany. Raw material dependencies include silicon wafers, automotive-grade microcontrollers, and ABS sensor housings. Single-source vulnerability in Gyeonggi Province foundry capacity introduces disruption risk. Distribution runs through Tier 1 chassis electronics suppliers with braking-system platform relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The iTPMS market functions as a cost-of-compliance arena where EU General Safety Regulation mandates create regulatory moats that protect incumbents with certified ESC-integrated platforms while raising barriers for uncertified entrants.
For Market Incumbents: Deepen algorithm calibration IP portfolios to defend against software-only specialists encroaching on aftermarket channels. Expand in-house production of wheel-speed sensor ASICs to reduce exposure to Taiwan foundry pricing volatility. Lock multi-year platform engineering contracts with German and Japanese OEMs before brake-by-wire architectures disrupt signal fidelity assumptions. For New Entrants and Emerging Players: Cloud-based fleet analytics platforms offer the lowest customer acquisition cost pathway into commercial vehicle specifications. Target India's passenger vehicle segment where domestic automakers lack ESC-integrated iTPMS penetration. Pursue software-only retrofit solutions for German independent garages seeking protocol reconciliation tools. For Investors and Strategic Acquirers: Re-rating potential sits with algorithm specialists possessing machine learning-based edge inference capabilities given brake-by-wire convergence catalysts. Five-to-ten year viability favors calibration IP owners over hardware-dependent sensor manufacturers. Monitor NHTSA threshold performance criteria revisions as inflection signal for North American market structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ESC Platform Integration | Locks in multi-year supply relationships with German and Japanese OEMs under UN ECE R141 mandates. |
| Machine Learning Edge Inference | Compresses detection latency for brake-by-wire architectures at Seoul Capital Area engineering centers. |
| Multi-Protocol Vehicle Bus Reconciliation | Reduces service bay time for aftermarket retrofit solutions in German independent garages. |
| Cloud-Based Fleet Analytics | Captures unbundled procurement specifications from Tokyo-based commercial vehicle leasing companies. |
| Semiconductor Backward Integration | Insulates margin structure from Gyeonggi Province foundry capacity constraints. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet leasing managers combined with bottom-up production database triangulation. Secondary sources included KBA type approval registers, MIIT GB standard enforcement records, NHTSA TREAD Act compliance documentation, and vehicle production databases. Top-down market sizing cross-validated against ESC module shipment data.
Data-stream reconciliation across wheel-speed sensor ASIC volumes, ESC platform integration rates, and algorithm licensing contracts informed the analytical framework. Segmentation dimensions modeled encompassed product architecture, technology layer, vehicle application, and end-user procurement authority. CAGRs derived from slope analysis of historical ESC penetration curves projected against regulatory mandate phase-in schedules. Industry-specific inputs included brake-by-wire architecture roadmaps and machine learning inference engine deployment timelines.
The model holds under stable regulatory enforcement intensity; deviation in UN ECE R141 harmonization pace or NHTSA threshold criteria revision would shift volume assumptions. Forecasts reflect assumptions regarding semiconductor foundry capacity normalization and OEM platform consolidation patterns. A model refresh is warranted upon material change in brake-by-wire signal fidelity specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Racing Slicks Tire Market
Tires and Wheels
North America Alloy Wheels Market
Tires and Wheels
High Performance Wheels Market
Tires and Wheels
Commercial Vehicle Forged Aluminum Alloy Wheels Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Global Electric Vehicle Tire Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
EV Tire Market
Tires and Wheels
Bicycle Rim Market
Tires and Wheels
Global Winter Tires Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
Automotive Wheel Spindle Market