
 In-Car Gaming System Market | 2026-2036
In-Car Gaming System Market Size, Share, and Industry Trends Forecast 2026-2036
In-Car Gaming System Market Foresight
Automotive electronics manufacturing in South Korea and Taiwan is realigning toward vehicle-integrated entertainment modules with dedicated GPUs and thermal management. Tesla leverages its vertical software stack to control the full gaming experience through its proprietary operating system. Harman International Industries sustains deep partnerships with European luxury marques for co-developed audio-visual gaming environments. Continental anchors supply contracts with tier-one cockpit integration programs across multiple German OEMs.
An in-car gaming system comprises dedicated processing hardware, display interfaces, and input peripherals installed within vehicle cabins to deliver interactive entertainment during stationary or passenger-use scenarios. These systems typically integrate multicore processors with clock speeds exceeding 2 GHz, support resolutions up to 4K on multiple screens, and employ active cooling to maintain thermal stability in automotive temperature ranges. Built-in systems and cloud gaming represent the fastest-expanding product categories, as automakers abandon physical media and prioritize subscription-based revenue streams. Smartphone integration retains volume leadership in aftermarket channels where retrofit costs deter full hardware replacement. OEMs dominate the end-user segment because factory-installed systems secure warranty alignment and calibration with vehicle electronics architectures.
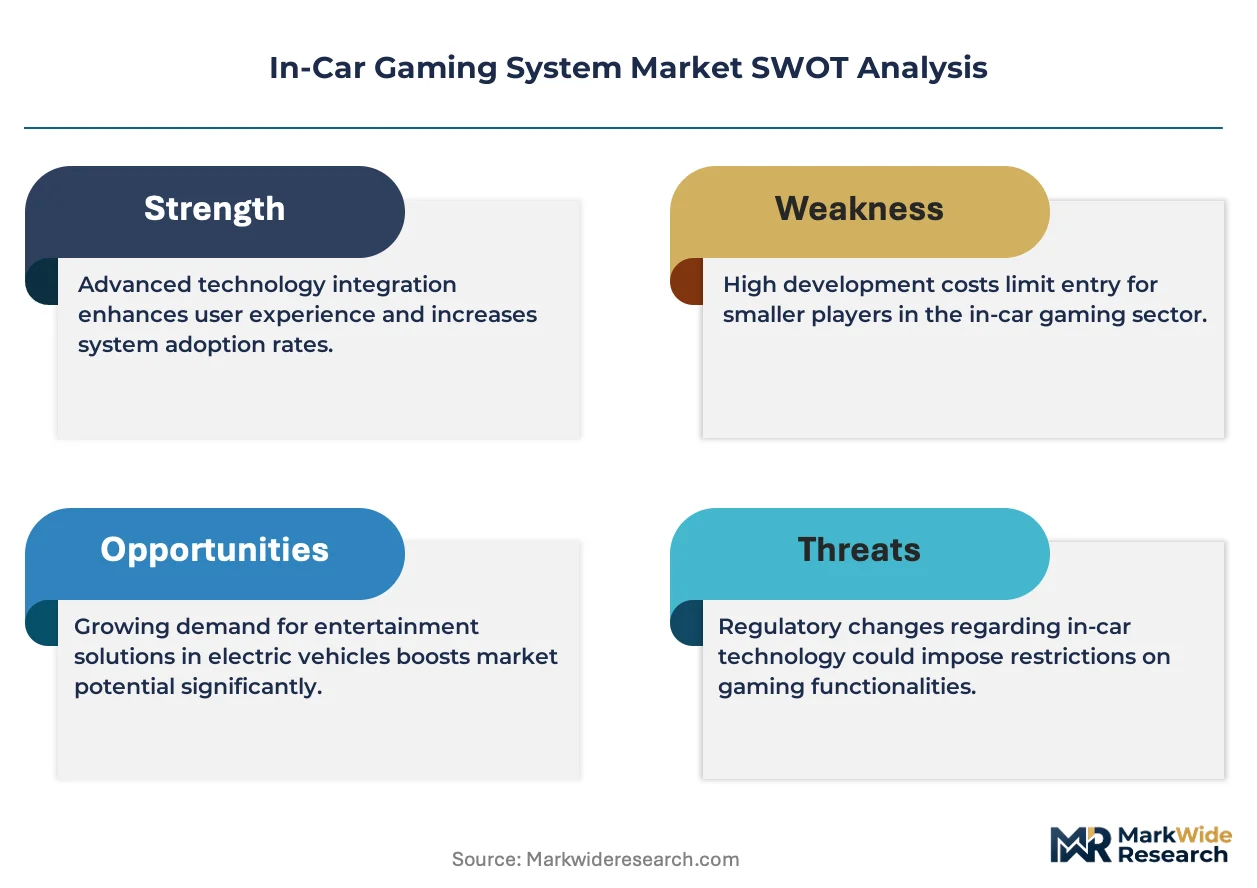
NHTSA guidelines on driver distraction limit touchscreen interactivity to parked states, while EU type-approval frameworks through UNECE WP.29 mandate cybersecurity certification for over-the-air gaming content delivery. China's MIIT enforces content licensing for in-vehicle entertainment platforms, creating compliance barriers for unapproved game publishers. Stakeholders must monitor evolving jurisdictional requirements for passenger safety classification and data privacy in connected gaming ecosystems.
Market Dynamics
Automotive cabin digitization is compressing hardware refresh cycles as EV platforms prioritize software-defined entertainment architectures over traditional infotainment lifecycles.
Growth Catalysts
- UNECE WP.29 cybersecurity mandates:European type-approval frameworks are accelerating OEM investment in certified over-the-air gaming platforms with hardened vehicle interfaces.
- Cloud gaming infrastructure:Low-latency 5G networks are enabling subscription-based gaming services that bypass dedicated console hardware in vehicle cabins.
- China EV cabin competition:Domestic brands deploy gaming systems as standard differentiation features, forcing premium marques to match entertainment specifications.
Market Restraints
- Automotive-grade GPU supply concentration:Advanced graphics processing units for thermal-extreme environments source from a limited supplier base in Taiwan and South Korea.
- NHTSA driver-distraction protocols:US guidelines restrict touchscreen interactivity to parked states, limiting engagement time and monetization potential.
- Silicon carbide thermal substrates:Specialized cooling materials for gaming processors face price volatility tied to semiconductor fabrication capacity constraints.
Strategic Opportunities
- India aftermarket retrofit channel:Premium vehicle owners seek smartphone-integrated gaming solutions where factory systems remain absent.
- Rear-seat passenger monetization:Subscription gaming services target fleet operators and family vehicle segments with per-seat licensing models.
- Voice-controlled interface convergence:Natural language processing is converging with gesture recognition to enable hands-free gaming navigation compliant with distracted-driving rules.
Industry Challenges
- Automotive software certification timelines:Functional safety validation under ISO 26262 extends gaming platform deployment schedules by 18-24 months.
- Legacy CAN bus integration complexity:Gaming systems must bridge proprietary vehicle communication protocols without disrupting safety-critical electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Car Gaming System Market |
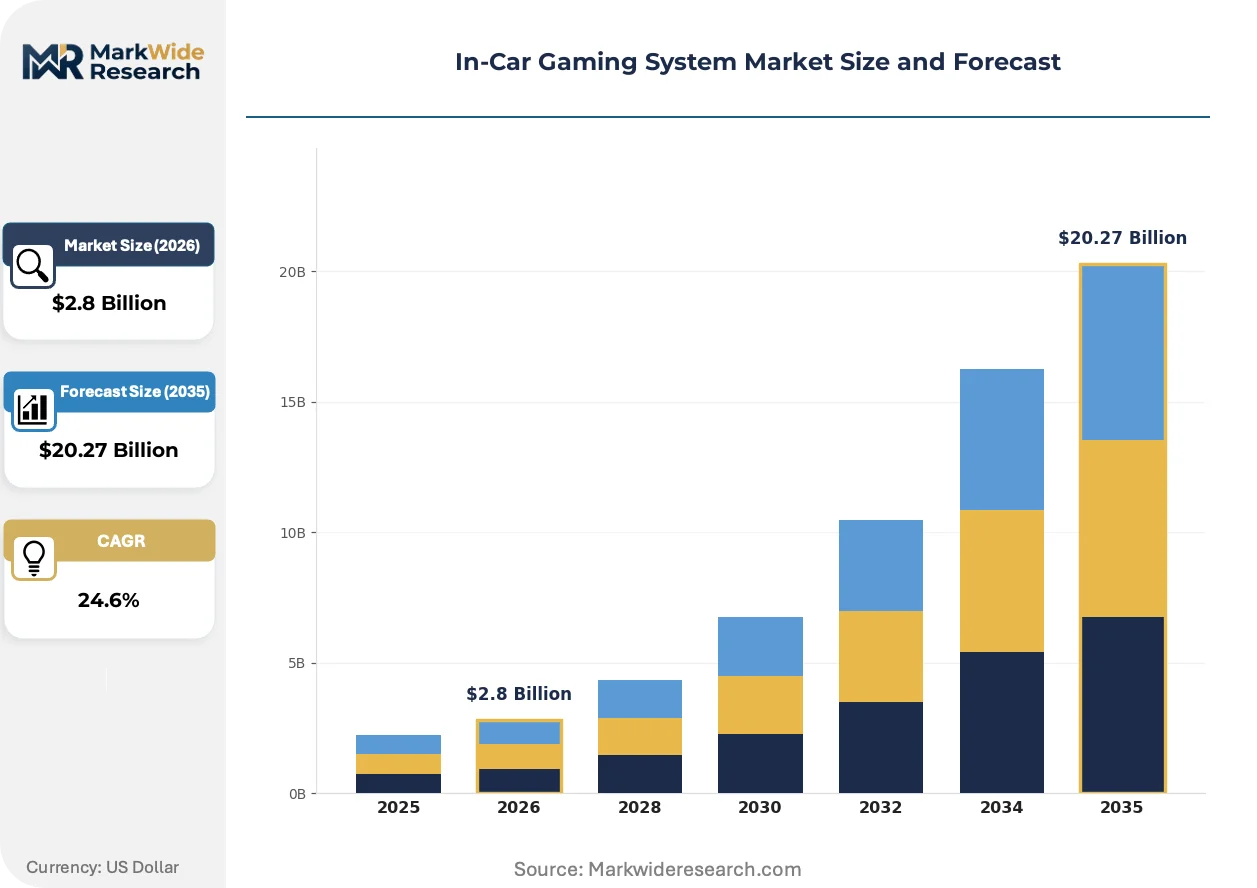
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Consoles, Built-in Systems, Smartphone Integration, Cloud Gaming End User: OEMs, Aftermarket Installers, Fleet Operators, Individual Consumers Technology: Streaming Services, Augmented Reality, Virtual Reality, Game Engines Distribution Channel: Online Retail, Automotive Dealerships, Electronics Stores, Direct Sales |
| Companies Covered | BMW, Ford Motor Company, Tesla, Bosch, Panasonic, Harman International Industries, Mercedes-Benz, Continental, Volkswagen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Car Gaming System Market Shifts & Advancements
Software-defined vehicle architectures are dissolving boundaries between infotainment, gaming, and productivity platforms through unified operating systems and over-the-air capability expansion.
Edge computing for automotive gaming is converging with distributed GPU architectures to enable real-time rendering without cloud dependency. Tier-one cockpit integrators deploy localized processing clusters that reduce latency for competitive multiplayer scenarios. This convergence is compressing the performance gap between vehicle-integrated systems and dedicated home consoles.
EU CSRD sustainability disclosure requirements are mandating carbon footprint transparency for gaming hardware supply chains. Component manufacturers must document embodied emissions from semiconductor fabrication through end-of-life recycling. Premium German OEMs now require ESG-certified suppliers for audio-visual gaming modules.
Fleet operators are unbundling entertainment service contracts from vehicle procurement, treating gaming subscriptions as separate operating expenditures. Rental and mobility-as-a-service providers negotiate enterprise licenses across multi-brand vehicle pools. This procurement evolution is most visible in China, where domestic EV fleets compete on passenger experience metrics.
In-Car Gaming System Market Segmentation
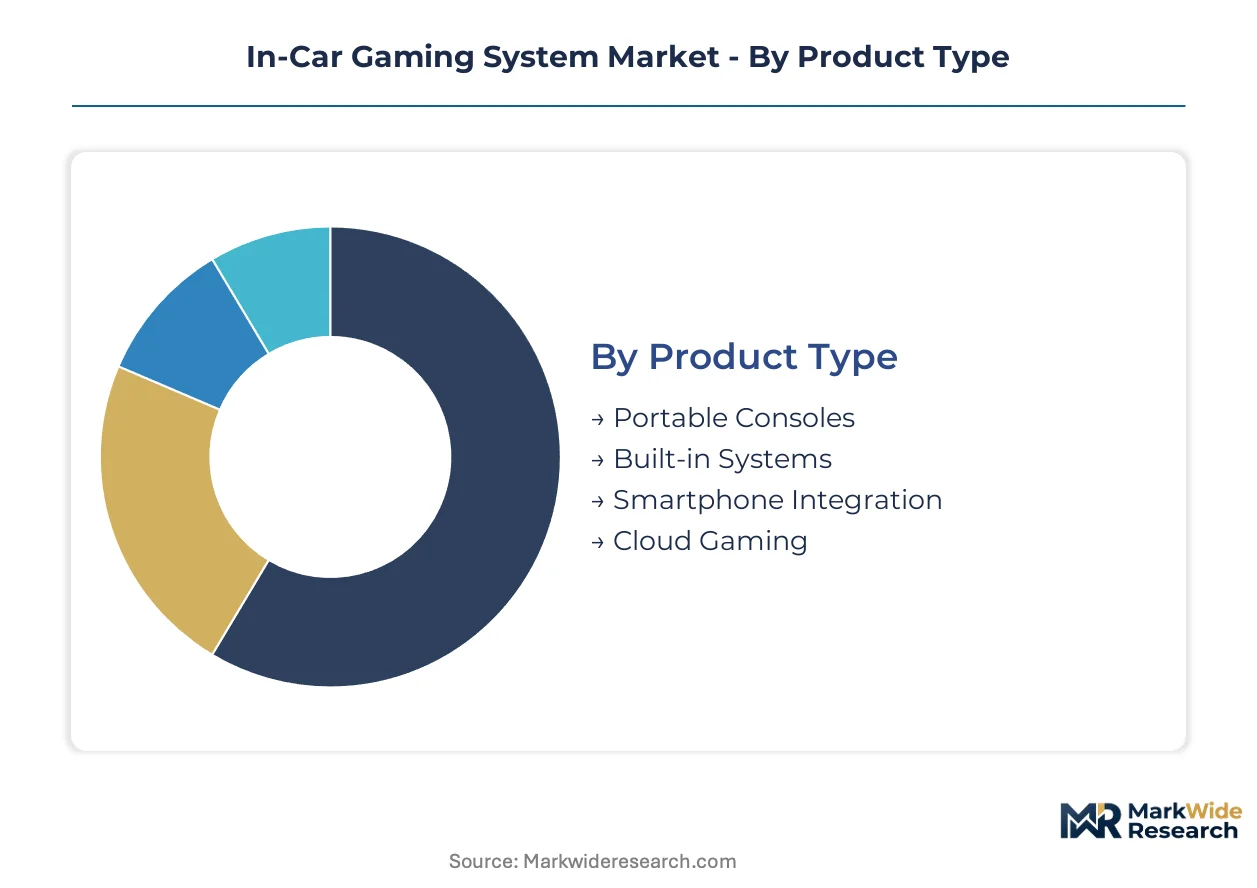
In-car gaming systems fragment across hardware form factors, software delivery models, and procurement pathways that each carry distinct margin profiles and upgrade cadences. Automakers now face strategic trade-offs between factory-integrated platforms with longer lifecycles and flexible aftermarket solutions that capture recurring software revenue.
Product Type:
Hardware refresh cycles compress as EV architectures prioritize software-defined entertainment over fixed-function infotainment units.
- Portable Consoles:Self-contained gaming devices with dedicated batteries and wireless connectivity that passengers deploy ad-hoc without vehicle integration. Demand clusters in family vehicle segments where children require entertainment independent of factory screen availability.
- Built-in Systems:Factory-embedded multicore processors with active thermal management and 4K display support, calibrated to vehicle electronics architectures for warranty alignment. Premium German and Chinese EV marques deploy these as standard cabin differentiation features.
- Smartphone Integration:Mirroring protocols and controller peripherals that leverage passenger devices for gaming without dedicated vehicle hardware. Aftermarket channels in India and Southeast Asia favor this low-cost retrofit path where factory systems remain absent.
- Cloud Gaming:Subscription-based streaming platforms that bypass local processing through 5G connectivity, enabling console-grade titles without thermal-intensive GPUs. This segment climbs fastest as fleet operators unbundle entertainment from vehicle procurement.
Built-in Systems sits at the top of the volume ranking, with Cloud Gaming climbing the fastest.
End User:
Procurement authority determines pricing power and service bundling flexibility across the value chain.
- OEMs:Vehicle manufacturers integrating gaming platforms at design phase with ISO 26262 functional safety certification and cybersecurity validation under UNECE WP.29. These contracts anchor supply relationships with tier-one cockpit integrators for multi-year production runs.
- Aftermarket Installers:Specialized automotive electronics shops retrofitting gaming hardware into existing vehicles, navigating legacy CAN bus complexity and thermal constraints without factory calibration support.
- Fleet Operators:Rental and mobility-as-a-service providers negotiating enterprise gaming licenses across multi-brand vehicle pools, treating subscriptions as separate operating expenditures from asset procurement.
- Individual Consumers:Private vehicle owners selecting portable or smartphone-integrated solutions where factory options prove insufficient or cost-prohibitive.
OEMs command the revenue concentration, while Fleet Operators are expanding most quickly through subscription monetization models.
Technology:
Rendering architecture choices determine latency sensitivity, hardware requirements, and content licensing complexity.
- Streaming Services:Cloud-dependent delivery of gaming content requiring persistent low-latency connectivity, with 5G infrastructure enabling competitive multiplayer scenarios without edge processing. China's MIIT content licensing rules create compliance barriers for unapproved publishers.
- Augmented Reality:Overlay gaming elements onto windshield and window displays using vehicle sensor fusion, demanding precise calibration with ADAS camera systems to avoid driver distraction violations under NHTSA guidelines.
- Virtual Reality:Headset-based immersive environments restricted to stationary vehicle states, with motion sickness mitigation algorithms tied to vehicle dynamics sensors.
- Game Engines:Licensed development platforms enabling automaker-proprietary titles and third-party porting, with Unreal Engine and Unity dominating automotive adaptation contracts.
Streaming Services holds the deployment scale advantage, with Augmented Reality gaining share fastest through windshield integration programs.
Distribution Channel:
Channel selection shapes customer acquisition costs and post-sale service attachment rates.
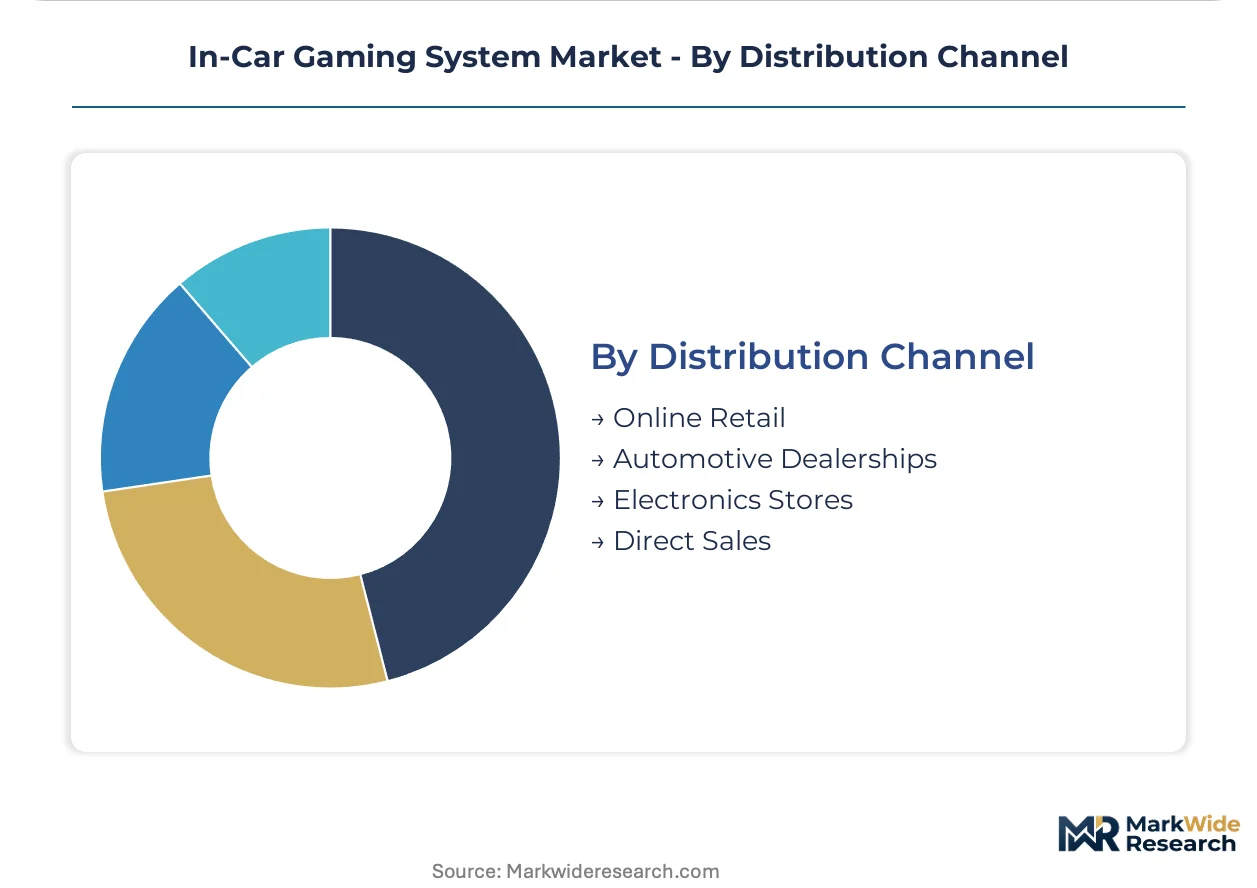
- Online Retail:E-commerce platforms for portable consoles, controllers, and subscription activation codes, with logistics networks penetrating regions lacking dedicated automotive electronics retail.
- Automotive Dealerships:Factory-authorized sales channels bundling gaming platform demonstrations with vehicle purchase consultations, securing warranty alignment and calibration services.
- Electronics Stores:Consumer electronics retailers stocking portable gaming peripherals and smartphone integration accessories, competing on price transparency against direct manufacturer channels.
- Direct Sales:Automaker-owned digital storefronts and subscription portals capturing recurring revenue without channel margin dilution, most developed in Tesla's vertical software stack.
Automotive Dealerships anchor the volume position, with Direct Sales showing the steepest expansion trajectory as software-defined vehicles mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as automakers relocate gaming system production toward jurisdictions with streamlined type-approval pathways and lower certification costs. South Korean and Taiwanese electronics clusters capture module assembly contracts from European OEMs seeking to bypass UNECE WP.29 compliance delays.
United States
NHTSA driver-distraction protocols restrict touchscreen gaming to parked vehicle states, compressing monetization windows for interactive content. The Infrastructure Investment and Jobs Act allocates spectrum for vehicle-to-everything connectivity, enabling cloud gaming trials in Michigan and California test corridors. Detroit-based tier-one suppliers anchor cockpit integration programs for domestic OEMs.
Germany
EU CSRD sustainability disclosure mandates force gaming hardware suppliers to document carbon footprints from semiconductor fabrication through end-of-life recycling. KBA type-approval frameworks require cybersecurity certification under UNECE WP.29 for over-the-air gaming platforms. Stuttgart and Munich house development centers where premium marques co-design audio-visual gaming environments with tier-one integrators.
China
MIIT content licensing rules create compliance barriers for unapproved game publishers seeking vehicle platform distribution. Domestic EV brands deploy gaming systems as standard cabin differentiation features, forcing premium marques to match entertainment specifications. Shenzhen and Shanghai clusters concentrate GPU thermal management manufacturing for automotive-grade processors.
South Korea
MFDS-equivalent automotive electronics standards align with UNECE frameworks, accelerating export certification for gaming module producers. Seoul Capital Area fabs specialize in silicon carbide thermal substrates for processor cooling in extreme automotive temperature ranges. Hyundai Motor Group integrates gaming platforms across EV lineups as standard infotainment features.
Japan
METI subsidies for software-defined vehicle architectures incentivize gaming platform R&D through public-private partnerships. Nagoya-based cockpit integrators bridge legacy CAN bus protocols with modern entertainment systems without disrupting safety-critical electronics. Toyota and Sony joint ventures explore edge computing clusters for localized multiplayer rendering.
In-Car Gaming System Market Competitive Landscape
German tier-one suppliers anchor one tier; South Korean and Taiwanese electronics specialists hold module manufacturing contracts for thermal management and GPU integration. The vendor base stratifies between vertically integrated automakers controlling full software stacks and component suppliers delivering calibrated hardware to multiple OEM programs. Three archetypes dominate: proprietary platform operators, cockpit integration specialists, and semiconductor thermal solution providers. Competitive moves center on strategic partnerships for audio-visual co-development and backward integration into GPU supply chains.
Within the proprietary platform tier, Tesla exemplifies vertical software control through its captive operating system architecture. Harman International Industries occupies a position representing cockpit integration specialists serving European luxury marques. Continental sits within the tier-one supplier archetype anchoring multi-OEM contracts across German manufacturers. These three entities illustrate divergent strategic postures: full-stack ownership, partnership-dependent integration, and scale-driven component supply.
| Leading Market Players |
|---|
| BMW |
| Ford Motor Company |
| Tesla |
| Bosch |
| Panasonic |
| Harman International Industries |
| Mercedes-Benz |
| Continental |
| Volkswagen |
| Others |
Supply & Pricing Matrix
Silicon carbide substrate price indices cascade through automotive GPU manufacturing into three-tier pricing structures across premium, standard, and economy levels. Taiwan and South Korean fab capacity allocation determines which OEM programs receive thermal-grade component priority, compressing margins for second-tier cockpit integrators locked into fixed-price contracts.
Pricing Analysis
Distributor markups on aftermarket portable consoles range from 25 to 40 percent above factory gate prices, while direct-to-OEM supply agreements for built-in systems carry volume-scaled discounts tied to multi-year production commitments. Certification tier under UNECE WP.29 cybersecurity mandates creates price differentiation between certified and non-certified gaming platforms. Cost compression in cloud gaming subscription tiers is intensifying because 5G infrastructure operators negotiate wholesale bandwidth rates. Fleet operators exhibit the highest price sensitivity due to per-seat licensing negotiations, whereas premium German marques absorb cost premiums for co-developed audio-visual environments.
Supply Chain Analysis
Automotive-grade GPU supply rests on Taiwan Semiconductor Manufacturing and Samsung Foundry capacity allocation decisions for 7nm and 5nm process nodes. Silicon carbide thermal substrates, high-bandwidth memory stacks, and multicore ARM-based processors constitute critical input dependencies. Single-source vulnerability concentrates in Taiwan Strait logistics corridors where marine shipping disruptions would idle module assembly lines across South Korean electronics clusters. Distribution runs through tier-one cockpit integrators who calibrate hardware-software bundles before final OEM vehicle assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where UNECE WP.29 cybersecurity mandates accelerate certified platform demand across European type-approval jurisdictions.
For Market Incumbents: Anchor supply relationships through captive silicon carbide thermal substrate sourcing from Seoul Capital Area fabs to defend against GPU allocation constraints. Secure multi-year cockpit integration contracts with Chinese EV marques before domestic tier-one suppliers achieve UNECE certification parity. ISO 26262 functional safety validation investment represents the critical lever for maintaining OEM specification lock-in. For New Entrants and Emerging Players: The price-point gap between premium built-in systems and economy smartphone integration tiers opens white-space targeting for mid-market cloud gaming peripherals. India's aftermarket retrofit channel offers the most penetrable geography where factory gaming systems remain absent from mass-market vehicle segments. A controller-peripheral subscription bundling model bypasses thermal hardware development barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with edge computing cluster specialists bridging legacy CAN bus protocols with software-defined vehicle architectures. Five-to-ten year viability hinges on backward integration into GPU supply chains rather than pure software licensing. Watch for MIIT content licensing rule enforcement in China as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Tesla's vertical operating system stack demonstrates full gaming experience control without tier-one intermediation. |
| GPU Supply Agreement | Hyundai Motor Group secures Seoul Capital Area fab allocation for standard infotainment gaming across EV lineups. |
| Platform Integration Partnership | Harman International Industries co-develops audio-visual environments with Stuttgart and Munich premium marques. |
| Cybersecurity Certification Pathway | Continental anchors multi-OEM contracts through KBA type-approval for over-the-air gaming content delivery. |
| Geographic Manufacturing Footprint | South Korean and Taiwanese electronics clusters capture module assembly from European OEMs seeking UNECE compliance efficiency. |
Research Methodology
Bottom-up OEM platform modeling reconciled against top-down GPU supply tracking forms the analytical core of this study. Primary interviews with tier-one cockpit integration procurement officers, OEM platform engineers, aftermarket distribution channel heads, and thermal substrate fabrication specialists combined with secondary validation against vehicle production databases, IHS Markit registration data, MIIT content licensing filings, and UNECE WP.29 certification registries. Triangulation across these sources resolves discrepancies between announced platform deployments and actual silicon allocation.
Input-output matrices map gaming content demand across vehicle class, propulsion architecture, content per vehicle tier, and regional production cluster dimensions. CAGRs derive from segment-level unit economics applied across the projection horizon, with cloud gaming subscriber forecasts incorporating 5G network deployment trajectories from infrastructure operator disclosures. Thermal management component pricing feeds directly into built-in system cost curves.
Caveats apply where NHTSA driver-distraction rule revisions or MIIT content licensing enforcement shifts could materially shift the outlook. Semiconductor fabrication capacity constraints and Taiwan Strait logistics disruptions constitute specific automotive electronics supply risks. A small set of regulatory trigger events warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
India Automotive Lighting Market
Automotive Electronics & Wiring
Automotive Secondary Wiring Harness Market
Automotive Electronics & Wiring
Latin America Automotive Camera Market
Automotive Electronics & Wiring
UAE Automotive Sensors Market
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Split-View Camera Module Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
Automotive Data Cables Market
Automotive Electronics & Wiring
Automotive Surround View Systems Market
Automotive Electronics & Wiring
Connected Car Devices Market
Automotive Electronics & Wiring
Bluetooth in Automotive Market
Automotive Electronics & Wiring
Automotive Digital Cockpit Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market