
 Europe Automotive Exhaust Aftertreatment Systems Market | 2026-2036
Europe Automotive Exhaust Aftertreatment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Exhaust Aftertreatment Systems Market Foresight
Euro 7 certification is collapsing the supplier base eligible for OEM contracts. Continental AG leverages its integrated sensor-to-catalyst architecture to sustain program wins with German premium manufacturers. Johnson Matthey anchors the platinum group metals supply chain through captive refining partnerships in South Africa and Russia. Faurecia competes on manufacturing scale, operating twelve exhaust system plants across France, Spain, and the Czech Republic.
Automotive exhaust aftertreatment systems chemically convert harmful combustion byproducts into less toxic emissions through catalytic reduction, selective catalytic reduction using aqueous urea injection, and particulate filtration with silicon carbide or cordierite substrates operating at temperatures exceeding 550°C. Their primary purpose is enabling internal combustion engines to comply with mandated tailpipe emission limits while preserving fuel efficiency. SCR systems dominate value pools in heavy-duty applications where urea dosing precision determines compliance margins. Catalytic converters remain the volume backbone for passenger vehicles but face substitution pressure from hybrid powertrains. DPF technology differentiates in the aftermarket channel where regeneration cycle reliability drives replacement frequency.
The European Commission's Euro 7 framework, ECHA's REACH restrictions on platinum group metal sourcing, and the EU Green Deal's 2035 ICE phase-out deadline collectively compress product development cycles and raise material compliance costs. EMA coordination with national type-approval authorities fragments enforcement timelines across member states. Stakeholders must monitor how Germany's KBA and France's ANSM interpret Euro 7 testing protocols, as divergent implementation timelines will split procurement strategies between early-compliant and delayed-adopter OEMs.
Market Dynamics
Euro 7 emission standards are compressing development cycles across Europe's automotive exhaust aftertreatment supply base, forcing simultaneous hardware redesigns and material compliance overhauls while OEMs navigate divergent national implementation timelines.
Growth Catalysts
- Heavy-duty fleet electrification delays:Commercial vehicle operators in Poland and Germany are extending diesel platform lifecycles, sustaining demand for SCR system retrofits and DPF replacements as battery-electric alternatives face infrastructure gaps.
- REACH platinum group metal traceability:ECHA's expanded substance of very high concern listings are pushing OEMs toward certified supply chains, creating procurement premiums for refiners with documented provenance from South African and Russian operations.
- Silicon carbide substrate adoption:Advanced DPF architectures using SiC cores are penetrating premium passenger segments, enabling higher regeneration temperatures and extended service intervals that reduce total cost of ownership for fleet operators.
Market Restraints
- Palladium-rhodium price volatility:PGM spot market swings are compressing catalyst manufacturer margins, with Russian supply uncertainty forcing European fabricators to absorb hedging costs or pass through to OEM contracts.
- Substrate supply concentration:Cordierite and SiC monolith production clusters in Germany and the Czech Republic create geographic chokepoints, leaving exhaust system integrators exposed to single-source risks during plant maintenance cycles.
- Hybrid powertrain substitution:PHEV architectures with extended electric-only ranges are reducing per-vehicle catalyst loading requirements in Germany's Stuttgart manufacturing corridor, eroding volume foundations for conventional three-way catalyst suppliers.
Strategic Opportunities
- Aftermarket channel digitization:Independent garages across Spain and Italy are adopting diagnostic-linked parts procurement platforms, enabling predictive DPF replacement scheduling based on telematics-derived soot load data.
- Euro 7 early compliance certification:Suppliers achieving KBA type-approval ahead of mandatory deadlines can lock in multi-year platform contracts with German premium manufacturers seeking supply security during transition periods.
- Urea dosing precision electronics:Convergence of NOx sensors with machine learning-enabled injection algorithms is creating value pools in heavy-duty retrofit markets, where non-compliant legacy fleets face urban access restrictions in French and Italian low-emission zones.
Industry Challenges
- Ceramic engineering talent scarcity:Exhaust substrate manufacturers in France and the Czech Republic face recruitment gaps for high-temperature materials specialists capable of optimizing pore structures for next-generation gasoline particulate filters.
- Dual certification complexity:Suppliers must simultaneously validate hardware against Germany's KBA and France's ANSM testing protocols, with divergent RDE cycle interpretations forcing redundant validation programs and compressed launch windows.
- Legacy platform integration friction:Euro 7-compliant aftertreatment architectures require packaging volume increases that conflict with existing vehicle underbody layouts, demanding costly structural modifications to aging platform toolings at Wolfsburg and Stuttgart assembly plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Exhaust Aftertreatment Systems Market |
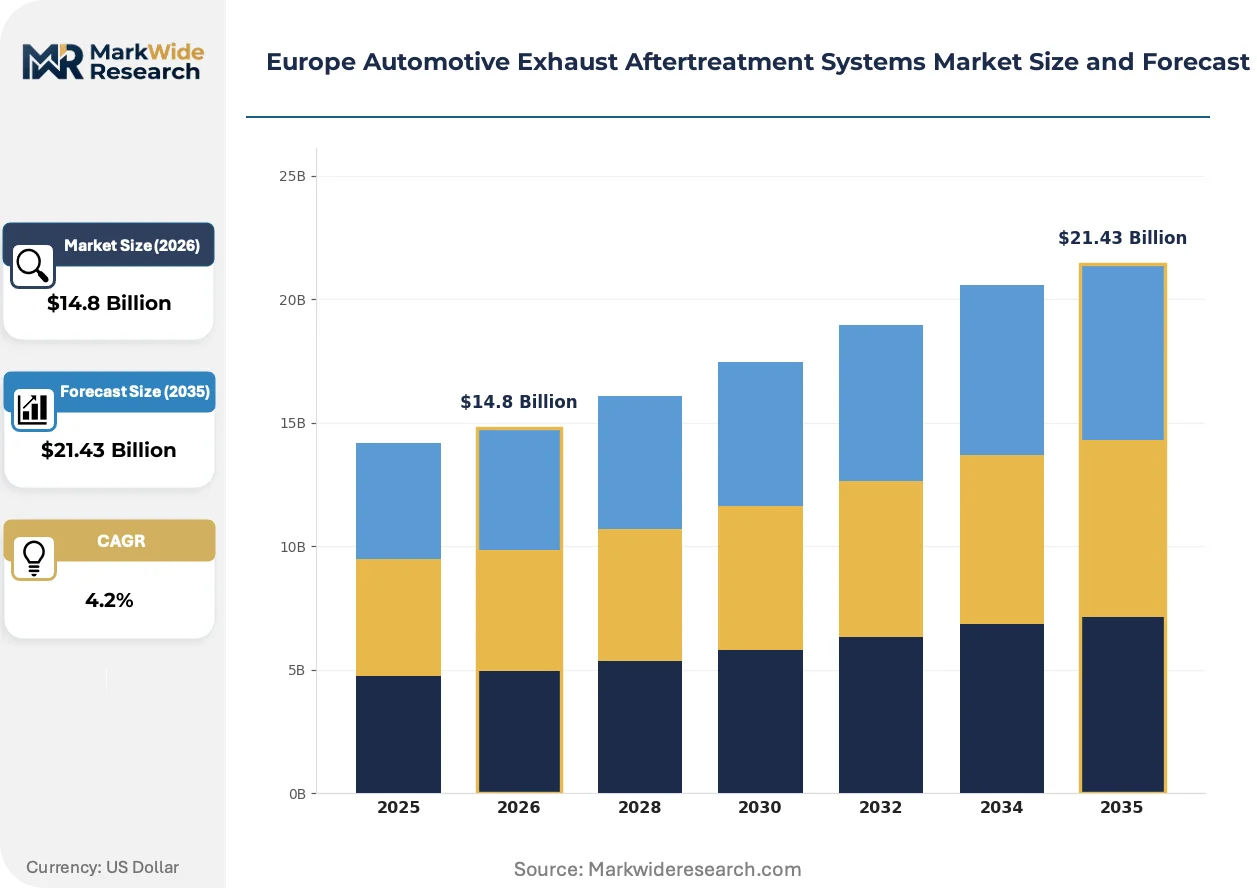
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.43 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SCR Systems, DPF, Catalytic Converters, Exhaust Gas Recirculation Technology: Passive, Active, Hybrid, Continuous Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Off-Road Equipment End User: OEMs, Aftermarket Providers, Fleet Operators, Distributors |
| Companies Covered | Continental AG, Faurecia, Johnson Matthey, Robert Bosch, Tenneco, Eberspächer, BASF SE, BorgWarner, Cummins, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Exhaust Aftertreatment Systems Market Shifts & Advancements
Active thermal management and predictive regeneration algorithms are displacing passive system architectures, while regulatory fragmentation between national type-approval authorities is splintering procurement strategies across the European supply base.
Gasoline particulate filters with asymmetric cell geometries are supplanting conventional symmetric substrates in direct-injection passenger vehicle applications. German premium OEMs are adopting these architectures for WLTP compliance, with the technology compressing catalyst volume requirements while maintaining filtration efficiency during urban cold-start cycles.
Euro 7's tightened PN and NOx limits are forcing hardware redesigns across all displacement categories. The regulation's expanded RDE boundary conditions are extending catalyst light-off responsibility to electric heating elements, with heavy-duty manufacturers in Poland and Germany accelerating development of 48V-powered pre-heating modules to guarantee compliance during low-load operation.
Fleet procurement teams are consolidating aftermarket service contracts around telematics-enabled condition monitoring. Independent garage networks in Italy and Spain are ceding diagnostic revenue to OEM-authorized channels as embedded sensors transmit DPF soot load data directly to manufacturer service platforms, bypassing traditional parts distribution intermediaries.
Europe Automotive Exhaust Aftertreatment Systems Market Segmentation
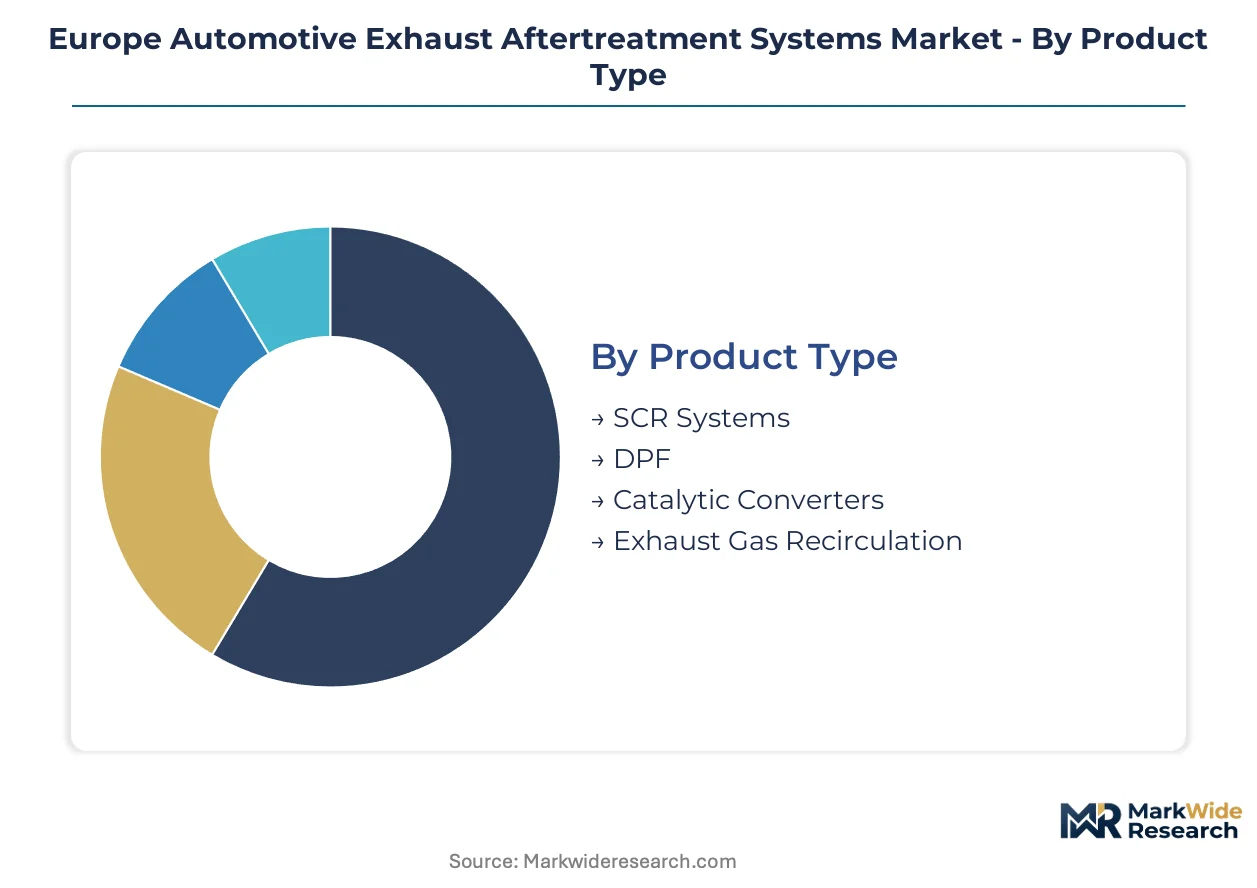
Exhaust aftertreatment systems fragment across hardware architectures, thermal management approaches, vehicle duty cycles, and procurement channels. Each dimension carries distinct margin structures and regulatory exposure profiles that reshape supplier positioning under Euro 7 timelines.
Product Type:
Margin pools concentrate in SCR system architectures where urea dosing precision commands procurement premiums from heavy-duty fleet operators facing urban access restrictions.
- SCR Systems:Aqueous urea injection architectures convert nitrogen oxides into nitrogen and water vapor through selective catalytic reduction. Polish and German commercial fleets sustain retrofit demand as battery-electric alternatives face charging infrastructure gaps. Euro 7's tightened NOx limits are forcing hardware redesigns with integrated NOx sensors and machine learning-enabled dosing algorithms.
- DPF:Diesel particulate filters trap soot particles in silicon carbide or cordierite substrates operating above 550°C. SiC cores penetrate premium passenger segments in Germany's Stuttgart manufacturing corridor, enabling extended regeneration intervals that reduce fleet total cost of ownership. Aftermarket replacement frequency concentrates in Italy and Spain where urban driving cycles accelerate ash accumulation.
- Catalytic Converters:Three-way catalysts oxidize carbon monoxide and unburned hydrocarbons while reducing nitrogen oxides in gasoline applications.
- Exhaust Gas Recirculation:EGR systems recirculate exhaust gases to lower combustion temperatures and reduce NOx formation at source.
SCR Systems hold installed capacity. DPF is rotating up the share rankings.
Technology:
Cost tier differentiation separates passive architectures from electronically controlled active systems, with hybrid approaches capturing mid-range value pools in transitional Euro 7 compliance windows.
- Passive:Systems rely on exhaust gas temperature and flow dynamics without electronic intervention. Cordierite substrates dominate this tier for cost-sensitive passenger vehicle applications in Spain and Italy where regeneration frequency tolerance runs higher.
- Active:Electronically controlled thermal management with fuel-borne catalysts or electric heating elements guarantees regeneration completion. German heavy-duty manufacturers in Poland accelerate 48V-powered pre-heating module development to satisfy Euro 7's expanded RDE boundary conditions during low-load operation.
- Hybrid:Combines passive substrate geometries with active thermal intervention for duty-cycle flexibility.
- Continuous:Non-cyclical filtration architectures using flow-through designs for specific gasoline direct-injection applications.
Active systems anchor revenue concentration. Hybrid configurations are climbing the fastest.
Application:
Volume distribution skews toward passenger vehicles while value-per-unit peaks in heavy-duty trucks where compliance margins determine fleet operating permissions.
- Heavy-Duty Trucks:Long-haul and urban distribution vehicles face the most stringent NOx and particulate number enforcement. SCR system retrofits dominate procurement in Germany and Poland as operators extend diesel platform lifecycles pending infrastructure for battery-electric alternatives.
- Passenger Vehicles:Gasoline particulate filters with asymmetric cell geometries supplant symmetric substrates for WLTP compliance. German premium OEMs adopt these architectures to maintain filtration efficiency during urban cold-start cycles while compressing catalyst volume requirements.
- Commercial Vehicles:Light and medium-duty vans and trucks with mixed urban-highway duty cycles.
- Off-Road Equipment:Construction and agricultural machinery subject to Stage V emission standards with distinct type-approval timelines.
Heavy-Duty Trucks command pricing power. Passenger Vehicles is rotating up the share rankings.
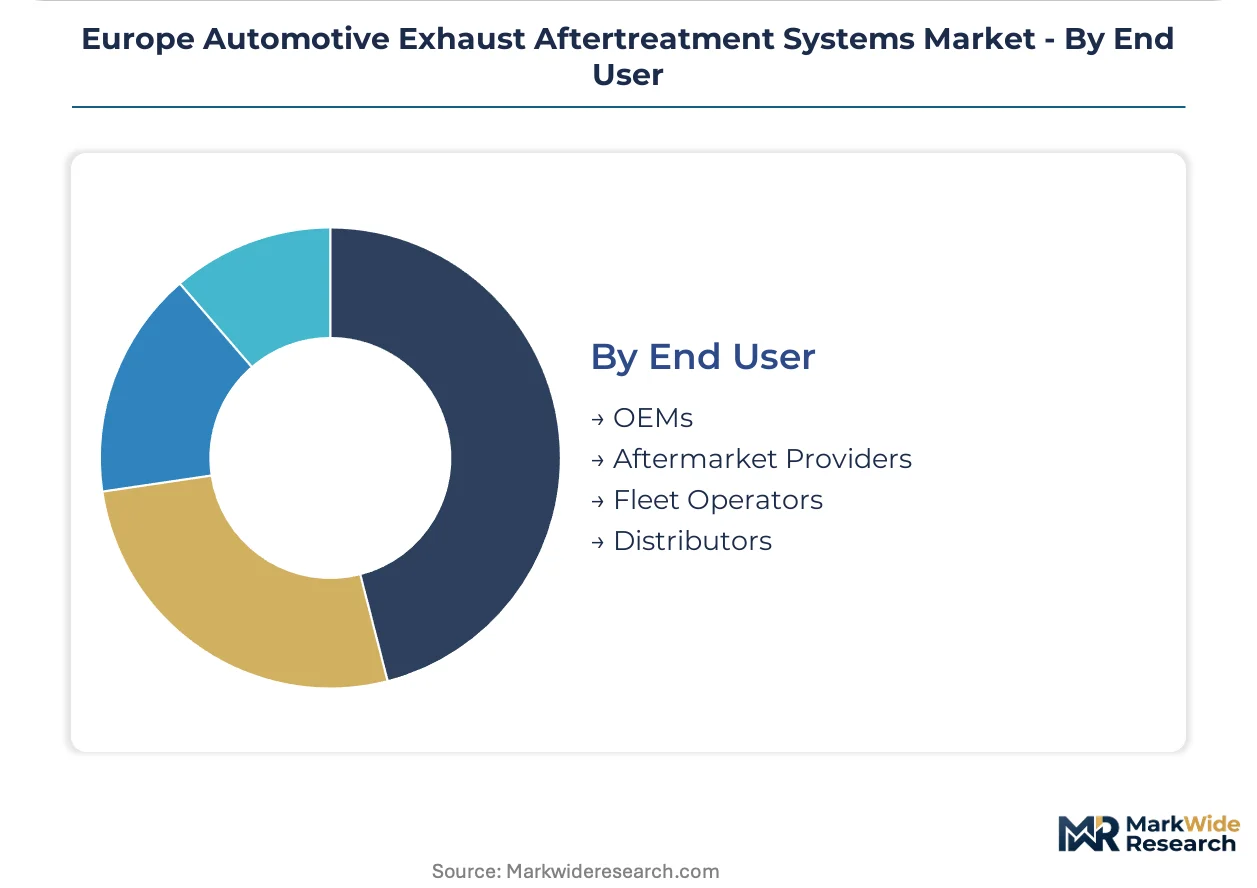
End User:
Customer type determines contract structure, with OEMs locking in multi-year platform agreements while aftermarket channels fragment toward telematics-linked service consolidation.
- OEMs:German premium manufacturers consolidate procurement around suppliers achieving KBA type-approval ahead of Euro 7 mandatory deadlines. Multi-year platform contracts reward integrated sensor-to-catalyst architectures that reduce validation redundancy.
- Fleet Operators:Commercial vehicle procurement teams consolidate aftermarket service contracts around condition monitoring platforms. Telematics-enabled soot load data transmission bypasses traditional parts distribution intermediaries in Italian and Spanish markets.
- Aftermarket Providers:Independent garage networks adopt diagnostic-linked parts procurement platforms for predictive DPF replacement scheduling.
- Distributors:Traditional wholesale channels facing margin compression from OEM-authorized service platform expansion.
OEMs hold installed capacity. Fleet Operators is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Euro 7 emission standards are forcing hardware redesigns across European manufacturing corridors, with national type-approval authorities creating divergent implementation timelines that split procurement strategies between early-compliant and delayed-adopter OEMs.
Germany
Commercial vehicle fleets in North Rhine-Westphalia and Baden-Württemberg are extending diesel platform lifecycles, sustaining demand for SCR retrofits. KBA testing protocols for Euro 7 certification are collapsing the eligible supplier base for OEM contracts. The Stuttgart-to-Wolfsburg manufacturing belt concentrates catalytic converter production for premium passenger segments.
Poland
Heavy-duty truck operators face urban access restrictions in Warsaw and Kraków low-emission zones, accelerating SCR system procurement. ECHA REACH restrictions on platinum group metal traceability push fleet procurement toward certified supply chains. Manufacturing clusters near Poznań assemble exhaust components for German OEM supply contracts.
France
ANSM interpretation of Euro 7 RDE testing protocols diverges from German KBA standards, forcing redundant validation programs. Faurecia operates exhaust system plants across Auvergne-Rhône-Alpes and Hauts-de-France. Parisian low-emission zones are tightening enforcement against non-compliant legacy commercial fleets.
Italy
Independent garage networks in Lombardy and Emilia-Romagna are adopting diagnostic-linked parts procurement platforms for predictive DPF replacement. EMA coordination with national type-approval authorities fragments enforcement timelines. Turin-based aftermarket distributors face margin compression from OEM-authorized service platform expansion.
Spain
Fleet operators in Catalonia consolidate aftermarket service contracts around telematics-enabled condition monitoring. Urban driving cycles in Barcelona and Madrid accelerate DPF ash accumulation, driving replacement frequency. Component assembly plants near Valencia supply exhaust substrates to French and German integrators.
Europe Automotive Exhaust Aftertreatment Systems Market Competitive Landscape
Player mix skews toward diversified automotive suppliers with captive catalyst manufacturing capabilities and integrated sensor-to-architecture competencies. Market structure concentrates around three strategic tiers: premium-tier specialists with KBA early-approval advantages, scale-driven fabricators with multi-plant European footprints, and PGM supply chain anchors with captive refining partnerships. Dominant competitive moves include geographic consolidation of substrate production and backward integration into platinum group metal sourcing.
Within the diversified supplier tier, Continental AG exemplifies integrated system architecture capabilities, while Faurecia represents manufacturing scale concentration across multiple European production sites. Johnson Matthey occupies a position anchoring precious metals supply chain security through documented provenance partnerships. These three entities collectively illustrate how Euro 7 compliance pressures are rewarding players with combined hardware design, materials sourcing, and regulatory validation competencies.
| Leading Market Players |
|---|
| Continental AG |
| Faurecia |
| Johnson Matthey |
| Robert Bosch |
| Tenneco |
| Eberspächer |
| BASF SE |
| BorgWarner |
| Cummins |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between German OEMs and PGM refiners lock in platinum group metal supply access while fixing price visibility across Euro 7 development cycles. These agreements insulate catalyst fabricators from spot market volatility while embedding REACH compliance premiums into contract structures.
Pricing Analysis
Certification level (KBA early-type-approval vs. standard compliance) creates the primary spread between premium and standard tier suppliers. Contract-based long-term offtake dominates hardware procurement, with price differentiation driven by REACH traceability documentation and integrated sensor-to-catalyst architecture bundling. Cost compression in cordierite substrate tiers is intensifying because of single-source concentration in Czech and German plants. Fleet operators exhibit highest price sensitivity in aftermarket DPF replacement, while premium OEMs absorb certification premiums for supply security.
Supply Chain Analysis
Strategic stockpiling of silicon carbide substrates prevails among German exhaust system integrators facing regeneration reliability requirements. Supply concentrates in Germany, the Czech Republic, and South Africa for cordierite monoliths, SiC cores, and platinum group metals respectively. Raw material dependencies rest on aqueous urea, palladium-rhodium catalyst formulations, and ceramic substrate precursors. Single-source vulnerability in German cordierite production exposes integrators during plant maintenance cycles. Distribution runs through OEM-authorized service platforms consolidating telematics-linked aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-enabled predictive maintenance contracts for DPF regeneration scheduling are expanding faster than hardware unit sales, creating recurring revenue layers that outpace one-time system procurement. Service-attach models now capture margin pools previously ceded to independent garage networks.
For Market Incumbents: Fortify PGM supply chain control through backward integration into South African refining partnerships before REACH traceability requirements harden. Expand captive SiC substrate production in the Czech Republic to reduce single-source exposure during Euro 7 validation windows. Hybrid powertrain substitution in Stuttgart's manufacturing corridor threatens three-way catalyst volume foundations. For New Entrants and Emerging Players: Anchor in aftermarket diagnostic platform development for Poland and Italy's fragmented independent garage networks. White-space concentrates in urea dosing precision electronics for heavy-duty retrofit markets facing urban access restrictions. Target telematics-linked parts procurement platforms as the most penetrable channel. Go-to-market through fleet operator direct contracts bypassing traditional distributor intermediaries. For Investors and Strategic Acquirers: Capital is best deployed toward integrated sensor-to-catalyst architects with KBA early-approval credentials and captive PGM sourcing. Long-term viability across the analysis window favors suppliers combining hardware design, materials provenance, and regulatory validation competencies. Watch for divergence between German KBA and French ANSM Euro 7 implementation timelines as the inflection signal splitting procurement strategies.| Strategic Initiative | Industry Significance |
|---|---|
| PGM Supply Chain Backward Integration | REACH traceability requirements reward refiners with documented South African and Russian provenance partnerships. |
| KBA Early-Type-Approval Certification | Early compliance locks multi-year platform contracts with German premium manufacturers during Euro 7 transition. |
| Telematics Platform Development | Predictive DPF replacement scheduling captures diagnostic revenue from Italian and Spanish independent garages. |
| SiC Substrate Capacity Expansion | Higher regeneration temperatures enable extended service intervals reducing fleet total cost of ownership. |
| Urea Dosing Precision Electronics | Machine learning-enabled injection algorithms create value pools in Polish and German heavy-duty retrofit markets. |
Research Methodology
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet maintenance directors anchored the qualitative base. Primary interviews combined with secondary validation from KBA type-approval filings, ECHA REACH substance registrations, vehicle production databases, and customs trade records. Bottom-up unit economics triangulated against top-down regulatory demand modeling.
Sensitivity analysis tested forecast robustness across PGM price volatility scenarios and divergent national Euro 7 implementation timelines. The analytical framework segmented by product type (SCR, DPF, catalytic converter), technology tier (passive, active, hybrid), application (heavy-duty, passenger, commercial), and end-user channel (OEM, fleet, aftermarket). CAGRs derived from regression against historical compliance-driven replacement cycles and projected fleet electrification delays. Industry-specific inputs included urea consumption intensity per vehicle class and substrate regeneration frequency by duty cycle.
Material uncertainties — regulatory enforcement fragmentation, PGM supply disruption, and hybrid powertrain penetration rates — sit outside the modeled envelope. Forecasts reflect assumptions about KBA-ANSM protocol convergence and REACH substance listing timelines. Revision becomes warranted when Euro 7 implementation delays exceed thresholds or PGM spot price spreads breach contract hedging bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Middle East and Africa Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Nitrogen Tire Inflators Market
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
Vehicle Health Monitoring Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
Automotive Repair and Maintenance Services Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
Car Care Products Market
Vehicle Maintenance & Aftermarket
Car Detailing Products Market