
 United Kingdom Vehicle Recycling Market | 2026-2036
United Kingdom Vehicle Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Vehicle Recycling Market Intelligence
Premium component recovery is decoupling from commodity metal shredding as quality standards tighten across the United Kingdom. ASM Auto Recycling Ltd. leverages its dismantling expertise to capture higher margins from electronics and plastics streams. Charles Trent Ltd. anchors its position through specialized refurbishment operations serving OEM return programs. CarTakeBack.com Limited competes via nationwide collection network density that controls end-of-life vehicle flow.
United Kingdom vehicle recycling encompasses the systematic decommissioning, dismantling, and material recovery of retired automobiles to reintroduce ferrous and non-ferrous metals, polymers, and rare earth elements into manufacturing supply chains, with shredder residue typically processed to recover 85-95% of vehicle mass. The process serves both environmental compliance and resource security objectives for British automotive and materials industries. Passenger cars dominate vehicle type inflows due to fleet turnover volumes, though commercial vehicles yield higher per-unit metal recoveries that concentrate margin pools. Dismantling leads recycling method value capture because intact component resale commands premiums over shredded material prices. Metals recovery within component streams sustains the largest revenue share, yet plastics reprocessing exhibits the fastest structural expansion as automotive lightweighting trends multiply polymer content per vehicle.
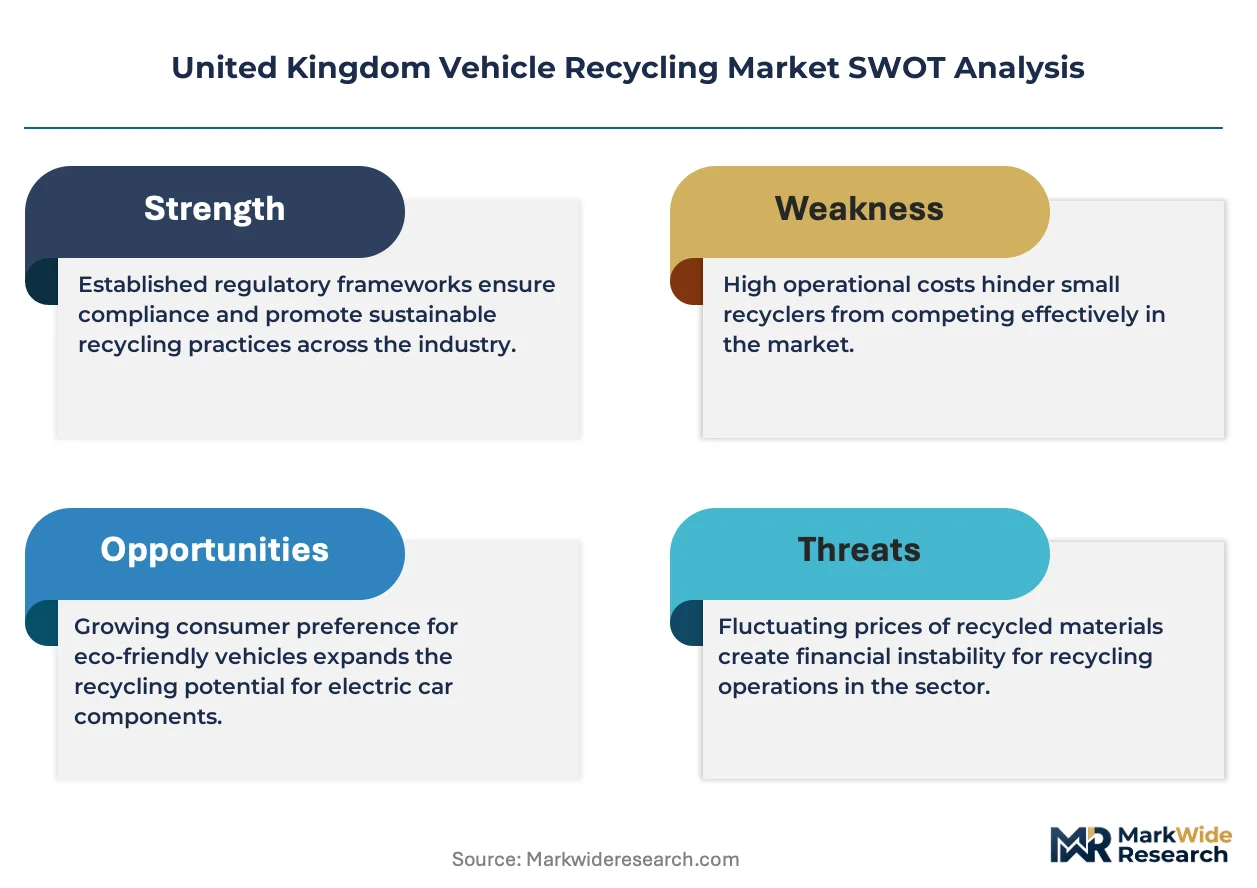
The UK's End-of-Life Vehicle Regulations and Environment Agency permitting frameworks mandate 95% recovery and 85% recycling rates, compelling operators to invest in advanced separation technologies or surrender market access. DVLA registration cancellation requirements and hazardous waste directives from the Environment Agency further shape operational compliance costs and facility siting decisions. Stakeholders must monitor proposed revisions to the UK REACH chemicals regime and emerging battery passport requirements that will redefine acceptable recovery pathways for electric vehicle components.
Market Dynamics
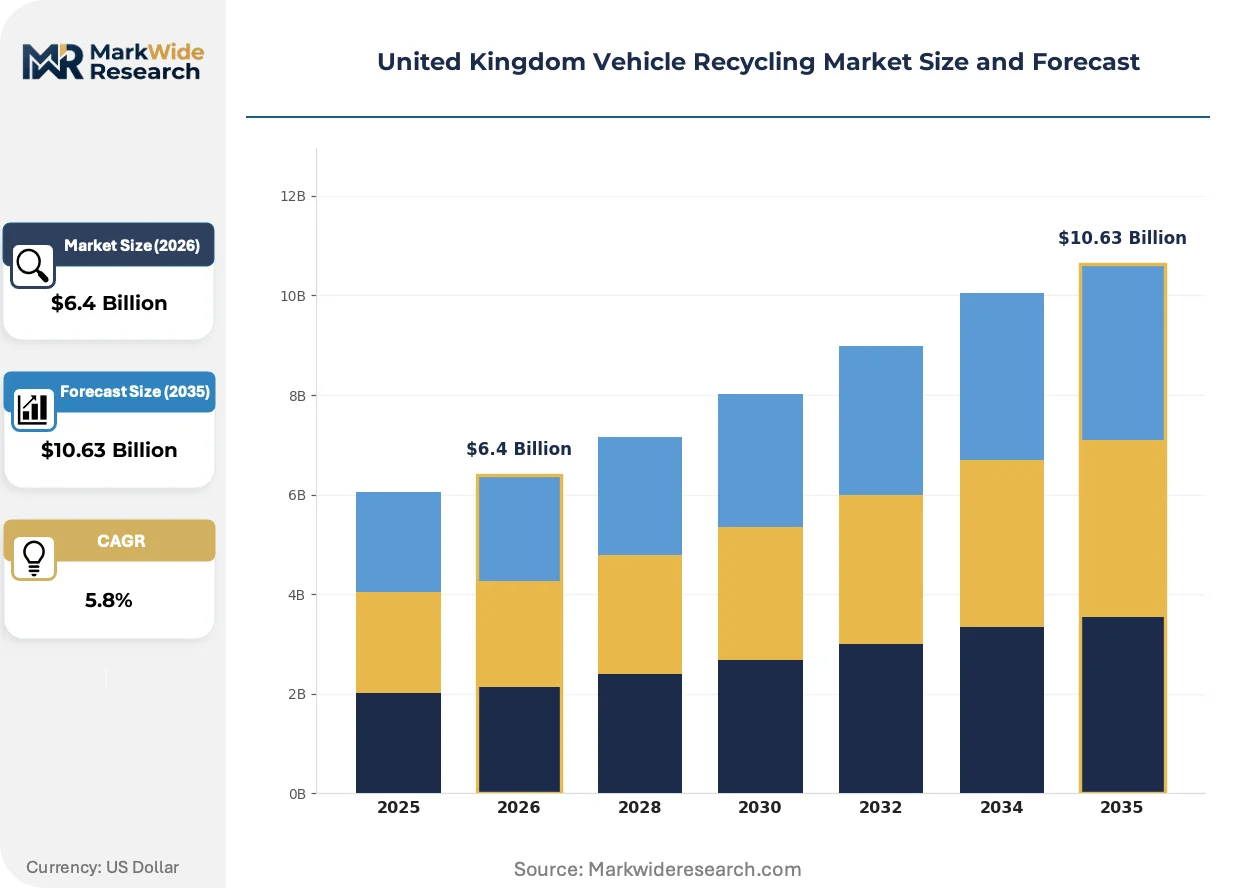
The United Kingdom vehicle recycling market is being fundamentally restructured by the Environment Agency's enforcement of 95% recovery and 85% recycling rates under End-of-Life Vehicle Regulations, which forces operators to deploy advanced separation technologies or exit the market entirely.
Growth Catalysts
- UK REACH chemicals regime:Proposed revisions to this framework are tightening material traceability requirements, compelling recyclers to invest in certified polymer recovery streams that command premium pricing from automotive OEMs.
- Aftermarket cost pressures:Independent repair networks across England's industrial corridor are expanding procurement of refurbished components as new part inflation squeezes margins, creating sustained demand for dismantled inventory.
- Electric vehicle battery passports:Emerging EU-UK alignment on battery lifecycle documentation is mandating recoverable material disclosure, positioning UK dismantlers with advanced lithium-ion processing capabilities for first-mover advantage.
Market Restraints
- Shredder residue processing costs:The technical complexity of extracting value from automotive shredder residue—containing mixed plastics, glass, and rubber—requires capital-intensive post-shredding separation that compresses margins for mid-scale operators.
- Scrap metal price volatility:Ferrous and non-ferrous commodity swings tied to Chinese import policies and Turkish steel demand create revenue unpredictability that constrains long-term investment planning.
- DVLA registration cancellation bureaucracy:Administrative delays in formal vehicle decommissioning extend holding costs for collection networks and create compliance gaps that expose operators to penalties.
Strategic Opportunities
- Wales and Scotland underpenetration:Shredding and reprocessing infrastructure concentrates in England's West Midlands, leaving Welsh and Scottish end-of-life vehicle flows dependent on long-haul transport to English facilities—creating regional hub development potential.
- Rare earth element recovery:Electric vehicle motor magnets and electronics assemblies contain neodymium and dysprosium concentrations that exceed primary ore grades, positioning specialized dismantlers for critical mineral supply security contracts.
- Component-as-a-service models:Subscription-based access to refurbished powertrain and electronic modules is displacing outright purchase in fleet management, opening recurring revenue streams for recyclers with refurbishment expertise.
Industry Challenges
- High-voltage technician certification:Safe handling of electric vehicle battery systems requires Level 3 IMI qualifications that remain scarce across the UK dismantling workforce, constraining EV processing capacity expansion.
- Permitting timeline compression:Environment Agency waste facility permits for new separation technologies face 18-24 month approval cycles that lag behind equipment innovation cycles, creating regulatory-capability mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Vehicle Recycling Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Buses Recycling Method: Shredding, Dismantling, Reprocessing, Refurbishing Component Recovery: Metals, Plastics, Electronics, Glass End User: OEMs, Aftermarket Providers, Scrap Dealers, Repair Shops |
| Companies Covered | Ampthill Metal Company, ASM Auto Recycling Ltd., Auto Spares & Salvage Limited, CarTakeBack.com Limited, Charles Trent Ltd., Copart UK Ltd., Go Green Vehicle Recycling & Recovery Ltd., LJC Auto Spares Ltd, Motorhog Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Vehicle Recycling Market Strategic Shifts & Innovations
Artificial intelligence-driven material identification and automated dismantling robotics are compressing labor dependency while improving recovery purity, fundamentally altering cost structures across the UK's vehicle recycling value chain.
Sensor-based sorting technology using near-infrared and X-ray fluorescence detection is integrating into post-shredding lines to isolate polymer grades and non-ferrous fractions with 98% purity rates. Major shredding operators in Birmingham and Coventry are retrofitting these systems to meet OEM material specifications for closed-loop manufacturing. This capability is integrating UK recyclers into European automotive supply chains previously dominated by primary material suppliers.
The Environment Agency's emerging guidance on persistent organic pollutants in vehicle shredder residue is tightening landfill diversion requirements and mandating thermal treatment or chemical recycling for contaminated fractions. This regulatory trajectory is accelerating capital deployment in pyrolysis and solvent-based purification technologies. Smaller operators without access to such infrastructure face consolidation pressure or contract processing arrangements with larger integrated facilities.
Fleet operators and leasing companies are unbundling end-of-life vehicle management from traditional disposal contracts, instead contracting directly with certified dismantlers for guaranteed recovery rates and carbon accounting documentation. This disintermediation of vehicle manufacturer take-back schemes is visible most acutely in corporate fleet renewals across London and the South East, where sustainability reporting requirements drive preference for transparent material flow documentation over lowest-cost disposal.
United Kingdom Vehicle Recycling Market Segmentation
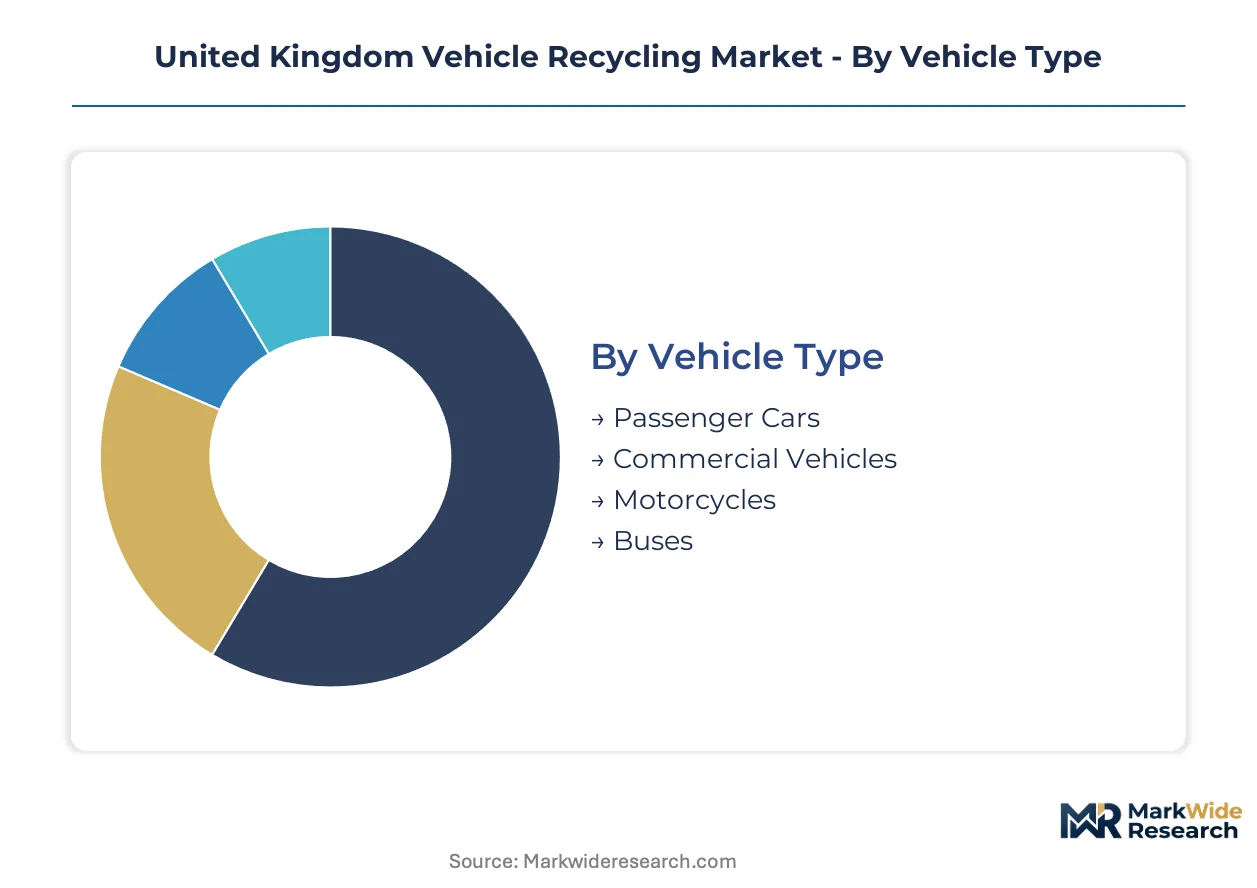
Segmentation in United Kingdom vehicle recycling reveals how capital deployment, regulatory compliance burdens, and margin structures vary dramatically across processing pathways. Understanding these divides explains why certain operators dominate specific value chain positions while others face consolidation pressure.
Vehicle Type:
Capital intensity escalates sharply with vehicle mass and hazardous material complexity, driving divergent facility investment strategies across the United Kingdom.
- Passenger Cars:High-volume, standardized construction enables automated shredding economies and consistent ferrous scrap grades. England's industrial Midlands processes the densest flows, with Birmingham and Coventry facilities optimized for compact vehicle geometries and rapid throughput cycles mandated by DVLA deregistration timelines.
- Commercial Vehicles:Heavy-duty chassis and powertrain components require specialized dismantling bays and extended processing windows. Fleet operators in the South East increasingly contract directly for guaranteed recovery rates, bypassing traditional scrap channels to secure carbon accounting documentation for corporate sustainability reporting.
- Motorcycles:Fragmented ownership patterns and dispersed collection geography compress margins through elevated logistics costs relative to recoverable material mass.
- Buses:Low annual retirement volumes and complex hazardous material profiles (refrigerants, seat foams) limit dedicated infrastructure investment, routing most units through adapted commercial vehicle facilities.
Passenger Cars absorb the bulk of installed capacity; Commercial Vehicles is expanding most quickly as fleet electrification accelerates specialized battery recovery demand.
Recycling Method:
Margin capture potential stratifies according to technical sophistication, with premium extraction commanding multiples over commodity processing.
- Dismantling:Manual component removal preserves functional integrity for resale into aftermarket channels. ASM Auto Recycling Ltd. and Charles Trent Ltd. anchor market position through electronics and plastics expertise that meets tightening UK REACH traceability requirements for certified polymer streams.
- Shredding:High-throughput metal liberation dominates mass recovery but faces margin compression from post-shredding residue treatment costs. Birmingham and Coventry operators are retrofitting sensor-based sorting to achieve 98% purity rates required for European automotive OEM closed-loop contracts.
- Reprocessing:Chemical and thermal treatment of shredder residue is gaining traction as Environment Agency landfill diversion rules tighten, though pyrolysis equipment cycles exceed permitting timelines.
- Refurbishing:Component-as-a-service models are displacing outright purchase in fleet management, creating recurring revenue for operators with Level 3 IMI qualified technicians capable of electric vehicle powertrain restoration.
Dismantling commands the highest margin per ton processed; Refurbishing is climbing the fastest as subscription-based fleet access models proliferate.
Component Recovery:
Material value concentration and separation technology requirements determine which recovery streams attract specialized investment versus commodity treatment.
- Metals:Ferrous and non-ferrous fractions sustain the largest revenue share through established smelter offtake agreements, though Chinese import policy volatility and Turkish steel demand swings create pricing unpredictability that constrains long-term capital planning.
- Plastics:Automotive lightweighting trends multiply polymer content per vehicle, with near-infrared and X-ray fluorescence detection enabling grade-specific isolation that commands premium pricing from manufacturers facing UK REACH compliance obligations.
- Electronics:Rare earth element concentrations in electric vehicle motor magnets and control modules exceed primary ore grades, positioning specialized dismantlers for critical mineral supply security contracts as battery passport documentation mandates expand.
- Glass:Contamination with laminated interlayers and embedded antennas limits closed-loop recycling, routing most automotive glass to secondary construction applications with lower value recovery.
Metals dominates current revenue composition; Plastics is gaining share fastest as polymer content per vehicle rises and separation technology costs decline.
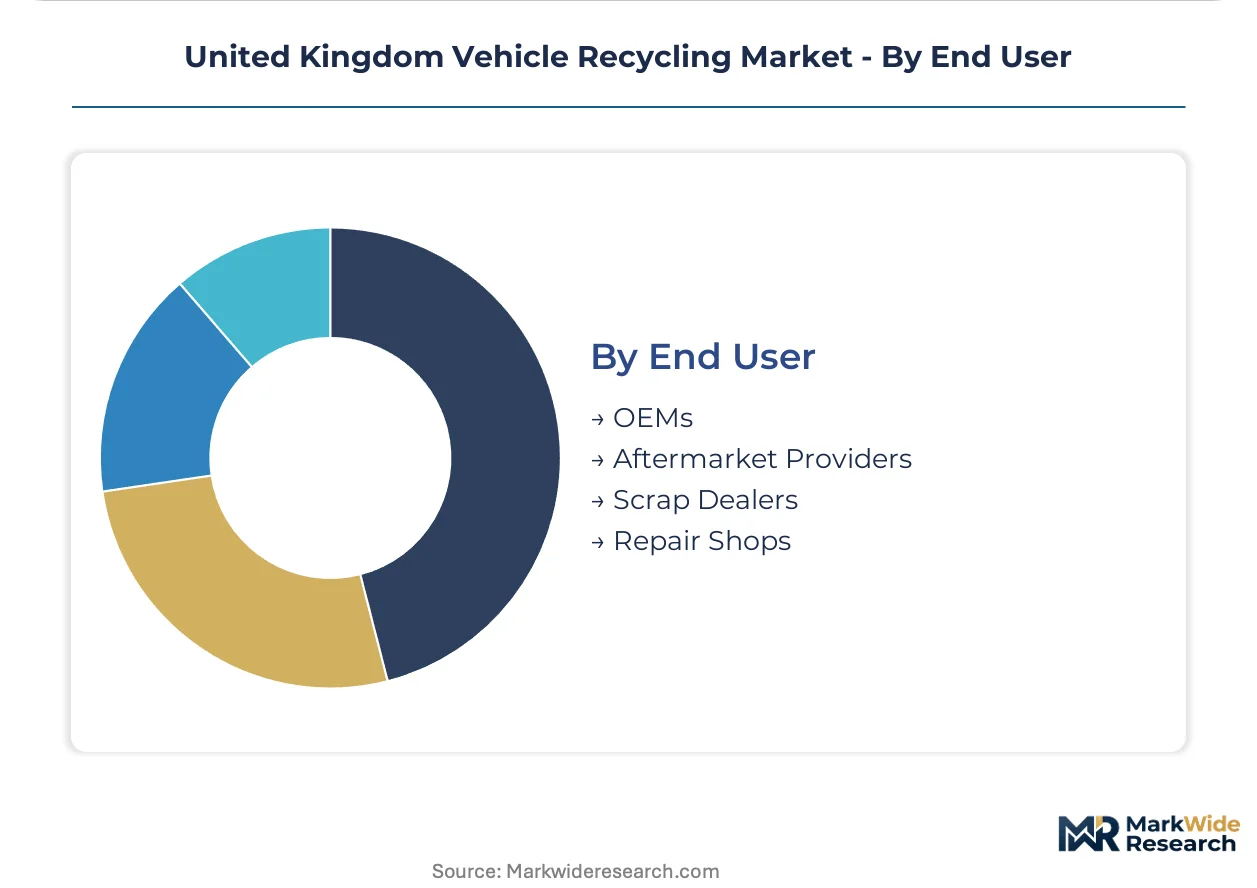
End User:
Procurement sophistication and compliance documentation requirements separate price-sensitive spot buyers from premium-contract partners.
- Aftermarket Providers:Independent repair networks across England's industrial corridor are expanding refurbished component procurement as new part inflation squeezes margins, creating sustained demand for dismantled inventory with verified provenance.
- OEMs:Return programs and closed-loop manufacturing commitments require certified material streams with full lifecycle documentation, favoring integrated dismantlers with advanced separation capabilities over commodity shredders.
- Scrap Dealers:Price-taking intermediaries face margin erosion as direct contracting between fleet operators and certified dismantlers disintermediates traditional collection networks.
- Repair Shops:Fragmented purchasing patterns and limited technical specification knowledge constrain premium pricing capture, though consolidation in national chains is elevating procurement sophistication.
Aftermarket Providers currently transact the highest volume; OEMs is expanding most quickly as manufacturer take-back schemes and carbon accounting requirements tighten supply chain integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Birmingham and Coventry anchor the United Kingdom's vehicle recycling infrastructure, hosting the densest concentration of shredding and reprocessing facilities that process end-of-life vehicle flows from across England's industrial corridor.
Midlands
Fleet turnover volumes from Birmingham's automotive manufacturing heritage sustain high-throughput dismantling operations. The Environment Agency's 95% recovery mandate under End-of-Life Vehicle Regulations compels operators to deploy advanced separation technologies. Coventry's shredding clusters retrofit sensor-based sorting systems to achieve purity rates required for OEM closed-loop contracts.
London and Southeast
Corporate fleet renewals drive demand for transparent material flow documentation and carbon accounting. DVLA registration cancellation requirements shape collection network logistics across Greater London. Specialist dismantlers in the M25 corridor contract directly with leasing companies for guaranteed recovery rates.
North England
Industrial vehicle retirement from Yorkshire's manufacturing base supports commercial vehicle dismantling specialization. The Environment Agency's hazardous waste directives influence facility siting decisions around Sheffield and Leeds. Regional operators face transport cost pressures moving shredder residue to Midlands reprocessing hubs.
Scotland
Scottish end-of-life vehicle flows depend on long-haul transport to English facilities due to shredding infrastructure gaps. The Scottish Environment Protection Agency enforces parallel recovery standards to UK-wide regulations. Glasgow and Edinburgh collection networks consolidate volumes for southbound shipment.
Wales
Welsh vehicle recycling capacity remains underdeveloped relative to generation volumes across South Wales industrial zones. Natural Resources Wales permitting frameworks govern facility expansion timelines. Newport and Cardiff operators explore regional hub development to reduce cross-border transport dependencies.
United Kingdom Vehicle Recycling Market Key Industry Players
Premium-margin players sit above commodity-margin players across dismantling expertise and component refurbishment capabilities. The market exhibits tiered concentration with integrated dismantler-refurbishers commanding multiples over pure-play shredders. Three archetypes dominate: certified component specialists serving OEM return programs, high-volume shredders with sensor-based sorting investments, and collection network operators controlling end-of-life vehicle flow geography. Consolidation pressure concentrates on mid-scale operators lacking advanced separation technologies, while strategic partnerships between dismantlers and fleet operators disintermediate traditional scrap channels.
Among UK-based operators, ASM Auto Recycling Ltd. and Charles Trent Ltd. exemplify the premium dismantling archetype through specialized refurbishment capabilities, while CarTakeBack.com Limited occupies a position within the collection network tier. These three companies represent distinct competitive vectors: component expertise, OEM program integration, and geographic density in vehicle flow control.
| Leading Market Players |
|---|
| Ampthill Metal Company |
| ASM Auto Recycling Ltd. |
| Auto Spares & Salvage Limited |
| CarTakeBack.com Limited |
| Charles Trent Ltd. |
| Copart UK Ltd. |
| Go Green Vehicle Recycling & Recovery Ltd. |
| LJC Auto Spares Ltd |
| Motorhog Ltd. |
| Others |
Cost & Logistics Intelligence
The Environment Agency's 95% recovery mandate gates qualified supply and premium-tier pricing access, as only operators with advanced separation technologies command OEM closed-loop contracts while commodity shredders face margin compression from residue treatment costs.
Pricing Analysis
Outcome-based pricing tied to certified material recovery rates anchors premium tiers, with dismantlers commanding multiples over shredders through verified polymer streams meeting UK REACH traceability requirements. Price differentiation rests on certification grade and volume scale, as fleet operators pay premiums for carbon accounting documentation. Cost compression in commodity metal recovery is intensifying because Chinese import policy volatility erodes long-term contract viability. Aftermarket repair networks exhibit highest price sensitivity, while OEMs demonstrate lowest sensitivity due to closed-loop manufacturing commitments.
Supply Chain Analysis
Regional distribution centers in Birmingham and Coventry operate hub-and-spoke patterns that consolidate flows from Scotland, Wales, and North England before reprocessing. Geographic supply concentrates in England's West Midlands, with shredding infrastructure drawing from Welsh and Scottish vehicle generation. Raw material dependencies rest on ferrous scrap grades, polymer feedstocks, and lithium-ion battery chemistries. Single-source vulnerability to Midlands processing capacity creates systemic risk. Distribution runs through direct fleet operator contracts that disintermediate traditional scrap dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom vehicle recycling market sits in a technology-transition phase, as sensor-based sorting and automated dismantling robotics displace manual labor-dependent recovery methods.
For Market Incumbents: To counter mid-scale operator consolidation pressure, deploy capital in pyrolysis and solvent-based purification technologies ahead of Environment Agency landfill diversion rule tightening. Acquire Level 3 IMI qualified technician capacity to capture electric vehicle battery processing premiums before workforce scarcity constrains expansion. For New Entrants and Emerging Players: Premium-economy tier price-point gaps in Welsh and Scottish regional hub development offer white-space entry, as long-haul transport dependencies create margin capture opportunities for localized shredding investment. Target fleet operator direct contracting channels with guaranteed recovery rate offerings as vehicle manufacturer take-back schemes face disintermediation. For Investors and Strategic Acquirers: Environment Agency permitting timeline compression for advanced separation technologies is the leading indicator that regulatory-capability mismatches will accelerate distressed asset availability. Long-term viability over the next decade favors integrated dismantler-refurbishers with rare earth element recovery capabilities. Watch for battery passport documentation mandate alignment between EU and UK regulators as inflection signal for lithium-ion processing capacity valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Based Sorting Deployment | Enables 98% purity rates required for European automotive OEM closed-loop manufacturing contracts. |
| Pyrolysis Capacity Buildout | Addresses Environment Agency emerging guidance on persistent organic pollutants in shredder residue streams. |
| Level 3 IMI Technician Certification | Unlocks electric vehicle high-voltage battery processing capacity constrained by workforce scarcity. |
| Regional Hub Development | Reduces Welsh and Scottish cross-border transport dependencies to English Midlands facilities. |
| Component-as-a-Service Launch | Captures recurring revenue from fleet management subscription models displacing outright powertrain purchase. |
Research Approach
Trade association filings, Environment Agency permitting records, and DVLA registration databases formed the secondary backbone, supplemented by primary interviews with dismantling facility operators, OEM sustainability procurement leads, aftermarket component distributors, and fleet management executives. Bottom-up and top-down triangulation validated volume estimates across vehicle type, recycling method, and component recovery segments.
Bottom-up modeling anchored the analytical lens, with top-down cross-checks against macro vehicle retirement projections. Segmentation dimensions spanned vehicle class, recycling method sophistication, material recovery stream, and end-user procurement archetype across the analysis window. CAGRs were derived from fitted trend analysis incorporating DVLA deregistration velocity, polymer content per vehicle trajectories, and battery electric vehicle fleet penetration assumptions.
Inputs from regulatory filing databases and trade flow statistics were available through the study window; gaps in real-time shredder residue processing cost reporting introduce uncertainty bands around margin structure projections. Forecasts reflect documented assumptions regarding Environment Agency rulemaking timelines and EU-UK regulatory alignment trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Engine Module-Level Repair and Refurbishment Services Market
Vehicle Maintenance & Aftermarket
Car Polisher Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
Europe Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market
Vehicle Maintenance & Aftermarket
Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market
Vehicle Maintenance & Aftermarket
Highway Maintenance Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market