
 Automotive Repair and Maintenance Services Market | 2026-2036
Automotive Repair and Maintenance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Repair and Maintenance Services Market Analysis
Fleet buyer concentration is consolidating across North American and European commercial vehicle operators, pushing volume toward national account contracts with multi-location service networks. LKQ Corporation anchors its position through aftermarket parts distribution integration that lowers repair cycle times for collision and mechanical shops. Robert Bosch GmbH leverages its Bosch Car Service franchise system to standardize diagnostic equipment and technician training across affiliated workshops. Mobivia Groupe competes through its Norauto and Midas banners, combining retail parts sales with scheduled maintenance bays in European hypermarket locations.
Automotive repair and maintenance services encompass mechanical restoration, preventive servicing, and diagnostic correction performed on vehicle powertrain, chassis, electrical, and body systems to sustain roadworthiness and extend operational life. The activity spans fluid replacement, component refurbishment, software calibration, and structural repair using OEM-specified or equivalent aftermarket parts, typically governed by manufacturer service intervals and regulatory safety standards. Engine diagnostics and brake repair within the service type dimension command disproportionate margin pools due to safety-critical regulatory inspection requirements and specialized tooling barriers. Electric vehicle servicing within the technology segment is expanding fastest as battery thermal management, high-voltage isolation protocols, and regenerative system maintenance create certified technician scarcity that protects pricing for early-qualified providers.
FAA vehicle safety directives for commercial ground support equipment, EPA emissions testing mandates under the Clean Air Act, and NHTSA recall enforcement mechanisms collectively elevate documentation and technical compliance burdens across US service operations. The EU Green Deal's end-of-life vehicle directives and REACH chemical restrictions on brake fluids and refrigerants are reshaping parts procurement and waste disposal protocols for European workshops. Stakeholders must monitor how software-defined vehicle architectures shift warranty control toward OEM cloud platforms and determine whether independent shops can retain diagnostic access as over-the-air updates centralize repair authorization.
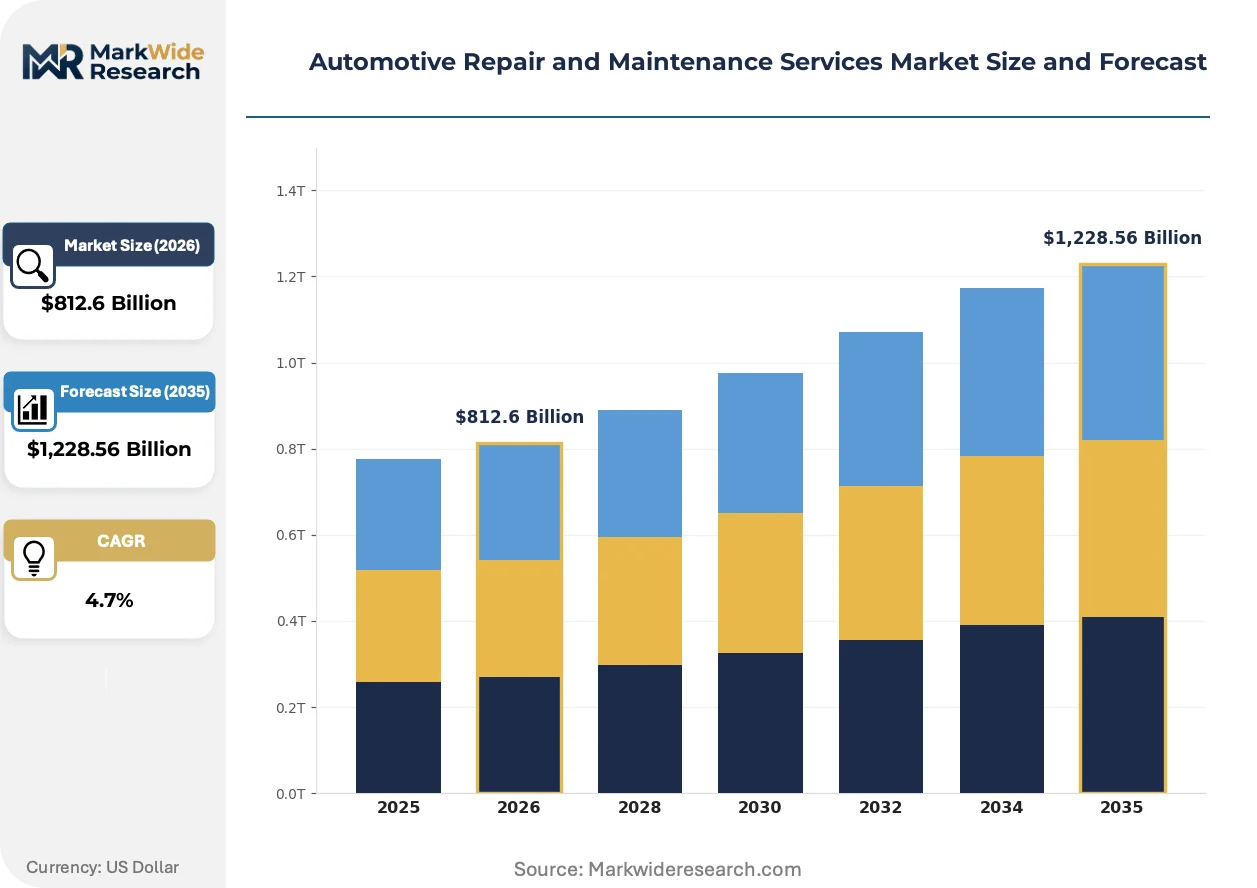
Market Dynamics
Software-defined vehicle architectures are transferring diagnostic authority from physical service bays to OEM-controlled cloud platforms, forcing independent workshops to negotiate subscription-based tool access while fleet operators consolidate purchasing power through national account structures.
Growth Catalysts
- OBD-III Readiness Mandates:EPA emissions enforcement in the United States is elevating diagnostic service complexity and pulling volume toward certified providers with advanced scan tool capabilities.
- Fleet Uptime Requirements:Commercial vehicle operators are tightening service level agreements and expanding multi-location contracts with national repair networks to minimize downtime penalties.
- Stuttgart-Munich Aftermarket Cluster:Germany's concentrated independent workshop and OEM-certified chain competition is driving service innovation and technician training investments across aging vehicle parc maintenance.
Market Restraints
- Specialized Tooling Barriers:Engine diagnostics and brake repair require capital-intensive equipment that locks out smaller independent operators from high-margin safety-critical work.
- Certified Technician Scarcity:High-voltage isolation protocols and battery thermal management for electric vehicles are creating qualified labor bottlenecks that limit service capacity expansion.
- REACH Chemical Restrictions:European workshops face reformulation costs and disposal protocol changes for brake fluids and refrigerants under EU chemical regulations.
Strategic Opportunities
- EV Maintenance White Space:Battery system servicing and regenerative brake maintenance present first-mover advantages for early-qualified providers in certified technician markets.
- Hypermarket Service Bays:Retail parts sales integration with scheduled maintenance locations is capturing convenience-driven consumer segments in European automotive retail.
- Over-the-Air Update Revenue:Software calibration services and subscription diagnostic access represent emerging revenue streams as OEMs centralize vehicle firmware control.
Industry Challenges
- High-Voltage Certification Timelines:Electric vehicle technician qualification programs require extended training periods that lag behind vehicle deployment rates and constrain service supply.
- Cloud Platform Access Negotiations:Independent workshops face deteriorating bargaining positions as OEMs gate diagnostic data behind proprietary subscription services and authorized network requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Repair and Maintenance Services Market |
| Market Size in 2026 | $812.6 Billion |
| Market Size in 2035 | $1,228.56 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Oil Change, Brake Repair, Tire Rotation, Engine Diagnostics End User: Private Vehicle Owners, Fleet Managers, Dealerships, Workshops Technology: Automated Systems, Advanced Diagnostics, Hybrid Technology, Electric Vehicle Servicing Product Type: Engine Components, Brake Systems, Electrical Parts, Tires |
| Companies Covered | Belron International Limited, Midas, LKQ Corporation, Mobivia Groupe, Caliber Collision, Robert Bosch GmbH (Bosch Car Service), Jiffy Lube International, Vehicle Service Group, Driven Brands Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Repair and Maintenance Services Market Emerging Trajectories
Diagnostic equipment, service delivery formats, and technician qualification pathways are undergoing simultaneous restructuring as electrification and connected vehicle architectures redefine what constitutes automotive repair expertise.
Remote diagnostic platforms are modularizing how vehicle health monitoring integrates with physical service scheduling. Fleet operators and multi-location service networks are adopting cloud-connected scan tools that pre-stage parts and labor before a vehicle reaches the bay. This architecture is compressing repair cycle times and shifting competitive advantage toward data-integrated service providers.
EPA emissions testing mandates under the Clean Air Act are tightening documentation requirements for diagnostic service records and repair verification protocols. Workshops must now maintain auditable digital trails linking scan tool outputs to specific technician actions and parts installations. California's Air Resources Board enforcement patterns are spreading to other state-level regulators and elevating compliance infrastructure costs across US service operations.
Buyer concentration among national fleet accounts is consolidating purchasing authority and unbundling traditional dealer-tied maintenance relationships. Large commercial vehicle operators are issuing request-for-proposal contracts that specify multi-state coverage, guaranteed uptime metrics, and standardized invoicing formats. This procurement evolution is most visible across North American long-haul trucking and last-mile delivery fleets where total cost of ownership calculations now dominate supplier selection criteria.
Automotive Repair and Maintenance Services Market Segmentation
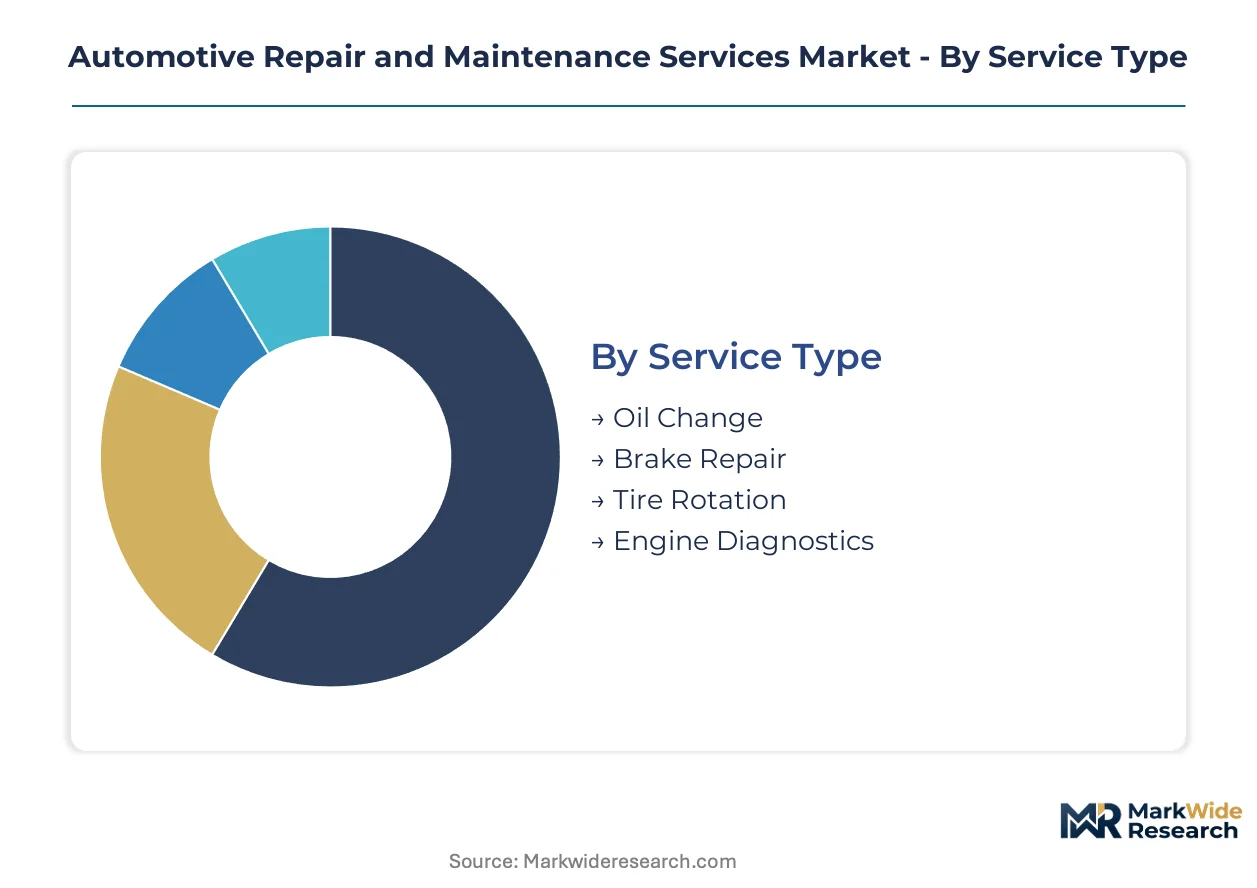
Service differentiation across the automotive repair and maintenance services market determines margin capture, technician specialization requirements, and capital investment intensity. Segmentation reveals how diagnostic complexity, electrification transitions, and fleet procurement centralization reshape competitive positioning across distinct service categories.
Service Type:
Supply concentration in specialized tooling and certified technician pools fragments competitive intensity across routine versus complex maintenance procedures.
- Engine Diagnostics:Advanced scan tool protocols and emissions verification software define this segment. Fleet operators in Germany's Stuttgart-Munich corridor prioritize providers with EPA-aligned documentation capabilities for commercial vehicle compliance.
- Brake Repair:Safety-critical regulatory inspection mandates elevate margin structures through specialized equipment barriers. Independent workshops in the United States face NHTSA recall enforcement mechanisms that pull volume toward certified national networks.
- Oil Change:High-frequency, low-margin maintenance standardized across quick-lube chains and hypermarket service bays.
- Tire Rotation:Seasonal demand cycles and wheel alignment integration define regional workshop scheduling patterns.
Today's leader: Engine Diagnostics. Tomorrow's challenger: Brake Repair.
End User:
Procurement centralization among commercial operators is displacing fragmented individual consumer purchasing across service network selection criteria.
- Fleet Managers:Multi-location contract structures and guaranteed uptime specifications dominate commercial vehicle service procurement. Long-haul trucking operators in the United States consolidate purchasing through national account agreements with standardized invoicing formats.
- Private Vehicle Owners:Convenience-driven selection patterns favor retail-integrated service locations with transparent pricing and appointment scheduling.
- Dealerships:Warranty-tied maintenance relationships and OEM diagnostic tool exclusivity protect service volume for newer vehicle parc.
- Workshops:Independent repair facilities compete through technician specialization and aftermarket parts sourcing flexibility.
Volume concentrates with Fleet Managers. Margin protection sits with Dealerships.
Technology:
Certification scarcity and training infrastructure gaps create tiered competitive access across electrification and automation service capabilities.
- Electric Vehicle Servicing:High-voltage isolation protocols and battery thermal management systems demand extended technician qualification programs. Early-qualified providers in Germany capture pricing premiums as vehicle deployment outpaces certified labor supply.
- Advanced Diagnostics:Cloud-connected scan tools and remote health monitoring integrate physical service scheduling with predictive maintenance algorithms.
- Automated Systems:ADAS calibration and sensor alignment services expand with advanced driver assistance feature penetration.
- Hybrid Technology:Dual powertrain maintenance combines internal combustion service protocols with electrified component handling procedures.
Electric Vehicle Servicing is climbing the fastest. Advanced Diagnostics holds installed base depth.
Product Type:
Parts procurement integration and inventory velocity differentiate service providers across component replacement and refurbishment categories.
- Electrical Parts:Software-defined vehicle architectures elevate module replacement complexity and OEM authorization requirements.
- Engine Components:Powertrain refurbishment and remanufacturing services extend vehicle operational life for aging parc maintenance.
- Brake Systems:Pad and rotor replacement cycles align with regulatory inspection intervals and safety-critical performance standards.
- Tires:Seasonal replacement demand and wheel alignment services drive recurring revenue patterns in consumer-facing locations.
Electrical Parts is gaining share fastest. Engine Components anchors current revenue pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States fleet operators consolidate purchasing power faster than German independents can scale certified networks, creating divergent competitive dynamics across the Atlantic repair landscape.
United States
Commercial vehicle uptime mandates and long-haul trucking density pull volume toward national account structures. EPA emissions enforcement under the Clean Air Act elevates documentation burdens for diagnostic service records. The Midwest industrial corridor spanning Illinois, Michigan, and Ohio anchors collision repair and mechanical refurbishment capacity for aging vehicle parc.
Germany
Independent workshop density and OEM-certified chain competition concentrate service innovation investments. EU Green Deal end-of-life vehicle directives reshape parts procurement and waste disposal protocols. The Stuttgart-Munich aftermarket cluster drives technician training standards for powertrain diagnostics and electrified system maintenance.
China
Electric vehicle deployment rates outpace certified technician qualification programs, creating qualified labor bottlenecks. MIIT standards for new energy vehicle servicing establish high-voltage isolation protocol requirements. The Yangtze River Delta manufacturing belt concentrates battery thermal management service demand near production facilities.
Japan
Precision manufacturing heritage sustains advanced driver assistance system calibration demand. METI regulations on automotive software updates influence cloud-based diagnostic access frameworks. The Kanto region surrounding Tokyo maintains dense networks of specialized electrical system repair facilities.
India
Two-wheeler and commercial vehicle parc expansion drives preventive maintenance volume growth. BIS standards for automotive components elevate quality verification requirements for replacement parts sourcing. The Maharashtra-Gujarat industrial corridor concentrates multi-brand service networks for fleet operators.
Automotive Repair and Maintenance Services Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented national account and independent workshop tiers. Parts distribution integration anchors scale advantages for collision and mechanical repair cycle compression. Three archetypes dominate: aftermarket parts distributors with service network ties, franchise-system operators standardizing technician training, and retail-integrated maintenance providers capturing convenience-driven segments. Consolidation through multi-location contract acquisitions and diagnostic equipment standardization represents the dominant competitive trajectory.
Within the franchise-system tier, Robert Bosch GmbH exemplifies equipment and training standardization across affiliated workshops. LKQ Corporation occupies a position representing parts distribution integration with repair network density. Mobivia Groupe sits within the retail-integrated archetype, combining parts sales with scheduled maintenance capacity. These three anchors illustrate how divergent strategic positions—equipment control, supply chain capture, and consumer convenience—compete for overlapping service demand pools without requiring identical capability investments.
| Leading Market Players |
|---|
| Belron International Limited |
| Midas |
| LKQ Corporation |
| Mobivia Groupe |
| Caliber Collision |
| Robert Bosch GmbH (Bosch Car Service) |
| Jiffy Lube International |
| Vehicle Service Group |
| Driven Brands Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Software-defined vehicle architectures are simultaneously compressing diagnostic labor costs and concentrating tool authorization within OEM cloud platforms, reshaping how service providers capture margin across physical and digital maintenance workflows. Fleet procurement centralization in the United States and Germany is amplifying volume discounts while certified technician scarcity protects pricing premiums for high-voltage EV servicing.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing belt are reshaping price floors for battery thermal management components and diagnostic modules. Three-tier pricing structure across premium, standard, and economy levels separates OEM-authorized networks with proprietary scan tool access from independent workshops using aftermarket equipment. Cost compression in routine maintenance runs through quick-lube chains and hypermarket service bays as volume scale offsets thin per-service margins. Fleet managers exhibit lowest price sensitivity due to uptime guarantee penalties, while private vehicle owners drive competitive intensity through convenience-driven selection.
Supply Chain Analysis
Workforce availability constraints in Germany, the United States, and China are tightening procurement timelines for certified technicians and specialized diagnostic equipment. Parts sourcing draws from Mexico for collision components, China for electrical modules, and Germany for precision powertrain elements. Single-source vulnerability concentrates in OEM-exclusive diagnostic software licenses that gate independent workshop access. Distribution runs through national account structures for fleet operators and franchise networks for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as commercial vehicle uptime requirements and EPA emissions enforcement elevate specifications toward certified, documented service tiers.
For Market Incumbents: Hedge against cloud platform lockout by negotiating multi-year diagnostic data access agreements with OEMs before subscription terms harden. Deepen backward integration into remanufactured parts sourcing to compress repair cycle times for collision and mechanical shops facing national account pricing pressure.
For New Entrants and Emerging Players: Capture white space in electric vehicle battery servicing across China's Yangtze River Delta and Germany's Stuttgart-Munich corridor where certified technician deployment lags vehicle parc growth. Target fleet operators with guaranteed uptime contracts and standardized digital reporting that aligns with EPA documentation mandates.
For Investors and Strategic Acquirers: Roll-up economics work for regional multi-location service networks because fleet procurement centralization favors scale players with geographic coverage density. Long-term viability hinges on diagnostic data access rights rather than physical bay count alone. Monitor OEM cloud platform subscription pricing announcements as inflection indicators for independent workshop margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| EV Technician Certification Investment | High-voltage qualification programs protect pricing power as battery deployment outpaces labor supply. |
| OEM Diagnostic Data Partnership | Cloud platform access agreements secure independent workshop competitiveness against authorized network exclusivity. |
| Fleet National Account Expansion | Multi-location contracts with uptime guarantees capture commercial vehicle procurement centralization. |
| Remanufactured Parts Integration | In-house refurbishment capacity lowers repair cycle times and parts procurement costs. |
| Hypermarket Service Bay Rollout | Retail-integrated maintenance locations capture convenience-driven consumer segments in European automotive retail. |
Methodological Framework
Direct dialogue with fleet operations directors, independent workshop owners, OEM service network managers, and aftermarket parts distributors anchored qualitative findings in operational realities. Secondary validation drew from EPA enforcement records, NHTSA recall databases, EU Green Deal implementation reports, and vehicle registration data from Germany's KBA and China's MIIT. Bottom-up service volume estimates triangulated against top-down fleet expenditure analysis across the projection horizon.
Bottom-up modeling segmented the market by service type, end user archetype, technology tier, and product category, with regional production clusters and regulatory framework as cross-cutting dimensions. CAGRs were derived from technician supply forecasts, vehicle parc aging curves, and fleet contract expansion patterns throughout the forecast period. Industry-specific inputs included OBD-III readiness timelines, REACH chemical restriction implementation phases, and high-voltage certification program graduation rates.
Underlying measurement precision varies by segment; engine diagnostics and brake repair carry tighter precision than emerging electric vehicle servicing categories where technician supply data remains sparse. Forecasts reflect assumptions about OEM cloud platform access terms, EPA enforcement intensity, and fleet uptime penalty structures. Practitioners should monitor NHTSA software-defined vehicle guidance, EU battery regulation secondary legislation, and fleet RFP issuance patterns for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Car Detailing Products Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Fuel Additives Market
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market
Vehicle Maintenance & Aftermarket
Catenary Maintenance Vehicle Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
Silicone in Car Care Products Market
Vehicle Maintenance & Aftermarket
US Car Care Products Market
Vehicle Maintenance & Aftermarket
Vehicle Health Monitoring Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market