
 Vehicle Networking Market | 2026-2036
Vehicle Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Networking Market Analysis
Over-the-air software update subscriptions is pivoting vehicle networking from hardware-centric sales to recurring revenue models. NXP Semiconductors leverages its broad automotive semiconductor portfolio to anchor connectivity solutions across multiple vehicle tiers. Continental AG sustains engineering depth in V2X communication stacks, while Robert Bosch GmbH dominates integrated telematics platforms through captive production of sensors and control modules.
Vehicle networking encompasses the embedded communication architectures, protocols, and hardware that enable data exchange between vehicle systems, infrastructure, and external networks, typically operating across CAN, Ethernet, and wireless interfaces with latency thresholds below 10 milliseconds for safety-critical functions. Its primary purpose centers on enabling autonomous driving capabilities, predictive maintenance, and real-time traffic optimization. Cellular-based V2X technology is capturing the fastest expansion as 5G rollouts mature, while onboard units remain the largest product category by installed base. Fleet tracking applications are generating disproportionate margin pools due to long-term service contracts and data monetization opportunities.
The European Telecommunications Standards Institute shapes V2X protocol harmonization, while the U.S. NHTSA and FCC jointly govern spectrum allocation and safety certification for connected vehicle deployments. China's MIIT enforces domestic cybersecurity standards that condition market access for foreign communication module suppliers. Stakeholders must weigh regulatory fragmentation against the cost of developing region-specific certification pathways.
Market Dynamics
The shift from hardware-centric sales to recurring software revenue is compressing traditional component margins while elevating platform economics. Over-the-air update subscriptions now anchor long-term customer relationships, forcing suppliers to restructure engineering teams around continuous deployment pipelines.
Growth Catalysts
- EU AI Act compliance mandates:Automotive OEMs must certify AI-driven networking systems for safety-critical functions, creating certified supplier demand.
- Fleet telematics data monetization:Commercial operators in Germany leverage V2X infrastructure investments to optimize routing and reduce fuel expenditure.
- 5G network slicing:Cellular carriers deploy dedicated automotive bandwidth with sub-10 millisecond latency guarantees for autonomous emergency braking.
Market Restraints
- Semiconductor supply concentration:Advanced automotive Ethernet PHYs depend on fabrication capacity concentrated in Taiwan and South Korea.
- Copper and lithium price volatility:Wiring harness and battery materials expose module costs to commodity exchange fluctuations.
- DSRC spectrum allocation freeze:FCC regulatory uncertainty in the United States delays dedicated short-range communication deployment timelines.
Strategic Opportunities
- India PLI scheme for automotive electronics:Domestic manufacturing incentives attract communication module assembly away from import-dependent supply chains.
- Predictive maintenance convergence:Edge AI processing fuses with CAN bus diagnostics to enable component failure forecasting before warranty expiration.
- Direct-to-fleet subscription channels:Bypassing Tier-1 integrators, semiconductor vendors sell connectivity stacks directly to logistics operators.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 certification expertise concentrates among experienced German and Japanese engineering pools.
- Multi-protocol integration complexity:Legacy CAN networks must interoperate with new Ethernet backbones without latency degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Networking Market |
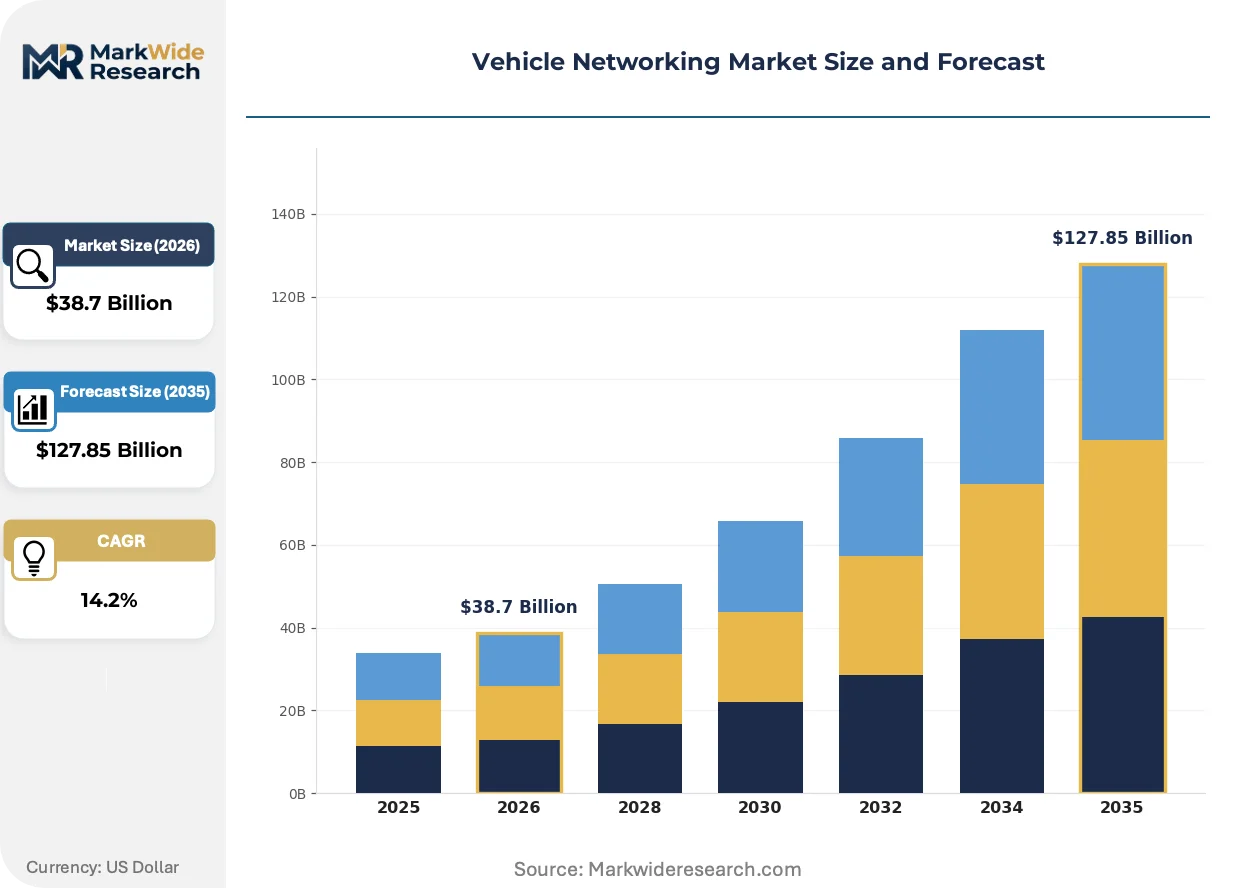
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: V2X, DSRC, Cellular, Wi-Fi Product Type: Onboard Units, Telematics Devices, Sensors, Communication Modules End User: OEMs, Aftermarket Providers, Fleet Operators, Governments Application: Traffic Management, Collision Avoidance, Remote Diagnostics, Fleet Tracking |
| Companies Covered | NXP Semiconductors, Continental AG, Infineon Technologies AG, STMicroelectronics, Broadcom, Robert Bosch GmbH, Denso Corporation, Analog Devices, Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Networking Market Emerging Trajectories
Software-defined vehicle architectures are dissolving the boundary between networking hardware and application layers. This convergence demands new engineering competencies and supplier partnerships.
Automotive Ethernet with Time-Sensitive Networking is absorbing deterministic communication workloads previously reserved for dedicated CAN-FD segments. Powertrain and chassis control units at BMW and Mercedes-Benz adopt 100BASE-T1 for real-time sensor fusion. The technology is absorbing safety-critical traffic from legacy fieldbus systems, compressing the need for parallel network infrastructures.
The EU AI Act's risk classification framework imposes conformity assessment procedures on autonomous driving networking stacks. Tier-1 suppliers in Stuttgart and Munich reorganize quality management systems around notified body engagement. German OEMs delay certain Level 3 feature rollouts to secure certification documentation.
Fleet procurement departments now mandate open API access and data portability clauses in telematics contracts. Traditional black-box systems from incumbent suppliers face displacement by modular platforms supporting third-party analytics integration. This pattern is most visible among refrigerated transport operators in the Netherlands seeking cold-chain verification interoperability.
Vehicle Networking Market Segmentation
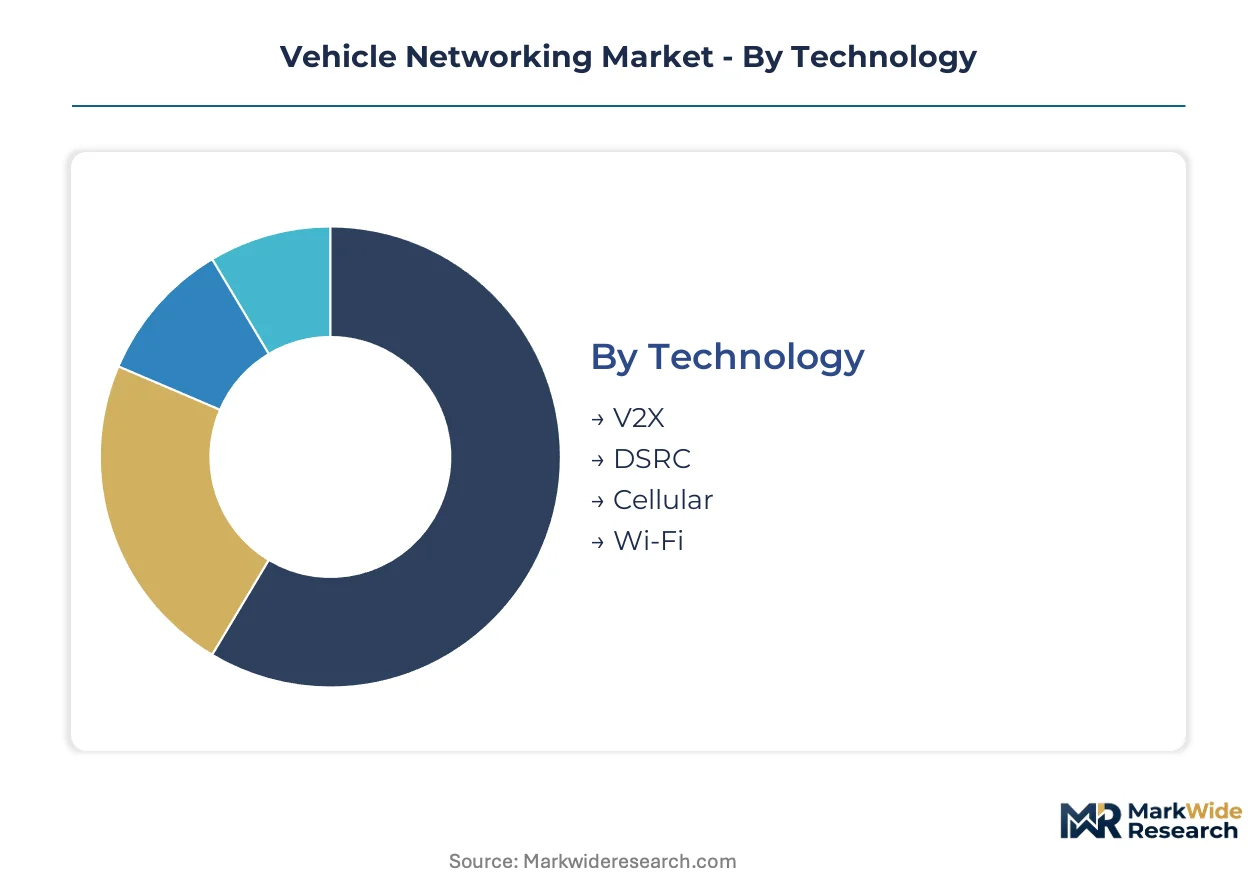
Vehicle networking segmentation reveals divergent margin structures across protocol generations and customer procurement patterns. Suppliers must align R&D investment with the specific latency, certification, and lifecycle requirements of each technology and end-use category.
Technology:
Volume concentrates in mature protocols with established certification pathways, while premium pricing attaches to next-generation cellular stacks with deterministic latency guarantees.
- Cellular:5G network slicing enables sub-10 millisecond latency guarantees for autonomous emergency braking and platooning coordination. German commercial fleet operators in the Rhine-Ruhr corridor leverage cellular V2X infrastructure investments to optimize routing algorithms and reduce fuel expenditure.
- V2X:Dedicated vehicle-to-everything protocols encompass both cellular-based and direct short-range variants for cooperative awareness messaging. Stuttgart-based Tier-1 suppliers reorganize quality management systems around EU AI Act conformity assessment procedures for V2X-enabled autonomous driving stacks.
- DSRC:IEEE 802.11p-based dedicated short-range communication provides mature interoperability for basic safety messaging without cellular dependency. FCC regulatory uncertainty in the United States delays deployment timelines and concentrates remaining investment in European corridors.
- Wi-Fi:802.11ax-based vehicle Wi-Fi handles high-bandwidth infotainment and software update delivery within local area coverage. BMW and Mercedes-Benz integrate Wi-Fi 6E for passenger content streaming and over-the-air firmware distribution.
Today's leader: Cellular. Tomorrow's challenger: V2X.
Product Type:
Application-specific integration depth determines whether modules ship as standalone components or embedded subsystems within larger electronic control units.
- Onboard Units:Self-contained communication gateways mounting in passenger and commercial vehicles to aggregate multi-protocol traffic. These units command the largest installed base across German automotive manufacturing lines due to mandatory eCall compliance and V2X readiness requirements.
- Telematics Devices:Integrated cellular modems with GPS positioning and accelerometer arrays for usage-based insurance and stolen vehicle recovery. Fleet operators in the Netherlands mandate open API access and data portability clauses, displacing traditional black-box systems with modular platforms.
- Sensors:Radar, lidar, and camera modules generating raw data streams requiring deterministic network transport to fusion controllers. Robert Bosch GmbH dominates integrated platforms through captive production of sensors and control modules.
- Communication Modules:Compact radio frequency transceivers embedding protocol stacks for OEM and aftermarket installation. NXP Semiconductors leverages its automotive semiconductor portfolio to anchor connectivity solutions across multiple vehicle tiers.
Onboard units anchor current revenue. Telematics devices are climbing the fastest as subscription models displace hardware sales.
End User:
Procurement sophistication varies sharply between specification-driven OEM engineering teams and price-sensitive aftermarket distributors.
- OEMs:Vehicle manufacturers specifying networking architectures during platform development with multi-year validation cycles. German OEMs delay certain Level 3 feature rollouts to secure EU AI Act certification documentation for autonomous driving networking stacks.
- Fleet Operators:Commercial vehicle owners purchasing telematics and V2X capabilities as operational expenditure with ROI measured in fuel efficiency and asset utilization. Refrigerated transport operators in the Netherlands seek cold-chain verification interoperability across modular platforms.
- Aftermarket Providers:Independent installers and distributors retrofitting connectivity solutions to existing vehicle parc with simplified certification requirements. These channels prioritize plug-and-play installation and smartphone app integration over deep vehicle bus integration.
- Governments:Public authorities procuring roadside units and traffic management infrastructure for cooperative intelligent transport systems. The European Telecommunications Standards Institute shapes V2X protocol harmonization that conditions government procurement specifications.
Fleet operators are gaining share fastest as direct subscription channels bypass Tier-1 integrators.
Application:
Safety-critical functions command premium pricing and functional safety certification, while convenience applications compete on feature velocity and user experience.
- Fleet Tracking:Real-time vehicle location and status monitoring generating long-term service contracts and data monetization opportunities. Commercial operators leverage V2X infrastructure investments to optimize routing and reduce fuel expenditure.
- Collision Avoidance:Cooperative awareness and emergency braking systems requiring sub-10 millisecond latency with ISO 26262 ASIL-D functional safety certification. 5G network slicing provides dedicated automotive bandwidth with deterministic guarantees.
- Remote Diagnostics:Predictive maintenance algorithms fusing CAN bus diagnostics with edge AI processing to forecast component failure. Edge AI processing enables component failure forecasting before warranty expiration.
- Traffic Management:Centralized and edge-based systems optimizing signal timing and routing recommendations based on aggregated vehicle probe data. Stuttgart and Munich reorganize quality management systems around notified body engagement for AI-driven networking certification.
Fleet tracking dominates margin pools today. Collision avoidance holds the steepest expansion trajectory as autonomy regulations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates automotive Ethernet PHY production while the United States struggles with DSRC spectrum allocation uncertainty, creating divergent infrastructure investment patterns across major vehicle manufacturing bases.
Germany
Commercial fleet operators in the Rhine-Ruhr corridor leverage cellular V2X infrastructure for routing optimization. The EU AI Act mandates conformity assessment for autonomous driving networking stacks through notified bodies in Stuttgart and Munich. Bavaria-based Tier-1 suppliers reorganize quality management systems around certification documentation requirements.
United States
NHTSA and FCC joint governance of spectrum allocation delays dedicated short-range communication deployment timelines. Regulatory uncertainty concentrates remaining V2X investment in European corridors rather than domestic infrastructure. Michigan and California automotive clusters await clarity on 5.9 GHz band reallocation before committing roadside unit procurement.
China
MIIT enforces domestic cybersecurity standards conditioning market access for foreign communication module suppliers. Domestic manufacturing of automotive Ethernet switches accelerates in the Yangtze River Delta. Shanghai-based OEMs integrate edge AI processing with CAN bus diagnostics for predictive maintenance convergence.
Japan
METI coordinates standardization efforts for automotive Ethernet with Time-Sensitive Networking adoption. Functional safety engineering expertise concentrates in Nagoya and Tokyo engineering pools. Toyota and Honda suppliers adopt 100BASE-T1 for real-time sensor fusion in powertrain control units.
India
The PLI scheme for automotive electronics attracts communication module assembly away from import-dependent supply chains. Tamil Nadu and Karnataka manufacturing corridors expand domestic semiconductor packaging capacity. Fleet operators in Maharashtra pilot direct-to-fleet subscription channels bypassing traditional Tier-1 integrators.
Vehicle Networking Market Vendor Landscape
Top-tier vendors anchor integrated telematics platforms, while mid-tier specialists concentrate on protocol-specific communication modules. The vendor base stratifies across semiconductor fabricators, Tier-1 system integrators, and sensor-captive platform providers. Three archetypes dominate: broad automotive semiconductor portfolios, V2X communication stack engineering depth, and captive sensor-to-module vertical integration. Competitive moves center on strategic partnerships for 5G network slicing access and portfolio diversification into edge AI processing.
Within the semiconductor-centric tier, NXP Semiconductors N.V. and Infineon Technologies AG exemplify broad automotive portfolio strategies that anchor connectivity solutions across multiple vehicle tiers. Continental AG occupies a position representing V2X communication stack engineering depth, while Robert Bosch GmbH anchors the integrated platform archetype through captive production structures. STMicroelectronics and Renesas Electronics Corporation sit within the microcontroller-focused specialist segment serving deterministic networking workloads.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Continental AG |
| Infineon Technologies AG |
| STMicroelectronics |
| Broadcom |
| Robert Bosch GmbH |
| Denso Corporation |
| Analog Devices |
| Renesas Electronics Corporation |
| Others |
Supply Flow & Price Mechanics
Functional safety engineering expertise concentrated in Stuttgart and Munich engineering pools feeds directly into pricing-tier spreads across automotive networking modules, with ISO 26262 ASIL-D certification commanding substantial premiums over uncertified alternatives.
Pricing Analysis
Capacity additions in India's Tamil Nadu and Karnataka manufacturing corridors are reshaping price floors for communication modules, compressing margins on standard-tier products while premium-mid-economy pricing differentiation persists around functional safety grades. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified stacks from ASIL-B intermediate offerings and aftermarket plug-and-play units. Pricing pressure stems from 5G modem commoditization as MediaTek and Qualcomm automotive silicon proliferates. Fleet operators exhibit highest price sensitivity due to volume procurement and subscription model expectations, while German OEM engineering teams prioritize certification reliability over unit cost.
Supply Chain Analysis
Reverse logistics flows for telematics device refurbishment and onboard unit remanufacturing concentrate in the Yangtze River Delta and Taiwan, extending module lifecycles and compressing new-unit demand in replacement markets. Semiconductor fabrication draws from Taiwan and South Korea for advanced automotive Ethernet PHYs, while copper wiring harnesses and lithium battery materials rest on Chilean and Australian extraction. Single-source vulnerability around TSMC automotive-grade capacity creates chokepoint exposure. Distribution runs through Tier-1 system integrators in Germany and direct-to-fleet channels in the Netherlands and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act functions as a regulatory compounder, with conformity assessment mandates for autonomous driving networking stacks generating sustained certified-supplier demand across the European automotive manufacturing base.
For Market Incumbents: Cement market position through captive production of sensors and control modules that lock out modular competitors, while accelerating ISO 26262 certification documentation for Level 3 feature portfolios before notified body backlogs lengthen. Threat substitution from direct-to-fleet subscription channels bypassing Tier-1 integrators demands channel control reinforcement through long-term service contracts with data portability restrictions. For New Entrants and Emerging Players: Enter via India's PLI scheme for automotive electronics assembly, targeting Maharashtra fleet operators piloting direct subscription procurement outside traditional integrator relationships. White-space concentrates in refrigerated transport cold-chain verification interoperability and edge-AI predictive maintenance convergence. Go-to-market leverage rests on open API architectures that displace incumbent black-box telematics systems. For Investors and Strategic Acquirers: Semiconductor fabricators with broad automotive portfolios are the most active acquirer in this space, seeking V2X communication stack engineering depth to complete platform coverage. Long-term viability favors targets with notified body relationships and ASIL-D certification pipelines. Signal to watch: FCC 5.9 GHz band reallocation clarity triggering US infrastructure procurement acceleration or further investment diversion to European corridors.| Strategic Initiative | Industry Significance |
|---|---|
| 5G Network Slicing Partnership | Cellular carriers deploy dedicated automotive bandwidth with sub-10 millisecond latency guarantees for autonomous emergency braking. |
| Software-Defined Vehicle Investment | BMW and Mercedes-Benz adopt 100BASE-T1 Ethernet backbones, dissolving hardware-application layer boundaries. |
| EU AI Act Certification Pathway | Stuttgart-based Tier-1 suppliers reorganize quality management systems around notified body engagement for conformity assessment. |
| Backward Integration into Sensor Production | Robert Bosch GmbH anchors integrated telematics platforms through captive radar and camera module manufacturing. |
| Geographic Manufacturing Footprint Expansion | Tamil Nadu and Karnataka corridors attract communication module assembly away from import-dependent supply chains. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operations managers with secondary validation against vehicle production databases, IHS Markit registration data, SEC 10-K filings, and ETSI protocol harmonization documents. Bottom-up module shipment estimates triangulated against top-down automotive Ethernet PHY consumption figures.
Segment-weighting across the projection horizon applied technology protocol, product type integration depth, end-user procurement sophistication, and application safety-criticality as core dimensions. CAGRs derived from installed base evolution, content-per-vehicle trajectories, and subscription revenue conversion rates. Forecast inputs incorporated 5G network slicing deployment timelines and EU AI Act certification pipeline constraints.
Inputs from Tier-1 engineering teams and fleet procurement departments were available through the study window; gaps in FCC spectrum reallocation timing and MIIT cybersecurity standard enforcement introduce uncertainty bands around US and China trajectory assumptions. Practitioners should monitor notified body capacity utilization and DSRC deployment commitment clarity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Connectivity Control Unit Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Automotive Secondary Wiring Harness Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Automotive NFC Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Automotive OLED Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Vehicle Control Unit (VCU) Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
Traffic Sign Recognition System Market
Automotive Electronics & Wiring
Automotive 360 Degree Technology Market
Automotive Electronics & Wiring
Automotive Optical Fiber Data Cable Systems Market