
 Automotive Aftermarket Glass Market | 2026-2036
Automotive Aftermarket Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Aftermarket Glass Market Analytics
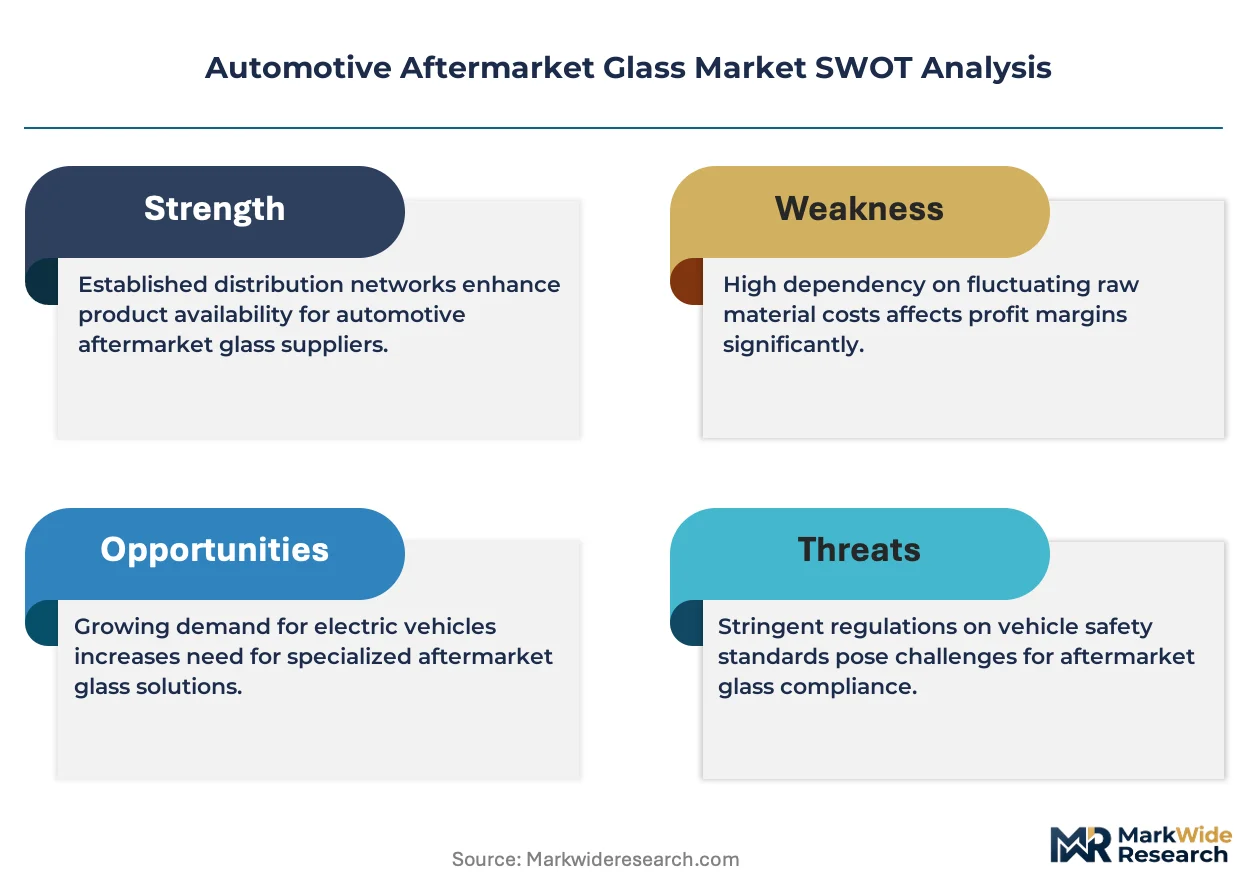
Asset-light leasing models for mobile replacement fleets is rewriting competitive entry barriers across the aftermarket glass value chain. Fuyao Glass Industry Group Co., Ltd. leverages its integrated float-glass capacity to anchor cost structures in replacement windshields. Saint-Gobain sustains premium positioning through laminated acoustic and solar-control glazing technologies. Guardian Industries dominates North American distribution via captive wholesale networks serving collision repair chains.
Automotive aftermarket glass comprises tempered and laminated safety glazing manufactured to optical clarity and impact-resistance specifications, primarily serving vehicle repair, replacement, and restoration needs. Laminated windshields incorporate polyvinyl butyral interlayers to prevent occupant ejection and enable passenger airbag deployment. Replacement services capture the largest value pool as advanced driver-assistance system recalibration requirements extend job complexity and pricing power. Online platforms represent the fastest-expanding distribution channel as fleet operators and insurers consolidate procurement through digital tendering systems.
The US National Highway Traffic Safety Administration enforces Federal Motor Vehicle Safety Standard 205 governing glazing materials and installation integrity, while Europe's CE marking and United Nations ECE R43 certification govern optical quality and fragmentation behavior. China's GB standards and SAMR oversight impose mandatory CCC certification on imported glass assemblies, shaping supplier qualification timelines. Stakeholders must monitor how evolving autonomous-vehicle sensor fusion requirements will redefine calibration protocols and technician certification standards across regulatory jurisdictions.
Market Dynamics
ADAS recalibration requirements are transforming windshield replacement from a commodity service into a technical specialty, compressing independent installer margins while elevating certified network value capture.
Growth Catalysts
- Sensor Fusion Mandates:NHTSA's advancing crashworthiness standards require laminated glass with embedded antenna arrays for V2X communication, expanding replacement complexity and service pricing power in the United States.
- F-Gas Phase-Down:Europe's F-Gas Regulation is accelerating manufacturing investment in vacuum-insulated glazing and thin-film coatings that reduce HVAC load, creating replacement demand for energy-efficient automotive glass.
- Fleet Electrification:Commercial fleet operators are consolidating glass procurement through telematics-integrated maintenance platforms, concentrating volume with suppliers capable of national mobile service coverage.
Market Restraints
- PVB Interlayer Concentration:Polyvinyl butyral supply concentrates among three chemical conglomerates, exposing replacement glass fabricators to input cost volatility and force majeure allocation risk.
- CCC Certification Timelines:China's SAMR mandates 90-120 day homologation cycles for imported glass assemblies, delaying aftermarket product launches and freezing inventory positions for non-domestic suppliers.
- Recycled Cullet Shortage:Post-consumer automotive glass recovery rates remain below 25 percent due to PVB separation costs, constraining float-glass manufacturers' cost reduction pathways and ESG commitments.
Strategic Opportunities
- Head-Up Display Compatibility:Wedge-shaped windshields with optimized optical wedge angles for HUD projection represent an underpenetrated premium tier in the replacement channel, commanding 40-60 percent price multiples over standard laminated products.
- Insurance-Integrated Platforms:Digital claims networks operated by major US auto insurers are consolidating installer selection algorithms, creating preferred-provider positions for glass suppliers with real-time inventory API connectivity.
- Thermal Comfort Coatings:Infrared-reflective glazing that reduces cabin heat load aligns with EPA fuel economy credits for reduced air conditioning draw, positioning coated replacement glass as a compliance-adjacent upgrade.
Industry Challenges
- ADAS Calibration Skill Gaps:Static and dynamic camera recalibration protocols require technician investment in OEM-specific diagnostic tools and software subscriptions, fragmenting training standards across installer networks.
- Windshield-Integrated Hardware Complexity:Rain sensors, lane-keeping cameras, and heated wiper park zones embedded in modern windshields extend replacement touch time and elevate damage liability exposure during installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Aftermarket Glass Market |
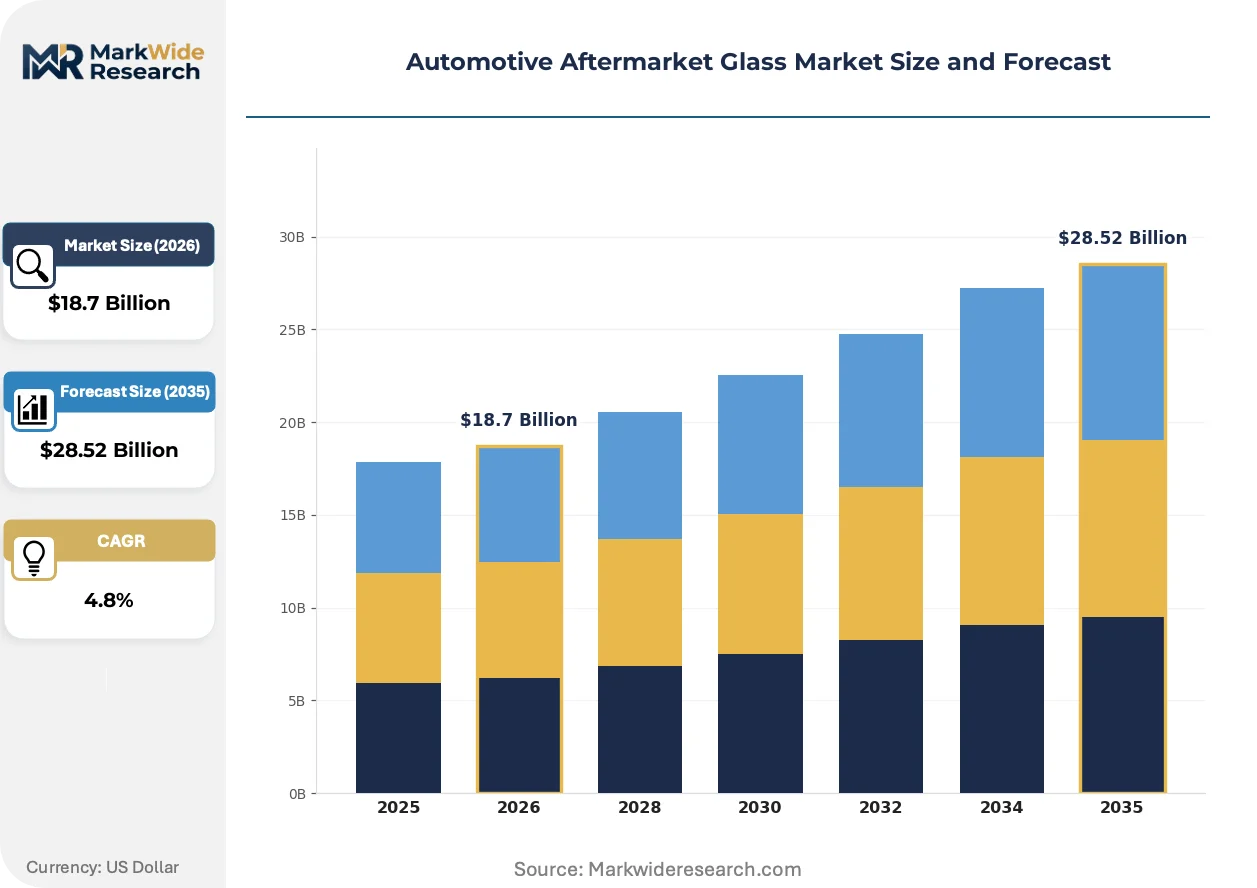
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Windshield, Side Window, Rear Window, Sunroof Service Type: Repair Services, Replacement Services, Tinting Services, Coating Services Distribution Channel: Retail Stores, Online Platforms, Service Stations, Wholesalers End User: Individual Consumers, Fleet Operators, Body Shops, Insurance Companies |
| Companies Covered | AGC Inc., Fuyao Glass Industry Group Co., Ltd., Saint-Gobain, Nippon Sheet Glass Co., Ltd., Xinyi Glass Holdings Limited, Guardian Industries, Central Glass Co., Ltd., Corning Incorporated, Vitro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Aftermarket Glass Market Evolving Landscape
Material science advances and regulatory chemistry constraints are forcing simultaneous evolution in glass composition, interlayer technology, and installation methodology across the replacement value chain.
Acoustic laminated glass incorporating constrained-layer damping interlayers is migrating from luxury OEM specification into mainstream replacement demand. Fleet operators operating electric commercial vehicles specify these assemblies to offset powertrain noise absence. The technology is migrating from premium tier availability toward standard catalog positioning as Chinese float-glass capacity expands acoustic PVB supply.
Europe's F-Gas Regulation imposes phased production caps on hydrofluorocarbon blowing agents used in polyurethane encapsulation of glass edges. Manufacturers are reformulating encapsulant chemistry toward water-blown or pentane-based systems. Laminated windshield fabricators serving EU member states face 18-month reformulation timelines and requalification testing under United Nations ECE R43 certification protocols.
Mobile replacement service platforms are consolidating procurement decisions away from individual vehicle owners toward fleet managers and insurance claim networks. Digital tendering systems aggregate demand across multiple carriers and commercial operators, compressing installer margins while rewarding suppliers with national logistics infrastructure. The United States exhibits the most advanced concentration of this channel shift, with three insurers controlling over 60 percent of glass claim routing through captive preferred provider networks.
Automotive Aftermarket Glass Market Segmentation
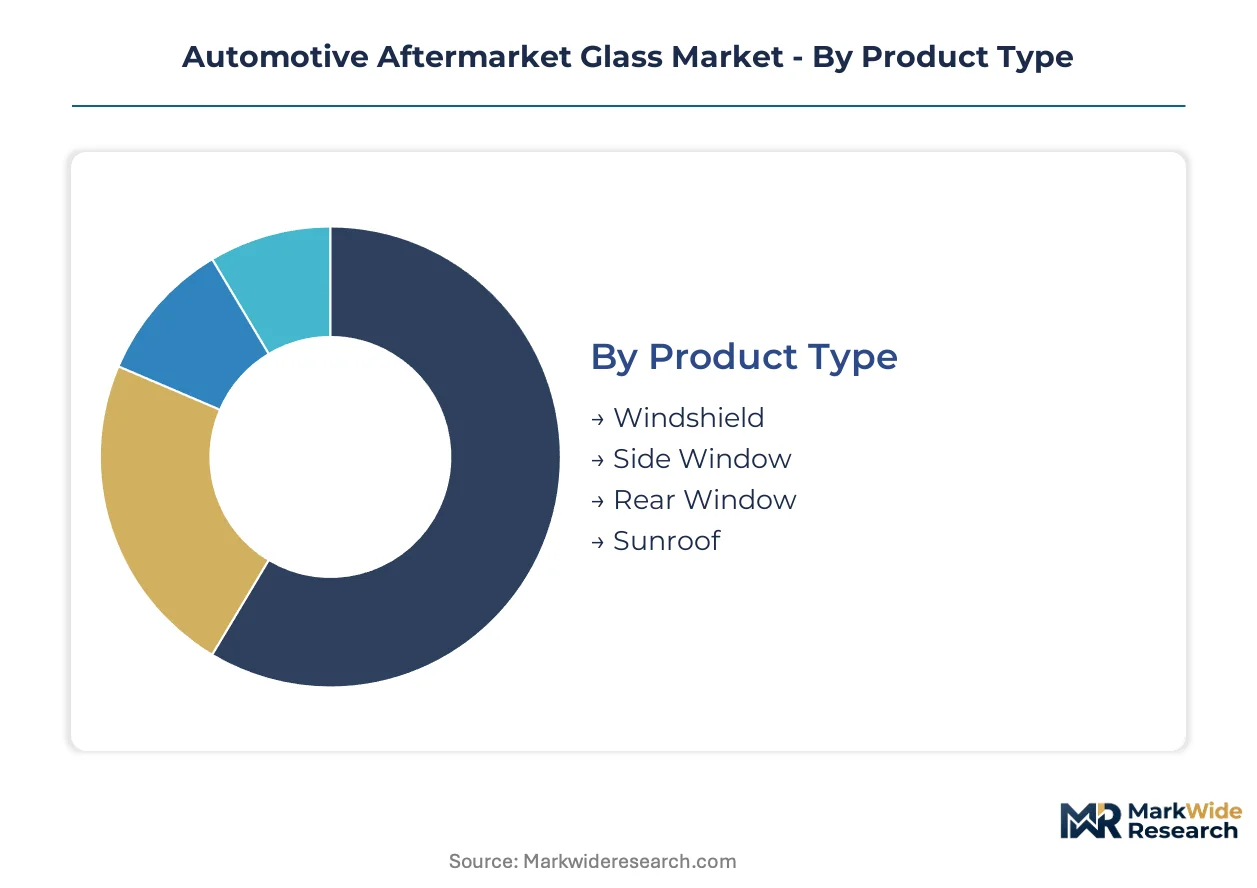
Segmentation in the automotive aftermarket glass market reveals how ADAS complexity, insurance claim routing, and fleet procurement consolidation are reshaping value capture across product, service, and channel dimensions. Understanding these splits exposes where pricing power concentrates and where commoditization pressures mount.
Product Type:
Windshield replacement commands the highest technical barrier and pricing premium due to embedded sensor arrays and calibration requirements, while side and rear windows compete on logistics efficiency and inventory turns.
- Windshield:Laminated safety glass with polyvinyl butyral interlayers must meet optical clarity standards for camera and LiDAR penetration. Demand concentrates in the United States where insurance-integrated mobile replacement networks handle complex recalibration protocols. NHTSA's Federal Motor Vehicle Safety Standard 205 enforcement elevates certified installer requirements.
- Side Window:Tempered glass fragments into granular pieces upon impact to prevent laceration injuries. Fleet operators in Germany and France consolidate procurement through telematics-linked maintenance platforms, prioritizing suppliers with national same-day service coverage.
- Rear Window:Defroster-integrated tempered assemblies with embedded antenna traces for radio and cellular reception.
- Sunroof:Laminated or tempered panels with UV-filtering interlayers serving premium vehicle restoration and upgrade demand.
The dominant share belongs to Windshield, while Sunroof is closing the gap fastest on luxury vehicle replacement and aftermarket upgrade demand.
Service Type:
Service margins diverge sharply between commodity repair and technology-intensive replacement requiring OEM diagnostic equipment.
- Replacement Services:Full glass removal and installation with ADAS static or dynamic recalibration using OEM-specific targets and scan tools. Insurance claim networks in the United States route over sixty percent of volume through preferred provider algorithms, compressing independent installer margins while rewarding certified national platforms.
- Repair Services:Resin injection for bullseye and star cracks under two inches in diameter. Individual vehicle owners in India and Brazil drive demand for low-cost alternatives to deductible-triggered replacements, though repair penetration stalls as windshield-integrated sensor density rises.
- Tinting Services:aftermarket film application for UV rejection and privacy regulation compliance.
- Coating Services:Hydrophobic and anti-reflective surface treatments applied to existing glass.
Replacement Services captures the revenue concentration, with Repair Services expanding most quickly in price-sensitive emerging markets before ADAS saturation.
Distribution Channel:
Channel power is migrating from fragmented retail toward consolidated digital procurement platforms controlled by fleet managers and insurers.
- Online Platforms:Digital tendering systems aggregate demand across multiple insurance carriers and commercial fleet operators, enabling real-time inventory API connectivity. The United States exhibits the most advanced platform concentration, with three insurers controlling majority claim routing through captive networks.
- Wholesalers:Captive distribution networks serving collision repair chains and independent installer cooperatives. Guardian Industries dominates North American wholesale positioning through vertically integrated logistics infrastructure.
- Retail Stores:Branded outlets and auto parts chains serving walk-in consumers and DIY installers.
- Service Stations:Quick-lube and maintenance facilities offering glass as ancillary service.
Wholesalers retain volume leadership, though Online Platforms are gaining share fastest on insurance and fleet procurement consolidation.
End User:
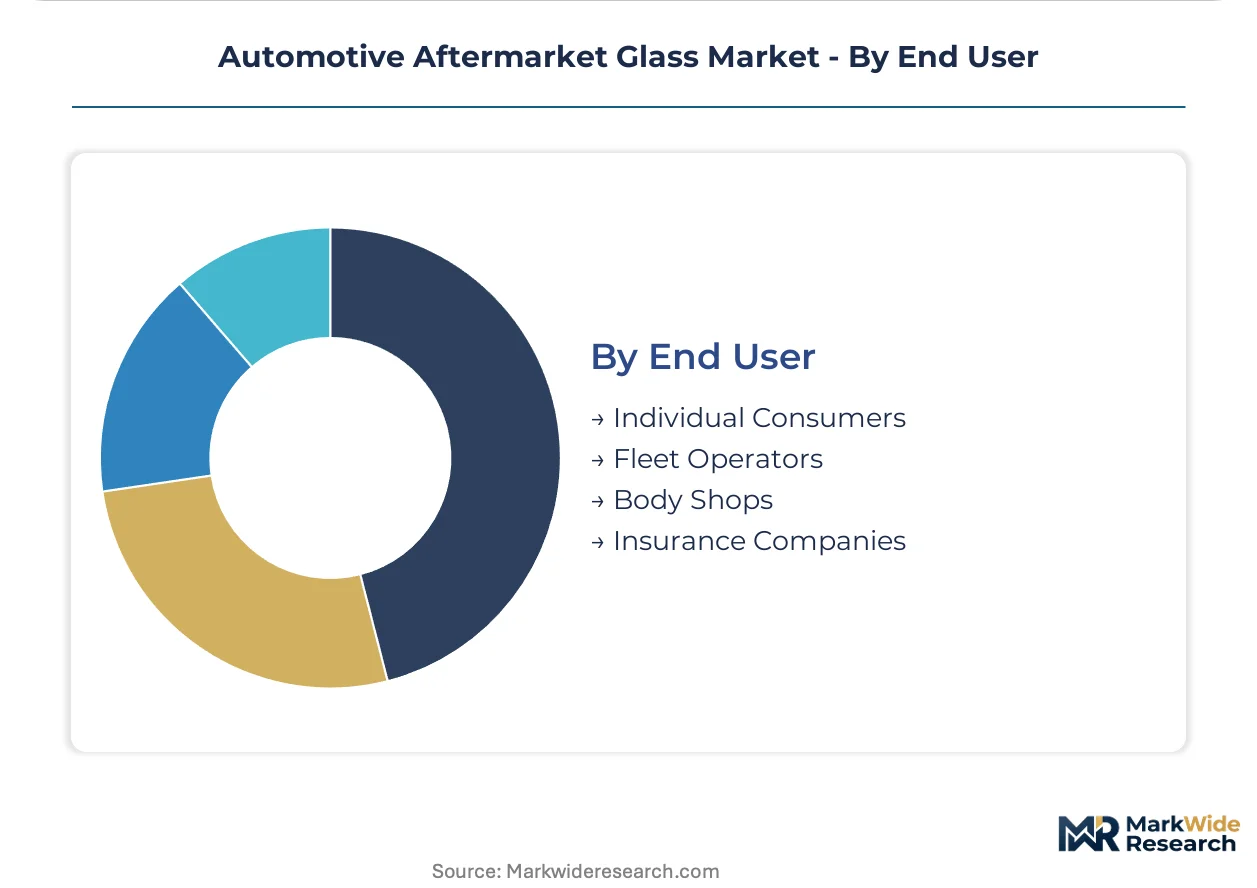
End-user economics separate fragmented individual demand from concentrated institutional purchasing with negotiated rate schedules.
- Insurance Companies:Claims networks operate as de facto procurement aggregators, selecting installers through algorithmic scoring of cost, cycle time, and customer satisfaction metrics. Major US carriers have built captive preferred provider networks that concentrate volume with suppliers offering national mobile service coverage.
- Fleet Operators:Commercial vehicle and rental car operators manage glass replacement through telematics-integrated maintenance platforms. Electrified commercial fleets specify acoustic laminated glass to offset powertrain noise absence, creating specification premiums.
- Individual Consumers:Retail purchasers paying out-of-pocket or through deductible-based claims.
- Body Shops:Collision repair facilities sourcing glass as part of comprehensive vehicle restoration.
Insurance Companies command the decision-making concentration, while Fleet Operators are climbing the fastest on electrification-linked specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Insurance-integrated claims networks and fleet electrification mandates are concentrating aftermarket glass demand in markets with mature automotive ecosystems and stringent safety regulations.
United States
NHTSA's Federal Motor Vehicle Safety Standard 205 enforcement elevates certified installer requirements for laminated windshields with embedded sensor arrays. Three major insurers control over sixty percent of glass claim routing through captive preferred provider networks. Detroit's collision repair corridor anchors national mobile replacement service infrastructure serving electrified commercial fleets.
Germany
Europe's F-Gas Regulation accelerates manufacturing investment in vacuum-insulated glazing and thin-film coatings that reduce HVAC load in electric commercial vehicles. KBA enforces United Nations ECE R43 certification governing optical quality and fragmentation behavior. Stuttgart's automotive supplier cluster concentrates acoustic laminated glass fabrication for premium fleet electrification programs.
China
SAMR mandates ninety-to-one-hundred-twenty day homologation cycles for imported glass assemblies, delaying aftermarket product launches and freezing inventory positions for non-domestic suppliers. GB standards impose mandatory CCC certification shaping supplier qualification timelines. Foshan's glass manufacturing belt expands float-glass capacity to anchor cost structures in replacement windshields.
Japan
METI promotes vehicle-to-everything communication infrastructure requiring laminated glass with embedded antenna arrays for sensor fusion applications. JIS standards govern optical clarity specifications for advanced driver-assistance system penetration. Aichi Prefecture's automotive corridor concentrates OEM-linked aftermarket glass distribution networks serving hybrid fleet operators.
India
BIS certification requirements and the PLI scheme for automotive components attract domestic laminated glass manufacturing investment. CDSCO-aligned safety standards elevate tempered glass specifications for commercial vehicle replacement. Pune's automotive hub anchors regional distribution infrastructure serving telematics-integrated fleet maintenance platforms.
Automotive Aftermarket Glass Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered competitive positions. Consolidation concentrates among integrated float-glass manufacturers and captive distribution networks serving collision repair chains. Three strategic archetypes dominate: integrated primary glass producers, wholesale distribution specialists, and mobile service platform operators. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure national logistics infrastructure and insurance network integration.
Within the integrated manufacturing tier, Fuyao Glass Industry Group Co., Ltd. and AGC Inc. exemplify scale-driven positions anchored in captive float-glass supply. Saint-Gobain occupies a premium-tier position representing acoustic and solar-control glazing specialization. Guardian Industries exemplifies distribution-focused competitive positioning through wholesale network control.
| Leading Market Players |
|---|
| AGC Inc. |
| Fuyao Glass Industry Group Co., Ltd. |
| Saint-Gobain |
| Nippon Sheet Glass Co., Ltd. |
| Xinyi Glass Holdings Limited |
| Guardian Industries |
| Central Glass Co., Ltd. |
| Corning Incorporated |
| Vitro |
| Others |
Value Network & Pricing Analysis
Float-glass overcapacity in China compresses base material costs while ADAS calibration complexity elevates technician-labor premiums in replacement services. This divergence between commodity input deflation and technical service inflation reshapes margin capture across the value chain, rewarding suppliers with captive float capacity and certified installer networks.
Pricing Analysis
Certification level creates the primary spread, with NHTSA-certified laminated assemblies commanding substantial premiums over uncertified imports. Three-tier pricing structure across premium acoustic-laminated, standard laminated, and economy tempered products segments buyer budgets. Pricing pressure stems from insurance-integrated procurement platforms aggregating volume and squeezing installer margins. Fleet operators exhibit lowest price sensitivity due to telematics-linked maintenance contracts, while individual retail purchasers drive cost compression through deductible avoidance.
Supply Chain Analysis
Extended payment terms from insurance claim networks finance inventory positions for wholesale distributors serving collision repair chains. Geographic supply concentrates in China, Germany, and the United States, with Foshan's manufacturing belt anchoring float-glass capacity. Polyvinyl butyral interlayers, polyurethane encapsulants, and conductive ceramic frits constitute critical input dependencies. Single-source vulnerability in PVB supply exposes fabricators to force majeure allocation risk. Distribution runs through captive wholesale networks and digital tendering platforms consolidating insurer and fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs value capture as insurance-integrated claims networks and telematics-linked fleet maintenance systems consolidate procurement decisions away from fragmented retail demand. Interoperability between glass supplier inventory APIs and insurer routing algorithms determines preferred-provider positioning.
For Market Incumbents: Build certification moats around ADAS recalibration capabilities to lock in insurance network contracts. Secure captive float-glass supply through backward integration or long-term offtake agreements with Chinese manufacturers. Invest in national mobile service infrastructure to meet fleet operator same-day coverage requirements. The threat of digital-native platform entrants with asset-light models demands preemptive channel control. For New Entrants and Emerging Players: Pursue white-space opportunities in HUD-compatible wedge-shaped windshields where technical barriers limit incumbent penetration. Target acoustic laminated glass specifications for electrified commercial fleets in Germany and France where noise-offset demand concentrates. Deploy direct API connectivity to telematics-integrated fleet maintenance platforms as primary go-to-market channel, bypassing wholesale distribution gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ADAS-calibration-enabled service networks due to diagnostic equipment and technician certification requirements. Long-term viability favors integrated manufacturers with captive glass supply and certified installation infrastructure over pure distribution plays. Acquisition target archetype: regional mobile service platforms with insurance network contracts and untapped fleet relationships. Signal to watch: consolidation of preferred-provider algorithms among top three US auto insurers.| Strategic Initiative | Industry Significance |
|---|---|
| ADAS Calibration Certification Investment | NHTSA enforcement elevates technical barriers and locks in insurance network contracts. |
| Float-Glass Capacity Expansion | Foshan's manufacturing belt anchors cost structures against PVB input volatility. |
| Insurance Platform API Integration | Real-time inventory connectivity determines preferred-provider algorithm scoring. |
| Acoustic Laminated Glass Line Extension | Electrified fleet noise-offset specifications create premium tier demand in Europe. |
| Mobile Service Network Consolidation | National coverage capabilities concentrate fleet procurement decisions. |
Research Methodology
A standing panel of OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and insurance claims network managers provided ongoing calibration across the study. Primary interviews combined with secondary validation from NHTSA enforcement records, ECE R43 certification databases, vehicle production registries, and customs trade data. Bottom-up installation volume estimates triangulated against top-down glass fabrication capacity assessments.
Scenario-bracketing framed demand projections across the analysis window, modeling windshield, side window, rear window, and sunroof segments alongside service type splits and distribution channel migration. CAGRs derived from regression analysis against vehicle parc growth, ADAS penetration curves, and fleet electrification timelines. Forecast inputs incorporated insurance claim routing concentration, F-Gas Regulation phase-down impacts, and CCC certification timeline delays for imported assemblies.
Macroeconomic conditions sit as an overlay; deviation in fleet capital expenditure cycles, automotive insurance premium trends, or lithium-ion battery cost trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding ADAS sensor fusion mandates and regulatory chemistry constraints. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Engine Module-Level Repair and Refurbishment Services Market
Vehicle Maintenance & Aftermarket
Car Recycling Market
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
Silicone in Car Care Products Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Classic Car Restoration and Restomod Services Market
Vehicle Maintenance & Aftermarket
Motor Winding Repair Service Market
Vehicle Maintenance & Aftermarket
United Kingdom Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market
Vehicle Maintenance & Aftermarket
Global Fleet Maintenance Software Market
Vehicle Maintenance & Aftermarket
OBD-Linked Predictive Maintenance Diagnostic Platforms Market
Vehicle Maintenance & Aftermarket
Stolen Vehicle Recovery Market
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market