
 Asia-Pacific Automotive Exhaust Aftertreatment Systems Market | 2026-2036
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market Outlook
China VI-grade aftertreatment hardware is bifurcating the competitive landscape between premium system integrators and cost-optimized module suppliers. Continental AG leverages its captive sensor and urea-dosing technology to control integrated system architectures. Tenneco Inc. anchors the region through exhaust component manufacturing scale across multiple Chinese provinces. Cummins sustains technology leadership in active regeneration controls for heavy-duty diesel applications.
Automotive exhaust aftertreatment systems comprise catalytic converters, particulate filters, and reagent injection hardware designed to reduce NOx, CO, hydrocarbons, and particulate matter below regulated thresholds, typically operating at exhaust temperatures between 200°C and 600°C with substrate coatings of platinum-group metals or base-metal zeolites. These systems serve the primary commercial purpose of enabling internal combustion engines to comply with tailpipe emission limits while preserving engine performance and fuel efficiency. Selective catalytic reduction dominates value capture due to its complexity and urea infrastructure dependency, while gasoline particulate filter demand accelerates fastest as gasoline direct-injection engines proliferate across Asian passenger car production. Diesel particulate filter technology occupies a mature but stable position in heavy commercial vehicle segments where regulatory enforcement remains stringent.
China's Ministry of Ecology and Environment enforces National VI emission standards that mandate combined SCR and DPF architectures for new diesel vehicles, while India's Central Pollution Control Board implements Bharat Stage VI norms requiring comparable aftertreatment intensity across major metropolitan testing cycles. Japan's Ministry of Land, Infrastructure, Transport and Tourism maintains parallel certification requirements that shape product development priorities for suppliers serving multiple Asian markets. Stakeholders must monitor regulatory harmonization gaps between national test protocols and real-driving emission enforcement timelines to calibrate regional manufacturing investments and technology roadmaps.
Market Dynamics
China's National VI emission enforcement is compressing supplier margins while fragmenting procurement authority between OEM captive workshops and independent fleet operators across the Asia-Pacific region.
Growth Catalysts
- India's Bharat Stage VI norms:The Central Pollution Control Board mandates diesel particulate filters and selective catalytic reduction for heavy commercial vehicles, forcing hardware retrofits across Delhi-Mumbai freight corridors.
- Platinum-group metal substitution:Base-metal zeolite coatings in catalytic substrates reduce cost exposure to palladium price volatility while maintaining conversion efficiency at exhaust temperatures above 450°C.
- Southeast Asian commercial fleet expansion:Cross-border logistics operators in Vietnam and Thailand are adopting SCR-equipped trucks to access Chinese and Indian transit corridors.
Market Restraints
- Platinum-group metal cost volatility:Rhodium and palladium price swings compress module supplier margins on fixed-price OEM contracts.
- China-centric substrate manufacturing:Cordierite and silicon carbide filter substrate production concentrates in Shandong and Jiangsu provinces, exposing buyers to single-country supply risk.
- Urea infrastructure gaps:AdBlue distribution networks remain underdeveloped in Indonesia and the Philippines, limiting SCR adoption outside major metropolitan clusters.
Strategic Opportunities
- Indonesia's diesel truck parc:The archipelago's 3.5 million uncontrolled heavy vehicles face impending emission mandates from the Ministry of Environment and Forestry.
- Gasoline particulate filter convergence:Direct-injection gasoline engines in Japanese and South Korean passenger car production create demand for GPF architectures adapted from diesel filter platforms.
- Active regeneration control integration:Sensor fusion between pressure differential monitors and temperature probes enables predictive filter maintenance, opening subscription-based fleet service models.
Industry Challenges
- Catalyst formulation chemist scarcity:Asia-Pacific universities produce insufficient graduates with expertise in washcoat engineering and PGM dispersion techniques.
- Homologation timeline compression:China's MEE accelerates certification cycles for National VI-b compliance, straining supplier validation capacity.
- Legacy Euro IV fleet incompatibility:Retrofit SCR systems face packaging constraints on older truck chassis with limited frame rail space and electrical architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Exhaust Aftertreatment Systems Market |
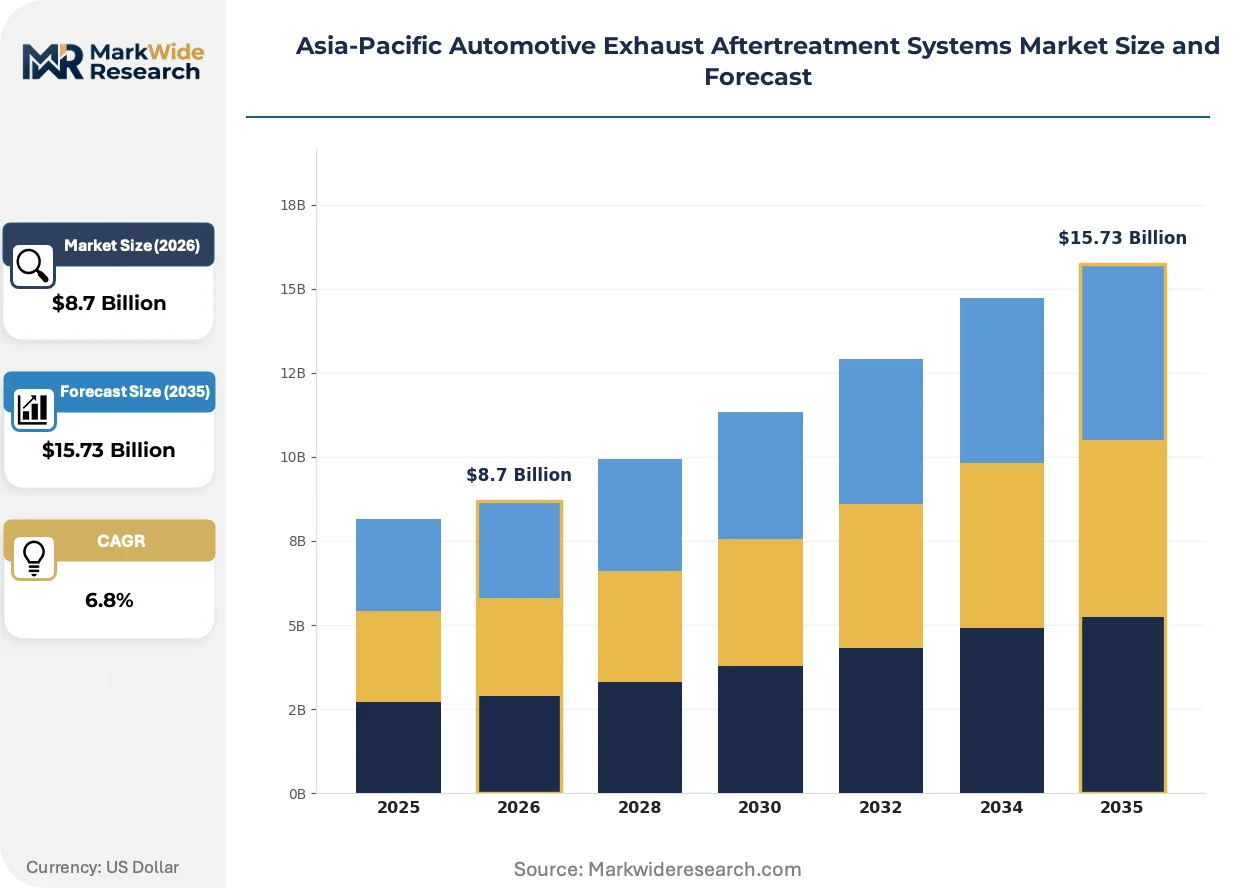
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Selective Catalytic Reduction, Diesel Particulate Filter, Lean NOx Trap, Gasoline Particulate Filter Technology: Active Regeneration, Passive Regeneration, Hybrid System, Catalyst Technology End User: OEMs, Aftermarket Providers, Vehicle Manufacturers, Fleet Operators Sale Channel: Direct Sales, Distributors, Online Retail, Service Centers |
| Companies Covered | Continental AG, Tenneco Inc., Cummins, Delphi Technologies PLC, Bosal Group, Donaldson Company, Harris Performance, Clean Diesel Technologies Inc., Faurecia, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market Strategic Shifts
Electrification pressure on diesel powertrains is forcing aftertreatment suppliers to extract maximum performance from smaller, more thermally efficient hardware packages while integrating sensor intelligence.
Integrated urea-dosing modules are miniaturizing pump and injector assemblies into single housing units that mount directly on the DEF tank. Chinese heavy-duty OEMs are specifying these compact systems for cab-under-engine configurations where packaging space is severely constrained. This consolidation is eliminating separate line sets and reducing installation labor by half.
Japan's METI has tightened real-driving emission test protocols for commercial vehicles, extending certification requirements beyond laboratory cycles to include urban stop-and-go and highway cruise profiles. Suppliers must now validate catalyst light-off performance across broader temperature and load ranges. The heaviest compliance burden falls on dual-layer SCR coatings optimized for low-temperature NOx conversion.
Fleet procurement managers are consolidating supplier relationships from multi-vendor component sourcing to single-source system integrators who warrant complete aftertreatment performance. This concentration favors Tier 1 suppliers with captive sensor, dosing, and catalyst manufacturing. The shift is most pronounced in Australia's mining and logistics sectors where total cost of ownership contracts now dominate tender specifications.
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market Segmentation
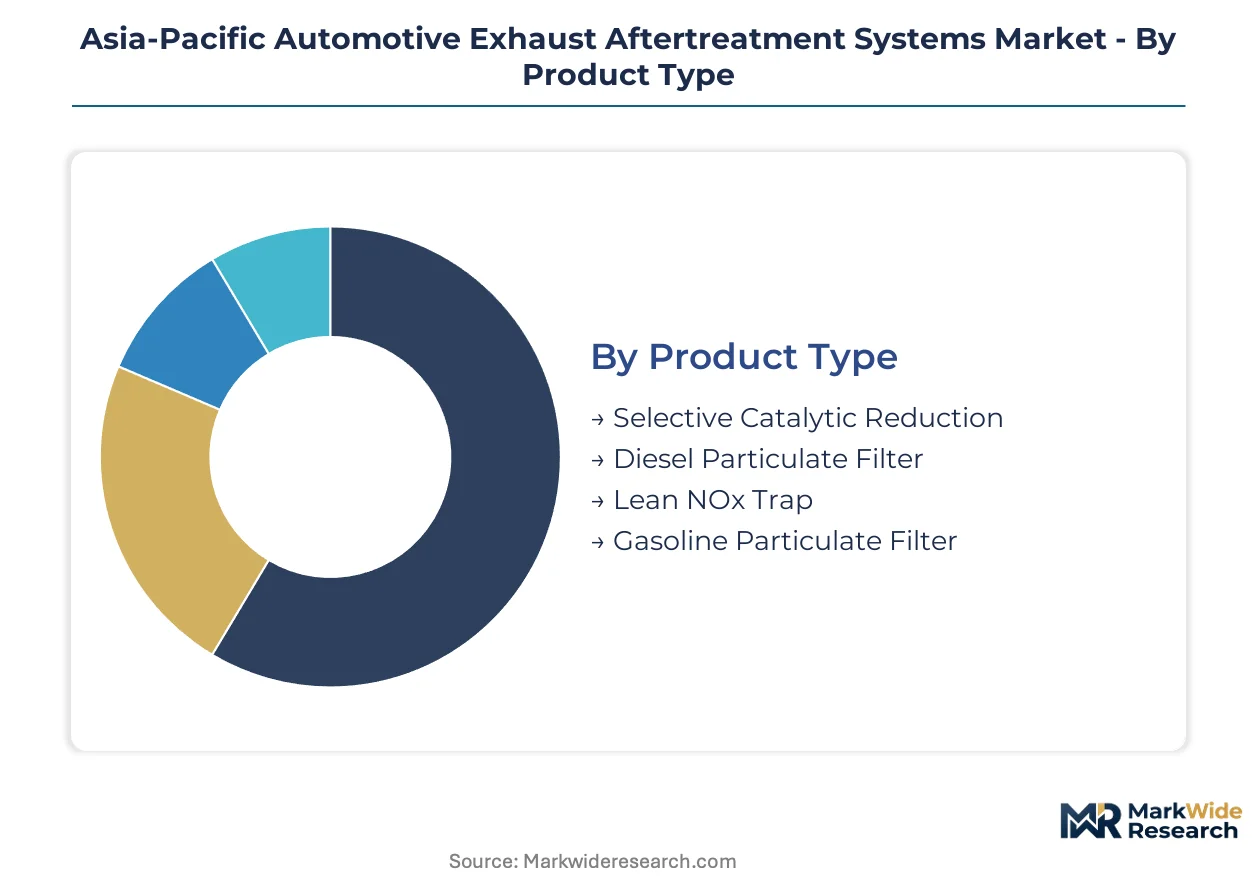
Aftertreatment hardware flows through distinct procurement channels shaped by emission enforcement intensity and fleet scale. Each segment category reflects divergent margin structures, technical validation requirements, and geographic concentration patterns across the Asia-Pacific region.
Product Type:
Selective catalytic reduction systems move primarily through OEM captive supply agreements, while particulate filters split between factory-fit and independent retrofit channels depending on regulatory phase-in timing.
- Selective Catalytic Reduction:Complex urea-dosing architectures with pump, injector, and control module integration. Heavy commercial vehicle demand concentrates in China's Shandong and Hebei provinces where National VI enforcement is strictest, with fleet operators absorbing higher upfront costs to avoid operating penalties.
- Gasoline Particulate Filter:Ceramic wall-flow substrates adapted from diesel filter platforms for direct-injection gasoline engines. Japanese and South Korean passenger car production drives specification volumes, with OEMs demanding compact radial designs that package within tight underfloor spaces.
- Diesel Particulate Filter:Silicon carbide or cordierite substrates with catalyzed or uncatalyzed coatings. India's Bharat Stage VI retrofit programs sustain aftermarket demand along Delhi-Mumbai freight corridors.
- Lean NOx Trap:Platinum-group metal absorber technology for smaller displacement diesel engines where SCR packaging is impractical. Southeast Asian light commercial vehicle applications in Thailand and Vietnam favor this lower-cost architecture.
By volume, selective catalytic reduction leads. By growth pace, gasoline particulate filter is gaining share fastest.
Technology:
Cost tiers separate active regeneration systems commanding premium pricing from passive architectures competing on installed cost in price-sensitive markets.
- Active Regeneration:Fuel-fired or electrically heated burner systems with closed-loop temperature control. Australian mining fleets and Indonesian palm oil logistics operators specify these for low-load duty cycles where passive regeneration fails.
- Hybrid System:Combined passive-active architectures with predictive control algorithms. China's heavy-duty OEMs are adopting these for National VI-b pre-compliance to minimize fuel consumption penalties during regeneration events.
- Passive Regeneration:Nitrogen dioxide-based soot oxidation without external energy input. Mature technology dominates Southeast Asian Euro IV-equivalent fleets where hardware cost minimization overrides efficiency optimization.
- Catalyst Technology:Washcoat formulations spanning base-metal zeolites to platinum-group metal dispersions. Japanese suppliers lead in low-temperature NOx conversion efficiency for urban stop-and-go validation protocols.
By installed base, passive regeneration dominates. By specification momentum, hybrid systems are climbing the fastest.
End User:
Customer type determines warranty terms, technical support intensity, and procurement contract structure across the value chain.
- OEMs:Factory-fit system integrators with multi-year platform supply agreements. Chinese heavy-duty truck manufacturers source complete SCR-DPF modules from Tier 1 suppliers with captive sensor and dosing manufacturing.
- Fleet Operators:Large-scale logistics and mining companies with total cost of ownership contracting. Australian iron ore haulers and Indonesian coal transporters consolidate procurement through single-source system integrators.
- Aftermarket Providers:Independent distributors and retrofit installers serving legacy fleet segments. India's Delhi-Mumbai corridor hosts dense networks of Bharat Stage VI conversion specialists.
- Vehicle Manufacturers:Passenger car and light commercial producers with platform-specific packaging constraints. Japanese and South Korean OEMs drive gasoline particulate filter specification for direct-injection engine families.
By contract value, OEMs lead procurement. By expansion rate, fleet operators are pulling ahead.
Sale Channel:
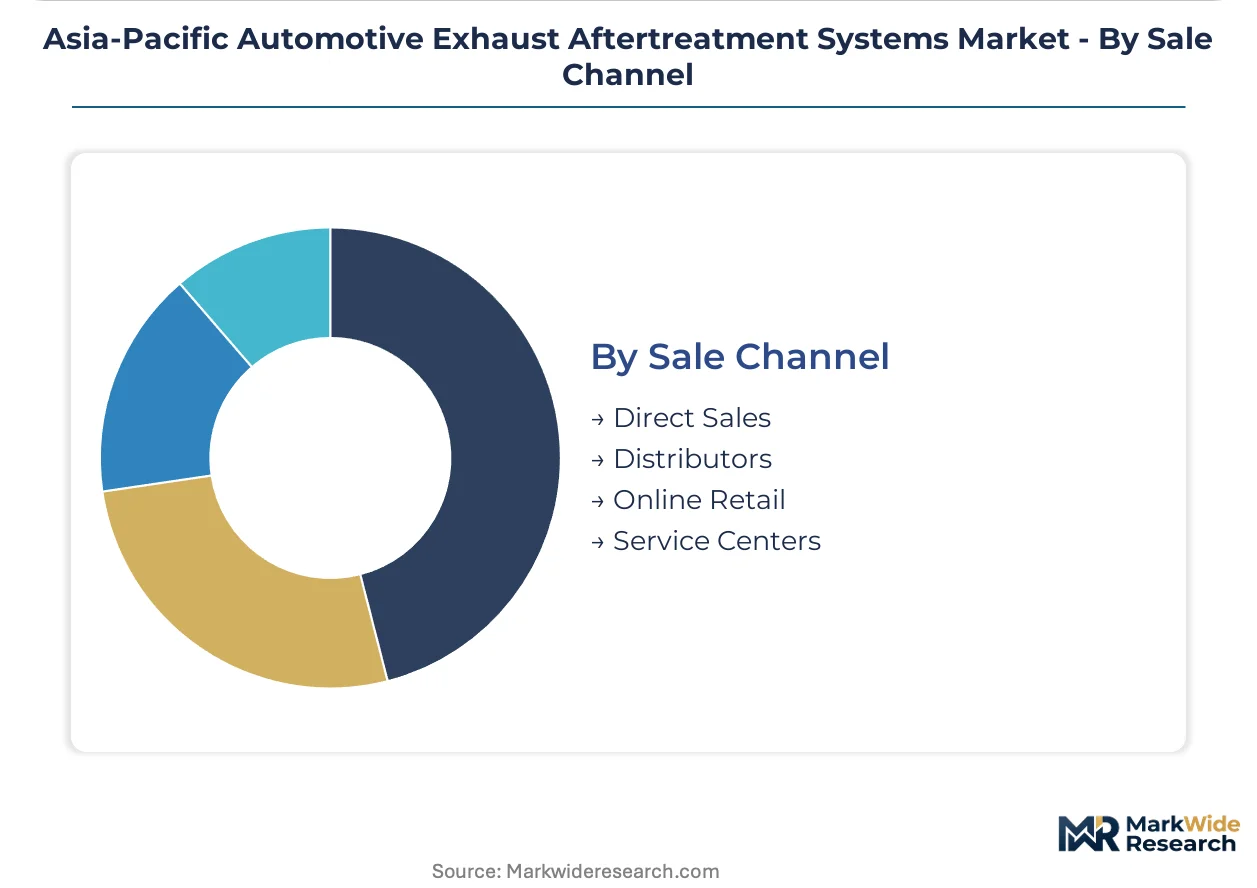
Channel mix varies sharply between metropolitan clusters with service infrastructure and dispersed geographies where direct distribution is uneconomical.
- Direct Sales:Manufacturer-to-OEM relationships with embedded engineering support. Continental AG and Tenneco Inc. maintain dedicated account teams at Chinese heavy-duty truck headquarters in Jinan and Baoding.
- Service Centers:Authorized repair networks with diagnostic capability and trained technicians. India's authorized Bharat Stage VI service points concentrate in Maharashtra, Gujarat, and Tamil Nadu.
- Distributors:Regional stocking intermediaries covering fragmented aftermarket demand. Indonesian archipelago logistics rely on Java-based distributors for AdBlue and replacement filter supply to outer island fleets.
- Online Retail:E-commerce platforms for standardized consumables and replacement components. Philippine and Vietnamese independent operators source urea and gaskets through B2B marketplaces with limited technical validation.
By transaction count, distributors lead. By margin capture, direct sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows across the Asia-Pacific region reveal a structural deficit in aftertreatment substrate manufacturing, with China importing cordierite and silicon carbide materials while exporting finished SCR and DPF modules to Southeast Asian markets.
China
Shandong and Jiangsu provinces host concentrated cordierite filter substrate production serving domestic heavy-duty truck OEMs. The Ministry of Ecology and Environment enforces National VI standards mandating combined SCR-DPF architectures, compressing supplier validation timelines for National VI-b pre-compliance. Jinan and Baoding cluster as headquarters cities where system integrators maintain dedicated engineering teams.
India
Delhi-Mumbai freight corridors drive Bharat Stage VI retrofit demand across legacy commercial fleets. The Central Pollution Control Board mandates diesel particulate filters and selective catalytic reduction for heavy commercial vehicles, forcing hardware upgrades. Maharashtra, Gujarat, and Tamil Nadu concentrate authorized service points with diagnostic capability for compliance validation.
Japan
Kanto and Kansai manufacturing regions anchor gasoline particulate filter specification for direct-injection passenger car platforms. The Ministry of Land, Infrastructure, Transport and Tourism extends certification requirements to real-driving emission test protocols including urban stop-and-go profiles. Nagoya-based suppliers lead development of low-temperature NOx conversion coatings.
Australia
Mining and logistics sectors in Western Australia and Queensland consolidate procurement through single-source system integrators warranting total cost of ownership. Iron ore haulers specify active regeneration systems for low-load duty cycles where passive architectures fail. Perth and Brisbane serve as fleet management hubs demanding predictive maintenance subscriptions.
Indonesia
Java-based distributors supply AdBlue and replacement filters to outer island logistics operators facing urea infrastructure gaps. The Ministry of Environment and Forestry prepares emission mandates for 3.5 million uncontrolled heavy vehicles. Jakarta and Surabaya concentrate metropolitan fleet adoption while archipelago logistics remain constrained by distribution network underdevelopment.
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market Competitive Environment
Listed leaders compete with private specialists across technology integration depth, with public companies commanding system-level supply agreements while private fabricators capture module subcontracting. The vendor base organizes into three tiers: integrated system architects with captive sensor and dosing manufacturing, scale-focused exhaust component producers with multi-province manufacturing footprints, and regional specialists in catalyst formulation or filter substrate production. Competitive moves center on backward integration into platinum-group metal sourcing and geographic expansion through joint ventures with Chinese heavy-duty OEMs.
Among Germany-based system architects, Continental AG exemplifies the integrated tier with control over sensor and urea-dosing technology. Tenneco Inc. represents North American scale players with manufacturing presence across multiple Chinese provinces. Cummins anchors the technology leadership position in active regeneration controls for heavy-duty diesel applications. These three companies illustrate divergent strategic postures: captive technology depth, manufacturing scale, and application-specific expertise respectively.
| Leading Market Players |
|---|
| Continental AG |
| Tenneco Inc. |
| Cummins |
| Delphi Technologies PLC |
| Bosal Group |
| Donaldson Company |
| Harris Performance |
| Clean Diesel Technologies Inc. |
| Faurecia |
| Others |
Value Chain & Pricing Dynamics
Substrate manufacturing scale in Shandong and Jiangsu provinces anchors both regional supply concentration and pricing floors for cordierite and silicon carbide filter materials. China's National VI enforcement timeline compresses supplier validation cycles, forcing OEMs to absorb premium pricing for pre-certified hardware while squeezing margin headroom on legacy module contracts.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with multi-year platform supply agreements. Price differentiation stems from certification grade—National VI-a versus VI-b compliance tiers—and volume scale commitments that unlock tiered rebates. Cost compression in the aftermarket retrofit segment is intensifying because Bharat Stage VI conversion specialists compete on installed cost along Indian freight corridors. Fleet operators exhibit the highest price sensitivity due to total cost of ownership contracting pressures, while mining sector buyers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Inventory lead times for platinum-group metals extend procurement cycles for catalyst washcoat suppliers dependent on South African and Russian rhodium concentrates. Raw material sourcing draws from cordierite deposits in China, silicon carbide production in Japan, and PGM refining in South Africa. Single-source vulnerability concentrates in Shandong province filter substrate foundries serving domestic heavy-duty OEMs. Distribution runs through OEM captive supply agreements for factory-fit SCR-DPF modules, with aftermarket channels relying on Java-based distributors for Indonesian archipelago coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
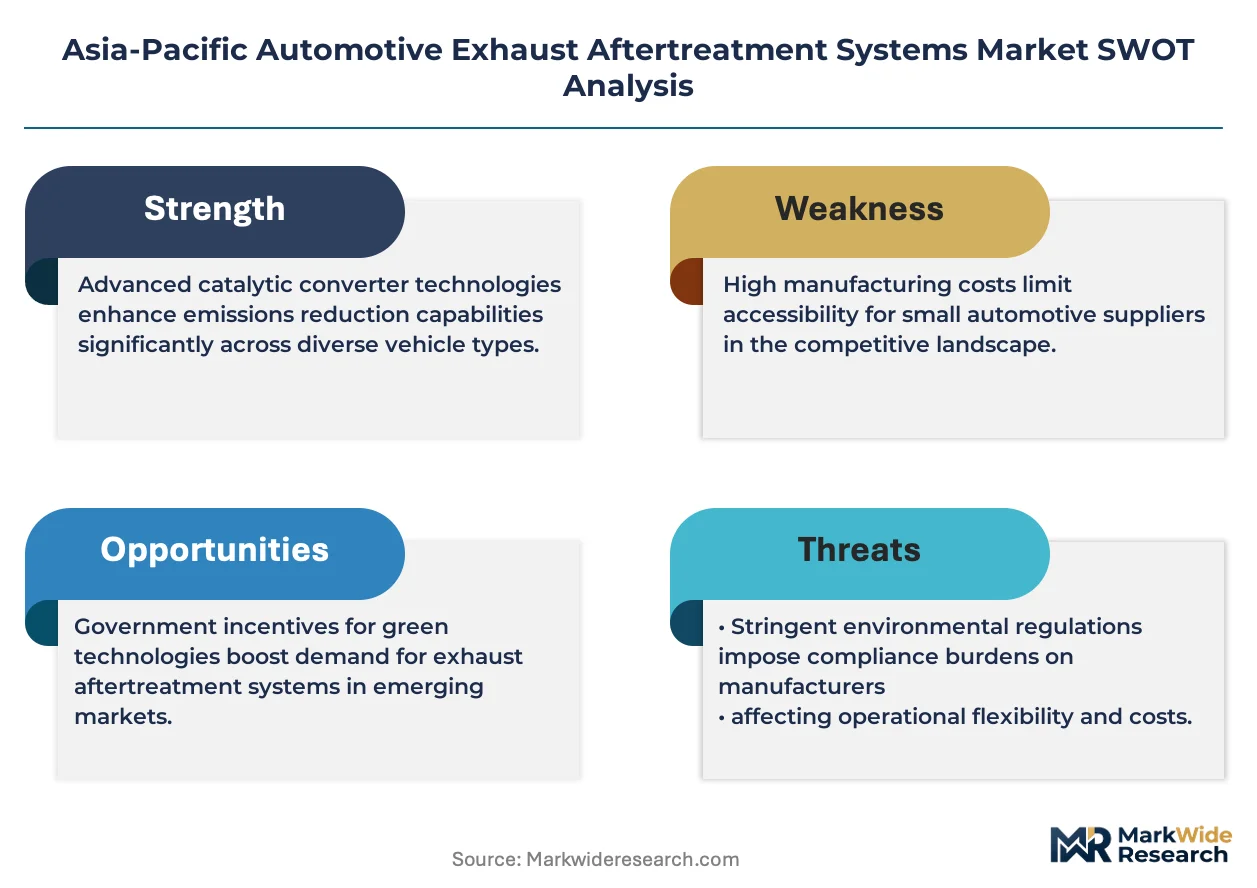
This market functions as a defensive-moat arena where regulatory entrenchment creates high switching costs—once OEMs validate a system integrator's National VI-b hardware, platform redesign penalties lock in multi-year relationships.
For Market Incumbents: Compound technology leadership in active regeneration controls through backward integration into temperature sensor manufacturing, insulating margin structures from component cost volatility. Deepen captive urea-dosing module production to defend against emerging Chinese cost-optimized suppliers penetrating the compact system segment. Prioritize certification investment for real-driving emission protocols ahead of Japan's METI enforcement timeline expansion.
For New Entrants and Emerging Players: Bharat Stage VI fast-track certification for Delhi-Mumbai corridor retrofit specialists opens immediate revenue traction without OEM platform engineering barriers. Target Indonesia's impending Ministry of Environment and Forestry mandates for the 3.5 million uncontrolled heavy vehicle parc, where urea infrastructure gaps favor lean NOx trap architectures over SCR complexity. Pursue joint venture structures with Chinese provincial OEMs to bypass captive supply agreement lock-in.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors catalyst formulation specialists with proprietary base-metal zeolite patents, as platinum-group metal substitution accelerates across the analysis window. Long-term viability hinges on regulatory enforcement durability rather than electrification displacement timelines. Monitor China MEE certification cycle compression as the inflection signal—accelerated validation timelines strain supplier capacity and favor scaled incumbents with captive testing infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive temperature probe production insulates Continental AG from component margin erosion. |
| National VI-b Pre-Certification Investment | Accelerated validation capacity secures platform supply agreements with Jinan and Baoding OEMs. |
| Joint Venture with Chinese Heavy-Duty OEM | Localized manufacturing footprint reduces logistics exposure across Shandong and Jiangsu provinces. |
| Lean NOx Trap Architecture Development | Lower-cost alternative targets Indonesian and Vietnamese light commercial segments with infrastructure constraints. |
| Subscription-Based Fleet Service Model | Predictive maintenance contracts with Australian mining operators generate recurring revenue beyond hardware sales. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet maintenance managers; and secondary validation against vehicle production databases, customs trade records for cordierite and silicon carbide substrates, and regulatory filings from China's MEE and India's Central Pollution Control Board. Bottom-up segmentation modeling triangulated against top-down market sizing from regional vehicle parc projections and emission mandate phase-in schedules.
Across the projection horizon, the analytical framework modeled demand across vehicle class, propulsion architecture, and regional regulatory cluster dimensions. CAGRs were derived from regression analysis of historical adoption curves mapped to enforcement intensity differentials. Forecast inputs incorporated platinum-group metal price trajectory assumptions and urea infrastructure buildout timelines for Southeast Asian markets.
Decision-makers should treat outputs as directional under sustained National VI enforcement and Bharat Stage VI retrofit program continuity; material deviation in regulatory delay or electrification acceleration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
US Car Care Products Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
Silicone in Car Care Products Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Heavy-Duty Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
United Kingdom Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market