
 Global Industrial Wooden Crates Market | 2026-2036
Global Industrial Wooden Crates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Wooden Crates Market Intelligence
Procurement behavior among large-scale industrial buyers is shifting from fragmented, transactional purchases to consolidated, long-term contracts. This trend favors large suppliers with extensive networks. Millwood Inc. leverages its national footprint in the United States to serve these consolidated accounts. Universal Forest Products specializes in a diverse range of wood-based industrial products, while TransPak differentiates through its custom crating and logistics services for high-value goods.
Industrial wooden crates are rigid shipping containers, constructed with wood sheathing or open slats, designed for the secure transport and storage of goods. They are engineered to protect contents from impact, compression, and environmental factors during domestic and international shipping. While standard wooden crates command volume, custom wooden crates for oversized or sensitive equipment generate higher margins. The selection between hardwood and softwood material grades often depends on the load-bearing requirements and cost constraints of the specific end-use sector.
International trade is governed by the ISPM 15 standard, which mandates heat treatment or fumigation to prevent pest spread, enforced by bodies like the USDA in the United States and the General Administration of Customs in China. These phytosanitary regulations directly influence material sourcing and processing costs for crate manufacturers. Future competitiveness will hinge on securing certified, sustainable wood supply chains while navigating volatile lumber prices and freight costs.
Market Dynamics
The central structural force shaping the industrial wooden crates market is the persistent tension between the non-negotiable costs of phytosanitary compliance under standards like ISPM 15 and the extreme volatility of global lumber and freight prices.
Growth Catalysts
- International Standards Compliance:The mandatory enforcement of the ISPM 15 standard by customs authorities like the USDA and China's GAC creates a consistent demand for certified, heat-treated, or fumigated wooden crates, sustaining a value-added market segment.
- Agricultural Sector Expansion:Continued growth in the global trade of fresh produce, particularly from agricultural economies in Latin America and Southeast Asia, drives volume demand for sturdy, ventilated wooden crates to protect goods during long-haul transit.
- Manufacturing Growth in India:India's focus on expanding its domestic manufacturing base, supported by policy frameworks like the Production Linked Incentive (PLI) scheme, is increasing the need for industrial packaging to transport machinery, components, and finished goods.
Market Restraints
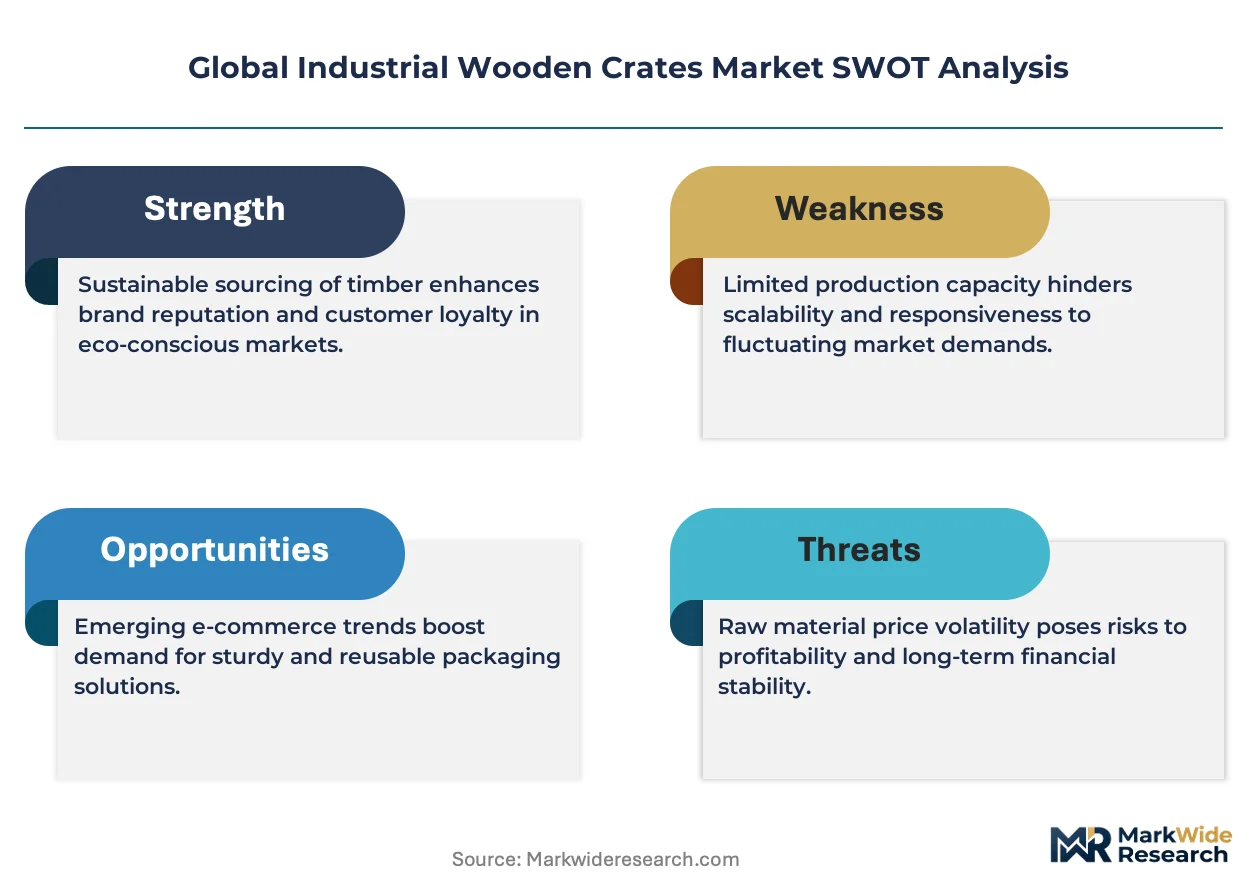
- Lumber Price Volatility:Unpredictable fluctuations in the price of softwood and hardwood, driven by housing market cycles, logging restrictions, and supply chain disruptions, create significant margin pressure and make long-term contract pricing difficult for crate manufacturers.
- Substitution from Plastic Crates:In closed-loop logistics systems and for applications requiring high durability and reusability, engineered plastic and composite containers present a significant substitution threat to traditional wooden crates, especially where weight is a concern.
- Cost of Phytosanitary Treatment:The capital and operational costs associated with installing and running kilns for heat treatment or managing fumigation processes to meet ISPM 15 standards represent a significant barrier for smaller, less capitalized crate producers.
Strategic Opportunities
- Smart Crate Development:Integrating IoT sensors for tracking location, temperature, and shock into high-value custom crates offers a new service-based revenue stream, particularly for shipping sensitive electronics, medical devices, or aerospace components.
- Renewable Energy Sector Crating:The global build-out of renewable energy infrastructure creates demand for highly specialized, oversized custom crates for transporting fragile and heavy components like solar panels, inverters, and wind turbine gearboxes.
- Sustainable Sourcing Certification:Proactively developing and marketing supply chains certified by the Forest Stewardship Council (FSC) or the Programme for the Endorsement of Forest Certification (PEFC) can attract environmentally conscious enterprise customers.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of skilled carpenters and woodworkers capable of designing and fabricating complex, custom-engineered crates for specialized equipment hinders the ability of manufacturers to scale up their high-margin business lines.
- Logistics Cost Management:Navigating and absorbing volatile and rising freight costs, both for inbound lumber and outbound finished crates, presents a constant operational challenge that directly impacts profitability and competitive pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Wooden Crates Market |
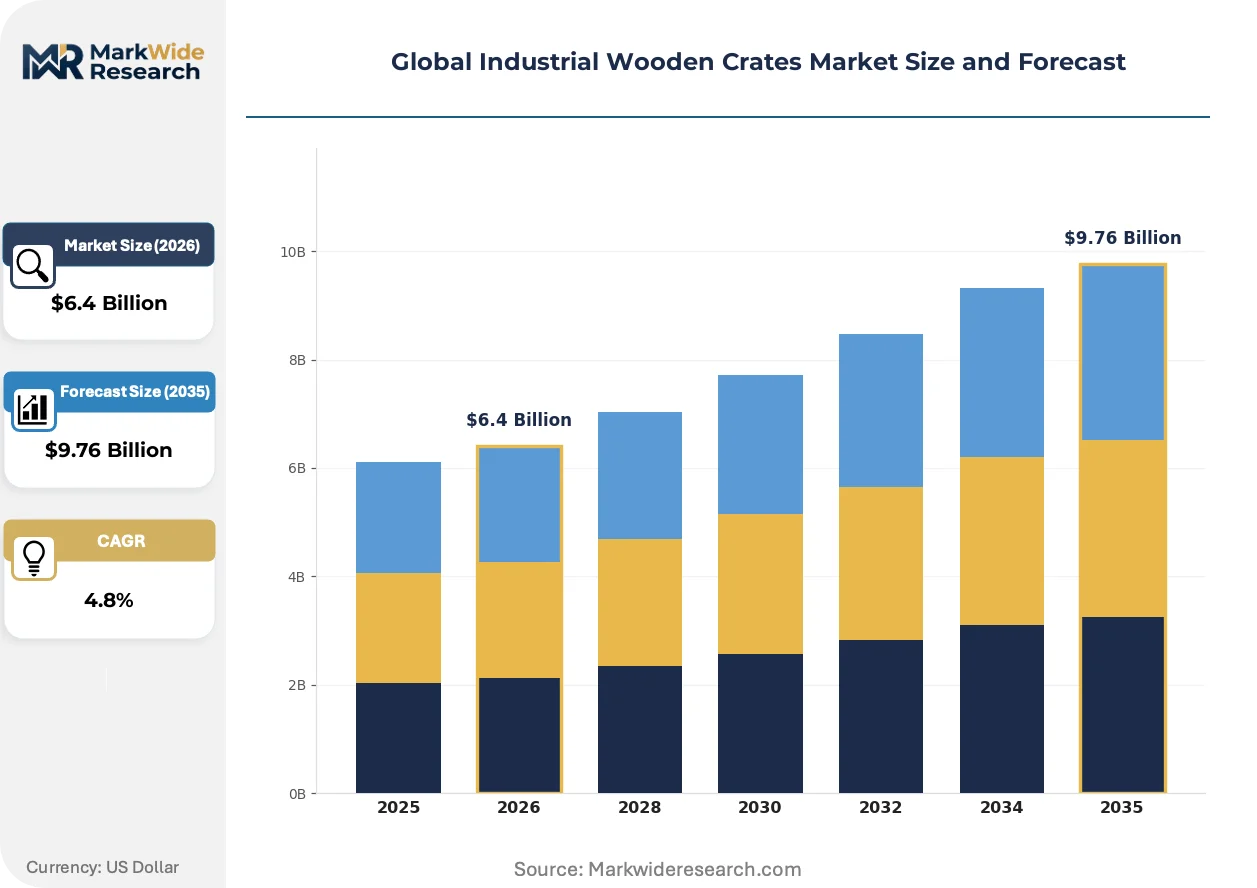
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Wooden Crates, Custom Wooden Crates, Collapsible Wooden Crates, Heavy-Duty Wooden Crates, Ventilated Wooden Crates Material Grade: Softwood, Hardwood, Plywood, Recycled Wood, Treated Wood End Use Sector: Manufacturing Plants, Agricultural Producers, Chemical Processors, Electronics Assemblers, Textile Manufacturers Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesale Suppliers, Trade Shows |
| Companies Covered | Unipaq, Inc., Crate Innovations, Millwood Inc., Universal Forest Products, Packaging Specialties Inc., DIA Packaging, Monmouth Packaging, Eltete Packaging, TransPak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Wooden Crates Market Strategic Shifts & Innovations
The industrial wooden crate market is being redefined by a dual push for operational efficiency through automation and supply chain transparency driven by sustainability mandates. These forces compel manufacturers to invest in new production technologies and traceability systems.
Advanced design software, including CAD and CAM programs, allows for the precise modeling of custom crate solutions. Large-scale manufacturers and custom fabricators are adopting these tools to optimize material usage and ensure structural integrity before production begins. This technology is automating the pre-production and cutting stages, reducing manual errors and enabling the rapid prototyping of complex designs for clients in sectors like aerospace and heavy machinery.
New regulations from the European Union concerning deforestation-free products are setting a higher bar for supply chain verification. The policy requires importers to prove that commodities like wood did not originate from recently deforested land. Crate manufacturers who supply customers in the EU are most affected, compelling investment in rigorous traceability systems from the forest to the final product to maintain market access.
A significant shift in purchasing behavior sees large industrial customers consolidating their packaging supply base under long-term agreements. This trend displaces fragmented, spot-buy transactions in favor of strategic partnerships that often include vendor-managed inventory services. The automotive and electronics industries in North America and Europe are at the forefront of this shift, seeking to improve supply chain reliability and reduce administrative overhead.
Global Industrial Wooden Crates Market Segmentation
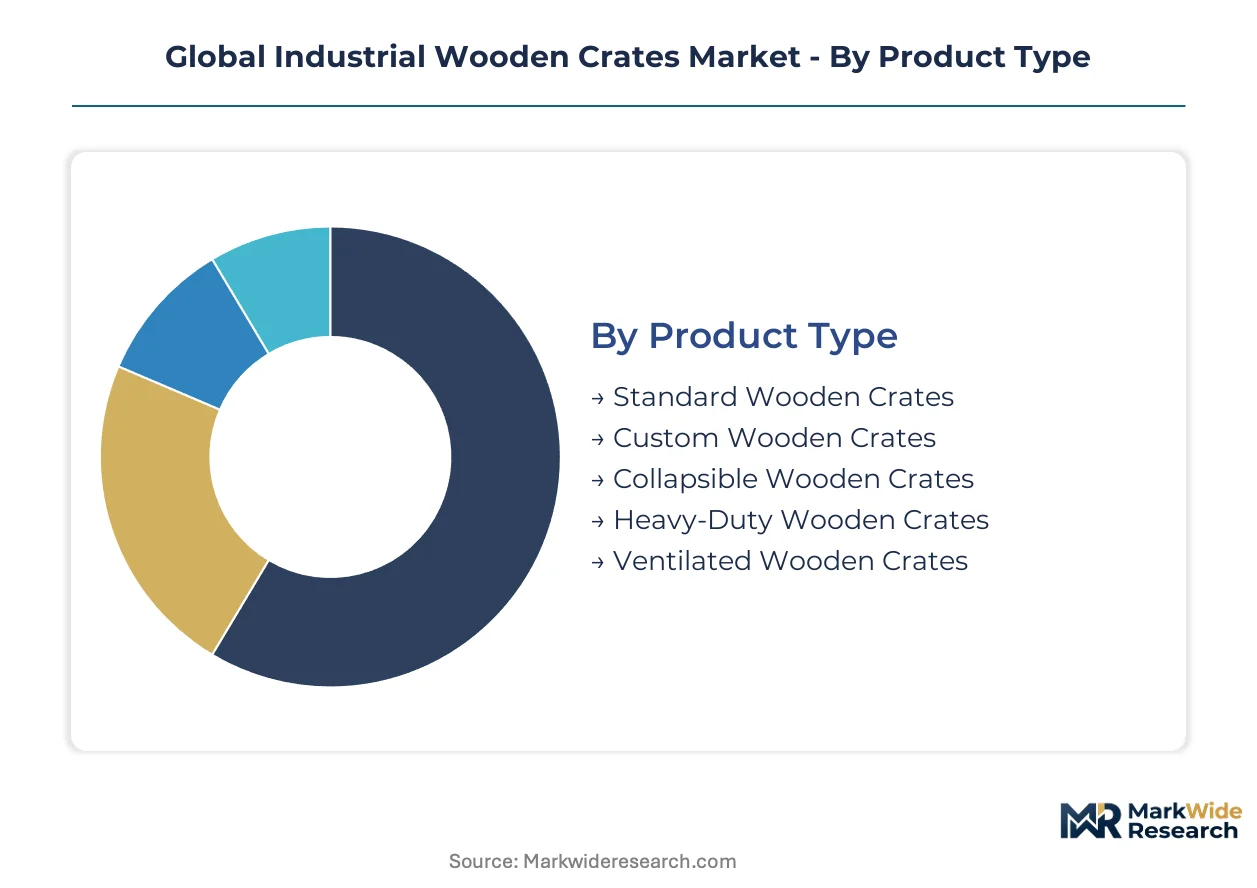
The segmentation of the industrial wooden crates market illuminates varied requirements across diverse end-use applications and operational scales. Understanding these distinct segments helps manufacturers tailor product offerings and optimize production processes. Each category reflects specific demands for protection, durability, and logistical efficiency in global trade.
Product Type:
The capital intensity within product type segmentation varies significantly, with specialized production lines for custom and heavy-duty crates requiring substantial upfront investment.
- Custom Wooden Crates:These containers are engineered to precise specifications for unique cargo, often incorporating specialized bracing. Demand concentrates in aerospace and heavy machinery industries in Germany, driven by the need for exact fit and maximum protection.
- Heavy-Duty Wooden Crates:Constructed with reinforced lumber and robust fastening, these crates are designed for extreme loads and harsh transit conditions. Global manufacturing hubs in China drive significant demand for transporting industrial equipment.
- Standard Wooden Crates:Mass-produced, general-purpose containers offer cost-effective packaging for various goods.
- Collapsible Wooden Crates:Designed for reusability, these crates disassemble for return logistics, reducing freight costs.
- Ventilated Wooden Crates:Strategic openings ensure air circulation for perishables, crucial for fresh produce exports.
Most installed capacity flows through Standard Wooden Crates. Expansion is steepest in Custom Wooden Crates.
Material Grade:
Material grade segmentation often reflects a tiered cost structure, with softwood representing the entry-level option and specialized treated woods commanding a premium.
- Hardwood:Sourced from deciduous trees, hardwood offers superior strength and density, ideal for heavy-duty and long-term storage applications. Industrial clients in Japan prioritize hardwood for shipping high-value components.
- Treated Wood:This material undergoes processes like heat treatment to meet international phytosanitary standards such as ISPM 15, preventing pest transmission. Global trade routes mandate treated wood for international shipments.
- Softwood:Derived from coniferous trees, softwood is lighter and economical for standard crates.
- Plywood:Engineered wood sheets offer high strength-to-weight ratios for lighter goods.
- Recycled Wood:Utilizing reclaimed timber, this grade supports circular economy initiatives.
The preference for Softwood dominates due to its cost-effectiveness. Treated Wood is gaining traction from stringent international trade regulations.
End Use Sector:
Each end-use sector imposes distinct application-specific requirements on industrial wooden crates, from environmental controls to extreme load-bearing capabilities.
- Manufacturing Plants:These facilities require diverse crating solutions for raw materials and finished goods, often demanding custom sizes. Automotive manufacturers in South Korea rely heavily on robust crating for complex supply chains.
- Agricultural Producers:Growers of fresh produce need ventilated, stackable crates to protect delicate items from damage and spoilage during transit. Latin American economies depend on these for exporting fruits and vegetables.
- Chemical Processors:This sector uses specialized crates for safe transport of sensitive materials.
- Electronics Assemblers:High-value electronic components require crates with anti-static properties.
- Textile Manufacturers:Crates protect fabrics and apparel from moisture and physical damage.
Demand from Manufacturing Plants provides foundational stability. Agricultural Producers exhibits strong potential for future growth.
Distribution Channel:
Distribution channel segmentation is critically influenced by customer type and purchasing behavior, impacting volume, customization, and logistical support.
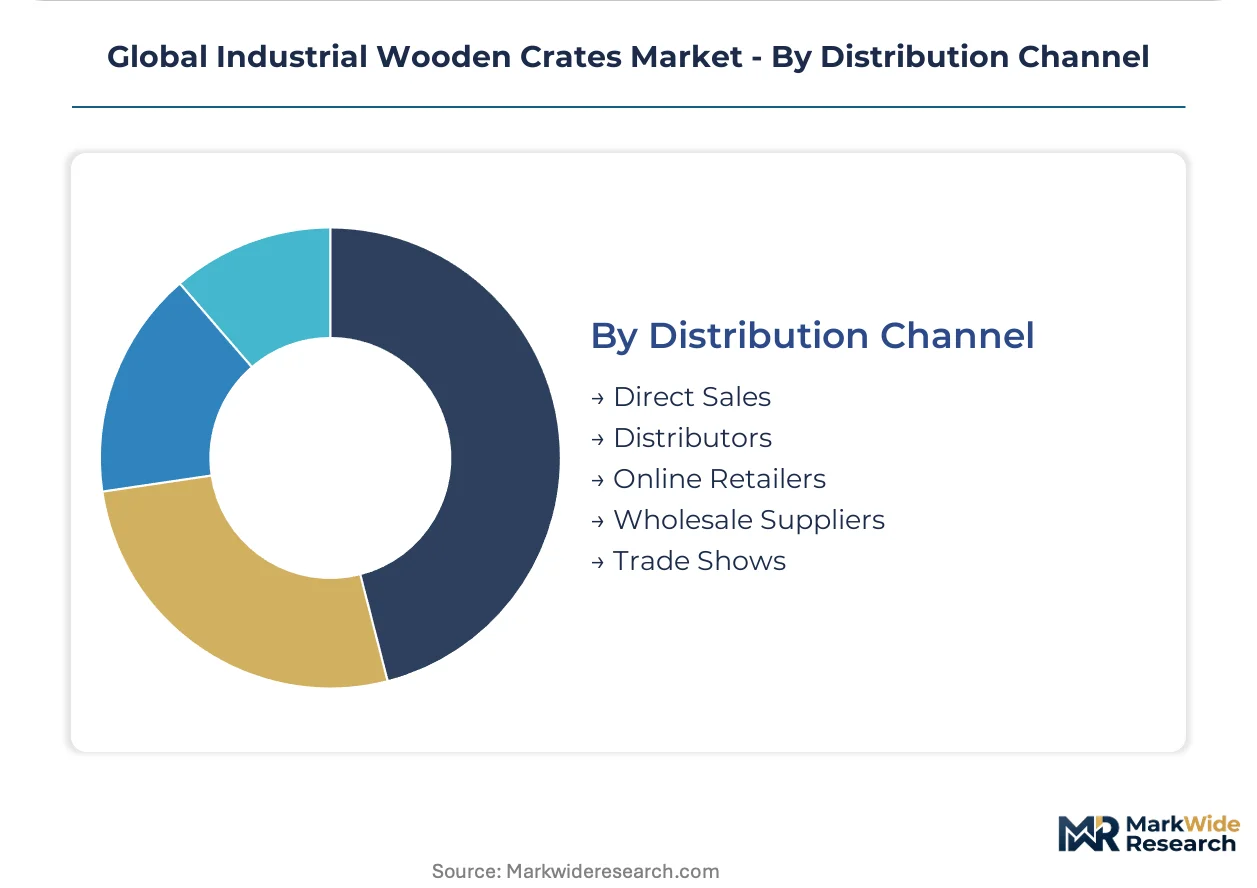
- Direct Sales:This channel involves direct transactions between manufacturers and large industrial clients, facilitating custom orders and long-term contracts. Major automotive companies in North America leverage direct sales for consolidated packaging.
- Distributors:Distributors act as intermediaries, providing regional access and logistical support to small to medium-sized enterprises (SMEs) requiring standardized crates. European logistics networks utilize distributors for diverse manufacturing clients.
- Online Retailers:This channel serves smaller businesses and individual consumers.
- Wholesale Suppliers:Wholesalers cater to businesses requiring bulk standard crates.
- Trade Shows:Manufacturers use trade shows to showcase specialized crating.
The efficiency of Direct Sales supports high-volume transactions. Niche requirements increasingly leverage Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's robust manufacturing sector drives substantial demand for heavy-duty wooden crates, contrasting with the United States where agricultural exports and consolidated industrial accounts shape procurement. This global market reflects diverse regional drivers and regulatory landscapes. Latin American agricultural output also significantly influences demand.
China
Demand for industrial wooden crates in China stems from its expansive manufacturing base and export-oriented economy. The General Administration of Customs (GAC) strictly enforces ISPM 15 standards for all international shipments. Manufacturing clusters in the Yangtze River Delta actively consume standard and heavy-duty crates for machinery and goods transport.
United States
Agricultural producers and large industrial buyers generate consistent demand for wooden crates across the United States. The USDA oversees phytosanitary compliance, mandating heat treatment for international wood packaging materials. Major automotive and electronics industries in the Midwest and Southeast leverage direct sales for packaging solutions.
India
India's burgeoning manufacturing sector, bolstered by the Production Linked Incentive (PLI) scheme, fuels substantial demand for industrial packaging. The country's Directorate General of Foreign Trade (DGFT) ensures adherence to international trade regulations for wood products. Industrial corridors around Chennai and Pune require diverse crating solutions for machinery and components.
Germany
Precision engineering and high-value machinery exports underpin Germany's demand for custom wooden crates. European Union regulations, including those concerning deforestation-free products, influence material sourcing for manufacturers. Aerospace and automotive hubs in Bavaria and Baden-Württemberg require specialized crating for sensitive equipment.
Brazil
Agricultural exports, particularly fresh produce, drive significant volume demand for ventilated wooden crates in Brazil. The country's Ministry of Agriculture, Livestock and Food Supply (MAPA) enforces phytosanitary requirements for wood packaging. Major port cities like Santos and Paranaguá are key distribution points for crates supporting international trade.
Global Industrial Wooden Crates Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the industrial wooden crates market, creating a tiered competitive structure. The market exhibits a mix of large-scale, network-driven suppliers and niche custom fabricators. Dominant strategic archetypes include volume producers of standard crates, custom engineering specialists, and integrated logistics providers. Competitive moves frequently involve geographic expansion to serve consolidated accounts and strategic partnerships to secure sustainable wood supply.
Within the North American market, Millwood Inc. exemplifies a large-scale provider leveraging its national footprint to serve consolidated industrial accounts. Universal Forest Products, Inc., a US-based company, occupies a position as a diversified supplier of wood-based industrial products. Furthermore, TransPak, Inc., another US-headquartered firm, sits within the archetype of a custom crating and logistics service provider for high-value goods. These companies collectively illustrate the varied approaches to market penetration and value proposition within the sector.
| Leading Market Players |
|---|
| Unipaq, Inc. |
| Crate Innovations |
| Millwood Inc. |
| Universal Forest Products |
| Packaging Specialties Inc. |
| DIA Packaging |
| Monmouth Packaging |
| Eltete Packaging |
| TransPak |
| Others |
Cost & Logistics Intelligence
Large industrial buyers, seeking supply reliability and cost predictability, increasingly drive a shift towards long-term contract-based pricing in the industrial wooden crates market. This procurement behavior consolidates demand and favors suppliers with extensive networks.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard wooden crates, particularly in high-volume segments. The dominant pricing model involves contract-based long-term agreements for large accounts, while custom projects utilize project-based pricing. Price differentiation often stems from the customization level required and adherence to specific certification levels like ISPM 15. Pricing pressure stems from the extreme volatility of global lumber prices and rising freight costs. Small to medium-sized enterprises (SMEs) exhibit the highest price sensitivity, whereas aerospace and heavy machinery sectors prioritize protection over cost.
Supply Chain Analysis
Direct sales channels handle complex custom orders and consolidated accounts, while distributors serve regional SMEs with standardized products. The supply chain for industrial wooden crates concentrates heavily in China, the United States, and Brazil, reflecting major manufacturing and agricultural hubs. Raw material dependencies center on softwood and hardwood lumber, alongside specialized fasteners. Commodity price volatility in lumber presents a significant structural risk across the entire supply chain. Logistics chokepoints and rising freight costs also impact profitability for manufacturers and distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a late-cycle quality story, with increasing demand for custom-engineered solutions driving value. The shift towards protecting high-value goods necessitates premium specifications and advanced crating designs.
For Market Incumbents: Cement relationships with large industrial buyers through long-term, consolidated contracts that offer vendor-managed inventory services. Invest in advanced automation and CAD/CAM software to optimize material usage and reduce labor costs, countering lumber price volatility. Proactively pursue sustainable sourcing certifications like FSC to differentiate against competitors and meet evolving EU regulations. Expanding vertical integration into wood processing can mitigate raw material supply risks.
For New Entrants and Emerging Players: Logistics service providers offer a viable entry point for specialized crating solutions. Target the renewable energy sector, which demands highly specialized, oversized custom crates for fragile components like wind turbine gearboxes. Focus on developing smart crates with integrated IoT sensors for tracking high-value goods, particularly sensitive electronics. A go-to-market angle emphasizing rapid prototyping and design expertise for complex equipment in Germany can carve out a niche.
For Investors and Strategic Acquirers: Diversified packaging conglomerates are the most active acquirers in this space, seeking to broaden their product portfolios and geographic reach. Long-term viability remains strong due to foundational demand from manufacturing and agriculture. Acquisition targets should prioritize niche custom fabricators with strong engineering capabilities or integrated logistics providers. The signal to watch is the increasing adoption of sustainable sourcing certifications by enterprise customers, indicating future market preference.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Automation | Optimizes material usage and reduces labor costs for crate manufacturers. |
| Develop Smart Crating Solutions | Creates new service-based revenue streams for high-value electronics and medical devices. |
| Secure Sustainable Wood Supply | Attracts environmentally conscious enterprise customers and ensures compliance with EU regulations. |
| Expand Custom Crating Capabilities | Addresses growing demand from aerospace and heavy machinery industries for specialized protection. |
| Consolidate Supply Base Agreements | Enhances supply chain reliability and reduces administrative overhead for large industrial buyers. |
Research Approach
Bottom-up end-use modeling reconciled against top-down production capacity tracking forms the analytical core of this study. Primary interviews with procurement managers, logistics directors, and plant engineers provided qualitative insights. Secondary validation drew from customs trade data, forestry reports, manufacturing output statistics, and corporate financial statements.
The forecast framework utilizes an input-output matrix to project market dynamics over the projection horizon. Segmentation dimensions modeled include product type, material grade, end-use sector, distribution channel, and regional manufacturing activity. Compound annual growth rates (CAGRs) were derived through regression analysis and expert consensus. Key industry-specific forecast inputs include lumber price indices and ISPM 15 compliance rates.
Revisions become necessary when geopolitical trade disruptions, sudden shifts in commodity lumber availability, or unforeseen regulatory changes materialize. Forecasts reflect assumptions regarding economic stability and supply chain resilience. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Transport Racks Market
Industrial Packaging
Industrial Plastic Bags Market
Industrial Packaging
Middle East and Africa Octabin Market
Industrial Packaging
Overpack Drum Market
Industrial Packaging
Industrial Bulk Packaging Market
Industrial Packaging
Corrugated Automotive Packaging Market
Industrial Packaging
Industrial Pails Market
Industrial Packaging
Cone Bottom Tank Market
Industrial Packaging
Corrugated Bulk Bins Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Anti-Static Reel Racks Market
Industrial Packaging
Dunnage Racks Market
Industrial Packaging
Asia-Pacific Warehouse Drums and Barrel Market
Industrial Packaging
Nestable Drums Market
Industrial Packaging
Industrial Packaging Market
Industrial Packaging
Bulk Packaging Market