
 Corrugated Automotive Packaging Market | 2026-2036
Corrugated Automotive Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Automotive Packaging Market Analysis
Buyer concentration among vehicle assemblers is decoupling from traditional tier-1 dependency as battery OEMs and EV platform specialists enter procurement channels with distinct specifications. DS Smith Plc leverages its European recycling infrastructure to supply closed-loop programs for German automakers. International Paper Company anchors North American capacity through integrated virgin fiber mills serving Detroit-area assembly plants. Smurfit Kappa Group competes on modular tray designs that adapt to multiple powertrain formats without tooling changes.
Corrugated automotive packaging consists of engineered paperboard structures, typically fluted medium laminated between linerboards at basis weights from 125 to 400 grams per square meter, designed to protect components through compression strength and vibration dampening during multimodal transit. Boxes and trays dominate current volume as standardized formats for engine and transmission modules, while inserts capture expanding margin pools through custom die-cut configurations for battery cells and electronic control units. Recycled paper feeds the bulk of shipping applications, though virgin fiber sustains premium protective packaging segments where moisture resistance and dimensional stability under load are critical.
The EPA's automotive waste reduction guidelines and China's MEE packaging circularity rules are elevating post-consumer content minimums and end-of-life recovery obligations across supplier tiers. REACH restrictions on certain coating chemistries and California's extended producer responsibility frameworks are forcing material substitutions in laminated and coated paper grades. Stakeholders must monitor how battery packaging safety standards from transport regulators intersect with state-level recycling mandates to determine whether regional format adaptation or global platform standardization offers lower compliance cost.
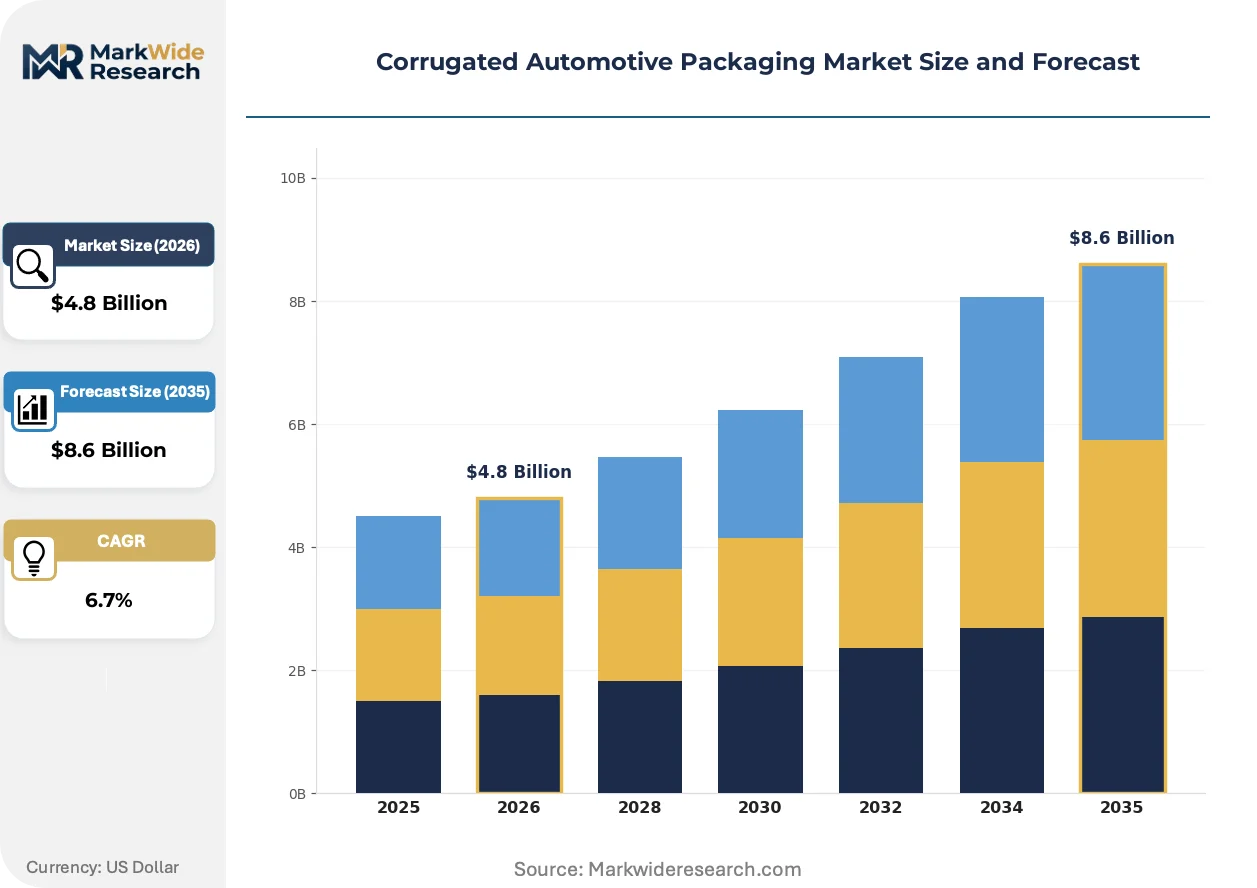
Market Dynamics
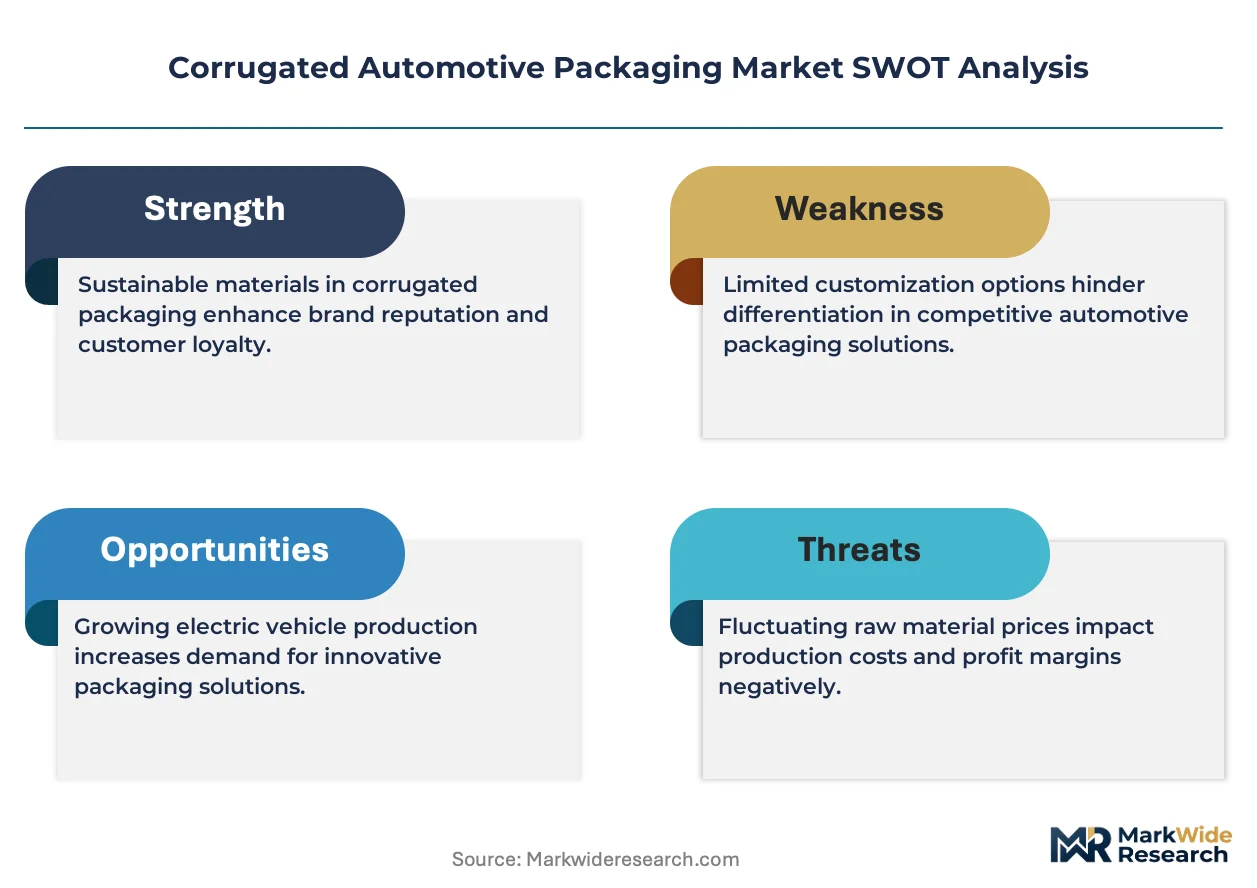
The corrugated automotive packaging sector faces a structural compression between battery OEM procurement autonomy and legacy tier-1 supplier networks, forcing converters to engineer dual-channel fulfillment systems without duplicating fixed assets.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability thresholds are accelerating closed-loop partnerships between converters and German vehicle assemblers.
- EV battery pack logistics:Lithium-ion cell transport requirements for thermal runaway containment are creating specialized demand for flame-retardant corrugated architectures.
- Just-in-time assembly corridors:Stuttgart-to-Wolfsburg supply nodes require precision-timed protective packaging with zero-defect delivery guarantees.
Market Restraints
- Old corrugated container price volatility:Recycled fiber input costs swing with municipal collection rates, compressing converter margins unpredictably.
- REACH coating restrictions:Banned chemistries in moisture-barrier laminates force expensive reformulation of food-contact-grade alternatives.
- Plastic returnable totes:Durable injection-molded containers threaten high-volume engine part shipments with lower per-trip costs.
Strategic Opportunities
- India automotive manufacturing:PLI scheme incentives for electric vehicle production are creating virgin demand for export-grade protective packaging.
- Battery cell-to-pack modularity:Standardized tray formats spanning cylindrical, prismatic, and pouch cell geometries reduce tooling amortization.
- California extended producer responsibility:Post-consumer content mandates favor converters with integrated recycling infrastructure.
Industry Challenges
- Structural engineer talent scarcity:Finite element analysis expertise for dynamic load simulation commands premium compensation.
- Dual certification timelines:UN 38.3 lithium battery transport approval叠加 ISTA 3A transit testing extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Automotive Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Trays, Inserts, Pallets Material: Recycled Paper, Virgin Fiber, Laminated Paper, Coated Paper End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Shipping, Storage, Protective Packaging, Retail Display |
| Companies Covered | DS Smith Plc, Packaging Corporation of America, International Paper Company, Sealed Air Corporation, Georgia-Pacific LLC, Smurfit Kappa Group, Mondi Group, Pratt Industries, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Automotive Packaging Market Emerging Trajectories
Active reshaping in this market stems from the collision of electrification-driven packaging complexity with regulatory compression on material circularity, forcing simultaneous innovation in protective performance and end-of-life recovery.
Fluted honeycomb hybrid structures are consolidating protective packaging architectures for battery modules. Tier-1 battery OEMs in Germany and South Korea specify these composites for 400+ kilogram pack assemblies. The technology is consolidating what previously required separate cushioning, bracing, and moisture-barrier layers into single-source supply agreements.
China's MEE packaging circularity rules are mandating traceable post-consumer fiber content across automotive supplier tiers. Domestic converters must document recovery chain custody from collection through re-pulping. Battery packaging for export markets faces the strictest audit protocols, with some producers establishing captive recycling streams to guarantee compliance.
Consolidated procurement desks at EV platform specialists are displacing fragmented purchasing through legacy component suppliers. These centralized functions negotiate directly with packaging converters for cell-to-vehicle programs, bypassing traditional tier-1 intermediaries. The shift is most visible in California and Shanghai, where new entrants lack incumbent supplier obligations.
Corrugated Automotive Packaging Market Segmentation
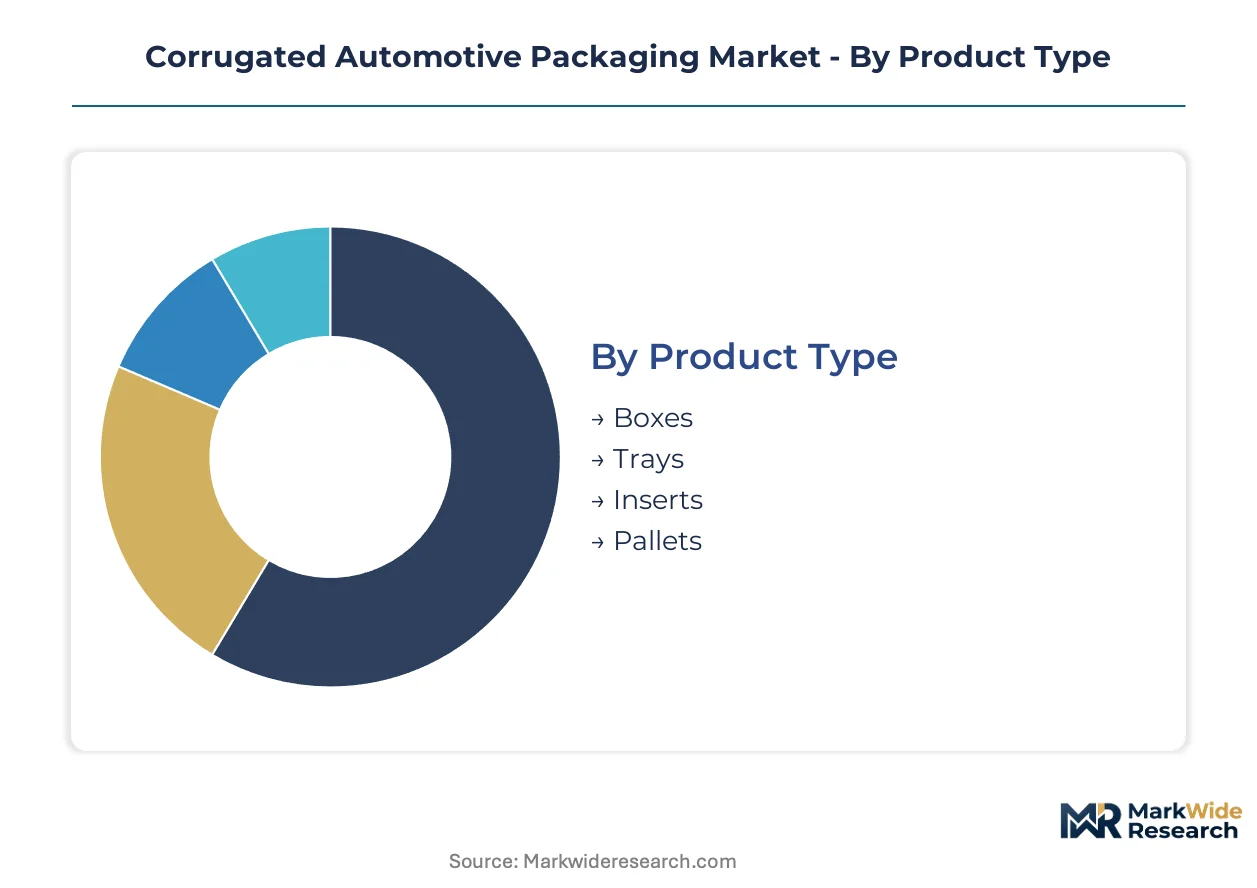
Electrification and regulatory compression are fragmenting demand across incompatible specifications. Procurement desks now source through parallel channels—legacy tier-1 networks for internal combustion powertrains, direct converter relationships for battery platforms—forcing segmentation logic that tracks both material performance and channel autonomy.
Product Type:
Structural format determines compression strength, nesting efficiency, and automation compatibility on assembly lines.
- Boxes:Standardized RSC and FOLC formats dominate high-volume engine and transmission shipments. German OEMs specify double-wall constructions for Stuttgart-to-Wolfsburg just-in-time corridors where pallet-level integrity is non-negotiable.
- Trays:Modular die-cut designs with interlocking corners adapt to multiple powertrain formats without retooling. South Korean battery OEMs specify these for cylindrical and prismatic cell geometries, reducing tooling amortization across platform generations.
- Inserts:Custom-engineered partitions and cushioning for battery modules and electronic control units command premium positioning through finite element analysis validation.
- Pallets:Heavy-duty corrugated platforms with block or stringer configurations substitute for wood in closed-loop European programs subject to ISPM-15 exemption benefits.
Boxes lead on scale; trays lead on momentum.
Material:
Cost tier and performance specification split procurement between circular economy mandates and protective criticality.
- Recycled Paper:Post-consumer fiber at 80-100% content satisfies China's MEE circularity rules and California extended producer responsibility thresholds. Municipal collection rate volatility compresses converter margins unpredictably.
- Virgin Fiber:Unbleached kraft linerboard delivers moisture resistance and dimensional stability under load for premium battery packaging segments. Integrated mill capacity anchors North American supply security.
- Laminated Paper:PE or bio-based barrier films extend shelf life in humidity-exposed storage applications, though REACH restrictions on certain coating chemistries force reformulation cycles.
- Coated Paper:Wax and polymer treatments for grease resistance in powertrain component shipping face substitution pressure from recyclable alternatives.
Recycled paper leads on volume; virgin fiber leads on margin expansion.
End User:
Channel structure is decoupling as battery platform specialists bypass legacy intermediaries.
- OEMs:Consolidated procurement desks at EV platform specialists negotiate direct converter agreements for cell-to-vehicle programs, displacing fragmented tier-1 purchasing.
- Tier-1 Suppliers:Legacy component manufacturers retain packaging specification authority for internal combustion powertrains but lose autonomy on electrified platforms.
- Aftermarket Providers:Fragmented demand for replacement part packaging concentrates in North American and European distribution networks with lower format standardization.
- Vehicle Assemblers:Final assembly plants in Germany's manufacturing corridor require zero-defect delivery guarantees and closed-loop recovery systems.
OEMs lead on specification control; vehicle assemblers lead on recovery obligation intensity.
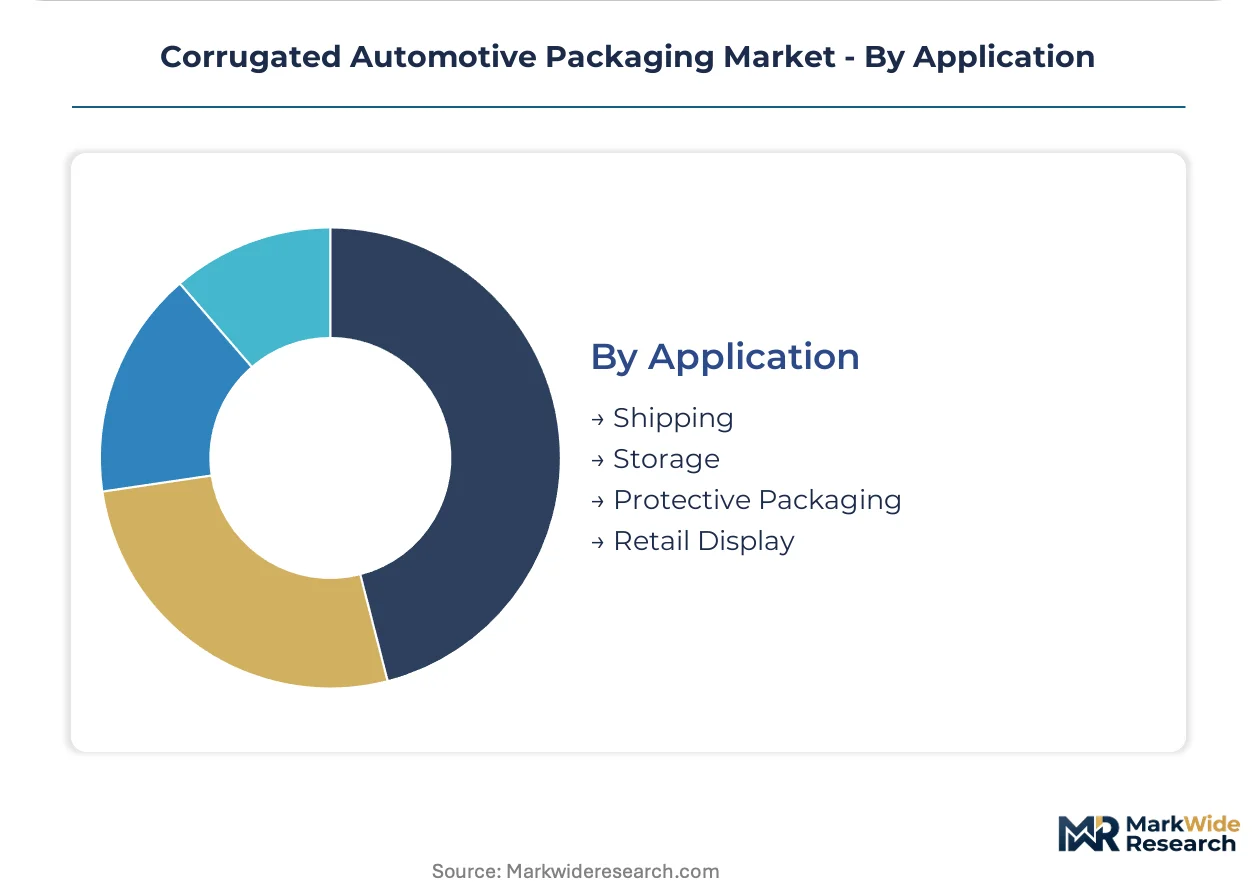
Application:
Functional use case determines protective performance requirements and end-of-life handling protocols.
- Shipping:Multimodal transit from component supplier to assembly plant demands ISTA 3A certification and UN 38.3 compliance for lithium-ion configurations.
- Storage:Long-duration warehousing of battery cells and electronic modules requires moisture-barrier integrity and stack height optimization.
- Protective Packaging:Dynamic load simulation and vibration dampening for 400+ kilogram battery pack assemblies specify fluted honeycomb hybrid architectures.
- Retail Display:Branded point-of-sale formats for aftermarket accessories represent marginal volume with higher print quality specifications.
Shipping leads on volume concentration; protective packaging leads on technical complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers and structural designers concentrate in Germany's automotive manufacturing corridor, China's Yangtze River Delta industrial zone, and the US Midwest assembly belt. These talent clusters anchor converter operations and R&D facilities serving electrification-driven demand.
Germany
Battery OEM procurement autonomy and just-in-time delivery networks drive specialized corrugated demand. The EU Packaging and Packaging Waste Regulation mandates closed-loop recovery systems. Stuttgart-to-Wolfsburg supply corridors require zero-defect protective packaging with precision-timed logistics.
China
EV platform specialists and lithium-ion cell producers expand procurement channels beyond legacy tier-1 networks. MEE packaging circularity rules enforce traceable post-consumer fiber content across supplier tiers. Yangtze River Delta converters establish captive recycling streams to guarantee export compliance.
United States
Detroit-area assembly plants and California EV startups source through divergent procurement structures. EPA automotive waste reduction guidelines elevate post-consumer content minimums. The Midwest integrated mill corridor anchors virgin fiber supply security for premium battery packaging segments.
India
PLI scheme incentives for electric vehicle production generate virgin demand for export-grade protective packaging. BIS standards for recyclable materials intersect with state-level extended producer responsibility frameworks. Tamil Nadu and Gujarat automotive clusters attract converter capacity expansion.
South Korea
Battery OEMs specify modular tray designs adapting to cylindrical and prismatic cell geometries without retooling. MFDS transport safety standards overlap with UN 38.3 lithium battery compliance requirements. Busan-Ulsan industrial zone converters serve cell-to-pack packaging demand for export markets.
Corrugated Automotive Packaging Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Integrated paperboard producers with captive fiber supply anchor premium protective packaging segments, while regional converters capture standardized shipping applications through cost positioning. Strategic archetypes include closed-loop service providers, modular design specialists, and scale-driven commodity suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as electrification fragments procurement channels.
Among European-anchored converters, DS Smith Plc and Smurfit Kappa Group occupy positions within the closed-loop and modular design tiers respectively. International Paper Company represents the North American integrated producer archetype with mill-to-market supply chain control. These three entities exemplify how geographic fiber integration and design engineering capabilities map to divergent customer procurement structures.
| Leading Market Players |
|---|
| DS Smith Plc |
| Packaging Corporation of America |
| International Paper Company |
| Sealed Air Corporation |
| Georgia-Pacific LLC |
| Smurfit Kappa Group |
| Mondi Group |
| Pratt Industries |
| WestRock Company |
| Others |
Supply Flow & Price Mechanics
Fluted honeycomb hybrid adoption for 400+ kilogram battery pack assemblies simultaneously compresses per-unit material costs and concentrates converter bargaining power among tier-1 battery OEMs in Germany and South Korea. These single-source supply agreements displace fragmented multi-layer purchasing, tightening margin capture for engineered protective architectures while loosening price discipline on standardized shipping formats.
Pricing Analysis
The bundled-vs-unbundled service split separates premium protective packaging from commodity shipping applications. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity, with UN 38.3 lithium battery transport approval and ISTA 3A transit testing commanding substantial premiums. Cost compression in standardized box formats intensifies because recycled fiber input costs swing unpredictably with municipal collection rates. Tier-1 battery OEMs exhibit lowest price sensitivity due to non-negotiable safety specifications, while aftermarket providers face acute margin pressure on undifferentiated replacement part packaging.
Supply Chain Analysis
Dual-sourcing requirements from German vehicle assemblers and South Korean battery OEMs mandate multi-supplier qualification across virgin fiber mills and captive recycling streams. Supply concentrates in Germany's Stuttgart-to-Wolfsburg corridor, China's Yangtze River Delta, and the US Midwest integrated mill belt. Raw material dependencies center on OCC price volatility, unbleached kraft linerboard availability, and PE barrier film supply. Single-source vulnerability threatens converters lacking backward integration into fiber supply. Distribution runs through just-in-time assembly corridors requiring precision-timed logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Specification intensity for lithium-ion cell thermal runaway containment and UN 38.3 compliance elevates premium protective packaging above commodity substitution threats.
For Market Incumbents: Cement closed-loop recovery dominance by expanding captive recycling infrastructure in Germany's manufacturing corridor to meet EU Packaging and Packaging Waste Regulation mandates. Deepen structural engineering capabilities for finite element analysis validation as talent scarcity intensifies. Defend against modular tray commoditization by locking in multi-generation cell-to-pack platform agreements with South Korean battery OEMs. For New Entrants and Emerging Players: The price-point gap between flame-retardant honeycomb hybrids and standard double-wall boxes offers entry latitude for mid-tier converters. Target India's Tamil Nadu and Gujarat automotive clusters where PLI scheme incentives generate virgin demand without incumbent supplier obligations. Lead with ISTA 3A certification investment to bypass tier-1 intermediary channels and contract directly with California EV platform specialists. For Investors and Strategic Acquirers: Valuations sit cheapest among regional converters with underutilized virgin fiber capacity and untapped structural engineering benches. Long-term viability hinges on electrification sustaining specification premiums against plastic returnable tote substitution. Watch for battery OEM procurement desk consolidation in Shanghai and California as the inflection signal for direct-channel converter capture.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Infrastructure Expansion | EU Packaging and Packaging Waste Regulation mandates elevate converter compliance premiums in Germany. |
| Structural Engineering Talent Acquisition | Finite element analysis expertise scarcity commands premium compensation in battery packaging validation. |
| Flame-Retardant Honeycomb Hybrid Scale-Up | Tier-1 battery OEMs in South Korea consolidate multi-layer architectures into single-source agreements. |
| Direct OEM Channel Development | EV platform specialists in California and Shanghai bypass legacy tier-1 intermediaries for cell-to-pack programs. |
| India Manufacturing Footprint Establishment | PLI scheme incentives for electric vehicle production generate export-grade protective packaging demand. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged tier-1 supplier procurement directors, OEM platform engineers, converter operations managers, aftermarket distribution heads, and recycling infrastructure specialists. Secondary validation drew from EPA automotive waste reduction guidelines, China's MEE packaging circularity rules, EU Packaging and Packaging Waste Regulation filings, vehicle production databases, and ISTA transit testing protocols. Bottom-up segment sizing and top-down market reconciliation anchored value estimates.
Segment-weighting approaches distributed volume and value across product type, material grade, end-user channel, and application function dimensions. CAGRs were derived from trend extrapolation and driver elasticity modeling across the projection horizon. Forecast inputs incorporated electrification penetration curves, battery pack weight trajectories, and regulatory compliance timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery architectures would alter the outlook for thermal runaway containment specifications. Deviation in OCC price volatility or REACH coating restriction enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Dunnage Racks Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Bulk Liquid Transport Packaging Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Overpack Drum Market
Industrial Packaging
Slip Sheets Market
Industrial Packaging
Industrial Chemical Packaging Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Anti-Static Reel Racks Market
Industrial Packaging
Nestable Drums Market
Industrial Packaging
Corrugated Bulk Bins Market
Industrial Packaging
Global Industrial Wooden Crates Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Transport Racks Market
Industrial Packaging
Middle East and Africa Octabin Market