
 Dunnage Racks Market | 2026-2036
Dunnage Racks Market Size, Share, and Industry Trends Forecast 2026-2036
Dunnage Racks Market Analytics
NSF International food equipment standards is shifting the cost-of-entry calculus for dunnage rack suppliers, forcing design upgrades to meet sanitation benchmarks. Metro leverages its vertical integration across aluminum extrusion and polymer fabrication to sustain compliance leadership. Cambro Manufacturing anchors its position through specialized polymer formulations that resist bacterial colonization. Eagle Group competes on geographic dominance in North American foodservice distribution channels.
Dunnage racks are elevated storage platforms, typically fabricated from aluminum, stainless steel, or high-density polyethylene, designed to hold goods above floor level to prevent moisture damage and contamination in commercial and industrial environments. Standard load ratings range from 1,500 to 3,000 pounds per unit, with slatted or mesh deck configurations enabling drainage and airflow in wet-processing zones. Metal racks command the largest revenue pool due to durability demands in heavy-duty warehousing, while plastic variants represent the fastest-expanding category as FDA-compliant polymer formulations displace wood in food-contact applications. High-capacity configurations capture premium margins in pharmaceutical cold-chain facilities where palletized biologics require validated floor-clearance protocols.
FDA food code provisions, NSF/ANSI 2 food equipment standards, and OSHA material handling regulations collectively shape product specifications and market access for dunnage rack manufacturers. NSF certification functions as a procurement gatekeeper in U.S. foodservice and healthcare verticals, while OSHA load-safety mandates drive specification engineering in industrial warehousing. Stakeholders must monitor evolving polymer recycling mandates and embodied-carbon disclosure requirements as sustainability criteria penetrate capital equipment procurement decisions.
Market Dynamics
NSF/ANSI 2 food equipment certification requirements are compressing supplier margins while simultaneously consolidating procurement authority among large-scale foodservice distributors and contract food management companies. This regulatory pressure is reconfiguring competitive advantage around compliance infrastructure rather than pure manufacturing scale.
Growth Catalysts
- FDA Food Code alignment:State-level adoption of FDA food safety provisions mandates elevated storage for perishables, directly expanding dunnage rack deployment in commercial kitchens and cold storage facilities.
- Aluminum extrusion advances:Improved corrosion-resistant alloy formulations extend rack lifecycles in high-moisture processing environments, reducing total cost of ownership for protein and dairy processors.
- Healthcare foodservice expansion:Hospital and long-term care facility renovation cycles are incorporating NSF-certified polymer dunnage systems to meet Joint Commission sanitation audits.
Market Restraints
- Aluminum price volatility:Primary metal input costs fluctuate with energy-intensive smelting economics, compressing margins for metal rack fabricators during commodity spikes.
- Polymer supply concentration:FDA-compliant high-density polyethylene resin production concentrates among specialized compounders, creating single-source vulnerability for food-grade rack manufacturers.
- Wood pallet persistence:Lower upfront cost and established reverse logistics networks sustain wood platform use in non-regulated warehousing segments.
Strategic Opportunities
- Pharmaceutical cold chain:Biologics distribution requires validated floor-clearance protocols, opening premium specifications for load-rated aluminum systems in temperature-controlled facilities.
- EU Green Deal procurement:Embodied carbon disclosure requirements for capital equipment create first-mover advantage for manufacturers with verified lifecycle assessments and recycled content certifications.
- E-commerce fulfillment:Fresh grocery delivery expansion drives demand for modular, sanitizable storage at micro-fulfillment centers and dark store operations.
Industry Challenges
- NSF certification timelines:Third-party testing and facility audit cycles extend product launch schedules by 8-14 months, delaying revenue recognition for new designs.
- Welding technician scarcity:Qualified aluminum TIG welders command premium wages, constraining production scaling for custom heavy-duty configurations.
- Legacy ERP integration:Foodservice distributors require EDI-compatible order systems, forcing smaller fabricators to absorb software upgrade costs or lose contract eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dunnage Racks Market |
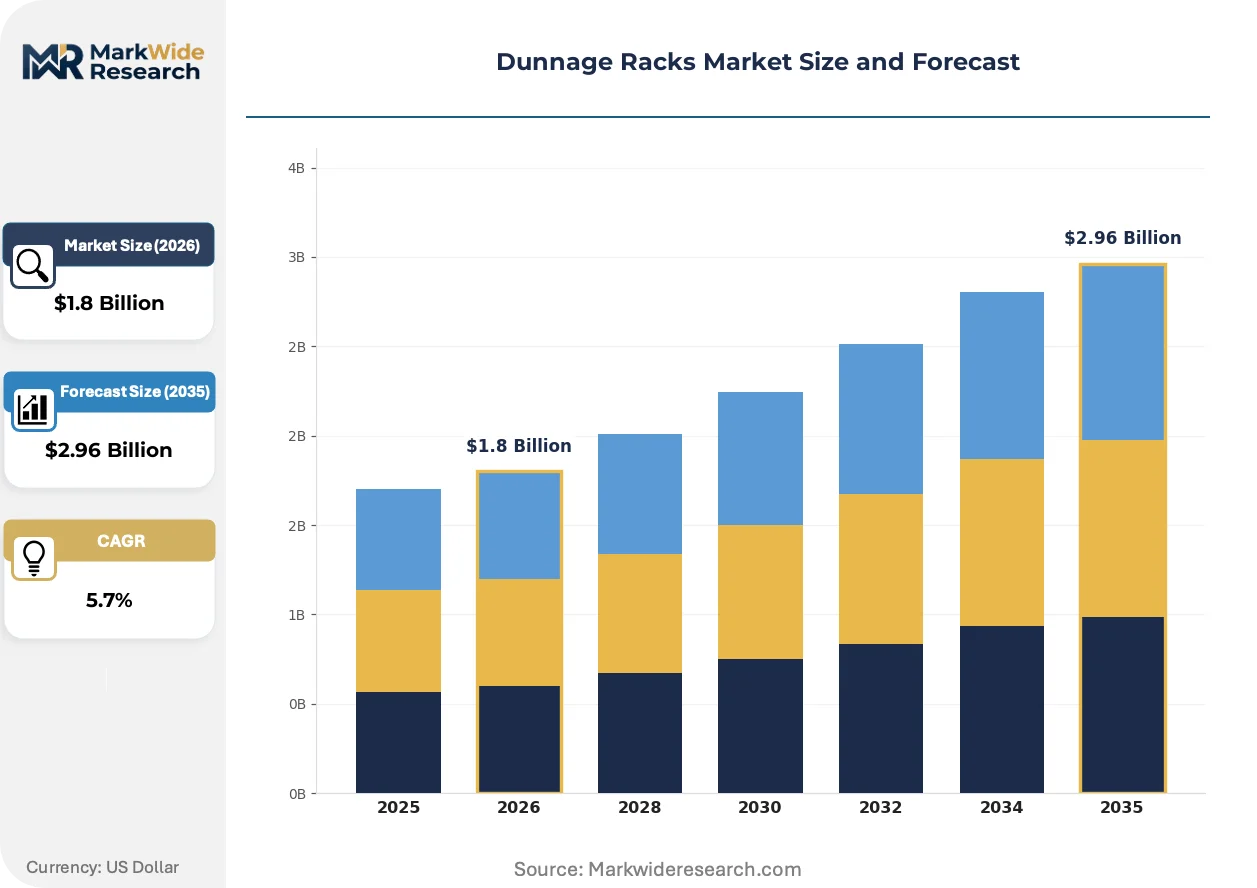
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Racks, Metal Racks, Wood Racks, Stackable Racks Industry Vertical: Food & Beverage, Aerospace, Automotive, Pharmaceuticals Capacity: Standard Capacity, High Capacity, Heavy Duty, Custom Capacity End User: Manufacturers, Retailers, Distributors, Warehousing |
| Companies Covered | Metro (InterMetro Industries Corporation), New Age Industrial, Cambro Manufacturing, Eagle Group, Winholt Equipment, Advance Tabco, Channel Manufacturing, Nexel Industries, Quantum Storage Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dunnage Racks Market Evolving Landscape
Material science advances and procurement digitization are compressing traditional specification cycles while elevating hygiene performance benchmarks. These shifts favor suppliers with integrated design-to-certification capabilities.
Antimicrobial polymer formulations incorporating silver-ion or copper-additive technologies are overtaking standard HDPE in high-sensitivity food processing applications. Poultry and ready-to-eat meal manufacturers specify these surfaces to reduce biofilm formation between sanitation cycles. The technology is compressing replacement intervals for traditional racks while commanding 15-25% price premiums.
REACH regulation restrictions on certain metal finishing chemistries are forcing European fabricators to migrate toward mechanical surface preparation and anodizing alternatives. This transition elevates capital requirements for coating line reconfiguration. German and French food equipment manufacturers are responding by consolidating finishing operations to achieve scale economies.
Centralized procurement through group purchasing organizations is displacing decentralized site-level purchasing in multi-unit restaurant and healthcare systems. Contract administrators now specify NSF-certified dunnage racks as standard across facility portfolios. This concentration is most visible in United States contract foodservice, where three purchasing collectives control specification authority for over 40% of institutional foodservice locations.
Dunnage Racks Market Segmentation
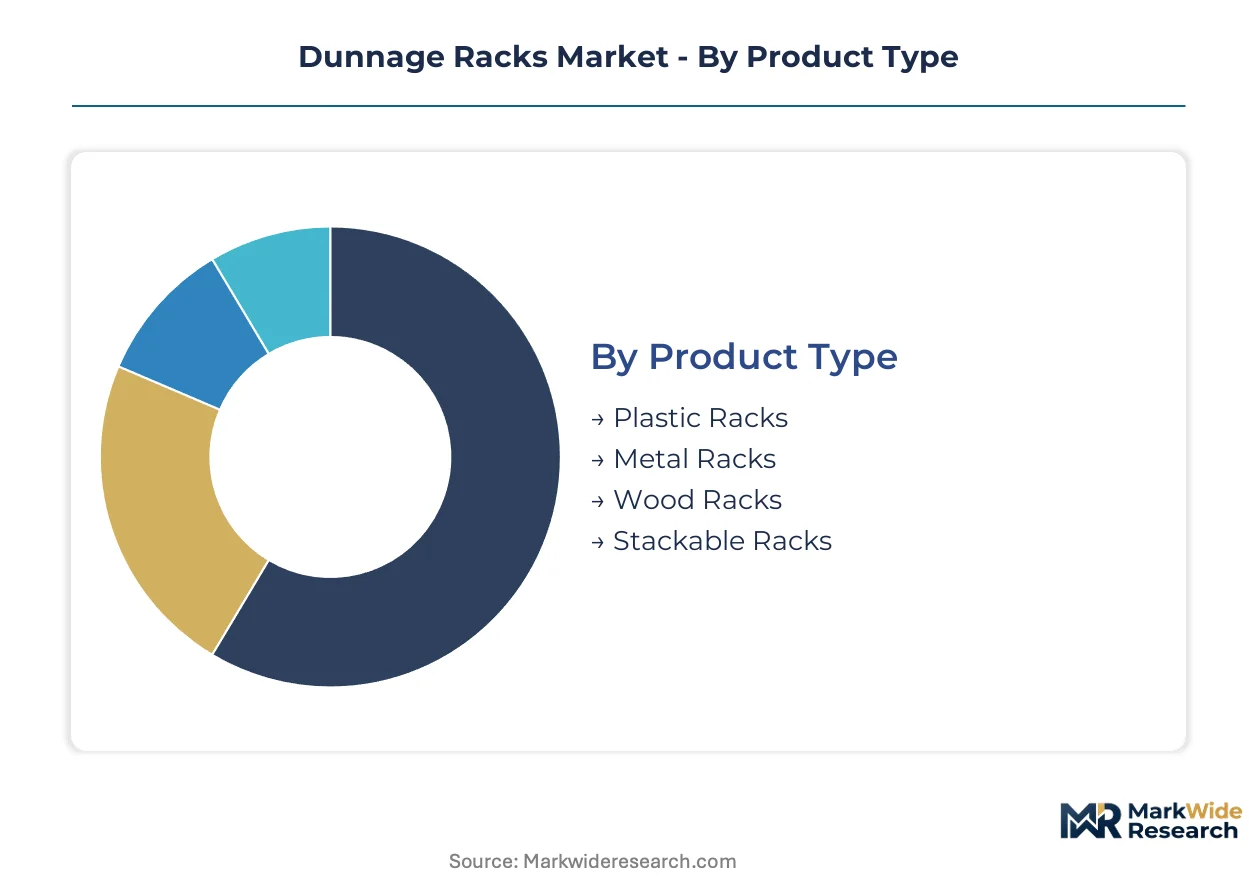
Dunnage rack specifications diverge sharply between integrated foodservice systems and standalone industrial deployments. Procurement patterns in each segment cluster reflect distinct compliance burdens, load requirements, and replacement cycles that reshape supplier economics.
Product Type:
Standalone installations dominate foodservice and pharmaceutical cold storage, while embedded rack systems integrate into automated warehousing and conveyor-fed distribution centers.
- Plastic Racks:High-density polyethylene and polymer composites resist moisture absorption and bacterial colonization in FDA-regulated environments. Demand concentrates in United States commercial kitchens and healthcare foodservice facilities where NSF/ANSI 2 certification gates procurement. Joint Commission sanitation audits accelerate specification of antimicrobial polymer formulations in hospital renovation cycles.
- Metal Racks:Aluminum extrusion and stainless steel fabrication deliver load ratings from 1,500 to 3,000 pounds for heavy-duty warehousing. United States protein processors and dairy operations specify corrosion-resistant alloys to extend equipment lifecycles in high-moisture processing zones.
- Wood Racks:Lower upfront cost sustains deployment in non-regulated warehousing segments with established reverse logistics networks.
- Stackable Racks:Modular configurations enable vertical space optimization in micro-fulfillment centers and dark store operations serving fresh grocery delivery.
Volume placements concentrate in metal racks; the faster expansion belongs to plastic racks.
Industry Vertical:
Cost tier stratification separates premium-validated specifications from commodity procurement, with regulatory intensity determining margin architecture across verticals.
- Food & Beverage:FDA food code alignment mandates elevated storage for perishables in commercial kitchens and cold storage facilities. State-level adoption of food safety provisions directly expands deployment in protein, dairy, and ready-to-eat meal manufacturing.
- Pharmaceuticals:Biologics distribution requires validated floor-clearance protocols and load-rated aluminum systems in temperature-controlled facilities. Premium specifications capture margins in cold-chain infrastructure where palletized temperature-sensitive products demand compliance documentation.
- Aerospace:Specialized handling requirements for precision components drive custom capacity configurations with non-marking surfaces.
- Automotive:Just-in-time parts distribution networks specify heavy-duty metal racks for sequenced component delivery to assembly plants.
Food & Beverage generates the highest unit volumes; Pharmaceuticals delivers the steepest expansion trajectory.
Capacity:
Application intensity determines specification tier, with pharmaceutical and aerospace verticals demanding engineered solutions while retail distribution accepts standard configurations.
- Standard Capacity:1,500-pound ratings serve general warehousing and retail backroom storage where palletized consumer goods require basic floor clearance. United States foodservice distributors specify these units for dry goods and packaged product storage.
- Heavy Duty:Reinforced aluminum and steel construction supports 3,000-pound loads in automotive parts distribution and protein processing facilities. OSHA load-safety mandates drive engineering specifications in industrial warehousing segments.
- High Capacity:Intermediate ratings bridge standard and heavy-duty applications in beverage distribution and wholesale grocery operations.
- Custom Capacity:Engineered solutions address pharmaceutical cold-chain validation requirements and aerospace component handling protocols.
Standard capacity dominates unit shipments; custom capacity commands the highest per-unit margins.
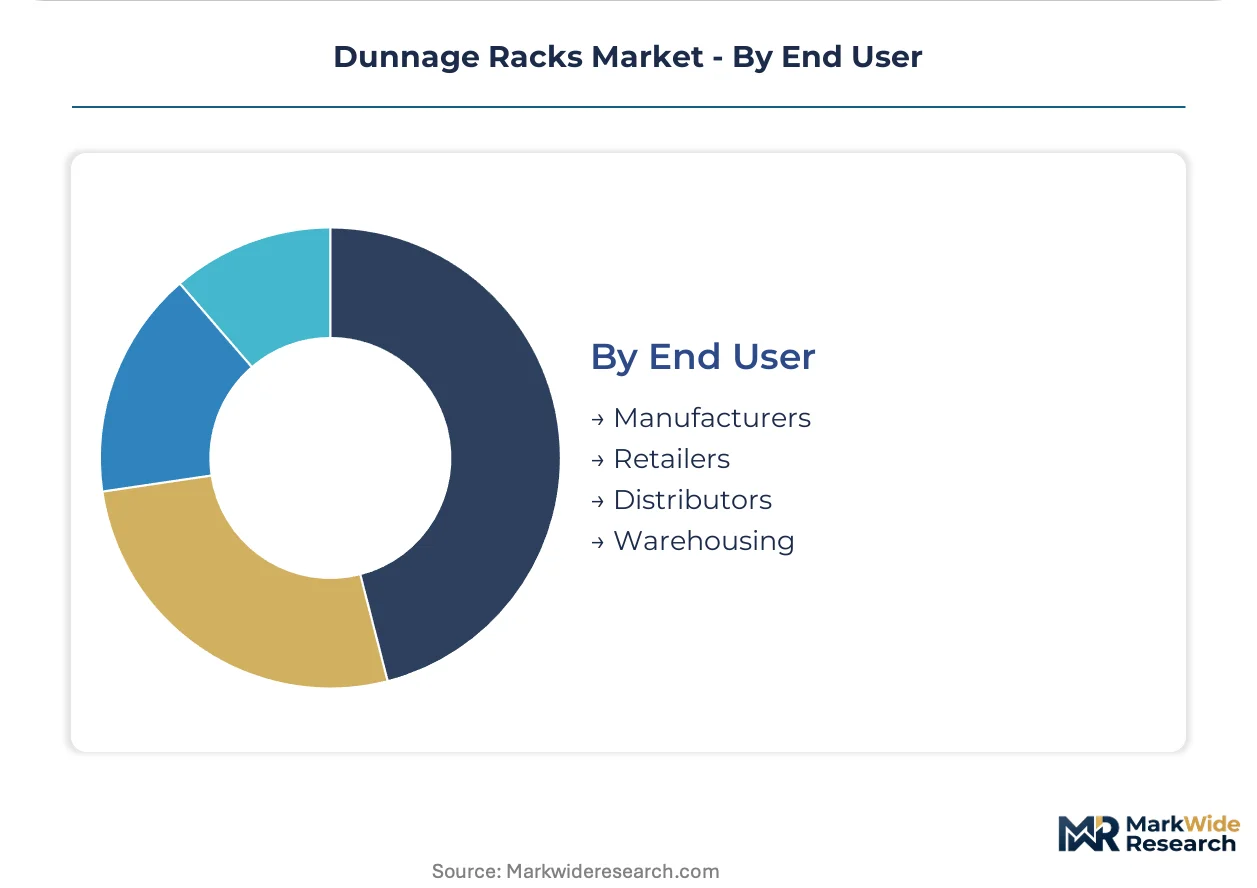
End User:
Customer type concentration shapes procurement authority, with centralized purchasing organizations displacing site-level decision-making in multi-unit systems.
- Manufacturers:Food and beverage producers drive adoption as FDA food safety codes tighten storage equipment requirements. Protein processors, dairy operations, and ready-to-eat meal manufacturers specify NSF-certified systems to meet sanitation benchmarks.
- Warehousing:Third-party logistics providers and dedicated distribution facilities balance durability demands against total cost of ownership in high-velocity operations. E-commerce fulfillment expansion drives demand for modular, sanitizable storage configurations.
- Distributors:Foodservice and industrial supply distributors face margin compression from NSF certification requirements while consolidating procurement authority among large-scale operators.
- Retailers:Grocery chains and mass merchandisers specify dunnage racks for backroom storage and micro-fulfillment center operations supporting delivery expansion.
Manufacturers account for the largest installed base; warehousing operations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial free zones and food processing corridors concentrate dunnage rack procurement in jurisdictions with stringent sanitation codes. Tax incentives for cold-chain infrastructure in designated economic zones accelerate specification of NSF-certified systems. Manufacturing clusters align with protein processing, dairy operations, and pharmaceutical distribution hubs.
United States
Foodservice distributors and contract food management companies drive specification volume. FDA food code adoption at state level mandates elevated storage for perishables in commercial kitchens. The Midwest protein processing corridor spanning Iowa, Nebraska, and Kansas deploys corrosion-resistant aluminum racks in high-moisture slaughter and fabrication facilities.
Germany
REACH regulation restrictions on metal finishing chemistries force coating line reconfiguration among fabricators. ECHA compliance timelines accelerate consolidation of finishing operations to achieve scale economies. The Baden-Württemberg food equipment manufacturing cluster migrates toward mechanical surface preparation and anodizing alternatives.
China
Fresh grocery delivery expansion drives demand for modular storage at micro-fulfillment centers. SAMR food safety enforcement tightens storage equipment requirements in cold-chain facilities. The Yangtze River Delta cold logistics zone around Shanghai specifies sanitizable polymer systems for e-commerce fulfillment operations.
India
FSSAI food safety code alignment expands deployment in dairy cooperatives and processed food manufacturing. PLI scheme incentives for food processing infrastructure accelerate capital equipment procurement. The Gujarat dairy belt and Maharashtra food processing zones adopt elevated storage platforms to meet sanitation audits.
Brazil
Protein export compliance with destination market sanitation standards elevates rack specifications in slaughter and packing plants. ANVISA food equipment guidelines shape procurement in pharmaceutical cold-chain facilities. The São Paulo state food processing corridor deploys NSF-equivalent systems to maintain access to United States and European export markets.
Dunnage Racks Market Competitive Landscape
United States producers anchor the premium-certified tier; European specialists hold compliance-adjacent positions in finishing and surface treatment. The vendor base organizes around three strategic archetypes: vertically integrated aluminum extruders with captive polymer fabrication, specialized NSF certification holders with healthcare foodservice focus, and regional metal fabricators competing on geographic proximity. Consolidation pressure concentrates among mid-scale operators facing NSF audit cost burdens. Capacity expansion and certification infrastructure investment represent the dominant competitive moves.
Within the vertically integrated tier, Metro anchors compliance leadership through in-house aluminum extrusion and polymer fabrication capabilities. Cambro Manufacturing occupies a position exemplifying specialized polymer formulation expertise for bacterial resistance. Eagle Group represents geographic dominance in North American foodservice distribution channels. These three entities collectively illustrate how competitive advantage reconfigures around certification infrastructure rather than pure manufacturing scale.
| Leading Market Players |
|---|
| Metro (InterMetro Industries Corporation) |
| New Age Industrial |
| Cambro Manufacturing |
| Eagle Group |
| Winholt Equipment |
| Advance Tabco |
| Channel Manufacturing |
| Nexel Industries |
| Quantum Storage Systems |
| Others |
Value Network & Pricing Analysis
Qualified aluminum TIG welders in the United States Midwest command premium wages that compress margins for custom heavy-duty configurations, widening the spread between NSF-certified premium tiers and standard commodity offerings. Labor-cost differentials between certified fabrication shops and regional metalworkers directly shape three-tier pricing stratification across foodservice, pharmaceutical, and industrial warehousing segments.
Pricing Analysis
Short lead-time premiums of 15-25% apply to antimicrobial polymer formulations with silver-ion or copper-additive technologies that poultry and ready-to-eat meal manufacturers specify for biofilm reduction. Pricing stratifies across premium, standard, and economy tiers based on NSF/ANSI 2 certification grade and volume scale, with spot inventory discounts available for non-certified aluminum extrusions. Cost compression in the standard tier stems from aluminum price volatility tied to energy-intensive smelting economics. Contract food management companies exhibit the lowest price sensitivity due to centralized procurement authority, while independent restaurant operators remain most responsive to upfront capital equipment costs.
Supply Chain Analysis
Single-source vulnerability sits with FDA-compliant high-density polyethylene resin production that concentrates among specialized compounders in the United States and Germany. Raw material dependencies include primary aluminum from domestic smelters, corrosion-resistant alloy formulations from European suppliers, and antimicrobial polymer additives from Japanese specialty chemical producers. Supply chain risk centers on REACH regulation restrictions forcing European fabricators toward mechanical surface preparation and anodizing alternatives. Distribution runs through foodservice equipment distributors and group purchasing organizations that consolidate specification authority across multi-unit restaurant and healthcare systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints from NSF certification timelines extending product launch schedules by 8-14 months prop pricing power for incumbent certificate holders. This bottleneck limits rapid capacity response to demand surges in pharmaceutical cold-chain and healthcare foodservice verticals.
For Market Incumbents: Anchor compliance leadership through captive aluminum extrusion and polymer fabrication capabilities that Metro has demonstrated. Invest in antimicrobial formulation R&D to defend against polymer specialists encroaching on food-contact applications. Expand finishing capacity in corrosion-resistant alloys to capture protein processor replacement cycles in the Midwest processing corridor. For New Entrants and Emerging Players: Foodservice equipment distributors represent the most accessible channel partner type for bypassing entrenched GPO relationships. Target micro-fulfillment center operators serving fresh grocery delivery expansion with modular, sanitizable stackable configurations. Pursue white-label manufacturing arrangements with established distributors lacking in-house fabrication capabilities. For Investors and Strategic Acquirers: The window for entry favors vertically integrated aluminum extruders with dormant polymer fabrication assets. Mid-scale regional fabricators facing NSF audit cost burdens present consolidation targets with immediate certification infrastructure value. Watch for aluminum price stabilization signals as inflection indicators for margin recovery in the metal rack segment.| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certification Infrastructure Investment | Third-party testing and facility audit capabilities gate procurement access in United States foodservice and healthcare verticals. |
| Antimicrobial Polymer Formulation Development | Silver-ion and copper-additive technologies command 15-25% price premiums in poultry and ready-to-eat meal processing. |
| Aluminum Alloy Corrosion Resistance Advancement | Extended equipment lifecycles in high-moisture protein and dairy operations reduce total cost of ownership. |
| Group Purchasing Organization Contracting | Centralized procurement through three United States collectives controls specification authority for over 40% of institutional foodservice locations. |
| Pharmaceutical Cold-Chain Validation Capability | Load-rated aluminum systems with compliance documentation capture premium margins in biologics distribution infrastructure. |
Research Methodology
Independent corroboration across primary interviews with foodservice equipment distributors, NSF certification auditors, aluminum extrusion plant managers, and polymer compounder technical directors underwrites the qualitative findings. Secondary validation draws from FDA food code adoption tracking, NSF/ANSI 2 standard revision documentation, SEC filings of publicly traded food equipment manufacturers, and United States customs data on aluminum extrusion imports. Bottom-up demand modeling from end-use verticals triangulates against top-down supply capacity assessments across certified fabrication facilities.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, industry vertical, capacity tier, and end-user category, with additional granularity on NSF certification status and antimicrobial surface treatment adoption. CAGRs derive from regression analysis of historical shipment data against regulatory adoption curves and capital expenditure cycles in food processing and pharmaceutical cold-chain infrastructure. Forecast inputs incorporate aluminum price futures curves and Joint Commission audit frequency trends in healthcare facility renovation.
Caveats apply where aluminum smelting energy cost shocks, REACH regulation expansion beyond European borders, or polymer supply disruptions from specialized compounders could materially shift the outlook. Forecasts reflect assumptions about state-level FDA food code adoption timing and group purchasing organization consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
MENA Industrial Packaging Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Corrugated Automotive Packaging Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Bulk Packaging Market
Industrial Packaging
Industrial Bulk Packaging Market
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Industrial Pails Market
Industrial Packaging
Cone Bottom Tank Market
Industrial Packaging
Insulated Bin Market
Industrial Packaging
Fiber Drums Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Industrial Chemical Packaging Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Dunnage Trays Market
Industrial Packaging
Overpack Drum Market