
 Bulk Packaging Market | 2026-2036
Bulk Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Packaging Market Analysis
Reusable container tracking through embedded RFID and IoT sensors is fragmenting traditional asset-light procurement models in bulk packaging. Greif leverages its North American reconditioning network to sustain circular service revenue. Mauser Packaging Solutions anchors European industrial chemical demand through its IBC rental and pooling infrastructure. Schütz GmbH & Co. KGaA differentiates via proprietary composite intermediate bulk container designs that compete on tare weight and drop-test performance.
Bulk packaging denotes engineered containers—typically exceeding 450 liters in nominal capacity—fabricated from high-density polyethylene, corrugated triple-wall board, or cold-rolled steel, designed for single-point filling and discharge of granular, liquid, or semi-viscous commodities. These systems reduce handling cost per unit volume and enable forklift or crane-mediated transfer between production, storage, and transport nodes. Flexible bags in woven polypropylene lead volume in agricultural and mineral exports, while pallet containers command premium positioning in pharmaceutical and specialty chemical logistics where clean-in-place protocols apply. Metal drums retain defensive share in solvent and lubricant distribution, though substitution by composite alternatives accelerates in regions with stringent empty-container return economics.
The EPA regulates hazardous material container integrity under 49 CFR standards, while the EU Packaging and Packaging Waste Directive mandates extended producer responsibility schemes that reshape material recovery obligations for plastic and fiber-based bulk formats. China's GB standards for dangerous goods packaging, administered by SAMR, enforce testing protocols that determine market access for imported container systems. Stakeholders must monitor diverging recyclability certification requirements across these jurisdictions when configuring regional manufacturing and service footprints.
Market Dynamics
Embedded sensor networks are digitizing asset tracking across reusable intermediate bulk container fleets, forcing converters to choose between capital-intensive pooling infrastructure and permanent displacement by third-party logistics operators.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates accelerate mono-material intermediate bulk container adoption among German chemical manufacturers seeking simplified end-of-life compliance.
- Composite material substitution:High-density polyethylene and polypropylene composites displace steel drums in solvent logistics, reducing tare weight and return freight costs for hazardous material shippers.
- Coastal manufacturing concentration:Export-oriented food processing clusters in China's Jiangsu and Zhejiang provinces drive demand for high-throughput flexible intermediate bulk container handling systems.
Market Restraints
- Resin price volatility:Polypropylene and polyethylene input costs fluctuate with naphtha and natural gas liquid pricing, compressing converter margins on fixed-price annual contracts.
- Steel drum supplier concentration:Cold-rolled steel drum fabrication concentrates among legacy metal packaging specialists with limited geographic redundancy in North American production.
- Cross-border certification friction:Divergent testing protocols under EPA 49 CFR, EU ADR, and China's GB standards create redundant qualification costs for container system exporters.
Strategic Opportunities
- Pharmaceutical clean-in-place protocols:Specialty chemical and active pharmaceutical ingredient logistics create premium positioning for stainless steel intermediate bulk containers with validated washing documentation.
- RFID-IoT convergence:Embedded tracking hardware combined with cloud-based fleet management software enables outcome-based container availability guarantees for chemical distributors.
- India's agrochemical expansion:Fertilizer and pesticide formulation growth under the PLI scheme for chemicals generates demand for woven polypropylene flexible intermediate bulk containers in Gujarat and Maharashtra.
Industry Challenges
- Welding and composite fabrication skills gap:Intermediate bulk container reconditioning facilities face recruitment pressure for certified pressure vessel technicians and automated blow-molding operators.
- Legacy enterprise resource planning integration:Pooling operators struggle to synchronize RFID-enabled container tracking data with customer warehouse management systems built on decade-old software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Packaging Market |
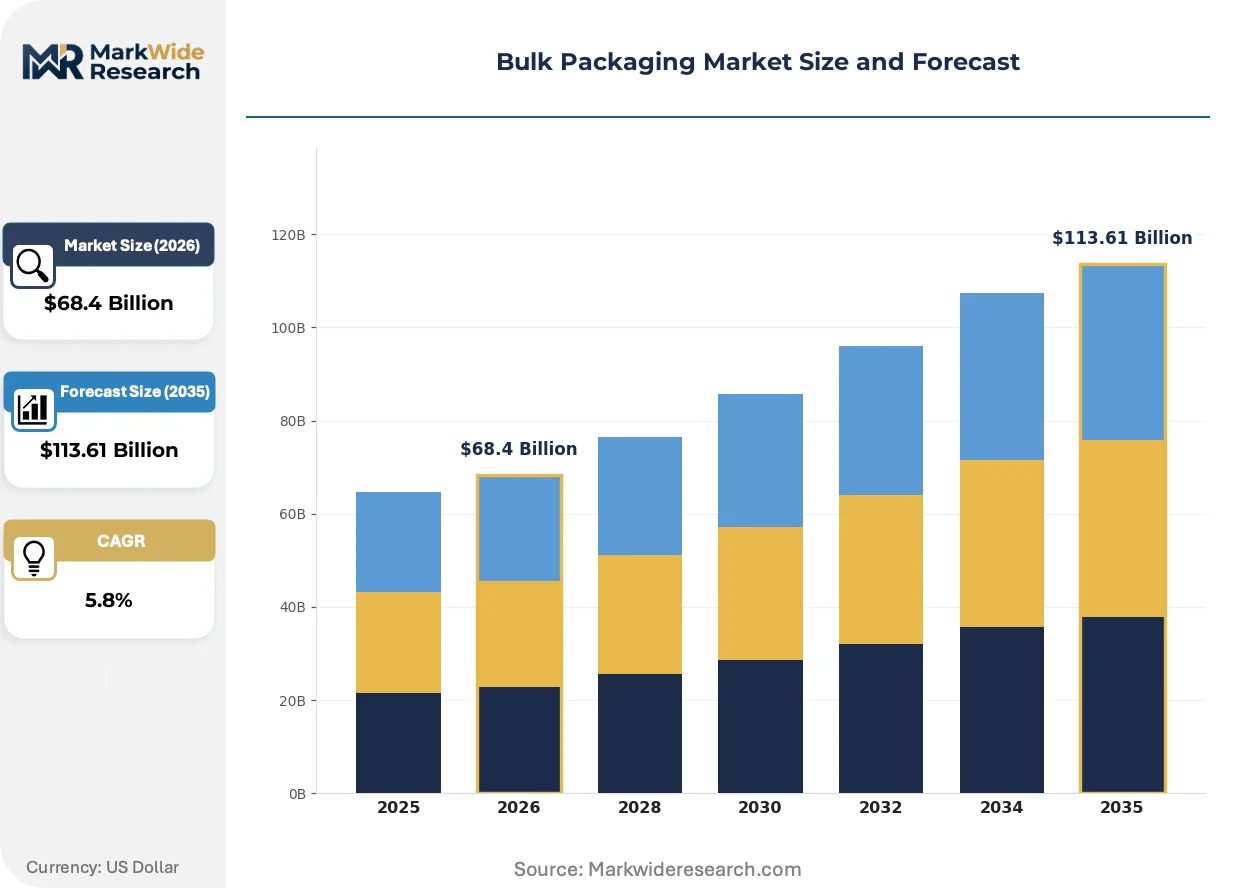
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Bags, Bulk Boxes, Pallet Containers, Drums Material: Plastic, Wood, Metal, Cardboard End User: Food & Beverage, Chemicals, Pharmaceuticals, Construction Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Mauser Packaging Solutions, Smurfit Kappa Group, Greif, Time Technoplast, DS Smith, Berry Global Group, Mondi, Conitex Sonoco, Schütz GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Packaging Market Emerging Trajectories
Sensor-enabled circular logistics, regulatory harmonization pressures, and procurement model fragmentation are compressing traditional asset ownership structures across bulk packaging value chains.
RFID and IoT sensor integration is digitizing container lifecycle management from filling through reconditioning. Chemical manufacturers in the Rhine-Ruhr industrial corridor now mandate real-time location tracking for hazardous material intermediate bulk containers. This visibility infrastructure enables dynamic fleet optimization and accelerates third-party pooling service penetration against captive container ownership.
REACH substance restrictions and the EU Green Deal's packaging recyclability targets are forcing material substitutions in multi-layer barrier constructions. Converters face reformulation costs to eliminate fluorinated compounds from chemical-resistant intermediate bulk container liners. German and Dutch packaging specialists respond with mono-material polyethylene designs that sacrifice some chemical compatibility for simplified mechanical recycling streams.
Asset-light procurement via rental and pooling contracts displaces direct purchase in industrial chemical distribution. Mid-sized specialty chemical distributors in the US Gulf Coast region now specify availability-based service agreements rather than capital expenditure for container fleets. This shift concentrates bargaining power with logistics operators possessing multi-site reconditioning networks and regulatory compliance documentation systems.
Bulk Packaging Market Segmentation
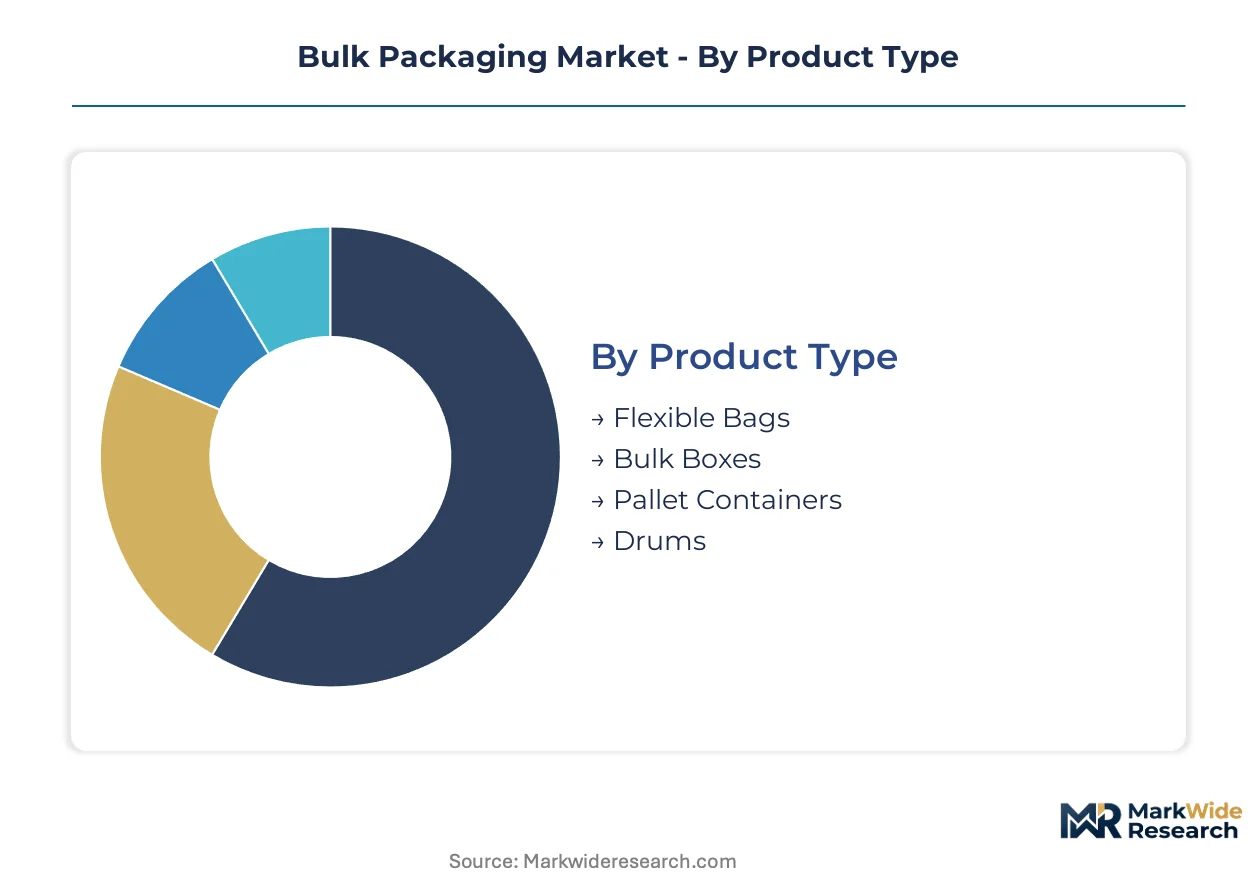
Bulk packaging segmentation reveals divergent asset turnover economics across container formats. Material selection and end-use compliance requirements create distinct margin profiles that reshape converter investment priorities.
Product Type:
Flexible bags turn inventory fastest with single-use agricultural applications, while pallet containers cycle slowly through multi-year pharmaceutical service contracts.
- Flexible Bags:Woven polypropylene or polyethylene constructions handle dry bulk commodities across mineral and agricultural supply chains. China's Jiangsu and Zhejiang export processing clusters drive throughput for woven polypropylene bulk bags handling fertilizer and feed ingredients, with demand tied to containerized export volumes through Shanghai and Ningbo ports.
- Pallet Containers:Rigid intermediate bulk container systems combine HDPE or steel vessels with integrated pallet bases for forklift handling. German chemical manufacturers along the Rhine-Ruhr corridor specify these for hazardous material transport under EU ADR regulations, with stainless steel variants commanding premium positioning for pharmaceutical clean-in-place protocols.
- Drums:Cold-rolled steel or composite constructions serve solvent and lubricant distribution networks.
- Bulk Boxes:Corrugated triple-wall or solid fiberboard designs handle dry goods with lower unit value.
Flexible bags anchor the volume base while pallet containers gain share at the steepest rate.
Material:
Cost tier stratification separates commodity resin grades from engineered composites and corrosion-resistant metals.
- Plastic:High-density polyethylene and polypropylene dominate through blow-molded intermediate bulk containers and injection-molded pallet bases. US Gulf Coast petrochemical integration supplies feedstock for domestic converter networks, though resin price volatility tied to natural gas liquid spreads compresses margins on annual supply contracts.
- Metal:Cold-rolled steel drums retain defensive positioning in flammable solvent logistics where UN certification requirements persist. European steel drum fabrication concentrates in Germany and Poland with limited geographic redundancy, creating supply vulnerability during raw material allocation periods.
- Cardboard:Recycled fiber-based bulk boxes serve dry goods with lower durability requirements.
- Wood:Pallet and crate components provide structural support in multi-material container systems.
Plastic captures the highest shipment volumes while metal holds pricing power in regulated hazardous material applications.
End User:
Application-driven specification intensity ranges from basic food-grade compliance to validated pharmaceutical documentation.
- Chemicals:Industrial chemical distribution demands UN-certified intermediate bulk containers with pressure relief and stacking load ratings. German manufacturers expanding intermediate bulk container adoption for hazardous material transport face tightening EU Packaging and Packaging Waste Regulation recyclability mandates that favor mono-material polyethylene designs over multi-layer barrier constructions.
- Food & Beverage:Bulk ingredient handling requires FDA or EFSA compliance for direct-contact applications. China's coastal food processing clusters in Shandong and Guangdong provinces import aseptic flexible intermediate bulk container systems for fruit concentrate and dairy ingredient exports.
- Pharmaceuticals:Active pharmaceutical ingredient logistics require stainless steel containers with validated washing documentation and batch traceability.
- Construction:Cement and mineral additive handling drives demand for woven polypropylene bulk bags with UV stabilization.
Food and beverage provides the broadest volume foundation while pharmaceuticals delivers the steepest margin expansion trajectory.
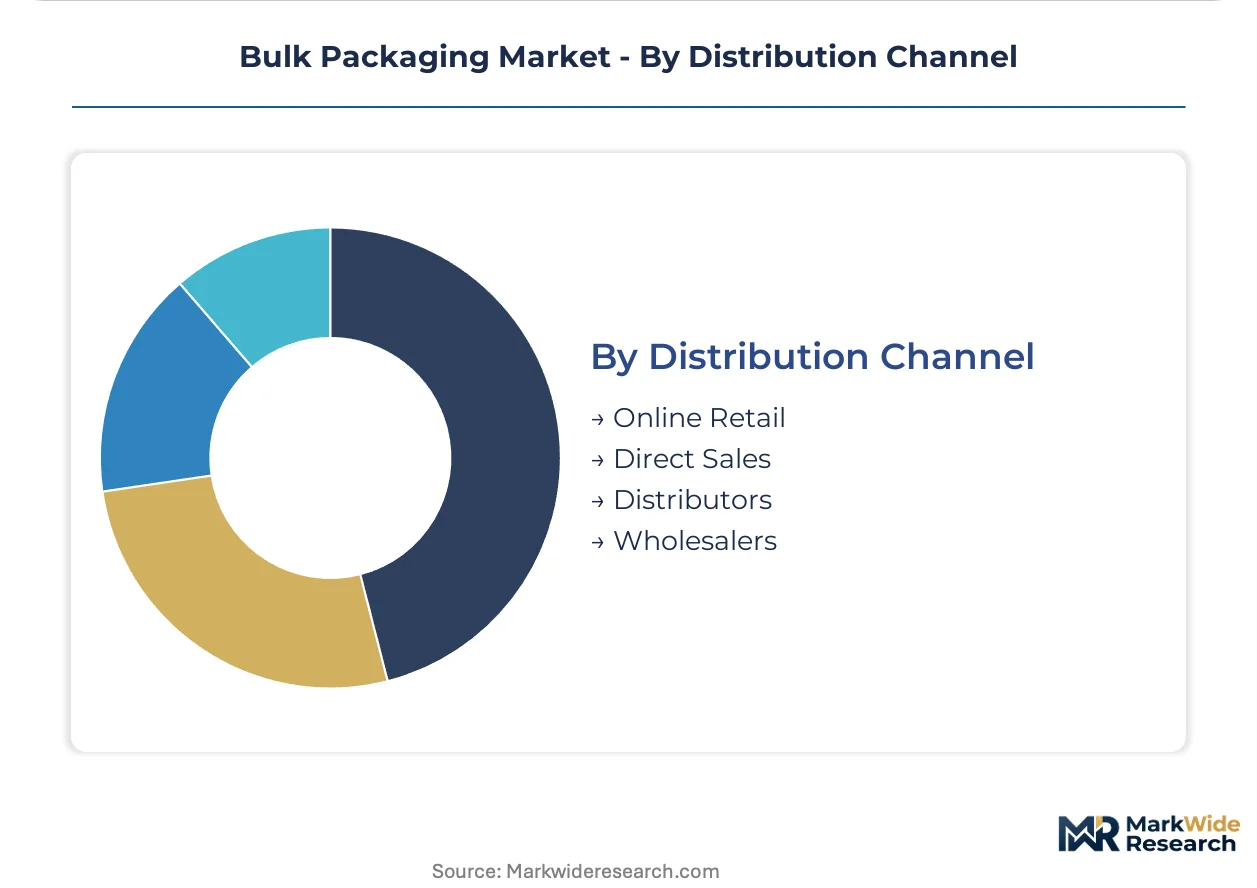
Distribution Channel:
Customer scale and procurement sophistication determine channel selection between direct converter relationships and intermediary stocking.
- Distributors:Industrial packaging specialists maintain regional inventory positions for mid-sized chemical and food processors. US Midwest and Southeast distributor networks stock intermediate bulk container and drum assortments with same-day fulfillment capabilities for manufacturing plants in Ohio, Indiana, and Georgia.
- Direct Sales:Large-volume chemical manufacturers negotiate annual container availability contracts directly with converters. German chemical majors along the Rhine-Main industrial corridor source intermediate bulk container fleets through direct procurement with embedded RFID tracking mandates.
- Online Retail:E-procurement platforms serve small-lot buyers with standardized catalog offerings.
- Wholesalers:Bulk aggregators handle commodity-grade flexible bag and corrugated box volumes.
Distributors dominate transaction frequency while direct sales captures the largest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial chemical distributors and food processors concentrate procurement authority across five national markets, each shaped by distinct regulatory frameworks and manufacturing cluster configurations.
United States
Petrochemical manufacturers along the Gulf Coast drive demand for intermediate bulk container fleets handling solvents and lubricants. EPA 49 CFR standards govern hazardous material container integrity testing, creating compliance barriers for imported systems. Houston and Baton Rouge processing clusters source composite IBC alternatives to reduce return freight costs on empty container circuits.
Germany
Rhine-Ruhr chemical majors specify RFID-tracked intermediate bulk containers for hazardous material transport under EU ADR protocols. The EU Packaging and Packaging Waste Regulation accelerates mono-material polyethylene adoption among converters seeking simplified recyclability compliance. BASF and Bayer supplier networks in Ludwigshafen and Leverkusen mandate real-time fleet visibility for hazardous cargo.
China
Coastal manufacturing provinces Jiangsu and Zhejiang import aseptic flexible intermediate bulk container systems for fruit concentrate and dairy ingredient exports. SAMR-administered GB standards for dangerous goods packaging enforce testing protocols that determine market access for foreign container suppliers. Shanghai and Ningbo port throughput shapes regional demand for high-volume woven polypropylene bulk bag handling systems.
India
Fertilizer and pesticide formulation growth under the PLI scheme for chemicals generates demand for woven polypropylene flexible intermediate bulk containers. FSSAI compliance requirements govern food-grade bulk packaging for agricultural commodity exports. Gujarat and Maharashtra agrochemical clusters in Vadodara and Pune source UV-stabilized bulk bags for domestic distribution networks.
Japan
Pharmaceutical clean-in-place protocols create premium positioning for stainless steel intermediate bulk containers with validated washing documentation. METI industrial standards coordinate with international UN certification requirements for chemical logistics. Osaka and Nagoya pharmaceutical manufacturing districts specify batch-traceable container systems for active pharmaceutical ingredient handling.
Bulk Packaging Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Asset-heavy pooling operators with multi-site reconditioning networks command procurement leverage against mid-sized converters dependent on direct sales relationships. Three archetypes dominate: integrated pooling service providers, composite material specialists, and fiber-based bulk box fabricators. Competitive moves concentrate on geographic expansion of reconditioning footprints and technology licensing for embedded tracking systems.
Within the integrated pooling tier, Mauser Packaging Solutions and Greif exemplify channel-control strategies through captive reconditioning infrastructure. Schütz GmbH & Co. KGaA occupies a position among composite material specialists emphasizing proprietary vessel designs. Smurfit Kappa Group and DS Smith represent fiber-based bulk box fabricators serving dry goods logistics with corrugated triple-wall constructions. These three archetypes anchor competitive positioning across asset-light procurement transitions and regulatory compliance service bundling.
| Leading Market Players |
|---|
| Mauser Packaging Solutions |
| Smurfit Kappa Group |
| Greif |
| Time Technoplast |
| DS Smith |
| Berry Global Group |
| Mondi |
| Conitex Sonoco |
| Schütz GmbH & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
North American resin production concentration along the US Gulf Coast feeds directly into converter margin pools for blow-molded intermediate bulk containers. HDPE and polypropylene feedstock pricing indexed to natural gas liquid spreads determines cost-plus contract structures for chemical distributors from Houston to Baton Rouge.
Pricing Analysis
Cost-plus contracts with monthly resin indexation dominate bulk packaging procurement between converters and chemical distributors. Three-tier pricing structure across UN-certified premium, food-grade standard, and agricultural economy levels reflects certification burden and wash-documentation requirements. Cost compression in standard-grade composite IBCs is intensifying because German chemical majors are consolidating purchase volumes under framework agreements. Agricultural buyers in India's Gujarat belt exhibit highest price sensitivity, while pharmaceutical clean-in-place protocols insulate stainless steel container pricing.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for woven polypropylene flexible intermediate bulk container sourcing. Manufacturing concentrates in China, Germany, and the United States for rigid IBC vessel fabrication, with blow-molding equipment dependencies resting on Italian and German machinery suppliers. Single-source vulnerability in cold-rolled steel drum fabrication creates supply continuity exposure during raw material allocation periods. Distribution runs through regional industrial packaging specialists maintaining same-day fulfillment positions in Ohio, Indiana, and Georgia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bulk packaging demand tracks industrial chemical production cycles, with Rhine-Ruhr chemical output recovery signaling the current upswing phase. Container utilization rates at major pooling operators provide the confirming indicator.
For Market Incumbents: Pre-empt composite material substitution by accelerating proprietary polyethylene formulation R&D before REACH restrictions eliminate fluorinated barrier compounds. Expand reconditioning footprint into India's Gujarat and Maharashtra clusters to capture PLI-driven agrochemical demand. Backward integration into HDPE recycling streams secures feedstock cost advantage as EU Packaging and Packaging Waste Regulation tightens. For New Entrants and Emerging Players: Pursue pharmaceutical stainless steel IBC segments where validated washing documentation creates incumbent switching costs. India's FSSAI-compliant food-grade bulk bag market offers the most penetrable white space among major economies. Lead with RFID-IoT tracking bundling to differentiate against asset-light distributors lacking fleet visibility infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward pooling operators with multi-site reconditioning networks and embedded compliance documentation systems. Long-term viability over the next decade hinges on circular service revenue capture versus transactional container sales. Watch chemical distributor procurement contract durations as the inflection signal—shortening terms indicate accelerating rental-pooling transition.| Strategic Initiative | Industry Significance |
|---|---|
| Reconditioning Network Expansion | Captures circular service revenue as German chemical majors shift from ownership to rental. |
| RFID-IoT Fleet Tracking Deployment | Enables outcome-based availability guarantees demanded by Rhine-Ruhr hazardous material shippers. |
| Mono-Material Polyethylene Reformulation | Secures EU Packaging and Packaging Waste Regulation recyclability compliance for IBC liners. |
| Stainless Steel CIP Protocol Certification | Unlocks pharmaceutical API logistics premiums in Osaka and Nagoya manufacturing districts. |
| India PLI Scheme Localization | Positions for fertilizer and pesticide formulation growth in Gujarat and Maharashtra clusters. |
Methodological Framework
Operator-level perspectives from plant managers at IBC reconditioning facilities, procurement leads at German chemical distributors, technical R&D directors at composite material specialists, and channel partners in US Midwest industrial packaging networks anchored the qualitative base. Primary interview findings triangulated against secondary sources including customs and trade flow data, ACC and Cefic industry reports, SEC 10-K filings from listed packaging converters, and SAMR-administered GB standard documentation. Bottom-up volume modeling across container formats reconciled with top-down chemical production and agricultural commodity trade projections.
Scenario-bracketing around resin price volatility and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material type, product format, end-use industry, and regional production hub cluster. CAGRs derived from curve-fitting historical shipment data against industrial chemical output indices and export trade volume trends. Forecast inputs incorporated REACH substance restriction phase-out schedules and India's PLI scheme chemical sector allocation patterns.
Sensitivities concentrate around polypropylene feedstock price spikes, EU recyclability mandate enforcement timing, and China GB standard testing protocol changes for imported container systems. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Global Dunnage Packaging Market
Industrial Packaging
Rigid IBC Market
Industrial Packaging
Slip Sheets Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Asia-Pacific Warehouse Drums and Barrel Market
Industrial Packaging
Dunnage Trays Market
Industrial Packaging
Industrial Bulk Packaging Market
Industrial Packaging
Industrial Filling Machine Market
Industrial Packaging
Nestable Drums Market
Industrial Packaging
Transport Racks Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Industrial Packaging Market
Industrial Packaging
Middle East and Africa Octabin Market
Industrial Packaging
Corrugated Octabins Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Overpack Drum Market