
 Industrial Bulk Packaging Market | 2026-2036
Industrial Bulk Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Bulk Packaging Market Analysis
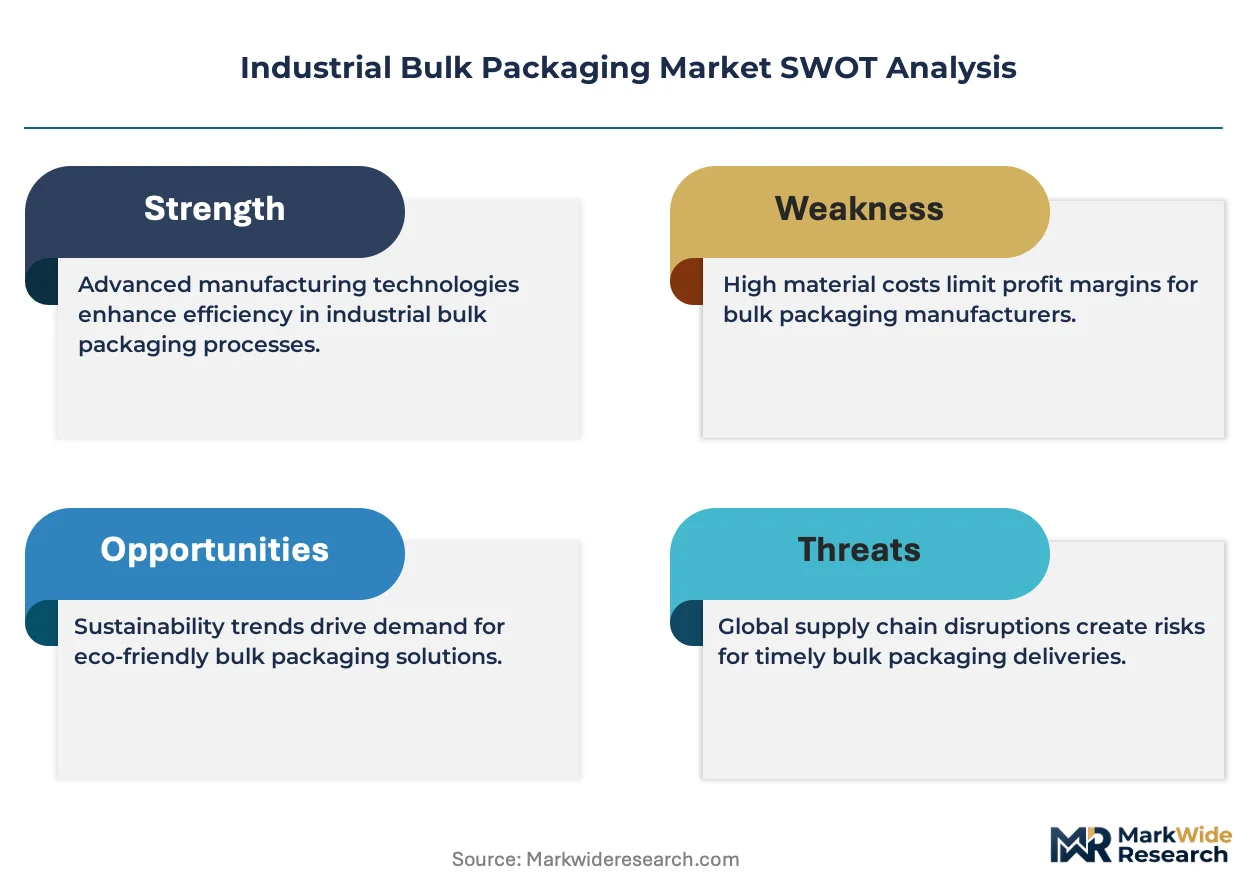
The gap between premium multi-trip IBC systems and single-use flexible bulk bags is restructuring procurement hierarchies across chemical and food processing supply chains. Greif Inc. dominates steel drum manufacturing through captive metal sourcing and North American plant density. SCHÜTZ GmbH & Co. KGaA anchors European IBC refurbishment networks with closed-loop pooling services. Mauser Packaging Solutions extends composite container R&D into corrosion-resistant barrier technologies for agrochemical clients.
Industrial bulk packaging encompasses large-format containment systems—typically 500 liters to 3,000 liters in rated capacity—engineered for granular, powder, liquid, or semi-viscous material transport between manufacturing sites and downstream processors. These systems employ welded steel, blow-molded polyethylene, woven polypropylene, or multi-ply corrugated constructions to withstand forklift handling, stacking loads, and intermodal transfer stresses. Flexible bulk bags capture volume leadership in agricultural and mineral commodity flows where cost-per-trip metrics override durability requirements. Rigid IBCs command margin concentration in pharmaceutical and specialty chemical segments where UN-certified hazardous material compliance commands pricing premiums. Metal drums retain defensive positions in solvent and lubricant distribution despite plastic substitution in water-based formulations.
US DOT hazmat regulations, EU REACH chemical authorization protocols, and FDA food contact substance notifications collectively determine material eligibility, labeling mandates, and reuse certification cycles across major trade corridors. EPA container containment requirements for agricultural pesticides and OSHA workplace lifting standards further constrain design parameters for domestic manufacturers. Stakeholders must track evolving Extended Producer Responsibility frameworks in European member states and California's pending plastic packaging fee structures to anticipate capital allocation timing for reusable fleet investments versus disposable format commitments.
Market Dynamics
Reusable IBC pooling networks are compressing total cost of ownership for chemical shippers while ECHA REACH substance authorization protocols force material traceability investments across European supply chains.
Growth Catalysts
- EU REACH compliance mandates:Chemical manufacturers in Germany and France must document container material origins and reuse cycles, accelerating certified IBC fleet expansion.
- US Gulf Coast petrochemical exports:Export-oriented bulk packaging demand concentrates along the Texas-Louisiana corridor where intermodal containerization requirements intensify.
- Woven polypropylene barrier films:Agricultural commodity processors adopt multi-ply flexible bulk bags with oxygen-scavenging liners for extended shelf-life transport.
Market Restraints
- Steel price volatility:Drum manufacturers face margin compression from scrap metal cost swings tied to Chinese construction demand cycles.
- Single-use plastic substitution limits:Solvent and lubricant formulations requiring UN-certified hazardous material containment resist polyethylene drum conversion.
- California plastic packaging fee uncertainty:Pending state-level Extended Producer Responsibility legislation delays capital allocation decisions for disposable format investments.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO-certified IBC refurbishment hubs can capture growing API bulk shipment volumes from Maharashtra and Gujarat manufacturing clusters.
- RFID-integrated fleet tracking:Converging sensor hardware and cloud logistics platforms enable outcome-based pooling contracts with real-time container location verification.
- Brazilian agrochemical distribution:ANVISA registration requirements for pesticide containers create demand for corrosion-resistant composite IBC systems in Mato Grosso soybean corridors.
Industry Challenges
- UN certification timeline compression:Hazardous material container testing protocols require 12-18 month approval cycles that lag behind customer product launch schedules.
- Welding technician scarcity:Steel drum production lines in Ohio and Pennsylvania face recruitment gaps for certified pressure-vessel fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Bulk Packaging Market |
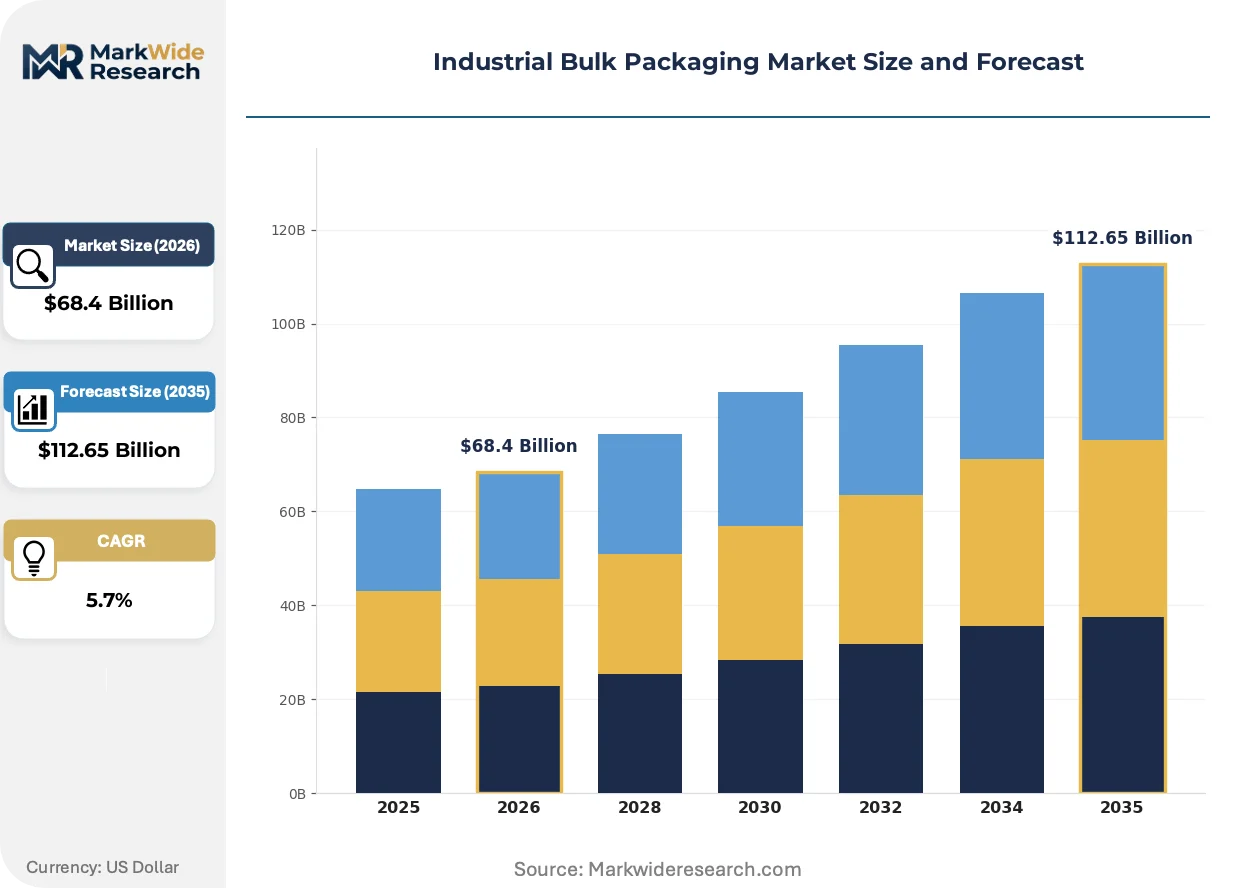
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $112.65 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Bulk Bags, Rigid Containers, IBCs, Drums Material: Plastic, Metal, Paper, Composite End Use Industry: Food & Beverage, Chemicals, Pharmaceuticals, Construction Distribution Channel: Direct Sales, Retail, E-commerce, Distributors |
| Companies Covered | Mauser Packaging Solutions, Greif Inc., Berry Global, SCHÜTZ GmbH & Co. KGaA, Mondi Group, DS Smith, International Paper, Sealed Air, Amcor Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Bulk Packaging Market Emerging Trajectories
Active material science breakthroughs are collapsing the performance gap between single-use flexible formats and multi-trip rigid systems across temperature-sensitive chemical shipments.
Barrier-coated polyethylene terephthalate is integrating oxygen and moisture scavenging layers directly into blow-molded IBC inner bottles. Specialty chemical producers in Basel and Ludwigshafen adopt these vessels for pharmaceutical intermediate transport. The technology is integrating corrosion resistance previously exclusive to stainless steel into commodity plastic price bands.
ECHA's SCIP database requirements for Substances of Very High Concern are forcing container manufacturers to disaggregate supply chain material declarations. Drum and IBC producers must now tag individual components with SVHC concentration data. European chemical distributors are responding by consolidating procurement around suppliers with pre-validated material passports.
Third-party logistics providers are unbundling container fleet management from traditional freight forwarding contracts. Agrochemical buyers in Iowa and Illinois now lease IBC pools separately from transport services, paying per-trip fees tracked through telematics. This model is most visible in North American crop protection distribution where seasonal demand spikes render owned-fleet economics unfavorable.
Industrial Bulk Packaging Market Segmentation
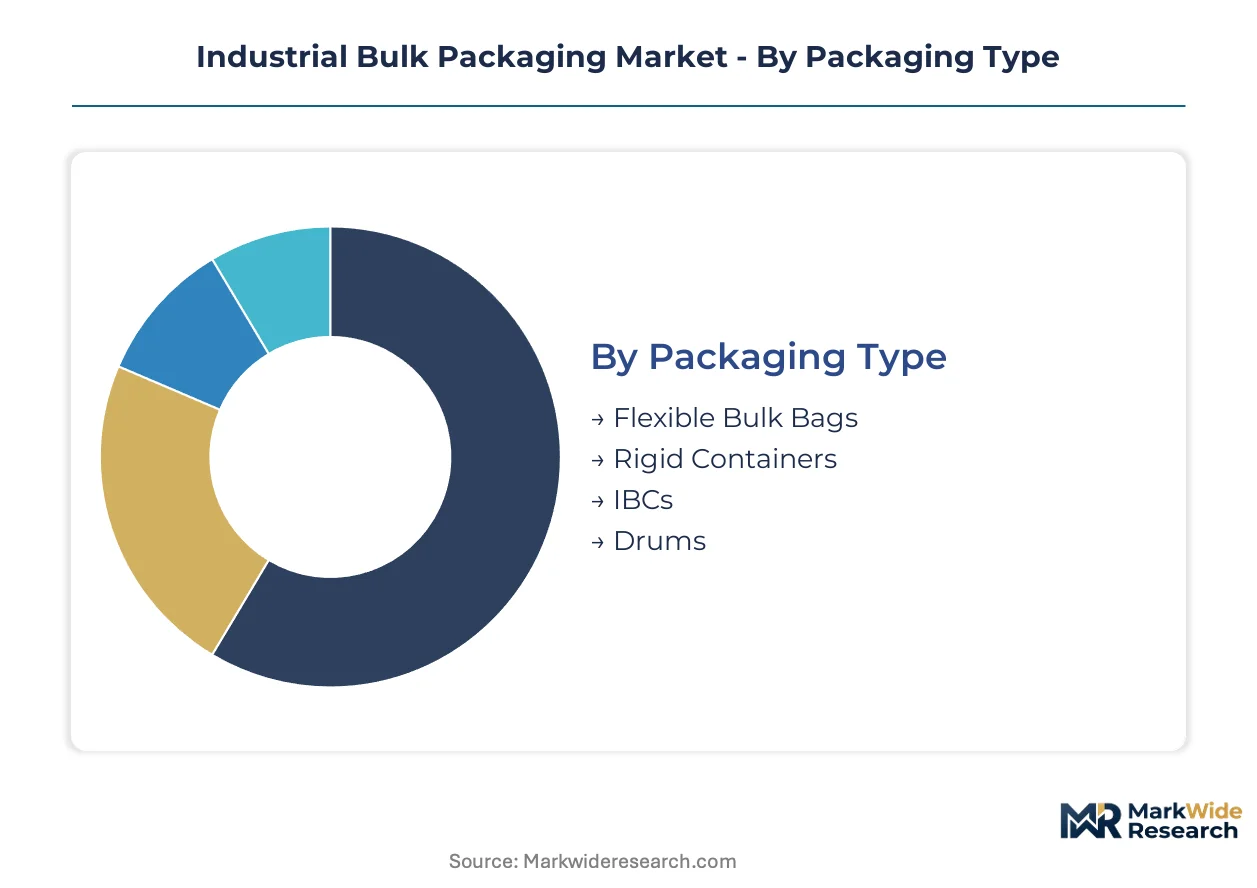
Industrial bulk packaging procurement decisions hinge on certification requirements, total trip economics, and material compatibility with regulated substances. Segmentation reveals where UN-certified hazardous material containment commands pricing premiums versus commodity formats competing on cost-per-trip metrics.
Packaging Type:
UN certification burdens fall heaviest on rigid formats for hazardous chemicals, while food-grade flexible systems face FDA food contact substance notification requirements.
- Flexible Bulk Bags:Woven polypropylene constructions with multi-ply liners dominate agricultural commodity flows. Demand concentrates in US Midwest grain elevators and Brazilian soybean export corridors where oxygen-scavenging barrier films extend shelf-life for extended intermodal journeys.
- IBCs:Blow-molded polyethylene or stainless steel intermediate bulk containers require 12-18 month UN testing protocols for hazardous material authorization. German chemical manufacturers under ECHA REACH compliance are expanding certified reusable IBC fleets with SCIP database traceability for SVHC substances.
- Drums:Welded steel or tight-head polyethylene containers retain defensive positions in solvent distribution despite plastic substitution in water-based formulations.
- Rigid Containers:Corrugated bulk bins and composite totes serve non-hazardous dry goods where forklift stacking strength outweighs moisture protection requirements.
Flexible bulk bags sit at the top of the volume ranking, with IBCs climbing the fastest as REACH compliance accelerates reusable fleet adoption.
Material:
Cost tiers separate commodity plastics from corrosion-resistant metals and engineered composites with barrier coating technologies.
- Plastic:High-density polyethylene and polypropylene dominate through blow-molding and rotational molding processes. Barrier-coated PET is integrating oxygen scavenging layers for pharmaceutical intermediate transport in Basel and Ludwigshafen.
- Metal:Cold-rolled steel drums face margin pressure from scrap metal volatility tied to Chinese construction demand cycles. Stainless steel IBCs command premium pricing for corrosive chemical containment.
- Composite:Fiber-reinforced plastic and multi-material laminates capture agrochemical applications requiring ANVISA-registered corrosion resistance.
- Paper:Multi-wall corrugated bulk bins serve dry food ingredients and construction minerals where single-trip economics and recyclability outweigh moisture protection needs.
Plastic materials hold the dominant volume position, with composite formulations expanding most quickly in corrosive chemical applications.
End Use Industry:
Application requirements drive segmentation between food-grade barrier specifications and hazardous material UN certifications.
- Chemicals:Specialty and commodity chemical producers require UN-certified containment for solvents, intermediates, and agrochemical formulations. US Gulf Coast petrochemical exporters drive demand for intermodal-compatible IBC systems.
- Food & Beverage:FDA food contact substance notifications govern polyethylene and polypropylene formats for dry ingredients and liquid concentrates. Oxygen-scavenging liners are penetrating extended supply chain applications.
- Pharmaceuticals:CDSCO-certified containment systems serve API bulk shipments from Maharashtra and Gujarat manufacturing clusters with barrier-grade material specifications.
- Construction:Cement, adhesives, and coatings utilize flexible bulk bags and steel drums where abrasion resistance and moisture protection balance cost constraints.
Chemical end use sits at the top of the volume ranking, with pharmaceuticals climbing the fastest as Indian API exports expand certified containment requirements.
Distribution Channel:
Customer type segmentation separates enterprise fleet leasing from spot procurement through intermediaries.
- Distributors:Third-party logistics providers unbundle container fleet management from freight forwarding, offering telematics-tracked per-trip IBC pooling in North American crop protection markets.
- Direct Sales:Large chemical manufacturers procure certified fleets through long-term supply agreements with material passport documentation for ECHA SCIP compliance.
- E-commerce:Digital platforms serve small-batch chemical and food ingredient buyers with standardized format specifications and rapid fulfillment.
- Retail:Limited penetration in industrial bulk packaging; occasional presence in construction mineral and agricultural supply cooperatives.
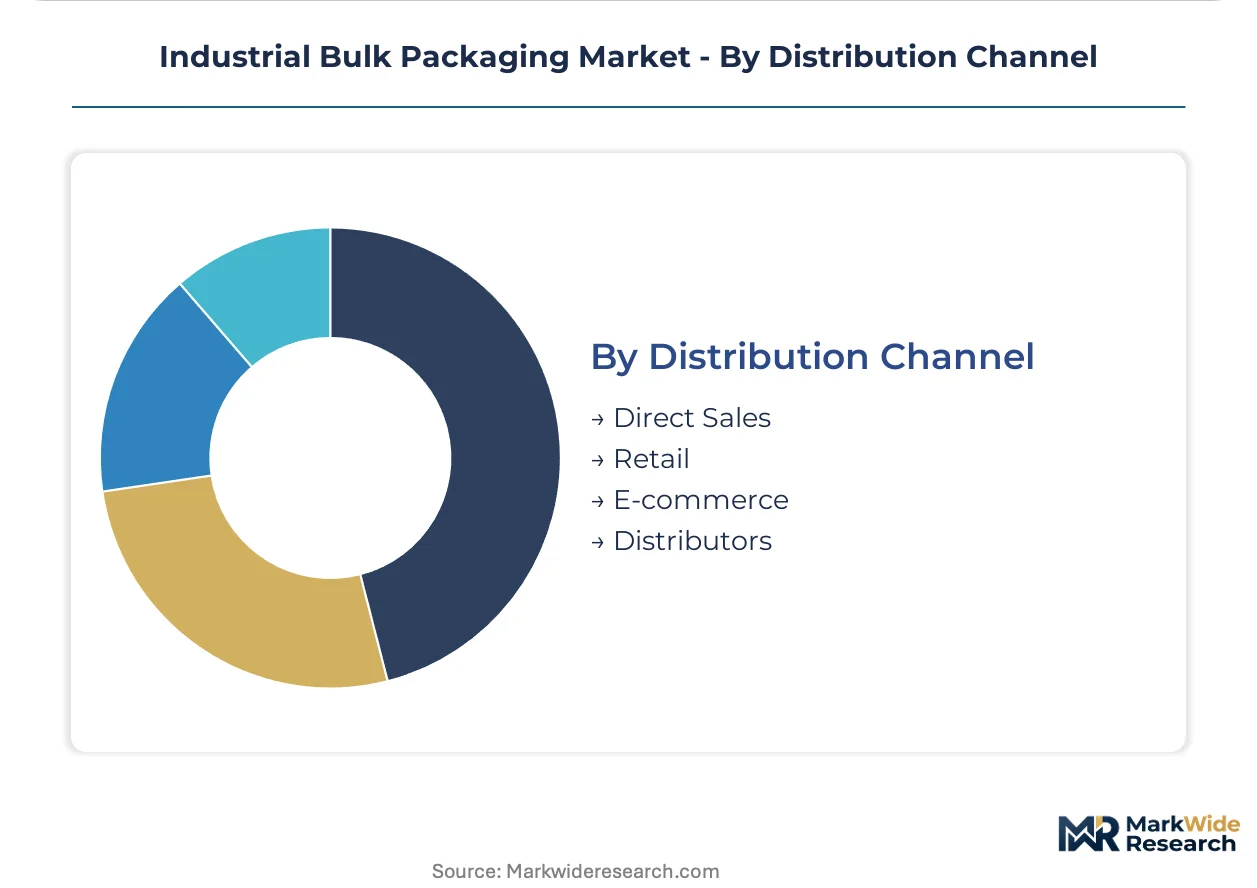
Distributor channels hold the dominant volume position, with direct sales gaining share fastest as REACH compliance drives consolidation around pre-validated supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified welding technicians and blow-molding engineers concentrate in Ohio, Pennsylvania, and Ludwigshafen, anchoring steel drum and IBC production capacity for hazardous material containment systems.
United States
US Gulf Coast petrochemical exporters drive intermodal IBC demand through Texas-Louisiana corridor facilities. EPA container containment requirements for agricultural pesticides constrain design parameters for domestic manufacturers. Houston and Beaumont refining clusters source UN-certified steel drums for solvent and lubricant distribution networks.
Germany
ECHA REACH compliance mandates force chemical manufacturers in Ludwigshafen and Leverkusen to document container material origins and reuse cycles. The country's SCIP database requirements for Substances of Very High Concern accelerate certified IBC fleet expansion. BASF and Bayer manufacturing clusters adopt closed-loop pooling services with material passport documentation.
India
API bulk shipments from Maharashtra and Gujarat manufacturing clusters create demand for CDSCO-certified containment systems. The country's national pharmaceutical regulator enforces barrier-grade material specifications for pharmaceutical intermediate transport. Mumbai-Pune and Ahmedabad-Vadodara corridors host emerging IBC refurbishment hubs serving export-oriented chemical producers.
Brazil
ANVISA registration requirements for pesticide containers generate demand for corrosion-resistant composite IBC systems. Soybean export corridors in Mato Grosso and Goiás deploy multi-ply flexible bulk bags with oxygen-scavenging liners. São Paulo-based agrochemical distributors unbundle container fleet management from traditional freight forwarding contracts.
China
Scrap metal cost swings tied to construction demand cycles compress drum manufacturer margins. The country's national standards body governs blow-molded polyethylene specifications for domestic chemical distribution. Yangtze River Delta petrochemical clusters in Shanghai and Ningbo source both steel drums and flexible bulk bags for solvent and mineral commodity flows.
Industrial Bulk Packaging Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the industrial bulk packaging landscape. Steel drum fabricators and blow-molded IBC manufacturers operate concentrated asset bases in Ohio, Pennsylvania, and Germany's chemical corridor. The vendor base separates into three archetypes: integrated metal processors with captive scrap sourcing, specialized pooling service operators with refurbishment networks, and diversified packaging conglomerates with multi-material portfolios. Capacity expansion and strategic partnerships dominate competitive moves as REACH compliance accelerates supplier consolidation.
Within the integrated metal processing tier, Greif Inc. and Mauser Packaging Solutions represent capital-intensive producers with North American plant density. SCHÜTZ GmbH & Co. KGaA exemplifies the specialized pooling archetype, anchoring European IBC refurbishment networks. These three companies occupy positions across steel drum manufacturing, composite container development, and closed-loop fleet management respectively.
| Leading Market Players |
|---|
| Mauser Packaging Solutions |
| Greif Inc. |
| Berry Global |
| SCHÜTZ GmbH & Co. KGaA |
| Mondi Group |
| DS Smith |
| International Paper |
| Sealed Air |
| Amcor Limited |
| Others |
Supply Flow & Price Mechanics
UN certification tier divergence between hazardous material IBCs and commodity flexible bulk bags manifests in both pricing premiums and supply chain sourcing patterns. Chemical shippers in Ludwigshafen and Houston pay triple-unit economics for certified fleets while agricultural buyers in Mato Grosso optimize cost-per-trip through disposable woven polypropylene formats.
Pricing Analysis
Bundled fleet management services versus unbundled per-trip leasing splits the pricing landscape for reusable IBC systems. Three-tier pricing structure across premium stainless steel, standard polyethylene, and economy refurbished formats reflects certification grade and barrier performance differentiation. Cost compression in steel drum manufacturing intensifies because scrap metal volatility tied to Chinese construction cycles erodes fabricator margins. Agricultural commodity processors demonstrate highest price sensitivity, while pharmaceutical intermediate shippers absorb premium pricing for oxygen-scavenging barrier technologies.
Supply Chain Analysis
Steel drum fabrication rests on cold-rolled steel supply from Chinese mills, blow-molded polyethylene feedstock from Gulf Coast petrochemical complexes, and woven polypropylene resin from Middle Eastern polymer producers. Raw material dependencies include scrap metal pricing indices, high-density polyethylene resin contracts, and polypropylene fiber grades. Single-source vulnerability concentrates in certified welding technician labor pools across Ohio and Pennsylvania. Distribution runs through third-party logistics providers offering telematics-tracked pooling contracts separate from freight forwarding services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as ECHA REACH compliance forces chemical manufacturers toward certified reusable fleets with material passport documentation. Premium specification demand from pharmaceutical intermediate transport collapses the historical performance gap between multi-trip rigid systems and single-use flexible formats.
For Market Incumbents: To counter margin compression from steel price volatility and plastic substitution limits, drum manufacturers should pursue backward integration into captive scrap metal sourcing and expand blow-molding capacity in Texas-Louisiana corridor facilities. Greif Inc. and Mauser Packaging Solutions exemplify the integrated metal processing archetype that can absorb input cost swings through upstream control over raw material flows. For New Entrants and Emerging Players: The mid-tier price-point gap between premium stainless steel IBCs and economy refurbished polyethylene units opens white-space opportunity in corrosion-resistant composite formulations for Brazilian agrochemical distribution. Target ANVISA-registered pesticide container requirements in Mato Grosso soybean corridors with fiber-reinforced plastic systems. A leasing-based go-to-market model unbundling fleet management from transport services captures seasonal demand spikes without owned-fleet capital intensity. For Investors and Strategic Acquirers: Consolidation pressure builds where ECHA SCIP database requirements and UN certification timelines favor suppliers with pre-validated material passports and established refurbishment networks. Long-term viability favors specialized pooling service operators with closed-loop logistics infrastructure over capital-heavy metal fabricators exposed to commodity input volatility. Watch RFID-integrated fleet tracking adoption rates as the inflection indicator for outcome-based contract penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Metal Sourcing | Cold-rolled steel drum fabricators in Ohio and Pennsylvania secure margin defense against Chinese construction demand cycles. |
| Barrier-Coated PET R&D Investment | Blow-molded IBC producers in Basel and Ludwigshafen capture pharmaceutical intermediate transport from stainless steel incumbents. |
| CDSCO-Certified Refurbishment Hub Expansion | IBC pooling operators in Mumbai-Pune corridor serve growing API bulk shipments from Maharashtra manufacturing clusters. |
| RFID-Integrated Fleet Tracking Deployment | Telematics-enabled per-trip contracts penetrate North American crop protection distribution with real-time container verification. |
| Closed-Loop Pooling Service Consolidation | SCHÜTZ GmbH & Co. KGaA's European refurbishment network model replicates in Indian pharmaceutical export corridors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at steel drum and IBC manufacturing facilities, procurement leads at downstream chemical and pharmaceutical producers, distribution channel partners managing fleet logistics, and technical R&D directors developing barrier coating technologies. Secondary validation drew from customs and trade data tracking bulk packaging flows, American Chemistry Council and Cefic industry reports, SEC 10-K filings from packaging conglomerates, and EPA container containment regulatory databases. Bottom-up unit economics modeling triangulated against top-down market sizing across packaging format segments.
Segment-weighting approaches distributed volume and value estimates across material type, end-use industry vertical, and regional production hub clusters throughout the projection horizon. The analytical framework modeled flexible bulk bags, IBCs, drums, and rigid containers separately, with further disaggregation by plastic, metal, composite, and paper material grades. CAGRs were derived from historical shipment correlations with downstream chemical production indices and agricultural commodity export volumes. Forecast inputs incorporated UN certification timeline constraints, REACH compliance implementation schedules, and scrap metal price elasticity assumptions.
Caveats apply where regulatory acceleration in Extended Producer Responsibility frameworks or sudden shifts in Chinese construction demand could materially shift the outlook for reusable versus disposable format economics. Forecasts reflect assumptions about certification timeline compression, welding technician labor availability, and barrier film technology cost curves. A small set of named triggers warrants ongoing watch: California plastic packaging fee legislation, ECHA SVHC list expansions, and Indian pharmaceutical export growth trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Fiber Drums Market
Industrial Packaging
Anti-Static Reel Racks Market
Industrial Packaging
Asia-Pacific Warehouse Drums and Barrel Market
Industrial Packaging
Industrial Filling Machine Market
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Cone Bottom Tank Market
Industrial Packaging
Dunnage Trays Market
Industrial Packaging
Industrial Packaging Market
Industrial Packaging
Industrial Pails Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Bulk Liquid Transport Packaging Market
Industrial Packaging
Insulated Bin Market
Industrial Packaging
Slip Sheets Market
Industrial Packaging
Corrugated Octabins Market