
 Middle East and Africa Octabin Market | 2026-2036
Middle East and Africa Octabin Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Octabin Market Foresight
Saudi Arabia's industrial packaging capacity build-out is reconfiguring supply dynamics across the Gulf. WestRock Company leverages its corrugated infrastructure to serve petrochemical clients with tailored octabin specifications. Napco National anchors domestic production through integrated paperboard mills in Dammam. Mondi competes on moisture-resistant liner technologies for humidity-exposed supply chains.
Octabins are eight-sided bulk containers engineered from triple-wall corrugated board with capacities typically ranging from 500 to 1,500 kilograms, designed for free-flowing dry goods transport and storage. Standard octabins dominate volume shipments for grain and resin handlers seeking minimal unit cost. Collapsible variants are gaining traction among chemical distributors prioritizing warehouse space recovery and return logistics efficiency. Kraft paper substrates lead material preference where recyclability mandates intersect with cost-sensitive procurement.
Saudi Standards, Metrology and Quality Organization (SASO) and South African Bureau of Standards (SABS) enforce load-bearing and hygiene benchmarks that filter out uncertified imports. Emirates Authority for Standardization and Metrology (ESMA) extends ECAS food-contact certification requirements to intermediate bulk packaging used in re-export trade. Stakeholders must track evolving conformity pathways across Gulf Cooperation Council harmonization talks and African Continental Free Trade Area technical barriers-to-trade negotiations.
Market Dynamics
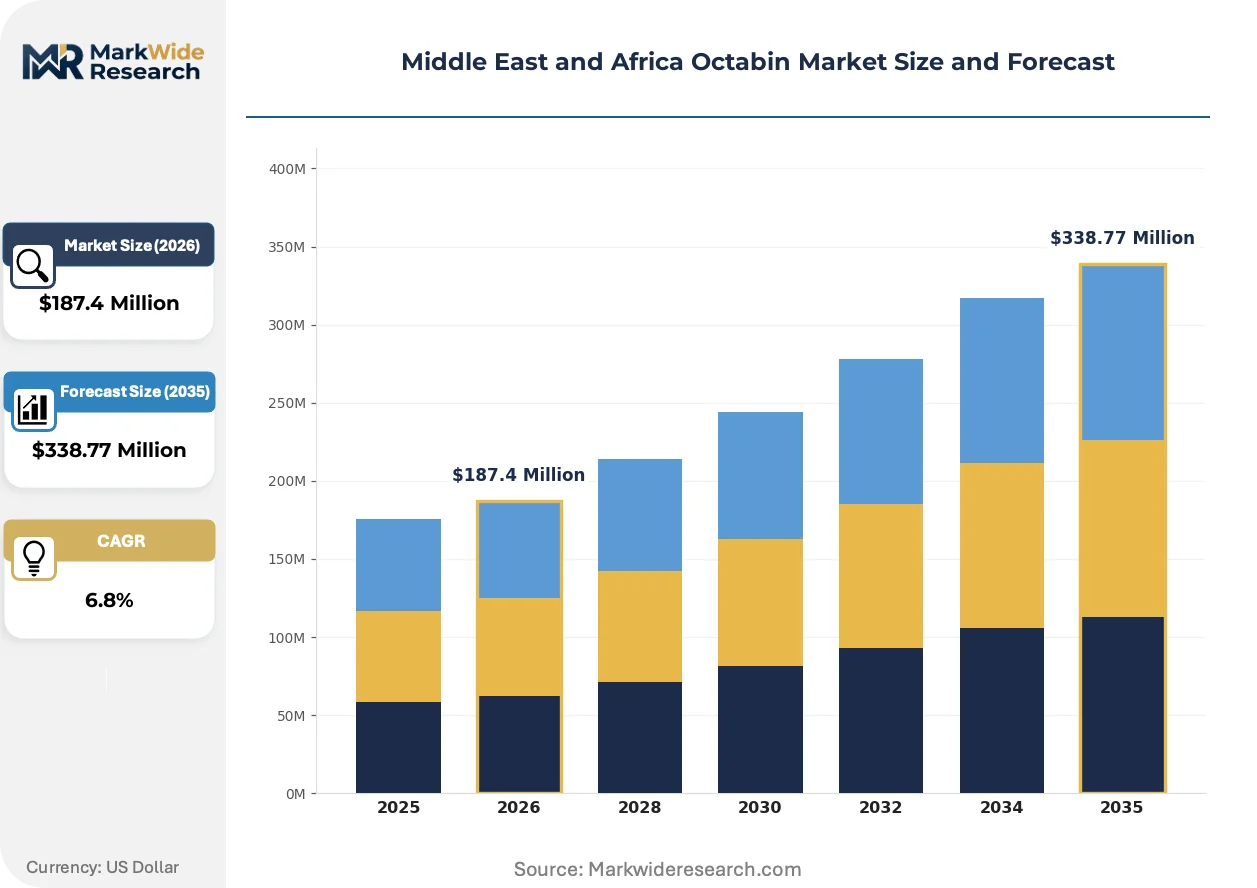
Petrochemical corridor expansion across the Gulf is compressing lead times for resin-grade octabin procurement while stricter ECAS certification requirements in the UAE are filtering supplier pools toward integrated converters with in-house liner testing capabilities.
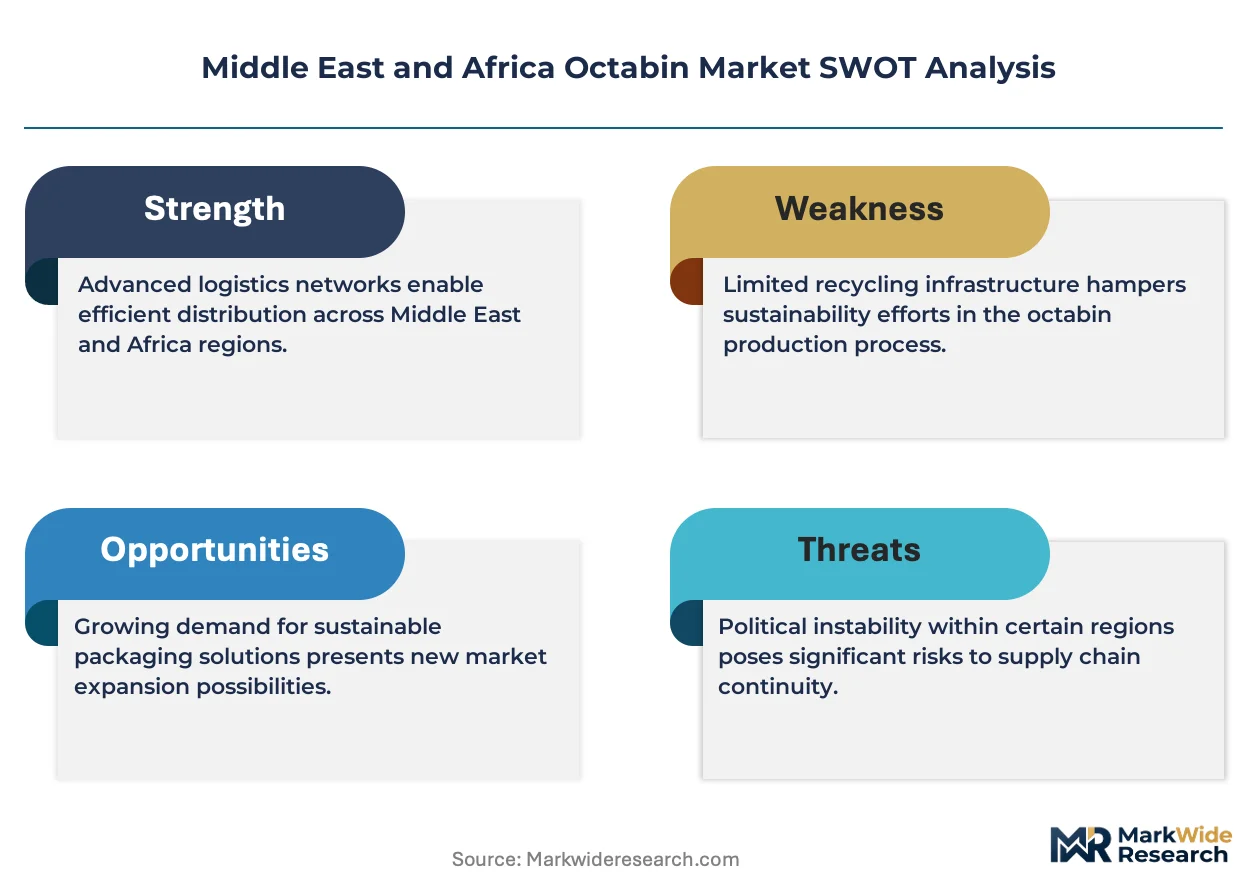
Growth Catalysts
- Grain export infrastructure:South African agricultural commodity handlers are scaling bulk packaging volumes to match rising maize and sorghum shipment throughput to Asian markets.
- ECAS food-contact mandates:Emirates Authority for Standardization and Metrology certification requirements for re-export trade are consolidating procurement toward certified liner system providers.
- Collapsible format adoption:Chemical distributors in Saudi Arabia's Eastern Province are prioritizing space-recoverable octabin variants for return logistics efficiency in polymer distribution.
Market Restraints
- Kraft paper input volatility:Pulp price fluctuations and containerboard supply tightness in Europe are transmitting cost pressure to MEA converter operations.
- Import dependency for specialty liners:Moisture-resistant and food-grade liner substrates concentrate among Nordic and German suppliers, exposing buyers to currency and shipping cost swings.
- Load-bearing standard fragmentation:Divergent SASO, SABS, and ESMA test protocols force parallel certification tracks, extending qualification timelines for multi-territory suppliers.
Strategic Opportunities
- Nigerian agro-processing:Cocoa and cashew export handlers in Lagos and Port Harcourt represent underpenetrated demand for certified bulk packaging as port modernization proceeds.
- GCC harmonization pathway:Gulf Cooperation Council technical alignment talks could collapse multi-country certification burden into single conformity assessment, rewarding early-integrated regional producers.
- Digital print integration:Combined QR-code traceability and variable-data branding on octabin outer surfaces is opening premium positioning for commodity exporters serving European retail chains.
Industry Challenges
- Corrugated structural engineering talent:Triple-wall board design and dynamic load modeling expertise remains scarce across Dammam and Johannesburg converter bases.
- Legacy warehouse automation incompatibility:Existing palletizing and stretch-wrapping lines in Saudi chemical distribution centers require retrofit to handle octagonal footprint containers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Octabin Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Octabin, Custom Octabin, Collapsible Octabin, Lined Octabin Material: Cardboard, Kraft Paper, Plastic, Composite End User: Food & Beverage, Chemicals, Pharmaceuticals, Retail Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | WestRock Company, D.V.A. Group, International Paper, Napco National, Dunapack Kft., Mondi, DS Smith, Rondo Ganahl, Smurfit Kappa Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Octabin Market Shifts & Advancements
Moisture-resistant liner technologies and digital traceability integration are redefining performance benchmarks for octabin specifications across humidity-exposed supply chains and export-oriented agricultural corridors.
Multi-layer barrier liner systems incorporating polyethylene-coated kraft and vapor-deposited aluminum oxide are hybridizing traditional corrugated octabin construction with active protection properties. Saudi polymer distributors operating Jeddah and Dammam warehouses are specifying these configurations for hygroscopic resin grades. The technology is hybridizing procurement criteria toward total-cost-of-ownership metrics rather than unit price alone.
SASO technical regulations for intermediate bulk packaging are tightening stack-load endurance and hygiene documentation requirements for domestic distribution. Saudi resin producers must now submit batch-level liner migration test reports. Petrochemical handlers with integrated captive packaging operations are absorbing compliance costs more efficiently than merchant market buyers.
Consolidated procurement desks at major South African grain cooperatives are compressing supplier rosters toward full-service converters offering design, certification, and logistics coordination. Regional distributors with standalone trading models are losing share to integrated packaging partners. This concentration is most visible in the Western Cape wheat and Eastern Cape citrus export corridors.
Middle East and Africa Octabin Market Segmentation
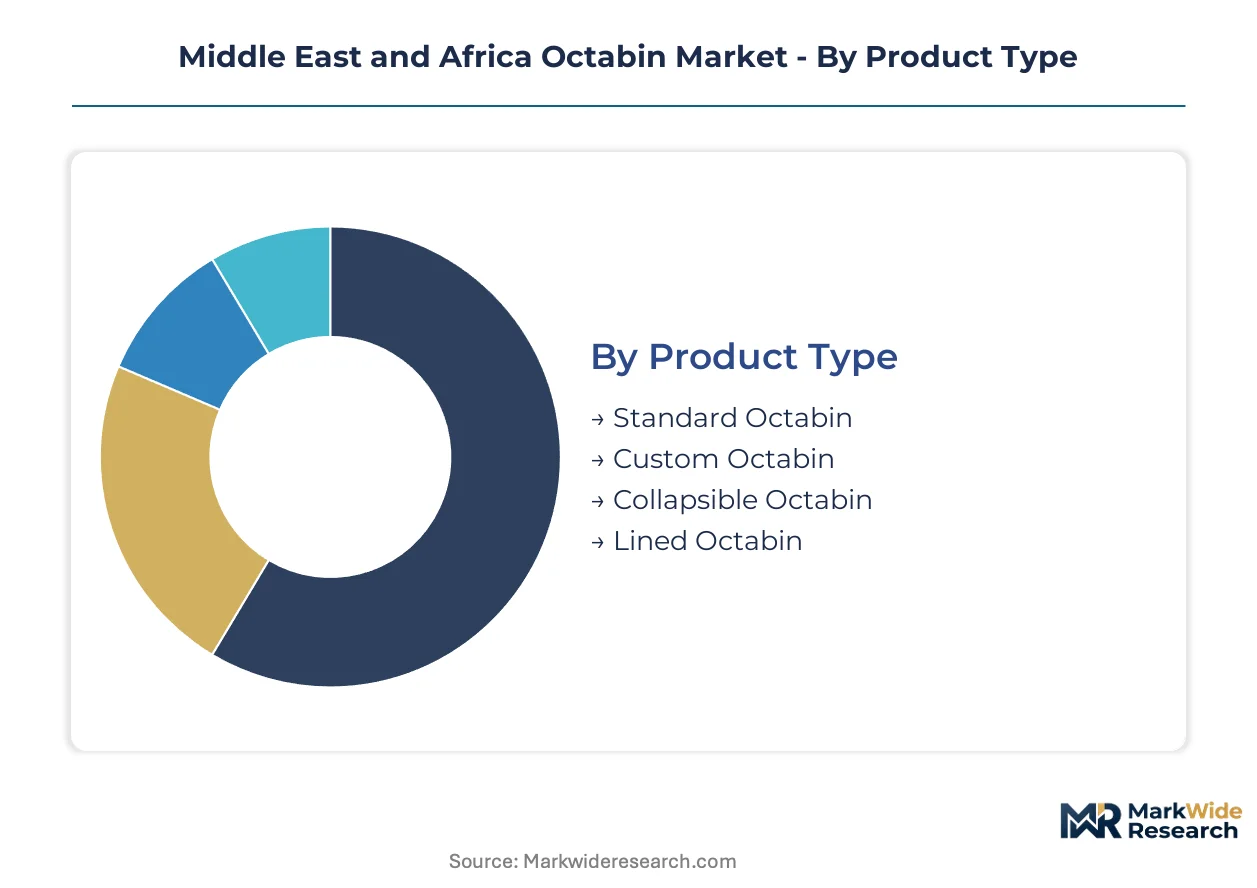
Octabin procurement patterns across the Middle East and Africa diverge sharply by product format, substrate choice, and channel structure. Understanding these segment boundaries clarifies where converters earn premium returns versus where price competition dominates volume flows.
Product Type:
Mature formats dominate established corridors while emerging configurations capture efficiency-driven replacement cycles.
- Standard Octabin:Triple-wall corrugated construction with fixed octagonal geometry serves grain handlers and resin shippers seeking minimal unit cost. South African maize exporters in the Western Cape specify these for bulk vessel loading to Asian markets.
- Collapsible Octabin:Fold-flat designs with reinforced corner posts enable warehouse space recovery and return logistics. Saudi polymer distributors in Dammam are specifying these for closed-loop distribution to domestic compounders.
- Custom Octabin:Engineered dimensions and load-bearing specifications for non-standard bulk densities. Food-grade configurations with ECAS-certified liners serve UAE re-export handlers.
- Lined Octabin:Multi-layer barrier systems incorporating polyethylene-coated kraft for moisture-sensitive cargoes. Hygroscopic resin grades moving through Jeddah's humid coastal warehouses drive specification.
Standard octabins handle the majority of throughput; collapsible variants are gaining share fastest among chemical distributors prioritizing logistics efficiency.
Material:
Substrate selection tracks recyclability mandates, moisture exposure, and total cost of ownership calculations across divergent supply chain conditions.
- Kraft Paper:Unbleached virgin or recycled fiber substrates dominate where recyclability mandates intersect with cost-sensitive procurement. SASO-compliant kraft grades anchor Saudi domestic production.
- Cardboard:Multi-ply containerboard constructions with specific edge crush test ratings for defined stack loads. South African converters source from integrated Dammam mills to reduce import dependency.
- Composite:Hybrid constructions combining corrugated shells with polymer or foil barrier layers. ECAS food-contact certification requirements in the UAE push specification toward tested composite systems.
- Plastic:Injection-molded or thermoformed polypropylene octagonal bins for liquid-tight or washdown applications. Niche penetration in pharmaceutical ingredient handling where fiber contamination risks exist.
Kraft paper commands the volume base; composite materials are expanding most quickly as barrier requirements tighten.
End User:
Demand concentration aligns with export-oriented commodity flows and import-dependent processing industries across the region's economic geography.
- Chemicals:Petrochemical producers and polymer distributors require high-volume intermediate bulk containers for resin pellet handling. Saudi Arabia's Eastern Province corridor generates concentrated specification for moisture-resistant and collapsible formats.
- Food & Beverage:Grain cooperatives, cocoa processors, and cashew exporters need certified food-contact packaging for European and Asian market access. ECAS and SABS hygiene documentation requirements filter supplier pools.
- Pharmaceuticals:Active ingredient and excipient handlers specify fiber-free or lined configurations to prevent contamination. South African generic drug exporters drive quality-tier procurement.
- Retail:Bulk dry goods distribution to hypermarket and cash-and-carry chains. Limited penetration relative to industrial segments due to palletization preferences.
Chemicals absorbs the largest share of tonnage; food and beverage is climbing the fastest as agricultural export infrastructure expands.
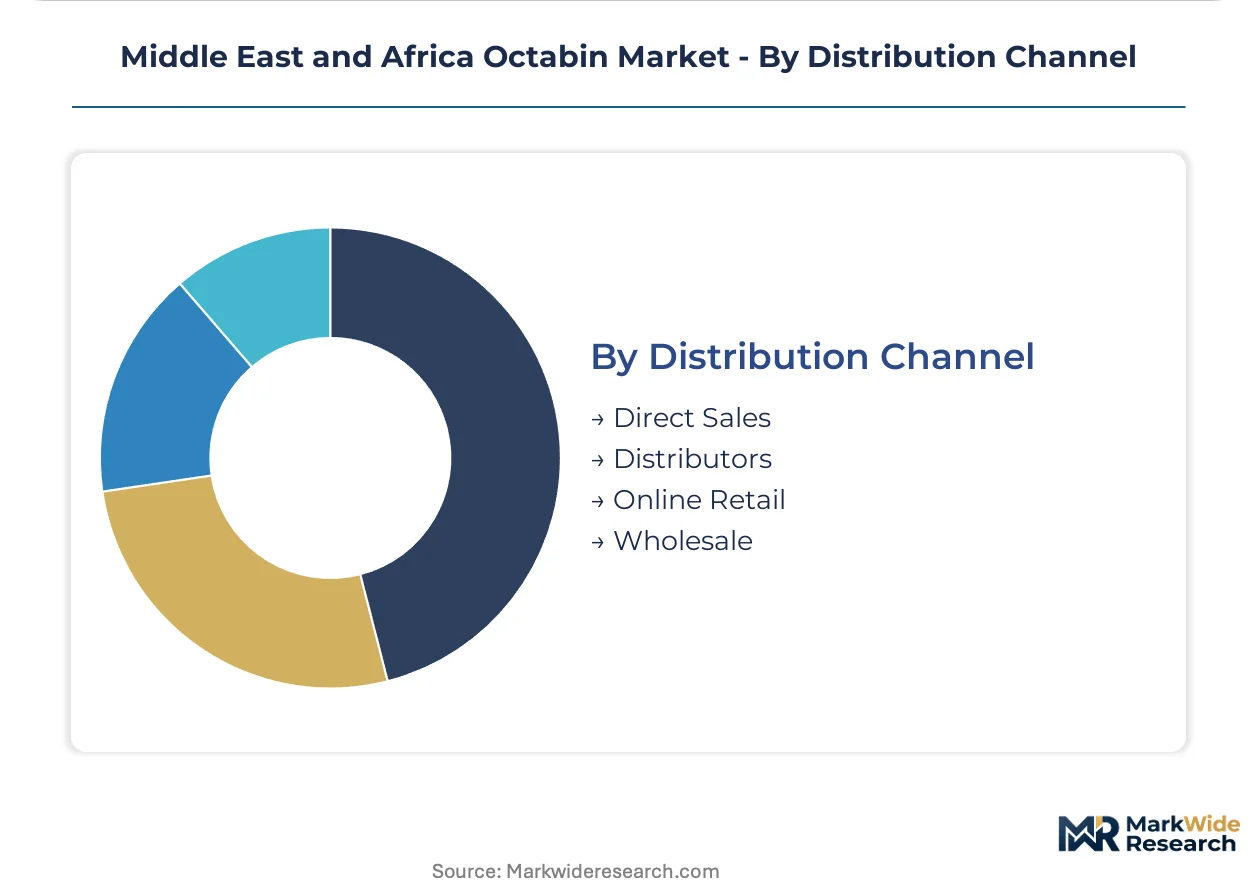
Distribution Channel:
Channel structure reflects buyer scale, certification complexity, and the geographic spread of converter manufacturing assets.
- Direct Sales:Large-volume petrochemical and grain handlers negotiate direct with integrated converters for specification-managed programs. WestRock and Napco National maintain dedicated account teams for Saudi Aramco-linked resin producers.
- Distributors:Regional packaging merchants stock standard sizes for mid-tier chemical and food processors. Johannesburg and Lagos distributor networks serve fragmented demand.
- Wholesale:Volume aggregators supplying smaller agricultural cooperatives and regional compounders. Price competition intensifies where specification requirements are minimal.
- Online Retail:Digital catalog procurement for standardized dimensions and small-batch orders. Nascent penetration limited by customization requirements and certification documentation needs.
Direct sales capture the highest-value contracts; distributor networks are expanding most quickly as procurement desks consolidate supplier rosters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SASO technical regulations anchor Saudi Arabia's dominance in Middle East and Africa octabin demand. The kingdom's petrochemical corridor generates concentrated procurement for resin-grade bulk packaging. National standards across the region create divergent certification burdens that reshape supplier access.
Saudi Arabia
Resin producers in the Eastern Province drive specification for moisture-resistant and collapsible formats. SASO mandates batch-level liner migration test reports for domestic distribution. Dammam's integrated paperboard mills anchor captive packaging operations for major polymer handlers.
United Arab Emirates
Re-export trade through Jebel Ali concentrates demand for ECAS-certified food-contact packaging. ESMA certification requirements filter supplier pools toward integrated converters with in-house liner testing. Dubai-based logistics operators specify multi-layer barrier systems for humidity-exposed cargoes.
South Africa
Grain cooperatives in the Western Cape scale bulk packaging volumes for maize and sorghum shipments to Asian markets. SABS hygiene documentation requirements filter supplier pools for agricultural export handlers. Port modernization in Durban and Cape Town expands certified packaging infrastructure.
Nigeria
Cocoa and cashew exporters in Lagos and Port Harcourt represent underpenetrated demand for certified bulk packaging. The country's national standards organization enforces load-bearing benchmarks for agricultural shipments. Agro-processing clusters in the southwest corridor drive initial specification adoption.
Egypt
Chemical distributors along the Suez Canal corridor generate emerging demand for intermediate bulk containers. National quality infrastructure regulations align with broader regional harmonization efforts. Alexandria's industrial zones attract packaging converters serving Mediterranean re-export trade.
Middle East and Africa Octabin Market Competitive Landscape
Integrated corrugated producers and regional packaging specialists split the market along certification capability and geographic proximity lines. Supplier concentration favors converters with captive liner testing and multi-territory qualification expertise. Two archetypes dominate: Gulf-based integrated paperboard mills with petrochemical anchor contracts, and European-headquartered multinationals competing on barrier technology and food-grade certification. Competitive moves center on backward integration into liner substrate supply and strategic partnerships with resin producers for specification lock-in.
Among integrated regional producers, Napco National exemplifies the captive mill archetype through its Dammam-based paperboard operations. WestRock Company occupies a position representing multinational corrugated infrastructure leveraged for petrochemical client specifications. Mondi sits within the specialty barrier tier, competing on moisture-resistant liner technologies for humidity-exposed supply chains.
| Leading Market Players |
|---|
| WestRock Company |
| D.V.A. Group |
| International Paper |
| Napco National |
| Dunapack Kft. |
| Mondi |
| DS Smith |
| Rondo Ganahl |
| Smurfit Kappa Group |
| Others |
Supply & Pricing Matrix
Jebel Ali's container freight corridors transmit European pulp cost volatility directly into MEA converter pricing power, compressing margins for merchant buyers while rewarding integrated producers with captive liner supply and multi-territory certification assets.
Pricing Analysis
Price spreads between Dammam and Johannesburg converters exceed transport cost differentials, reflecting SASO certification premiums and ECAS food-contact testing burdens. Three-tier pricing structure across premium certified, standard compliant, and economy unlined grades separates petrochemical anchor contracts from spot agricultural procurement. Pricing pressure stems from Nordic specialty liner import dependency and currency swings against the euro. Grain cooperatives exhibit acute price sensitivity; polymer distributors with captive packaging operations absorb cost compression more resiliently.
Supply Chain Analysis
Upstream kraft pulp feedstock concentrates in Sweden, Finland, and Germany, exposing MEA converters to containerboard tightness and energy cost pass-throughs from European mill closures. Raw material dependencies span unbleached softwood pulp, polyethylene-coated barrier substrates, and vapor-deposited aluminum oxide films. Single-source vulnerability concentrates in moisture-resistant liner grades where Nordic suppliers dominate qualified vendor lists. Distribution runs through direct sales for petrochemical volume contracts and Johannesburg-Lagos distributor networks for fragmented agricultural demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Structural engineering talent scarcity for triple-wall board design and dynamic load modeling constrains converter expansion, making specialized capability acquisition the defining competitive maneuver across the forecast window.
For Market Incumbents: Insulate petrochemical anchor contracts through backward integration into liner substrate supply and captive SASO certification laboratories. Resin producers with integrated packaging operations already absorb compliance costs more efficiently than merchant market competitors; extending this advantage through dedicated account engineering teams locks in specification-managed programs against European barrier-technology entrants. For New Entrants and Emerging Players: Pursue Nigerian cocoa and cashew export corridors in Lagos and Port Harcourt where certified bulk packaging penetration remains underdeveloped relative to South African grain infrastructure. ECAS food-contact certification capabilities acquired early position entrants for UAE re-export trade expansion as Gulf Cooperation Council harmonization talks advance technical alignment. For Investors and Strategic Acquirers: Gulf Cooperation Council regulatory harmonization reshapes the acquisition landscape by collapsing multi-country certification burdens into single conformity assessments, rewarding early-integrated regional producers. Five-to-ten year viability favors converters with captive paperboard mills and in-house liner testing capabilities. Monitor African Continental Free Trade Area technical barriers-to-trade negotiations as the signal for demand acceleration across West African agro-processing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Liner Substrate Supply | Captive kraft pulp sourcing insulates Napco National and WestRock from European containerboard volatility. |
| SASO Certification Laboratory Investment | In-house migration testing accelerates Saudi resin producer qualification timelines against import-dependent competitors. |
| Joint Venture with Polymer Distributors | Specification lock-in through Dammam-based compounder partnerships secures collapsible octabin volume commitments. |
| Digital Print Traceability Integration | QR-code branding opens premium positioning for South African grain cooperatives serving European retail chains. |
| West African Distribution Network Expansion | Lagos and Port Harcourt stocking points capture Nigerian cocoa export growth ahead of port modernization completion. |
Research Methodology
Cross-validation between converter production data and customs trade records anchors the qualitative findings across the Middle East and Africa octabin market. Primary interviews with corrugated plant managers, petrochemical procurement leads, grain cooperative logistics directors, and ECAS certification specialists combined with secondary validation from SASO technical regulations, SABS load-bearing standards, ESMA food-contact guidelines, and pulp futures pricing data. Bottom-up capacity modeling and top-down demand estimation triangulate volume outputs.
Calibration against historical containerboard price cycles and freight rate indices refines the analytical framework across the projection horizon. Segmentation dimensions span product format, substrate material, end-use industry, and distribution channel, with regional regulatory cluster as an additional modeled variable. CAGRs derive from trend extrapolation of petrochemical corridor expansion rates and agricultural export infrastructure investment pipelines. Forecast inputs include pulp price elasticity assumptions and certification timeline distributions.
Sensitivities concentrate around European energy cost pass-throughs to liner substrate pricing and Gulf Cooperation Council harmonization implementation timing. Forecasts reflect documented assumptions about converter capacity expansion schedules and grain shipment volume trajectories. Cross-checking against pulp futures forward curves and Jebel Ali container throughput indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Insulated Bin Market
Industrial Packaging
Industrial Chemical Packaging Market
Industrial Packaging
Dunnage Trays Market
Industrial Packaging
Global Dunnage Packaging Market
Industrial Packaging
Rigid IBC Market
Industrial Packaging
MENA Industrial Packaging Market
Industrial Packaging
Industrial Pails Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Corrugated Octabins Market
Industrial Packaging
Slip Sheets Market
Industrial Packaging
Bulk Packaging Market
Industrial Packaging
Corrugated Bulk Bins Market
Industrial Packaging
Industrial Plastic Bags Market
Industrial Packaging
Global Industrial Wooden Crates Market
Industrial Packaging
Industrial Filling Machine Market