
 Overpack Drum Market | 2026-2036
Overpack Drum Market Size, Share, and Industry Trends Forecast 2026-2036
Overpack Drum Market Outlook
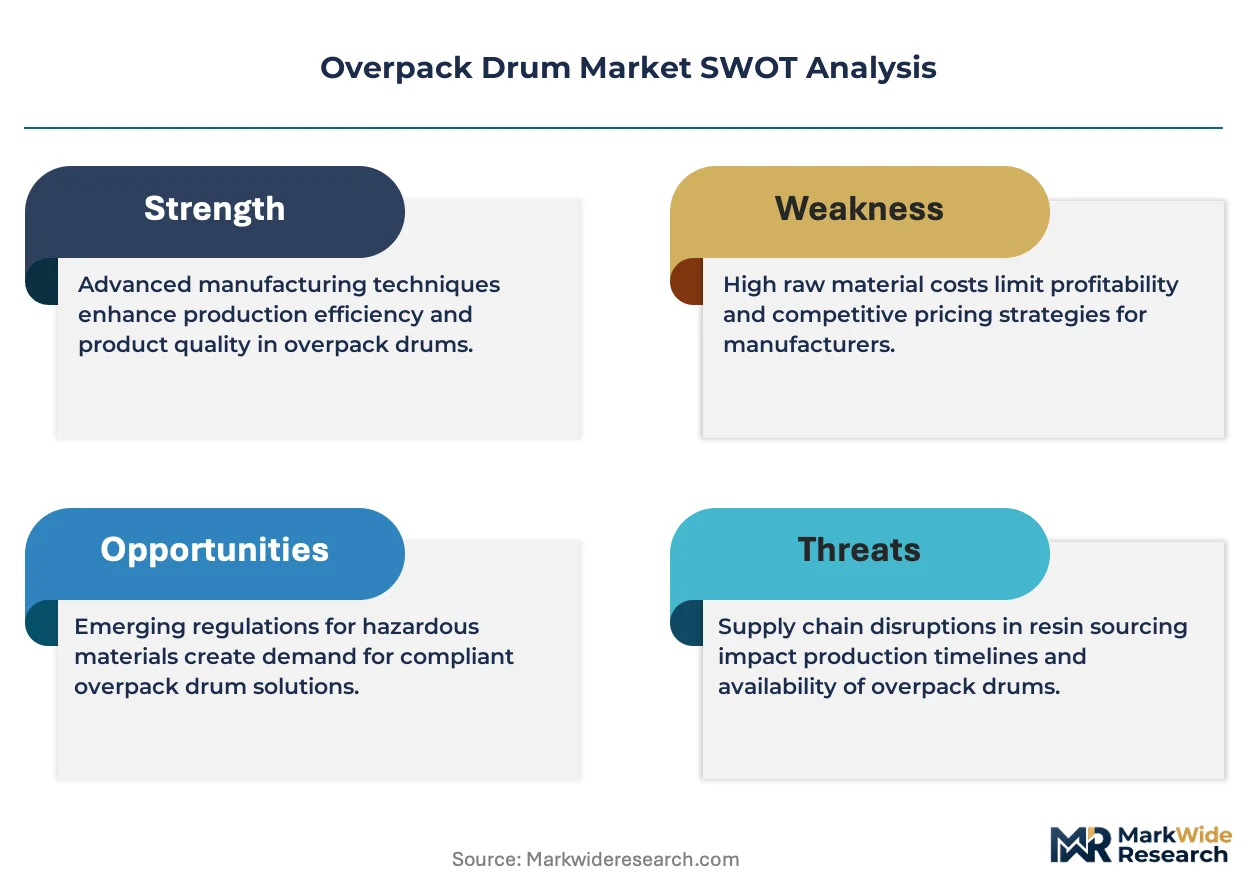
Aftermarket recertification and reconditioning services is rewriting margin distribution across the value chain. Greif Inc. leverages its integrated collection-and-recertification network to capture recurring revenue from large chemical accounts. Mauser Packaging Solutions anchors its position through closed-loop pooling systems that extend drum lifecycle utilization. SCHÜTZ GmbH & Co. KGaA differentiates via specialized intermediate bulk container-to-overpack hybrid designs for European chemical exporters.
An overpack drum is a secondary containment vessel designed to enclose and protect a primary package—typically a damaged, leaking, or non-compliant drum—during storage, handling, or transport of hazardous materials; construction specifications include UN-certified wall thickness, gasket-sealed closures rated for specific chemical compatibilities, and impact-resistant polyethylene or steel shells tested to DOT 49 CFR and IATA DGR drop and stack protocols. The primary industrial purpose is to prevent environmental release and ensure regulatory compliance when primary packaging fails or requires supplemental protection. Steel drums dominate high-volume chemical storage applications where thermal stability and puncture resistance command premium positioning, while polyethylene drums are gaining fastest in corrosive substance handling due to chemical inertness and lighter tare weights that reduce freight costs. Closed head configurations retain the largest share in hazardous waste consolidation, whereas open head designs capture expanding demand in food packaging and industrial use segments requiring frequent access.
The EPA's Resource Conservation and Recovery Act requirements and DOT hazardous materials regulations govern overpack drum specifications, testing protocols, and manifest documentation across the United States, while UN Performance-Oriented Packaging standards and IATA Dangerous Goods Regulations shape cross-border shipment compliance. OSHA workplace safety directives further mandate secondary containment in manufacturing and laboratory environments, embedding overpack drums into operational risk management frameworks. Stakeholders must monitor evolving state-level hazardous waste rulemakings and emerging bio-based material certifications that could redefine acceptable construction standards.
Market Dynamics
EPA hazardous waste rulemakings and DOT 49 CFR specification upgrades are forcing drum replacement cycles shorter than historical ten-year baselines, compressing capital planning horizons for chemical handlers and waste consolidators.
Growth Catalysts
- UN Model Regulations on dangerous goods transport:Cross-border chemical exporters in Germany and the Netherlands must maintain certified overpack inventories, expanding replacement demand for compliant polyethylene and steel shells.
- Gulf Coast petrochemical cluster expansion:New ethylene and propylene capacity additions around Houston and Corpus Christi are generating captive demand for thermal-stable steel overpacks in high-temperature process streams.
- Closed-loop pooling systems:Large chemical accounts are adopting lifecycle management contracts that embed recertification services, converting one-time drum sales into recurring revenue arrangements.
Market Restraints
- High-density polyethylene resin volatility:Feedstock cost swings tied to ethylene spot markets compress margin predictability for rotational-molded drum manufacturers.
- Steel tariff concentration risk:Domestic mill capacity limitations and Section 232 trade measures elevate input cost exposure for steel drum fabricators concentrated in Midwest production corridors.
- Intermediate bulk container substitution:Schütz and Mauser IBC-to-overpack hybrid designs are capturing volume in European chemical export lanes, constraining pure overpack drum addressable market expansion.
Strategic Opportunities
- Great Lakes industrial corridor consolidation:Ohio and Michigan hazardous waste handlers face EPA RCRA enforcement intensification, creating specification-upgrade demand for dual-certified steel-polyethylene composite drums.
- Bio-based material certification emergence:Emerging ASTM standards for renewable-content industrial packaging could unlock premium positioning for drum producers with validated circular feedstock chains.
- Drone-based hazmat logistics:Convergence of unmanned aerial vehicle transport protocols with lightweight polyethylene drum designs is opening last-mile delivery applications for remote industrial sites.
Industry Challenges
- UN Performance-Oriented Packaging certification timelines:Third-party testing bottlenecks at DOT-recognized laboratories extend new product qualification cycles to fourteen months, delaying revenue recognition for design innovations.
- Legacy ERP integration with track-and-trace mandates:Hazardous waste manifest digitization requirements under EPA e-Manifest rules force drum fleet operators to retrofit barcode and RFID systems onto aging inventory management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Overpack Drum Market |
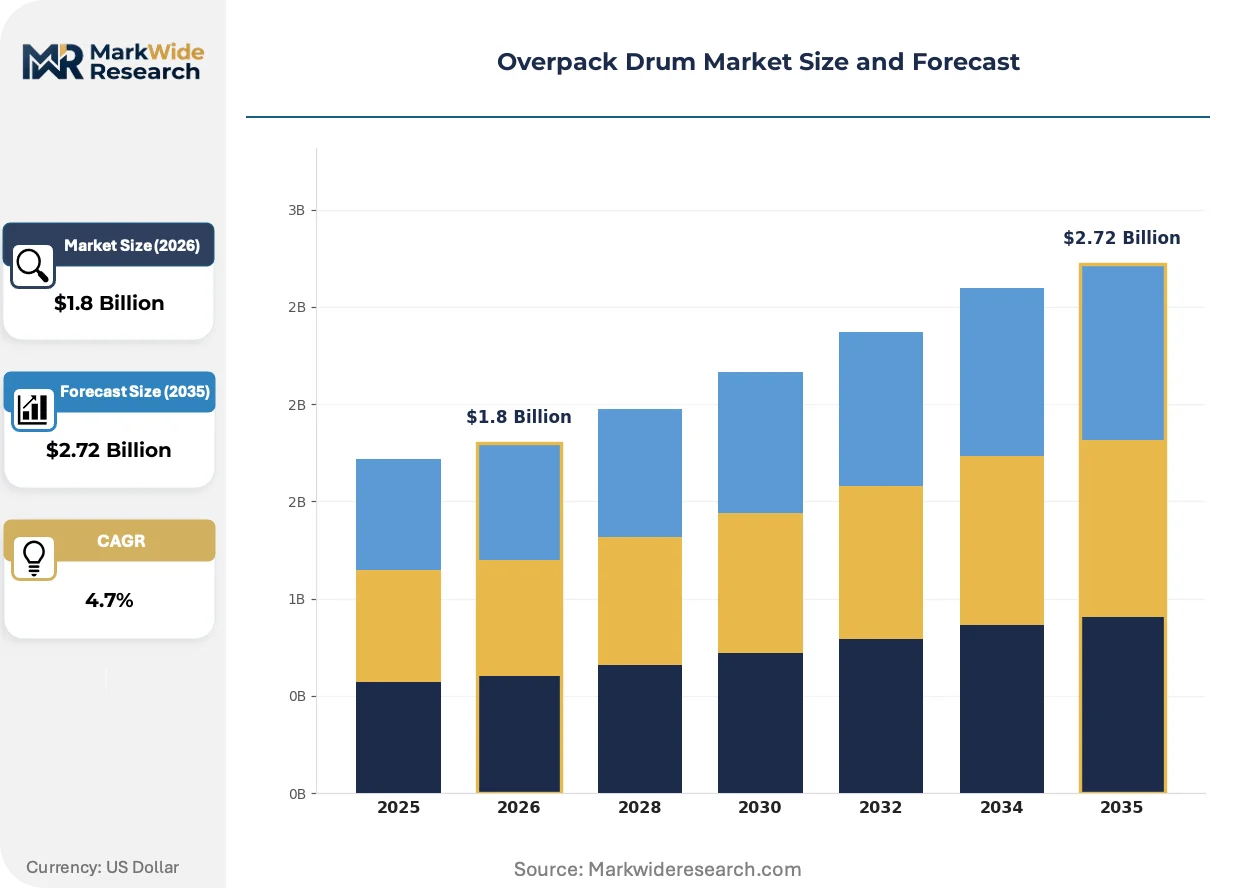
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Drum, Steel Drum, Fiber Drum, Plastic Drum Capacity: 30 Gallon, 55 Gallon, 110 Gallon, 210 Gallon Closure Type: Closed Head, Open Head, Tapped, Screw Cap Application: Hazardous Waste, Food Packaging, Chemical Storage, Industrial Use |
| Companies Covered | Greif Inc., Mauser Packaging Solutions, SCHÜTZ GmbH & Co. KGaA, Berry Global, Eagle Manufacturing, ENPAC, The Cary Company, Skolnik Industries, Berlin Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Overpack Drum Market Strategic Shifts
Embedded sensor integration and predictive maintenance protocols are transforming overpack drums from passive containment vessels into active compliance assets that generate operational data streams.
RFID-enabled drum tracking is digitizing fleet utilization patterns for chemical manufacturers running multi-site hazardous waste consolidation programs. Dow and BASF pilot deployments in Texas and Louisiana demonstrate real-time location monitoring compressing drum turnaround times by eliminating manual inventory reconciliation. This visibility infrastructure is digitizing asset-light logistics models previously dependent on physical yard checks.
EPA's e-Manifest system expansion is mandating electronic hazardous waste documentation across all fifty states, eliminating paper manifest workflows by 2025. Drum fleet operators must retrofit barcode and QR code systems to maintain manifest compliance, accelerating capital deployment into track-and-trace hardware. Small waste handlers in Appalachia and the Intermountain West face disproportionate compliance burdens due to limited IT infrastructure.
Leasing and pooling arrangements are displacing outright drum purchases among Fortune 500 chemical producers seeking to offload recertification liability. Mauser and Greif closed-loop service contracts bundle drum provision, collection, reconditioning, and regulatory documentation into per-use fees. This preference shift concentrates procurement authority among integrated service providers and marginalizes standalone drum manufacturers without reverse logistics networks, with adoption most advanced in Gulf Coast and Ohio River Valley chemical processing corridors.
Overpack Drum Market Segmentation
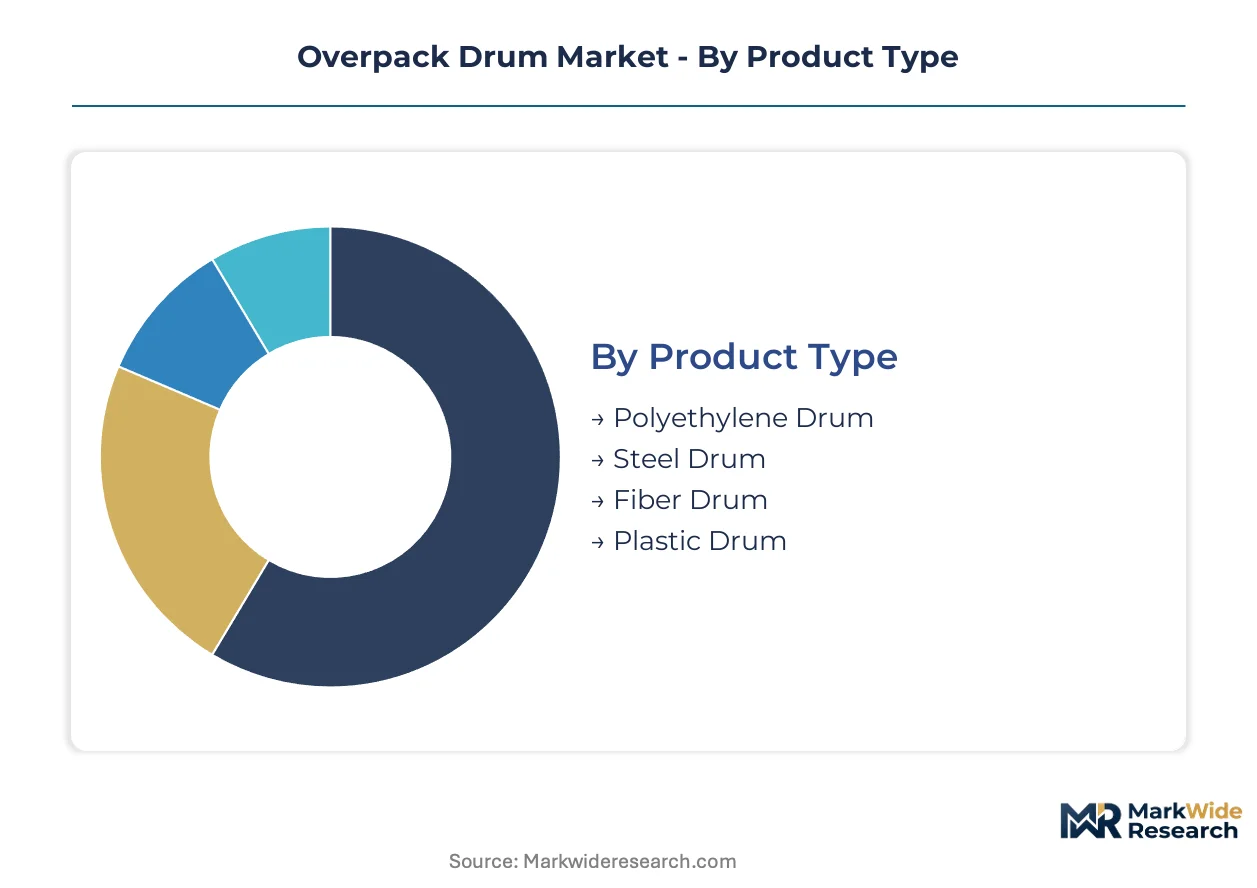
Overpack drum procurement patterns diverge sharply across material specifications, capacity tiers, and closure configurations. Each segmentation axis carries distinct implications for recertification frequency, logistics handling, and regulatory documentation burdens.
Product Type:
After-sales service intensity varies dramatically by material substrate, with polyethylene drums demanding liner replacement programs and steel shells requiring corrosion inspection protocols.
- Polyethylene Drum:Rotational-molded high-density polyethylene construction delivers chemical inertness against acids and caustics. Demand concentrates in corrosive substance handling along the Texas Gulf Coast, where lighter tare weights reduce freight costs for chemical exporters.
- Steel Drum:Cold-rolled carbon steel shells with UN-certified wall thickness provide thermal stability and puncture resistance. Procurement clusters around Houston and Corpus Christi petrochemical facilities where high-temperature process streams mandate metallic containment.
- Fiber Drum:Kraft fiberboard with moisture-resistant coatings offers biodegradable disposal pathways for non-hazardous dry goods.
- Plastic Drum:Injection-molded polypropylene variants serve food-grade and pharmaceutical applications requiring FDA-compliant contact surfaces.
Steel drums hold the largest share; momentum sits with polyethylene drums.
Capacity:
Volume scale dictates handling equipment requirements and manifests as the primary cost tier differentiator in fleet procurement decisions.
- 55 Gallon:The standard industrial benchmark dimensioned for forklift handling and railcar loading. Dominates hazardous waste consolidation across Ohio and Michigan RCRA enforcement corridors.
- 30 Gallon:Compact footprint suited to laboratory and pilot-scale chemical operations. Expanding most quickly in pharmaceutical manufacturing where batch sizes trend smaller.
- 110 Gallon:Intermediate volume capturing food packaging applications requiring bulk ingredient storage with manual access.
- 210 Gallon:Maximum single-drum capacity for high-density waste streams minimizing manifest documentation per ton shipped.
55 gallon configurations anchor procurement volumes; steepest expansion trajectory belongs to 30 gallon drums.
Closure Type:
Access frequency requirements separate applications into sealed containment versus routine sampling workflows.
- Closed Head:Factory-sealed integral top with bung fittings prevents vapor release. Retains dominant position in hazardous waste transport governed by DOT 49 CFR specifications.
- Open Head:Removable lid with bolt ring or lever lock closure enables drum interior access. Gaining share fastest in food packaging segments requiring ingredient addition and quality sampling.
- Tapped:Precision-machined threaded openings for controlled liquid dispensing.
- Screw Cap:Consumer-oriented closure format for retail chemical packaging.
Closed head drums retain the largest installed base; open head designs are climbing the fastest.
Application:
End-use regulatory exposure determines certification grade requirements and replacement cycle velocity.
- Hazardous Waste:EPA RCRA manifest documentation mandates UN Performance-Oriented Packaging certification. Concentrates procurement authority among integrated service providers with reverse logistics networks.
- Chemical Storage:Process intermediate containment in petrochemical and specialty chemical manufacturing. Demand clusters in Louisiana and Texas where ethylene capacity expansion drives captive drum consumption.
- Food Packaging:FDA 21 CFR compliance for direct food contact applications.
- Industrial Use:General-purpose lubricant and solvent handling outside hazardous classification thresholds.
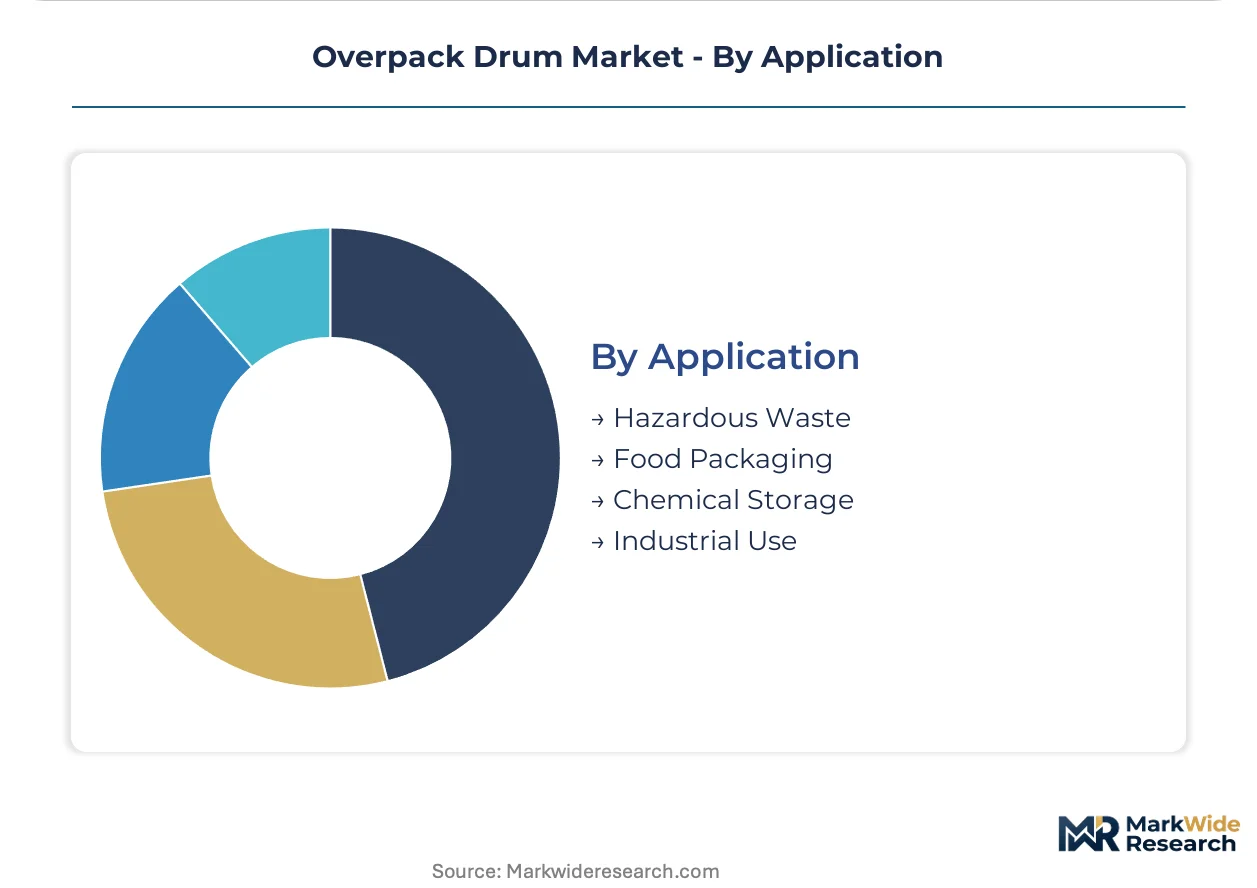
Hazardous waste applications command the largest revenue pool; chemical storage is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel fabrication concentrates in the United States and Germany where integrated mills supply cold-rolled carbon shells for UN-certified drums. Rotational molding of high-density polyethylene clusters along the Texas Gulf Coast and in the Netherlands near petrochemical feedstock sources.
United States
Gulf Coast ethylene capacity expansion around Houston and Corpus Christi generates captive demand for thermal-stable steel overpacks in high-temperature process streams. EPA Resource Conservation and Recovery Act enforcement intensifies manifest documentation requirements for hazardous waste handlers. Great Lakes industrial corridors in Ohio and Michigan face specification-upgrade pressure as RCRA compliance deadlines compress replacement cycles.
Germany
Cross-border chemical exporters in the Rhine-Ruhr region maintain certified overpack inventories to satisfy UN Model Regulations on dangerous goods transport. ECHA REACH compliance drives material traceability requirements through drum supply chains. BASF and Dow pilot deployments in Ludwigshafen demonstrate RFID-enabled fleet tracking compressing turnaround times.
Netherlands
Rotterdam petrochemical throughput generates demand for intermediate bulk container-to-overpack hybrid designs serving European export lanes. EU Packaging and Packaging Waste Directive shapes circular economy obligations for drum producers. Port of Rotterdam logistics clusters anchor closed-loop pooling system adoption among multinational chemical accounts.
China
Specialty chemical manufacturing expansion in the Yangtze River Delta drives procurement of corrosion-resistant polyethylene drums for acid handling. MIIT industrial packaging standards govern domestic certification protocols separate from UN Performance-Oriented Packaging. Ningbo and Shanghai port clusters concentrate drum fabrication capacity serving Asia-Pacific export routes.
India
Pharmaceutical manufacturing growth in Maharashtra and Gujarat expands demand for 30-gallon compact footprint drums suited to pilot-scale chemical operations. BIS certification requirements for industrial packaging create qualification barriers for imported drum suppliers. Hazira and Mundra industrial corridors attract drum leasing service providers seeking to capture recurring revenue arrangements.
Overpack Drum Market Competitive Environment
Integrated service providers and standalone fabricators split the market between recurring-revenue pooling contracts and transactional drum sales. Consolidation pressure concentrates procurement authority among operators with reverse logistics networks capable of handling recertification liability. Three archetypes dominate: closed-loop lifecycle managers, specialty hybrid designers, and regional fabrication specialists. M&A activity targets collection-and-recertification capabilities while capacity expansion focuses on Gulf Coast and Great Lakes proximity.
Among North American integrated service providers, Greif Inc. and Mauser Packaging Solutions exemplify the closed-loop archetype through lifecycle management contracts bundling provision, collection, and regulatory documentation. SCHÜTZ GmbH & Co. KGaA anchors the hybrid-design specialization serving European chemical export corridors with intermediate bulk container derivatives. These three entities represent distinct strategic responses to regulatory compression and customer preference shifts away from outright drum purchases.
| Leading Market Players |
|---|
| Greif Inc. |
| Mauser Packaging Solutions |
| SCHÜTZ GmbH & Co. KGaA |
| Berry Global |
| Eagle Manufacturing |
| ENPAC |
| The Cary Company |
| Skolnik Industries |
| Berlin Packaging |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Gulf Coast rotational-molding facilities is elevating supplier bargaining power while compressing procurement flexibility for polyethylene drum buyers. This utilization imbalance feeds directly into pricing postures, with contract manufacturers prioritizing long-term service bundling over spot transactions.
Pricing Analysis
After-sales recertification revenue now drives lifetime value more than initial drum sales. Three-tier pricing structure across certified-premium, standard-UN, and economy-non-certified levels separates hazardous waste handlers from food-grade buyers. Price differentiation hinges on UN Performance-Oriented Packaging certification grade and integrated reverse logistics inclusion. Cost compression in standard-grade polyethylene shells is intensifying because ethylene feedstock volatility erodes margin predictability. Small waste consolidators in Appalachia exhibit highest price sensitivity, whereas integrated chemical producers prioritize compliance assurance over unit economics.
Supply Chain Analysis
Contract manufacturing concentrates among Greif, Mauser, and SCHÜTZ facilities in the United States, Germany, and the Netherlands. Geographic supply concentration centers on Texas Gulf Coast ethylene derivatives, German cold-rolled steel mills, and Dutch petrochemical feedstock corridors. Raw material dependencies draw from high-density polyethylene resin, cold-rolled carbon steel coils, and synthetic gasket compounds. Supply chain risk rests on Section 232 steel tariff exposure disrupting Midwest fabrication economics. Distribution runs through closed-loop pooling networks rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Overpack drum incumbents face substitution defense against intermediate bulk container-to-overpack hybrid designs capturing European chemical export volume. IBC hybrid penetration threatens pure-play drum addressable market expansion.
For Market Incumbents: Build captive recertification moats through backward integration into collection-and-reconditioning networks. Acquire DOT-recognized laboratory capacity to compress fourteen-month UN certification timelines. Prioritize RFID-enabled fleet tracking deployment to defend against asset-light logistics competitors. Vertical integration into Gulf Coast rotational-molding capacity secures polyethylene supply continuity against ethylene volatility. For New Entrants and Emerging Players: Establish a beachhead in 30-gallon laboratory-scale drums where pharmaceutical batch downsizing creates specification gaps. Target drone-based hazmat logistics applications requiring lightweight polyethylene designs for remote industrial sites. Penetrate Great Lakes RCRA enforcement corridors where Ohio and Michigan waste handlers face disproportionate compliance burdens. Lead with per-use leasing models that offload recertification liability from capital-constrained buyers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across RFID-enabled smart drum sub-segments as sensor integration requirements proliferate. Long-term viability favors integrated service providers with reverse logistics networks over standalone fabricators. Acquisition target archetype: regional recertification specialists with EPA-compliant facilities and established chemical account relationships. Monitor DOT-recognized laboratory capacity expansion as inflection signal for new product qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Pooling Network Expansion | Captures recurring revenue from Dow and BASF multi-site hazardous waste programs. |
| RFID-Enabled Fleet Tracking Deployment | Compresses drum turnaround times through real-time location monitoring in Texas. |
| Backward Integration into Recertification | Captures margin pool from aftermarket reconditioning services in Ohio corridors. |
| Hybrid IBC-to-Overpack Design Development | Serves Rotterdam petrochemical throughput with space-efficient export configurations. |
| Bio-Based Material Certification Investment | Positions for ASTM renewable-content standards emerging in European circular economy frameworks. |
Study Parameters
The analysis maps polyethylene drum, steel drum, and hybrid IBC-to-overpack sub-sectors, each validated through plant managers, procurement leads at chemical manufacturers, distribution channel partners, and technical R&D directors. Primary interviews with hazardous waste handlers and closed-loop service operators combined with secondary validation from EPA e-Manifest filings, DOT 49 CFR dockets, customs/trade data, and SEC 10-K disclosures. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates across material specifications and closure configurations.
Assumptions held fixed include EPA RCRA enforcement intensity and UN Model Regulation certification requirements, while ethylene feedstock pricing and steel tariff trajectories were varied across scenarios. Segmentation dimensions modeled encompass material substrate, capacity tier, closure type, and application regulatory exposure throughout the forecast period. CAGRs derived from replacement cycle compression analysis and captive demand from Gulf Coast ethylene capacity expansion. Industry-specific inputs incorporated DOT-recognized laboratory bottleneck durations and RFID adoption curves from Dow and BASF pilot deployments.
Sensitivities concentrate around ethylene price volatility, Section 232 steel tariff adjustments, and UN certification timeline extensions. Forecasts reflect documented assumptions on regulatory enforcement trajectories and petrochemical capacity commissioning schedules. Quarterly review of EPA rulemaking dockets and DOT laboratory capacity indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Middle East and Africa Octabin Market
Industrial Packaging
Fiber Drums Market
Industrial Packaging
Insulated Bin Market
Industrial Packaging
MENA Industrial Packaging Market
Industrial Packaging
Nestable Drums Market
Industrial Packaging
Bulk Liquid Transport Packaging Market
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Transport Racks Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Corrugated Automotive Packaging Market
Industrial Packaging
Industrial Chemical Packaging Market
Industrial Packaging
Corrugated Bulk Bins Market
Industrial Packaging
Cone Bottom Tank Market
Industrial Packaging
Industrial Bulk Packaging Market
Industrial Packaging
Dunnage Air Bags Market