
 Industrial Packaging Market | 2026-2036
Industrial Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Packaging Market Intelligence
Modular IBC systems and collapsible pallet configurations is restructuring how bulk chemical buyers evaluate total cost of ownership against single-use alternatives. Greif Inc. anchors North American drum and IBC production through captive steel and plastic manufacturing. Mondi plc differentiates via integrated kraft paper and corrugated solutions for agricultural and chemical shippers. Schütz GmbH & Co. KGaA dominates European reusable container pooling with closed-loop logistics networks.
Industrial packaging encompasses engineered containment systems designed to transport and store bulk materials, typically handling weights from 250 kg to over 1,000 kg per unit, with specifications governed by UN certification for hazardous goods and ISO 16106 for transport packaging. Its primary purpose is to protect product integrity across multimodal supply chains while enabling efficient mechanical handling. Fiberboard and composite materials are capturing margin pools as brand owners seek lightweight alternatives to steel drums for non-hazardous chemicals. Plastic containers lead volume in food-grade and pharmaceutical applications due to inert surface properties and blow-molding scalability. Metal drums remain entrenched in solvent and coating segments where UN-rated containment is mandatory.
EPA hazardous waste manifest requirements and OSHA drum labeling standards shape product design and testing protocols for US-manufactured containers. REACH substance restrictions and EU Packaging and Packaging Waste Directive recyclability targets are redirecting R&D spend toward biodegradable substrates and post-consumer resin integration. Stakeholders must monitor how extended producer responsibility frameworks in multiple jurisdictions alter cost allocation between packaging producers and their industrial customers.
Market Dynamics
EU F-Gas Regulation and REACH substance restrictions are forcing converters to abandon fluorinated polymer linings and steel drums for fiberboard composite alternatives, compressing material certification timelines and restructuring supplier qualification protocols across chemical and agricultural supply chains.
Growth Catalysts
- REACH substance restrictions:Chemical manufacturers in Germany and France are accelerating fiberboard IBC adoption to eliminate SVHC compliance exposure. This redirects R&D spend toward biodegradable substrates.
- Reusable IBC pooling networks:Closed-loop logistics systems for intermediate bulk containers are cutting per-trip packaging costs for agrochemical shippers. Pooling operators are expanding fleet coverage across Benelux chemical corridors.
- China's dual carbon goals:MIIT guidelines are pressuring domestic steel drum producers to source recycled content. This creates specification pull for lightweight composite alternatives in solvent distribution.
Market Restraints
- Resin input cost volatility:Blow-molding grade polyethylene prices fluctuate with naphtha feedstock indices. Container producers lack pricing power to pass through raw material swings.
- UN certification bottlenecks:Transport testing for hazardous goods packaging faces extended queue times at accredited laboratories. New product launches stall awaiting 6A/6B test reports.
- Steel drum substitution limits:Solvent and coating segments retain metal containment for UN-rated flammability compliance. Fiberboard alternatives fail penetration in these specifications.
Strategic Opportunities
- Indian agrochemical export growth:DGFT export incentives are expanding bulk pesticide shipment volumes. Domestic IBC producers can capture specification-setting roles with multinational formulators.
- Pharmaceutical cold-chain convergence:Insulated IBC systems combined with real-time temperature logging address biologics distribution. This opens premium containment tiers beyond commodity chemical packaging.
- EU Packaging and Packaging Waste Directive recyclability targets:Post-consumer resin integration mandates are creating first-mover advantage for converters with verified recycling partnerships.
Industry Challenges
- UN 6A/6B certification talent scarcity:Qualified packaging engineers capable of designing test protocols for hazardous goods containment are concentrated at a handful of accredited consultancies. Hiring timelines extend project schedules.
- Legacy ERP integration with pooling platforms:Chemical shippers operating on-premise inventory systems face friction connecting to reusable container tracking networks. API standardization lags across logistics software vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Packaging Market |
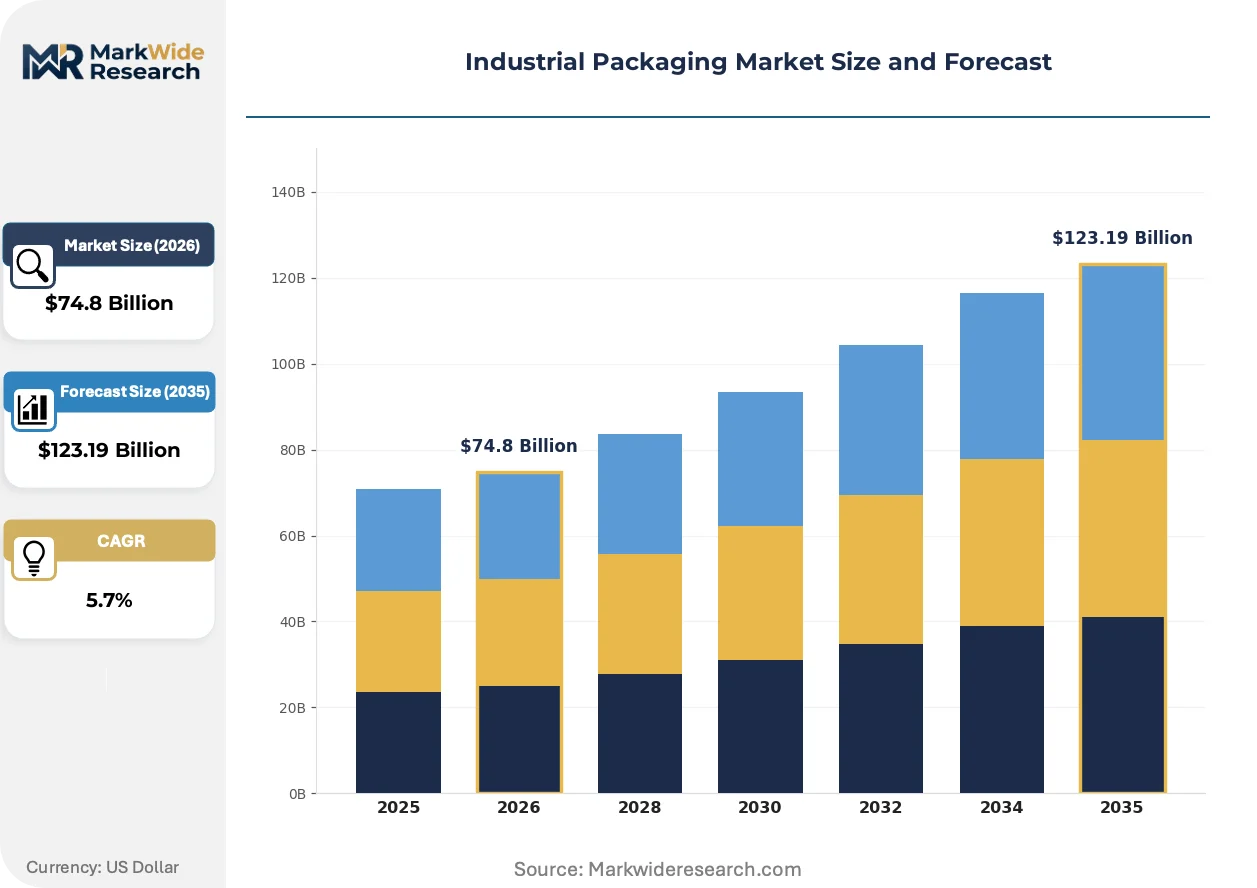
| Market Size in 2026 | $74.8 Billion |
| Market Size in 2035 | $123.19 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Metal, Glass, Fiberboard, Composite, Biodegradable Packaging Type: Drums, Bags, Boxes, Pallets, Containers, Canisters End Use Industry: Chemicals, Food & Beverage, Pharmaceuticals, Agriculture, Electronics, Textiles Distribution Channel: Wholesale, Direct Sales, E-commerce, Retail Outlets, Distributors, Industrial Suppliers |
| Companies Covered | Greif Inc., Mondi plc, WestRock Company, Amcor plc, International Paper Company, Mauser Packaging Solutions, DS Smith plc, Smurfit Kappa, Schütz GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Packaging Market Strategic Shifts & Innovations
Material science advances and regulatory pressure on circularity metrics are compressing development cycles for next-generation containment systems. Three developments are restructuring competitive positioning.
Collapsible composite IBC designs with integrated RFID tracking are modularizing fleet management for chemical distributors. Agrochemical formulators in the US Midwest are piloting these systems for seasonal demand spikes. The technology is modularizing how buyers calculate total cost of ownership against fixed steel drum fleets.
EPA hazardous waste manifest digitization requirements are mandating container-level traceability for US-manufactured drums. This is accelerating barcode and QR integration into drum sidewall specifications. Solvent producers in Texas and Louisiana are absorbing the compliance cost into premium drum tiers.
Buyers are consolidating vendor relationships around integrated packaging-plus-logistics contracts. Third-party pooling operators are displacing owned-container fleets for mid-size chemical shippers. This pattern is most visible in German chemical clusters where Schütz and competitors operate dense service networks.
Industrial Packaging Market Segmentation
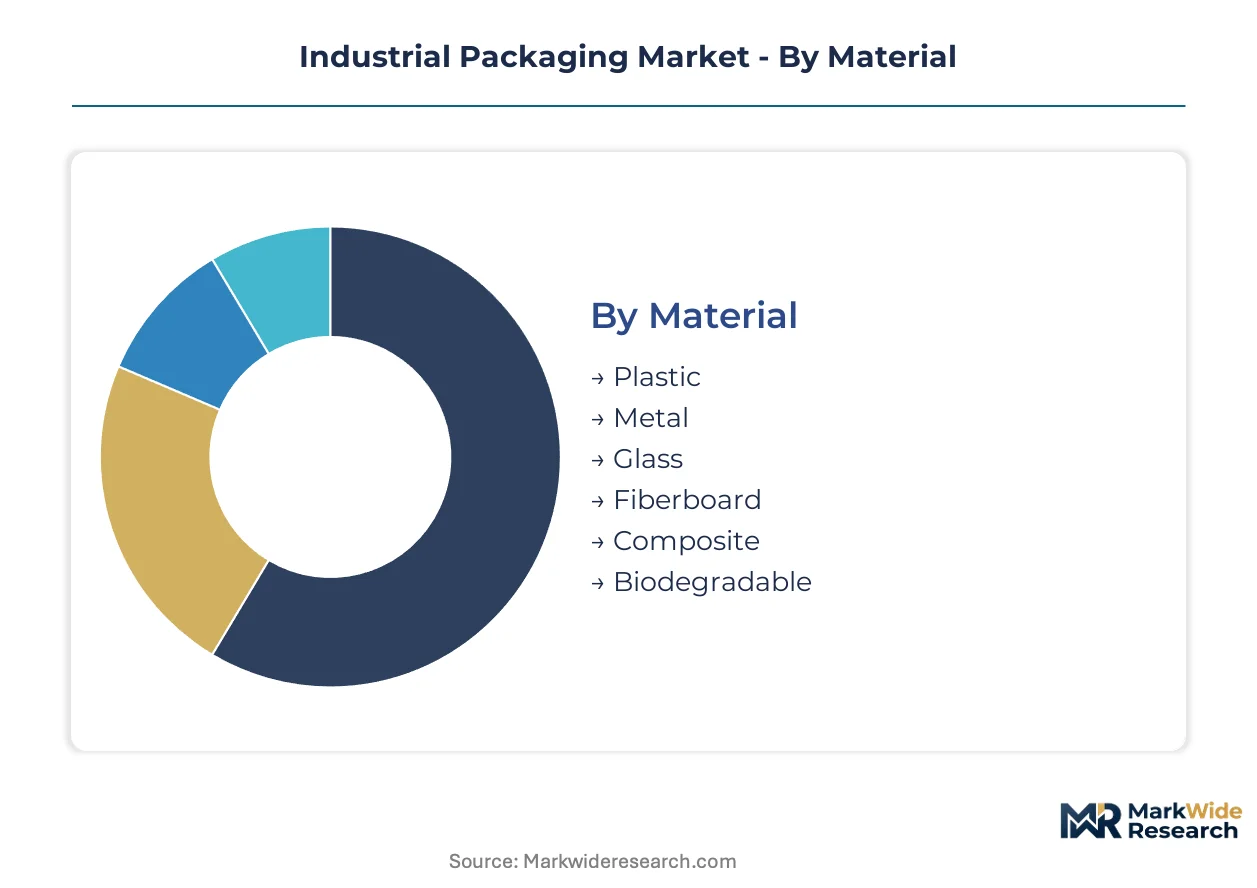
Industrial packaging buyers segment procurement decisions by containment performance, total cost of ownership, and regulatory compliance pathways. Material selection and packaging format choices cascade through supply chain configurations, determining qualification timelines and logistics partnerships.
Material:
Supply concentration in steel and resin production shapes converter sourcing strategies and margin structures across containment categories.
- Plastic:Blow-molded polyethylene and polypropylene containers dominate food-grade and pharmaceutical applications due to inert surface properties and scalable manufacturing. Demand concentrates in pharmaceutical distribution across Germany and the United States, driven by FDA and EMA purity requirements for active pharmaceutical ingredient containment.
- Metal:Cold-rolled steel drums provide UN-rated containment for solvents, coatings, and flammable chemicals where structural integrity under pressure is mandatory. Chemical manufacturers in Texas and Louisiana retain steel specifications for hazardous waste manifest compliance under EPA protocols.
- Glass:Borosilicate and soda-lime containers serve high-purity chemical and pharmaceutical segments requiring inert barrier properties and visual inspection capability.
- Fiberboard:Kraft paper-based IBCs and corrugated drums capture lightweight chemical shipments where UN certification permits non-metallic containment.
- Composite:Multi-layer fiberboard-plastic hybrid designs merge structural rigidity with chemical resistance for agrochemical distribution.
- Biodegradable:Starch-based and mycelium-derived substrates address EU Packaging and Packaging Waste Directive recyclability mandates for non-hazardous bulk goods.
Today's leader: Metal. Tomorrow's challenger: Fiberboard.
Packaging Type:
Cost tier differentiation separates commodity containment from engineered systems with integrated tracking and pooling capabilities.
- Drums:Cylindrical steel, plastic, or fiberboard containers ranging from 55 to 110 gallons remain the baseline format for chemical and coating distribution. Standardized drum dimensions enable mechanical handling compatibility across multimodal networks.
- Containers:Intermediate bulk containers with capacities of 275 to 330 gallons command premium positioning through reusable pooling networks and RFID-enabled fleet management. Agrochemical formulators in the US Midwest pilot collapsible composite IBCs for seasonal demand spikes.
- Bags:Flexible intermediate bulk containers and valve sacks handle powder and granular materials in agricultural and chemical processing.
- Boxes:Corrugated bulk bins and gaylord containers serve non-hazardous dry goods with stackable warehouse efficiency.
- Pallets:Pallet-based containment systems integrate base platforms with sidewall structures for unitized shipment of bagged or boxed goods.
- Canisters:Small-format metal and composite canisters address specialty chemical and pharmaceutical sampling requirements.
Containers are climbing the fastest as pooling economics displace owned-fleet depreciation.
End Use Industry:
Application-specific performance requirements fragment procurement specifications across containment categories and certification tiers.
- Chemicals:Solvents, coatings, and specialty chemicals drive the largest volume demand for UN-certified drums and IBCs with corrosion-resistant linings. REACH substance restrictions in Germany and France accelerate fiberboard adoption to eliminate SVHC compliance exposure.
- Pharmaceuticals:Cold-chain biologics distribution creates premium demand for insulated IBCs with real-time temperature logging and validated containment protocols.
- Food & Beverage:Food-grade plastic containers and aseptic bag-in-box systems address bulk ingredient transport with FDA and EFSA surface contact compliance.
- Agriculture:Pesticide and fertilizer formulators specify reusable IBC pooling to cut per-trip packaging costs across seasonal distribution cycles.
- Electronics:Moisture-barrier packaging and electrostatic discharge protection requirements govern semiconductor and component containment specifications.
- Textiles:Bulk fiber and dye chemical shipments utilize flexible intermediate bulk containers with breathable or sealed construction.
Today's leader: Chemicals. Tomorrow's challenger: Pharmaceuticals.
Distribution Channel:
Customer type and order scale determine channel selection between direct converter relationships and intermediated procurement.
- Direct Sales:Large chemical and pharmaceutical manufacturers negotiate multi-year supply agreements with drum and IBC converters for captive production capacity and custom specifications. Direct relationships dominate in German chemical clusters where Schütz and competitors operate dense service networks.
- Distributors:Regional packaging distributors aggregate demand from mid-size chemical shippers and provide inventory buffering for standard drum sizes. Distributor networks capture specification-setting roles with multinational formulators in India's expanding agrochemical export sector.
- Wholesale:Volume-based procurement cooperatives serve smaller chemical processors with standardized container specifications.
- E-commerce:Digital procurement platforms emerge for standardized drum and container specifications with transparent pricing and rapid fulfillment.
- Retail Outlets:Limited presence for small-format industrial packaging through trade supply stores serving maintenance and repair operations.
- Industrial Suppliers:Integrated MRO distributors bundle packaging procurement with broader industrial supply contracts.
Direct sales hold volume concentration. Distributors are gaining specification influence with mid-market shippers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial packaging industry traces its modern scale to German engineering traditions and post-war chemical sector expansion, with contemporary production gravity shifting toward Asian manufacturing corridors and North American shale-derived chemical feedstock regions.
Germany
REACH substance restrictions and SVHC compliance protocols are accelerating fiberboard IBC adoption among chemical manufacturers in the Rhine-Ruhr industrial belt. The EU F-Gas Regulation is eliminating fluorinated polymer linings from container specifications. Schütz GmbH operates dense reusable container pooling networks across North Rhine-Westphalia and Bavaria, serving agrochemical formulators with closed-loop logistics.
China
MIIT dual carbon guidelines are pressuring domestic steel drum producers to source recycled content and reduce carbon intensity in production. The Yangtze River Delta manufacturing cluster is consolidating specification-setting roles for composite IBC alternatives in solvent distribution. Chemical producers in Jiangsu and Zhejiang provinces are piloting lightweight fiberboard containment for non-hazardous bulk shipments.
United States
EPA hazardous waste manifest digitization requirements are mandating container-level traceability for drum manufacturers serving Texas and Louisiana petrochemical corridors. OSHA drum labeling standards shape product design protocols for solvent and coating segments. The Gulf Coast chemical cluster retains steel drum specifications for UN-rated flammability compliance where fiberboard alternatives fail penetration.
India
DGFT export incentives are expanding bulk pesticide shipment volumes from Gujarat and Maharashtra agrochemical manufacturing zones. Domestic IBC producers are capturing specification-setting roles with multinational formulators establishing regional distribution hubs. The Mumbai-Pune industrial corridor is emerging as a conversion point for reusable container pooling networks serving seasonal agricultural demand cycles.
France
ANSM pharmaceutical containment standards and EMA purity requirements are driving demand for blow-molded polyethylene containers in active pharmaceutical ingredient distribution. The EU Packaging and Packaging Waste Directive recyclability targets are redirecting converter R&D spend toward post-consumer resin integration. Lyon and Paris basin chemical clusters are consolidating procurement around integrated packaging-plus-logistics contracts with third-party pooling operators.
Industrial Packaging Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-tier and pooling-capability dimensions. The vendor base organizes into three strata: integrated steel and plastic converters with captive raw material sourcing, fiberboard specialists with kraft paper integration, and pooling operators with logistics network density. Consolidation pressure concentrates among mid-scale drum fabricators lacking UN certification in-house testing capabilities. Strategic moves center on backward integration into resin and steel production, plus geographic expansion of reusable container service networks.
Within the integrated converter tier, Greif Inc. and Mondi plc exemplify divergent material strategies—Greif anchoring North American metal and plastic containment through captive manufacturing infrastructure, Mondi differentiating via European kraft paper and corrugated integration for agricultural and chemical shippers. Schütz GmbH & Co. KGaA occupies a distinct position as a pooling-network specialist, representing the logistics-integrated archetype that is displacing owned-container fleets among mid-size chemical shippers. These three companies illustrate how competitive positioning fragments across material verticalization, geographic anchoring, and service model differentiation.
| Leading Market Players |
|---|
| Greif Inc. |
| Mondi plc |
| WestRock Company |
| Amcor plc |
| International Paper Company |
| Mauser Packaging Solutions |
| DS Smith plc |
| Smurfit Kappa |
| Schütz GmbH & Co. KGaA |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up drum fabricators now dominate mid-cap production tiers across North America and Europe, compressing working capital cycles and enforcing rigid price discipline on resin and steel input contracts. This ownership pattern concentrates purchasing power among fewer buyers while fragmenting seller leverage across scattered metalworking and blow-molding specialists.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates UN-certified hazardous goods containment from food-grade specifications and commodity drum tiers. Price differentiation rests on certification grade and volume scale, with pharmaceutical buyers absorbing premium positioning for EMA and FDA compliance tiers. Cost compression in standard-grade steel drums is intensifying because naphtha-indexed polyethylene volatility erodes converter margins. Agrochemical distributors in India and Brazil exhibit highest price sensitivity, while pharmaceutical cold-chain operators show least elasticity due to validated containment requirements.
Supply Chain Analysis
Refurbishment and remanufacturing flows for reusable IBCs now constitute a parallel supply channel, with Schütz and competitors operating dedicated reconditioning facilities across Germany, the Netherlands, and Belgium. Raw material sourcing draws from Chinese steel production, US Gulf Coast resin complexes, and Nordic kraft pulp mills. Single-source vulnerability concentrates in blow-molding grade polyethylene feedstock, where naphtha cracker outages in South Korea and Singapore cascade through global pricing. Distribution runs through converter-direct relationships for large chemical manufacturers and regional distributor networks for mid-tier agrochemical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in industrial packaging rests on pooling economics displacing owned-fleet depreciation, with reusable IBC networks capturing premium positioning against single-use drum alternatives.
For Market Incumbents: Cement control over closed-loop logistics networks in chemical corridor density zones, particularly Rhine-Ruhr and US Midwest agrochemical hubs. Expand captive steel and plastic production capacity to offset resin input cost volatility. Invest in UN 6A/6B certification testing capabilities in-house to compress new product launch timelines against competitors dependent on third-party laboratory queues.
For New Entrants and Emerging Players: Enter via pharmaceutical cold-chain containment tiers where insulated IBC systems with real-time temperature logging command premium positioning beyond commodity chemical specifications. Target Indian agrochemical export corridors where DGFT incentives expand bulk pesticide shipment volumes and domestic producers can capture specification-setting roles with multinational formulators. Pursue joint development agreements with biologics distributors seeking validated containment protocols.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale drum fabricators lacking in-house UN certification testing capabilities and stranded without pooling network assets. Long-term viability favors converters with verified post-consumer resin recycling partnerships aligned to EU Packaging and Packaging Waste Directive mandates. Monitor MIIT dual carbon guideline enforcement in China as inflection indicator for composite IBC substitution acceleration in solvent distribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Resin Production | Insulates margin structures from naphtha feedstock index volatility affecting polyethylene container costs. |
| Expansion of Reusable IBC Pooling Networks | Schütz and competitors displace owned-container fleets through closed-loop logistics density in Benelux chemical corridors. |
| Post-Consumer Resin Integration Programs | Converters with verified recycling partnerships capture first-mover advantage under EU recyclability mandates. |
| Pharmaceutical Cold-Chain Containment Development | Insulated IBC systems with temperature logging address biologics distribution premium tiers beyond commodity chemicals. |
| UN Certification Testing Capacity Expansion | In-house 6A/6B testing capabilities compress product launch timelines against competitors facing laboratory queue bottlenecks. |
Research Approach
Coverage spans Germany, China, the United States, India, and France, with primary inputs from each market gathered through structured interviews with plant managers at drum and IBC converters, procurement leads at downstream chemical manufacturers, distribution channel partners in agrochemical corridors, and technical R&D directors at fiberboard specialists. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA hazardous waste manifest databases. Bottom-up and top-down triangulation reconciled production capacity estimates with end-use demand segmentation.
Rate-of-change decomposition across the analysis window modeled volume and value trajectories through segmentation by material type, packaging format, end-use industry vertical, and regional production hub. CAGRs were derived from trend extrapolation of historical shipment data adjusted for regulatory inflection points including REACH substance restrictions and EU F-Gas Regulation phase-outs. Industry-specific forecast inputs incorporated MIIT dual carbon guideline enforcement patterns and DGFT export incentive utilization rates.
Inputs from converter production databases and trade association statistics were available through the study window; gaps in real-time pooling fleet utilization metrics introduce uncertainty bands around reusable IBC penetration forecasts. Practitioners should monitor EPA hazardous waste manifest digitization rollout progress and ECHA SVHC candidate list expansion for early signals of fiberboard substitution acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Anti-Static Reel Racks Market
Industrial Packaging
Transport Racks Market
Industrial Packaging
Global Industrial Wooden Crates Market
Industrial Packaging
Industrial Chemical Packaging Market
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Slip Sheets Market
Industrial Packaging
Bulk Liquid Transport Packaging Market
Industrial Packaging
Corrugated Octabins Market
Industrial Packaging
Industrial Pails Market
Industrial Packaging
Dunnage Racks Market
Industrial Packaging
Middle East and Africa Octabin Market
Industrial Packaging
Nestable Drums Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Corrugated Automotive Packaging Market