
 Cone Bottom Tank Market | 2026-2036
Cone Bottom Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Cone Bottom Tank Market Analytics
The cone bottom tank market is pivoting on a widening split between engineered polyethylene systems for chemical resistance and commodity carbon steel vessels for bulk agricultural and water applications. CST Industries Inc. leverages its vertically integrated fabrication network to dominate large-capacity industrial contracts across North American refineries. Synalloy Corporation anchors its position through specialized stainless steel alloy formulations that meet pharmaceutical-grade surface finish requirements. Poly Processing Company LLC differentiates via proprietary cross-linked polyethylene rotomolding technology that extends service life in aggressive chemical environments.
A cone bottom tank is a cylindrical storage vessel with a conical lower section engineered for complete drainage of viscous liquids, slurries, or settled solids, typically manufactured through rotational molding, welded fabrication, or filament winding with wall thicknesses calibrated to specific specific gravity ratings. The conical slope, generally set between 30 and 60 degrees depending on material flow characteristics, enables gravity-induced evacuation without mechanical agitation, reducing contamination risk in batch pharmaceutical processes and food-grade syrup handling. Polyethylene tanks lead the product type landscape due to cost efficiency and chemical inertness, while stainless steel commands premium margins in pharmaceutical and high-purity chemical installations where surface roughness standards apply. Above-ground installations dominate capacity categories below 5,000 gallons, whereas underground configurations concentrate in the above-5,000-gallon segment where space constraints and secondary containment mandates drive specification complexity.
The EPA enforces 40 CFR 112 Spill Prevention, Control, and Countermeasure rules that mandate impermeable barriers and periodic integrity testing for cone bottom tanks storing oil or hazardous substances above threshold volumes. OSHA's Process Safety Management standards impose mechanical integrity programs on chemical storage vessels, directly influencing inspection frequency and replacement cycles for carbon steel and fiberglass installations. ASTM D1998 and NSF/ANSI 61 certifications govern polyethylene tank resin specifications and potable water contact safety, creating compliance gateways that filter non-certified suppliers from municipal procurement pools. Stakeholders must monitor evolving state-level PFAS restrictions, as these compound bans are forcing material scientists to validate alternative liner systems for legacy fiberglass and coated steel tanks previously specified for fluorochemical processing.
Market Dynamics
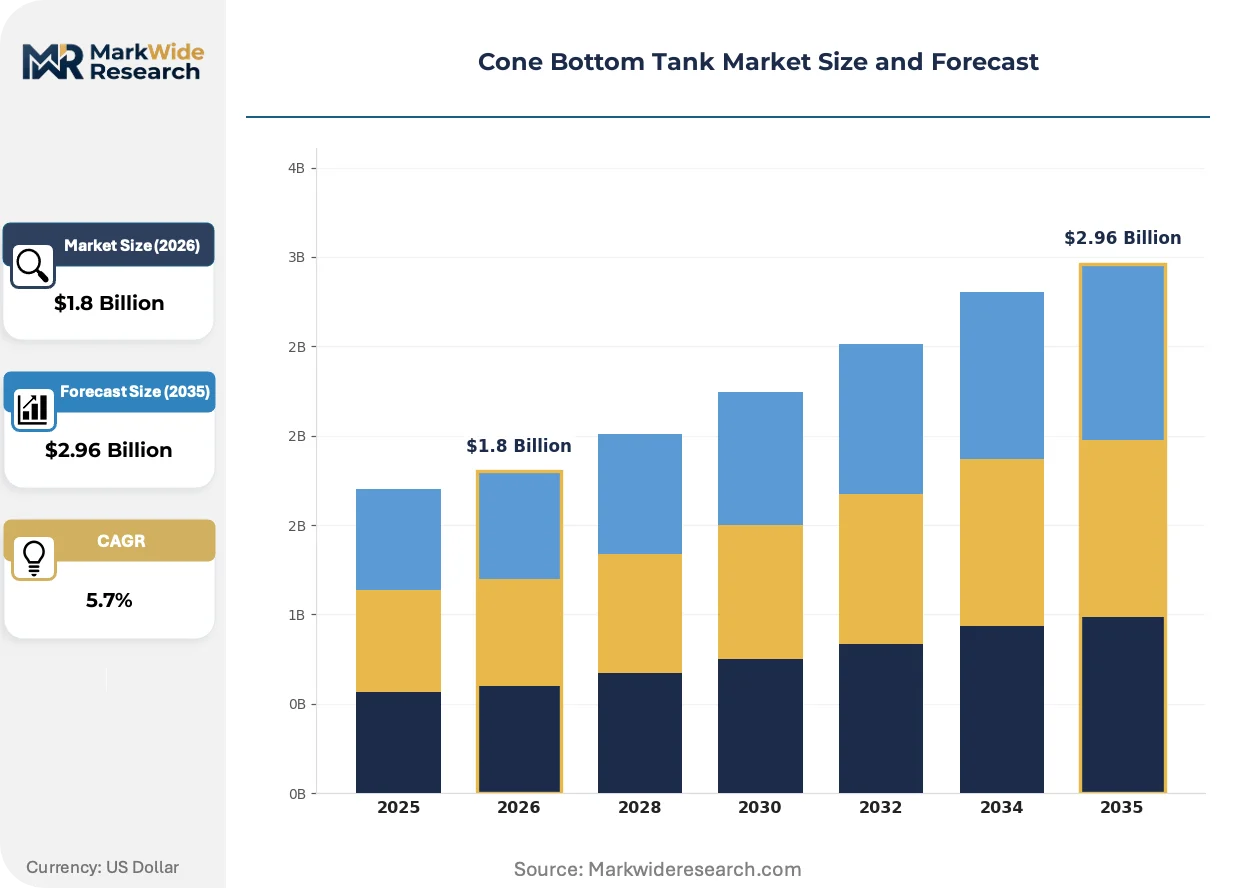
The cone bottom tank market pivots on EPA 40 CFR 112 secondary containment mandates that are forcing replacement cycles for legacy carbon steel vessels across US petrochemical corridors. Material certification requirements are tightening faster than fabrication capacity can adapt, creating supply bottlenecks for NSF/ANSI 61-compliant polyethylene systems.
Growth Catalysts
- EPA Spill Prevention Mandates:Updated 40 CFR 112 rules require impermeable barriers and periodic integrity testing for oil storage vessels, accelerating replacement demand across Texas Gulf Coast refineries.
- Water Treatment Expansion:Municipal utilities in California are expanding procurement of corrosion-resistant cone bottom tanks specifically engineered for sludge removal and complete drainage applications.
- Cross-Linked Polyethylene Rotomolding:Proprietary XLPE manufacturing processes extend service life in aggressive chemical environments, displacing fiberglass in fluorochemical processing applications.
Market Restraints
- Resin Price Volatility:Polyethylene feedstock costs fluctuate with crude oil indices, compressing margins for rotational molders serving agricultural bulk storage segments.
- Fabrication Concentration:Large-capacity welded steel vessel production concentrates among vertically integrated fabricators with captive plate rolling capacity, limiting new entrant participation.
- PFAS Compound Bans:State-level restrictions on fluorochemicals are forcing material scientists to validate alternative liner systems for legacy coated steel tanks.
Strategic Opportunities
- Pharmaceutical-Grade Surface Finishes:Specialized stainless steel alloy formulations meeting ASME BPE surface roughness standards command premium margins in biologics manufacturing.
- Underground Configuration Growth:Space constraints and secondary containment mandates in urban water districts are driving specification complexity for above-5,000-gallon buried installations.
- EU Green Deal Alignment:REACH-compliant recycled polyethylene resins open procurement pathways for European municipal water utilities with circular economy mandates.
Industry Challenges
- Welder Certification Bottlenecks:ASME Section IX qualified welders for pressure-rated stainless steel fabrication remain scarce relative to project backlog in North American refinery expansions.
- Multi-Standard Compliance Timelines:Simultaneous NSF/ANSI 61 potable water certification and ASTM D1998 chemical resistance validation extend product development cycles for polyethylene tank manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cone Bottom Tank Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Stainless Steel, Carbon Steel, Fiberglass End User: Food & Beverage, Chemicals, Pharmaceuticals, Water Treatment Installation: On-site, Off-site, Above Ground, Underground Capacity: Less than 500 Gallons, 500-1000 Gallons, 1000-5000 Gallons, Above 5000 Gallons |
| Companies Covered | CST Industries Inc., Synalloy Corporation, Containment Solutions Inc., Poly Processing Company LLC, Snyder Industries Inc., U.S. Plastic Corp., Sherman Roto Tank, Roto Dynamics Inc., Wagner Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cone Bottom Tank Market Evolving Landscape
Digital fabrication technologies and advanced polymer formulations are compressing lead times while extending operational lifespans in aggressive chemical environments. Three developments are restructuring competitive positioning.
Cross-linked polyethylene rotomolding is converging with IoT-enabled level monitoring systems to create smart chemical storage vessels that predict maintenance intervals. Pharmaceutical manufacturers are adopting these integrated systems fastest, replacing legacy carbon steel tanks that require manual inspection protocols. The convergence is compressing service contract margins for traditional tank fabricators while opening recurring revenue streams for technology-integrated suppliers.
REACH substance restrictions are forcing reformulation of fiberglass resin systems used in European chemical processing installations. ECHA's expanded candidate list of SVHCs now covers several legacy gelcoat chemistries, compelling tank manufacturers to validate epoxy vinyl ester alternatives. German and Dutch chemical processors are responding by consolidating procurement around suppliers with demonstrated EU-compliant material traceability.
Lifecycle service contracts are displacing capital purchase models among municipal water utilities with constrained maintenance budgets. California and Texas districts now specify ten-year operational guarantees encompassing tank integrity, liner replacement, and regulatory compliance documentation. This shift concentrates vendor selection around fabricators with regional service infrastructure rather than lowest capital cost.
Cone Bottom Tank Market Segmentation
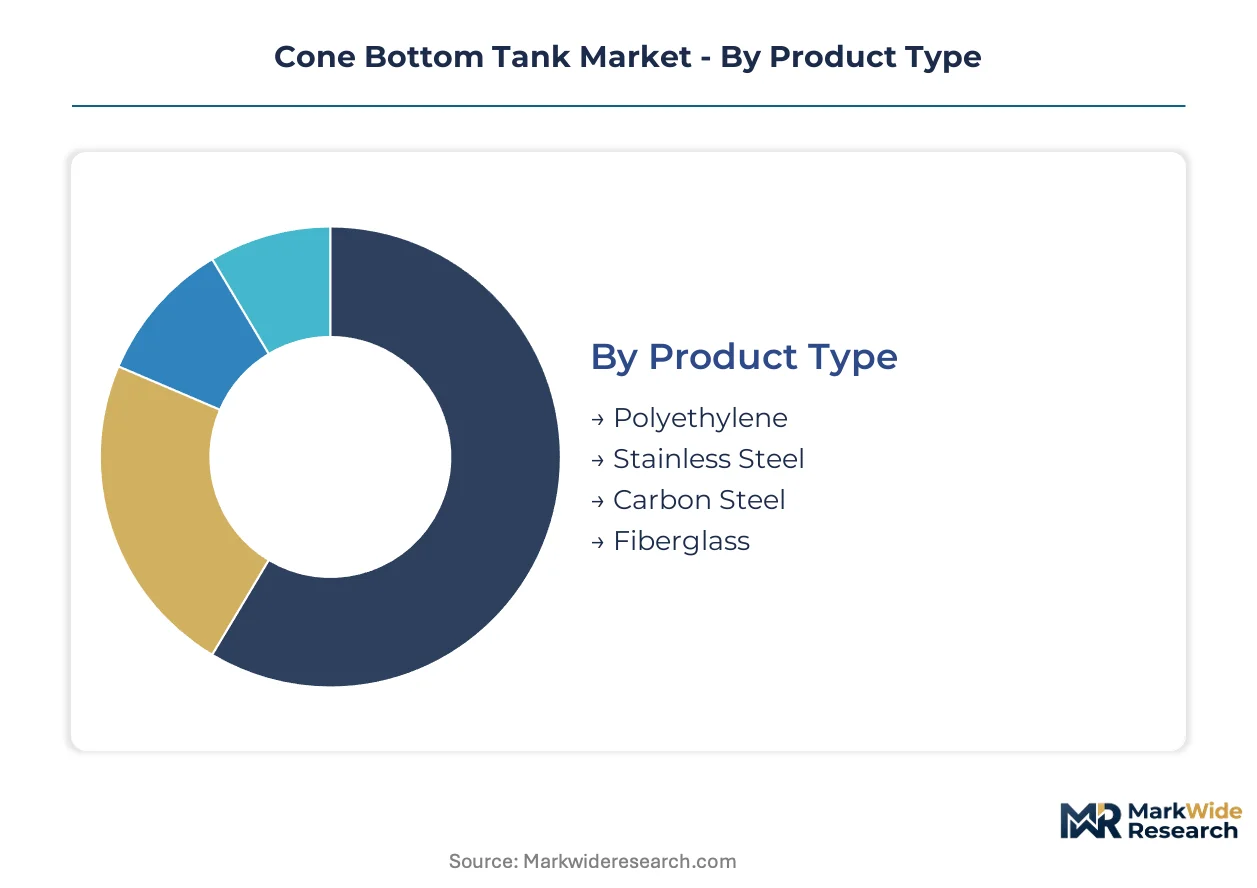
Cone bottom tank procurement splits sharply between standardized polyethylene vessels for agricultural bulk storage and engineered stainless steel systems for pharmaceutical surface finish compliance. Specification complexity escalates with capacity thresholds and secondary containment mandates.
Product Type:
Customization intensity spans from commodity rotomolded polyethylene to alloy-specific welded fabrications with certified surface roughness profiles.
- Polyethylene:Rotomolded high-density polyethylene with cross-linked variants delivers chemical inertness at the lowest capital cost point. Demand concentrates in California municipal water districts procuring NSF/ANSI 61-certified systems for potable water contact, driven by EPA secondary containment deadlines for legacy tank replacement.
- Stainless Steel:ASME BPE-compliant welded fabrications with Ra 0.8 μm surface finishes serve biologics manufacturing. Texas Gulf Coast petrochemical corridors specify these for corrosive chemical storage where fiberglass degradation risks exceed alloy premiums.
- Carbon Steel:Welded plate constructions dominate agricultural fertilizer and fuel oil storage with epoxy or polyurethane lining systems.
- Fiberglass:Filament-wound epoxy vinyl ester vessels persist in chlorine and sodium hypochlorite applications despite REACH-driven resin reformulation costs.
Leading the category by volume: Polyethylene. Growing fastest: Stainless steel.
End User:
Application-specific certification requirements create tiered margin structures across regulated and unregulated demand pools.
- Chemicals:Aggressive fluid compatibility drives specification toward XLPE and fiberglass with corrosion-resistant gelcoats. Gulf Coast refineries and fluorochemical processors in Texas anchor procurement volumes.
- Water Treatment:Municipal utilities prioritize complete drainage geometry for sludge removal and NSF/ANSI 61 potable water certification. California districts represent concentrated demand.
- Pharmaceuticals:ASME BPE surface finish standards and 3-A Sanitary Standards compliance command premium pricing for bioreactor feedstock storage.
- Food & Beverage:FDA 21 CFR 175.300 indirect food contact compliance governs syrup, edible oil, and wine fermentation tank specifications.
Volume leadership sits with Chemicals. Steepest expansion trajectory belongs to Pharmaceuticals.
Installation:
Site preparation costs and regulatory jurisdiction determine the split between factory-delivered and field-erected configurations.
- Above Ground:Dominates sub-5,000-gallon capacities with minimal civil engineering requirements and accessible inspection protocols.
- Underground:Space-constrained urban water districts specify these for above-5,000-gallon installations with double-wall containment and leak detection systems.
- On-site:Field-welded or bolted assemblies serve remote locations where transport economics prohibit factory delivery of large-diameter vessels.
- Off-site:Factory-controlled fabrication quality reduces inspection failures for pharmaceutical and high-purity chemical applications.
Above ground configurations dominate unit shipments. Underground installations gain share fastest in municipal procurement.
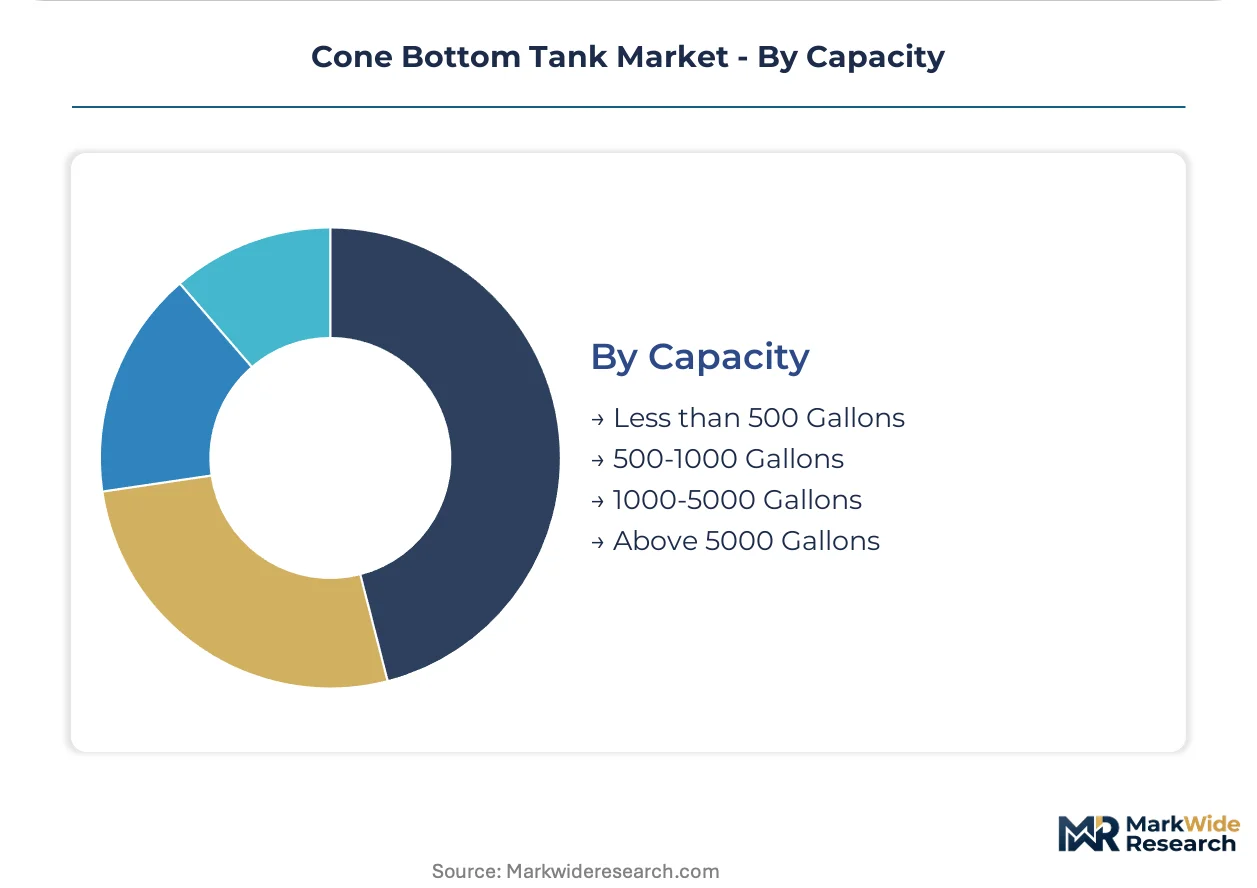
Capacity:
Fabrication method and material thickness scale nonlinearly with volume, creating distinct competitive dynamics at each threshold.
- 1000-5000 Gallons:Rotomolded polyethylene achieves maximum economies of scale in this range, with standardized molds and minimal wall thickness variation. Agricultural cooperatives and small municipal utilities drive replacement cycles.
- Above 5000 Gallons:Welded steel fabrication becomes cost-competitive as rotational molding hits dimensional limits. Petrochemical terminals and bulk chemical distributors specify these with custom cone angles for viscous fluid evacuation.
- 500-1000 Gallons:Compact footprints serve pilot-scale pharmaceutical manufacturing and specialty chemical batch processing.
- Less than 500 Gallons:Laboratory and pilot-plant applications favor portable polyethylene vessels with forklift pockets and minimal foundation requirements.
1000-5000 gallons represents the volume anchor. Above 5000 gallons climbs the fastest as refinery expansion projects backlog.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas Gulf Coast petrochemical corridor anchors procurement intensity for cone bottom tanks, with Corpus Christi and Houston refineries driving replacement cycles under tightened EPA secondary containment deadlines.
United States
California municipal water districts and Texas Gulf Coast refineries dominate procurement volumes. EPA 40 CFR 112 mandates accelerate replacement of legacy carbon steel vessels. The Permian Basin chemical terminals specify above-5,000-gallon welded fabrications with custom cone angles for viscous fluid evacuation.
Germany
REACH-compliant recycled polyethylene resins open procurement pathways for municipal utilities with circular economy mandates. ECHA's expanded SVHC candidate list forces reformulation of legacy fiberglass resin systems. The Rhine-Ruhr chemical processing belt consolidates procurement around suppliers with demonstrated EU-compliant material traceability.
China
Dual carbon goals and GB standards compliance reshape material specifications for industrial chemical storage. The Yangtze River Delta petrochemical cluster drives demand for corrosion-resistant vessels in fluorochemical processing applications. Shanghai-area fabricators face pressure to validate alternative liner systems amid tightening environmental enforcement.
India
BIS certification requirements and state-level water infrastructure programs expand municipal procurement pools. The Gujarat chemical belt and Maharashtra industrial corridors specify NSF/ANSI 61-compliant systems for potable water contact. Mumbai metropolitan utilities prioritize complete drainage geometry for sludge removal applications.
Canada
Health Canada and PMRA regulations govern chemical storage vessel specifications for agricultural and pharmaceutical applications. Alberta oil sands operations and Ontario chemical processors drive demand for double-wall containment systems. The Sarnia-Lambton petrochemical corridor specifies ASME-compliant fabrications for corrosive chemical handling.
Cone Bottom Tank Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the cone bottom tank market. Vertically integrated fabricators with captive plate rolling capacity dominate large-capacity industrial contracts, while specialized rotational molders capture standardized polyethylene segments. Three archetypes define competitive positioning: integrated steel fabricators serving petrochemical terminals, polymer specialists targeting municipal water certification, and stainless steel alloy formulators meeting pharmaceutical surface finish standards. Capacity expansion and strategic partnerships represent the dominant competitive moves, as fabricators seek to secure ASME-qualified welders and NSF/ANSI 61 certification pathways.
Among North American fabricators, CST Industries Inc. and Synalloy Corporation occupy positions at the engineered fabrication tier, with the former representing vertically integrated steel vessel production and the latter exemplifying specialized alloy formulation capabilities. Poly Processing Company LLC anchors the polymer technology vector, its position reflecting proprietary cross-linked polyethylene expertise. These three names illustrate how competitive advantage stratifies across material science, certification access, and fabrication scale rather than geographic coverage alone.
| Leading Market Players |
|---|
| CST Industries Inc. |
| Synalloy Corporation |
| Containment Solutions Inc. |
| Poly Processing Company LLC |
| Snyder Industries Inc. |
| U.S. Plastic Corp. |
| Sherman Roto Tank |
| Roto Dynamics Inc. |
| Wagner Enterprise |
| Others |
Value Network & Pricing Analysis
Cross-linked polyethylene rotomolding adoption is compressing production economics for commodity tank fabricators while concentrating supply among molders with captive XLPE resin formulation capabilities. This technology shift simultaneously erodes price premiums on legacy fiberglass systems and rewards backward-integrated producers who control polyethylene feedstock sourcing.
Pricing Analysis
Lifecycle operational guarantees anchor value-based pricing for municipal water utilities seeking ten-year service contracts encompassing tank integrity and regulatory compliance documentation. Pricing stratifies across pharmaceutical-grade ASME BPE fabrications, NSF/ANSI 61-certified municipal systems, and commodity agricultural vessels. Cost compression in the polyethylene tier is intensifying because resin feedstock costs fluctuate with crude oil indices. Agricultural cooperatives exhibit the highest price sensitivity, while biologics manufacturers accept premium pricing for certified surface finish compliance.
Supply Chain Analysis
ASME Section IX qualified welder shortages in Texas and Louisiana constrain large-capacity stainless steel fabrication capacity. Raw material sourcing draws from domestic steel plate rolling, imported high-density polyethylene resin, and specialized epoxy vinyl ester formulations. Single-source vulnerability concentrates in NSF/ANSI 61-certified resin supply chains where only three domestic compounders maintain active certification. Distribution runs through regional fabricator-direct channels for engineered vessels and distributor networks for standardized polyethylene tanks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around fabricators with dual certification access and regional service infrastructure, as EPA secondary containment deadlines eliminate marginal suppliers lacking NSF/ANSI 61 pathways.
For Market Incumbents: Lock in municipal utility relationships through lifecycle service contracts that bundle installation, integrity monitoring, and regulatory documentation. Expand captive polyethylene compounding capacity to insulate margins from resin price volatility. Defend against XLPE specialists by accelerating IoT-enabled level monitoring integration. For New Entrants and Emerging Players: Smart chemical storage vessels with predictive maintenance algorithms offer a technology-first wedge into pharmaceutical manufacturing segments where legacy carbon steel tanks require manual inspection protocols. Target California municipal water districts with constrained maintenance budgets seeking operational guarantee structures. Pursue partnership routes with established regional service networks rather than capital-intensive fabrication buildout. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking water infrastructure exposure. Long-term viability favors fabricators with demonstrated dual-certification capabilities spanning potable water and chemical resistance standards. Watch for inflection when state-level PFAS restrictions trigger accelerated replacement cycles for legacy coated steel installations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into XLPE Resin Compounding | Captive supply of cross-linked polyethylene insulates margins from crude oil index volatility. |
| ASME Section IX Welder Training Programs | Internal certification pipelines alleviate bottlenecks constraining large-capacity stainless steel output. |
| IoT-Enabled Level Monitoring Integration | Predictive maintenance capabilities open recurring revenue streams in pharmaceutical installations. |
| REACH-Compliant Recycled Polyethylene Validation | EU Green Deal alignment unlocks procurement pathways for circular economy-mandated utilities. |
| Ten-Year Operational Guarantee Structuring | Lifecycle contracts displace capital purchase models among budget-constrained municipal districts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with rotational molding plant managers, municipal water utility procurement leads, petrochemical terminal maintenance directors, and ASME-certified fabrication supervisors validated demand patterns. Secondary sources encompassed EPA enforcement action databases, NSF/ANSI certification registries, and SEC 10-K disclosures from publicly traded fabricators. Bottom-up tank shipment tallies by capacity tier and material type reconciled against top-down petrochemical capital expenditure tracking.
Data-stream reconciliation across installation permits, resin consumption surveys, and end-user procurement databases shaped the analytical framework. Segmentation modeling spanned product type, end-use industry, installation configuration, and capacity tier across the projection horizon. CAGRs derived from regression analysis of historical replacement cycles against regulatory deadline schedules. Industry-specific forecast inputs included EPA 40 CFR 112 enforcement trajectory projections and state-level PFAS restriction adoption timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt resin price spikes or accelerated welder certification bottlenecks. Material deviation in EPA enforcement intensity or REACH substance restriction expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Anti-Static Reel Racks Market
Industrial Packaging
Asia-Pacific Warehouse Drums and Barrel Market
Industrial Packaging
Industrial Plastic Bags Market
Industrial Packaging
Dunnage Trays Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
MENA Industrial Packaging Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Slip Sheets Market
Industrial Packaging
Middle East and Africa Octabin Market
Industrial Packaging
Fiber Drums Market
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Global Industrial Wooden Crates Market
Industrial Packaging
Industrial Bulk Packaging Market
Industrial Packaging
Industrial Packaging Market
Industrial Packaging
Transport Racks Market
Industrial Packaging
Pallet Scales Market