
 Asia-Pacific Warehouse Drums and Barrel Market | 2026-2036
Asia-Pacific Warehouse Drums and Barrel Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Warehouse Drums and Barrel Market Insights
Asset-light leasing models for returnable drum fleets is rewriting competitive dynamics across the Asia-Pacific Warehouse Drums and Barrel landscape. Greif Inc. leverages its pooled container programs to reduce capital barriers for mid-size chemical processors. Mauser Packaging Solutions sustains manufacturing scale through captive reconditioning networks in India and Thailand. Time Technoplast Ltd. specializes in multilayer polymer drums that compete on corrosion resistance against traditional steel alternatives.
Asia-Pacific warehouse drums and barrels are rigid cylindrical containers engineered from cold-rolled steel, high-density polyethylene, or fiberboard composites, typically manufactured through seam welding, blow molding, or spiral winding processes with UN-certified stacking load ratings up to 1,000 kg. These vessels serve as standardized intermediate bulk packaging for liquid chemicals, lubricants, and food-grade concentrates during storage and multimodal transport. Steel drums retain dominance in oil and gas applications where thermal stability and spark resistance are non-negotiable, while plastic drums are displacing metal in food and beverage uses due to weight reduction and inert interior surfaces. The 55-gallon capacity segment anchors volume throughput at petrochemical terminals, though custom sizes are gaining traction among pharmaceutical formulators seeking exact-batch containment.
India's BIS standards, China's GB/T 325 regulations for steel drums, and Japan's JIS Z 1600 framework collectively govern wall thickness, closure integrity, and hazardous goods compatibility across the region. Compliance with these national codes determines market access, as cross-border chemical trade requires dual-certified packaging for port clearance. Stakeholders must monitor how evolving extended producer responsibility rules in South Korea and Australia reshape reconditioning economics versus single-use drum procurement.
Market Dynamics
BIS certification mandates in India and GB/T 325 enforcement in China are tightening wall-thickness standards, forcing drum fabricators to retool seam-welding lines and consolidate supplier bases around dual-certified production facilities.
Growth Catalysts
- UN-certified stacking protocols:Chemical terminals in Vietnam's northern industrial corridor near Haiphong now require 1,000 kg load-rated drums for bulk liquid storage expansions, pulling demand toward certified steel alternatives.
- Extended producer responsibility rules:South Korea and Australia are reshaping reconditioning economics, creating captive revenue streams for drum leasing operators with closed-loop collection networks.
- Polymer corrosion resistance:Food-grade concentrate processors are switching from steel to multilayer HDPE drums for inert interior surfaces and weight reduction in multimodal transport.
Market Restraints
- Cold-rolled steel price volatility:Input cost swings compress margins for traditional drum fabricators unable to pass through raw material adjustments on long-term chemical processor contracts.
- Single-use plastic substitution limits:Fiberboard composite drums face technical barriers in hazardous liquid containment, constraining penetration beyond dry chemical and powder applications.
- Cross-border certification friction:Dual-certified packaging requirements for port clearance create inventory complexity for drum fleets serving multiple Asia-Pacific jurisdictions.
Strategic Opportunities
- Asset-light leasing penetration:Pooled container programs reduce capital barriers for mid-size chemical processors in Thailand and Indonesia, expanding addressable customer bases beyond integrated oil majors.
- Pharmaceutical exact-batch containment:Custom-capacity drums below 55-gallon standard are gaining traction among pharmaceutical formulators seeking precise batch sizing for active ingredient transport.
- Captive reconditioning networks:India and Thailand offer geographic positioning for integrated reconditioning facilities serving returnable drum fleets with lower turnaround costs than single-use procurement.
Industry Challenges
- Dual-certification compliance timelines:Simultaneous BIS and GB/T 325 testing protocols extend product launch cycles for drum fabricators targeting India-China cross-border chemical trade.
- Seam-welding skill scarcity:Certified welders capable of producing UN-compliant 1,000 kg load-rated steel drums command premium wages in Vietnam's Haiphong industrial corridor, constraining production scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Warehouse Drums and Barrel Market |
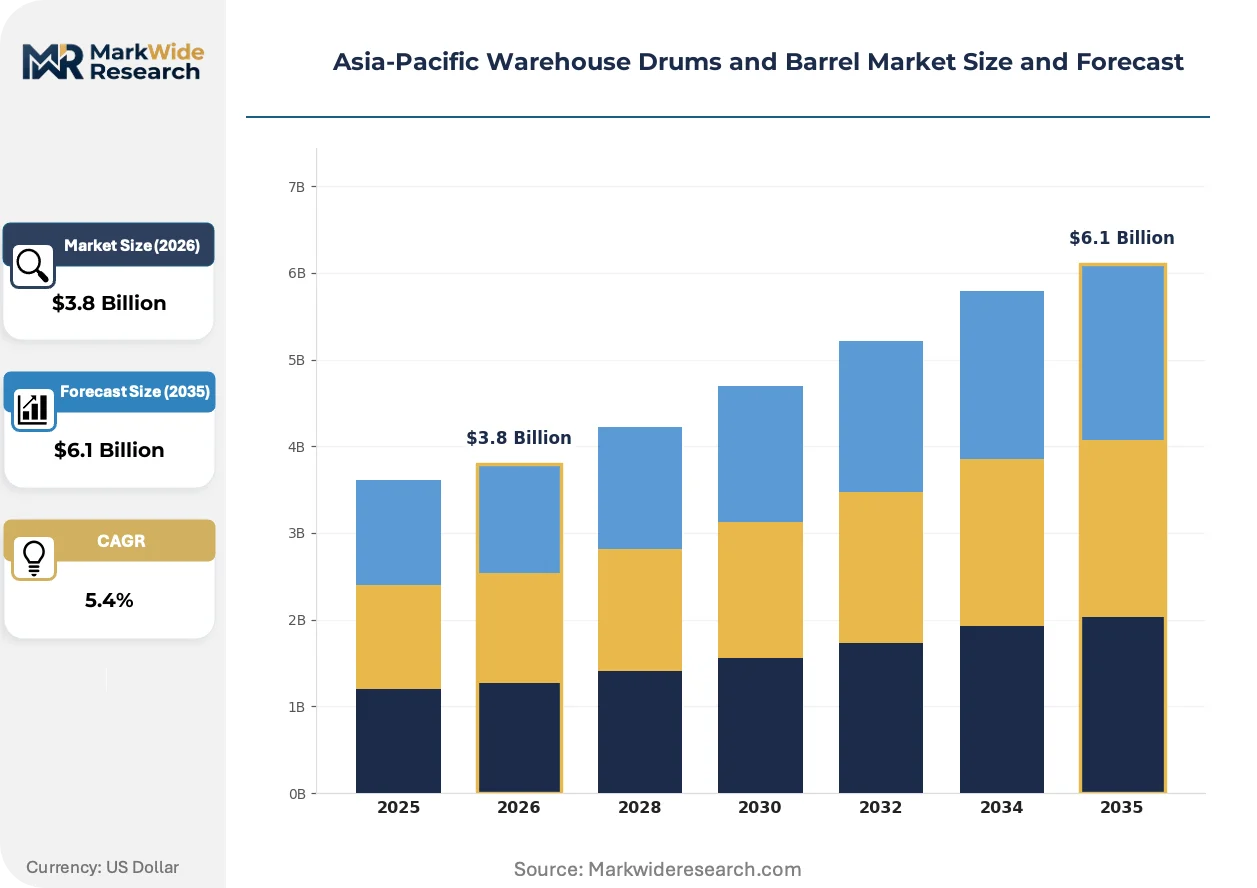
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Drums, Plastic Drums, Fiber Drums, Glass Drums End Use Industry: Chemicals, Food & Beverage, Pharmaceuticals, Oil & Gas Capacity: 55 Gallons, 30 Gallons, 15 Gallons, Custom Sizes Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Nippon Steel Drums Co. Ltd., Sonoco Products Co., Greif Inc., Balmer Lawrie & Co. Ltd., Skolnik Industries Inc., Mauser Packaging Solutions, Time Technoplast Ltd., Sicagen India Ltd., Schutz GmbH & Co. KGaA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Warehouse Drums and Barrel Market Trends and Innovations
Material science advances and regulatory tightening are converging to reshape drum construction methods, inspection protocols, and fleet management approaches across Asia-Pacific chemical logistics.
Multilayer polymer drum technology is hybridizing traditional blow-molding processes with co-extrusion barrier layers. Specialty chemical distributors in Japan and South Korea are adopting these vessels for solvent transport at accelerated replacement cycles. This hybridization is compressing the cost gap against steel alternatives in corrosive liquid applications while maintaining UN certification for maritime shipping.
India's BIS standards for hazardous material containers now mandate third-party wall-thickness verification and closure integrity testing. Drum fabricators serving the Indian market must maintain separate production lines with enhanced quality documentation. Small-scale steel drum producers without testing laboratory partnerships are exiting the certified segment, concentrating supply among integrated manufacturers with captive metrology capabilities.
Returnable drum leasing contracts are displacing outright purchase arrangements among mid-size lubricant blenders. Chemical processors in Malaysia and Singapore are unbundling drum procurement from logistics services, awarding fleet management to specialized container pooling operators. This behavioral shift is most visible in automotive lubricant supply chains where just-in-time delivery requirements favor flexible drum availability over owned asset bases.
Asia-Pacific Warehouse Drums and Barrel Market Segmentation
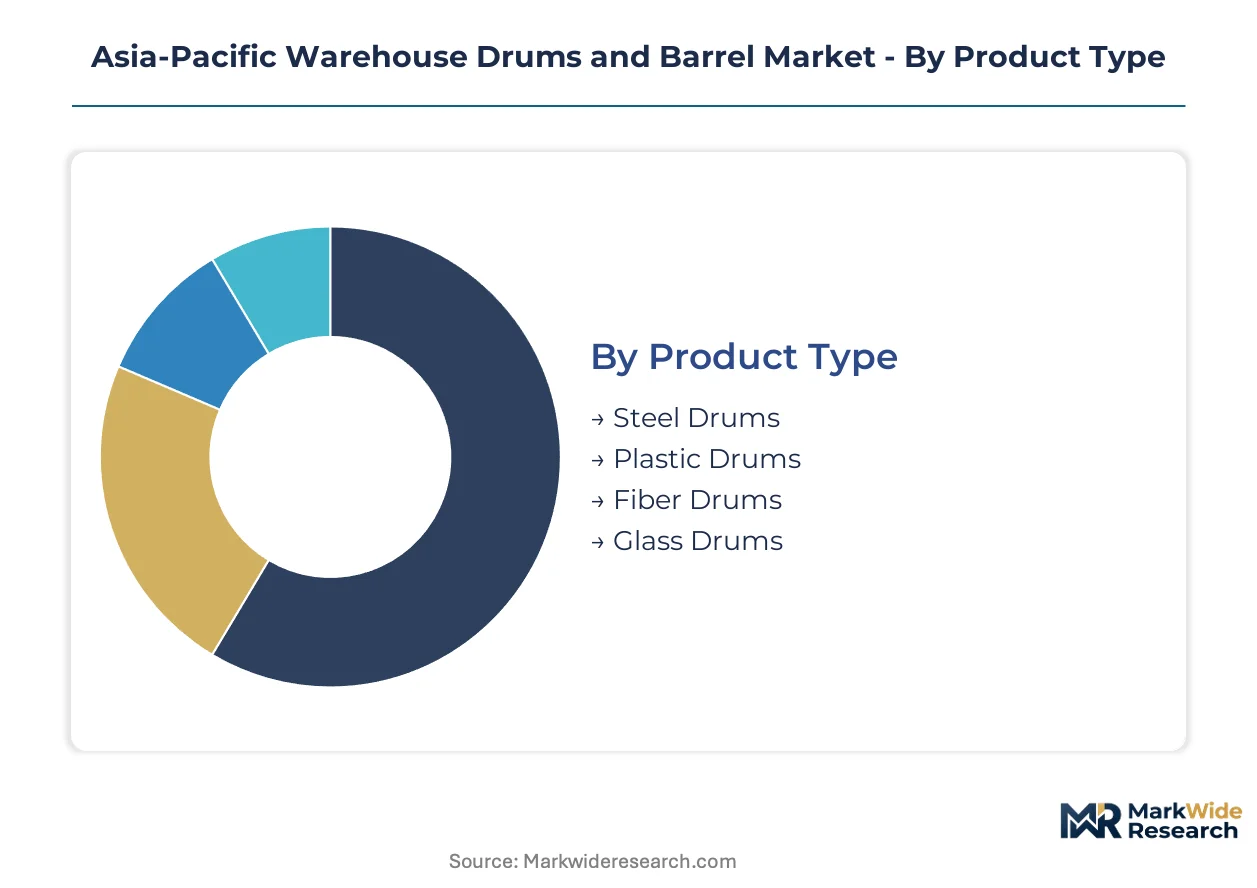
Product specifications, end-use requirements, and logistics configurations fragment the Asia-Pacific Warehouse Drums and Barrel Market into distinct procurement categories. Each segment carries unique certification burdens and cost structures that determine competitive positioning across chemical, food, and pharmaceutical supply chains.
Product Type:
Use-case spectrum spans hazardous liquid containment to lightweight dry goods transport, with material selection driven by corrosion resistance, thermal stability, and UN certification requirements.
- Steel Drums:Cold-rolled steel construction with seam-welded walls delivers UN-certified 1,000 kg stacking loads for petrochemical terminals. Demand concentrates in Vietnam's northern industrial corridor near Haiphong where oil and gas processors require spark-resistant containment for flammable liquids.
- Plastic Drums:Multilayer HDPE blow-molding with co-extrusion barrier layers competes on weight reduction and inert interior surfaces. Food-grade concentrate processors across Thailand and Malaysia are switching from steel to polymer for corrosion resistance in multimodal transport.
- Fiber Drums:Spiral-wound fiberboard composites serve dry chemical and powder applications where liquid containment is unnecessary. Technical barriers in hazardous liquid handling constrain penetration beyond non-reactive solid formulations.
- Glass Drums:Borosilicate or soda-lime construction provides inert containment for high-purity pharmaceutical intermediates. Niche adoption among active ingredient formulators in Japan and South Korea where chemical compatibility overrides fragility concerns.
Established volume favors steel drums; emerging adoption favors plastic drums.
End Use Industry:
Customer procurement patterns diverge sharply between hazardous chemical handlers with stringent certification requirements and food processors prioritizing weight economics.
- Chemicals:Solvent distributors and specialty chemical manufacturers drive demand for dual-certified packaging meeting both BIS and GB/T 325 standards. Bulk liquid storage expansions across Southeast Asia pull throughput toward 55-gallon steel alternatives with verified closure integrity.
- Food & Beverage:Concentrate processors and edible oil refiners prioritize polymer drums for inert surfaces and reduced tare weight in containerized shipping. India's FSSAI compliance requirements for food-contact materials shape material selection criteria.
- Pharmaceuticals:Active ingredient formulators and contract manufacturing organizations seek exact-batch containment below standard capacities. Custom-capacity drums below 55-gallon specifications gain traction for precise dosing in clinical trial material transport.
- Oil & Gas:Lubricant blenders and base oil terminals require thermal stability and spark resistance that anchor steel drum dominance. Just-in-time delivery requirements in automotive supply chains favor leased drum fleets over owned assets.
Volume concentration sits with chemicals; margin expansion sits with pharmaceuticals.
Capacity:
Standardization versus customization tension plays out across terminal operations requiring interchangeability and formulators seeking batch precision.
- 55 Gallons:The de facto international standard anchors petrochemical terminal throughput and maritime bulk liquid logistics. This capacity dominates leasing fleet configurations due to equipment interchangeability across Southeast Asian ports.
- 30 Gallons:Mid-size format serves specialty chemical distributors with moderate batch volumes and constrained storage footprints. Adoption concentrates among Japanese and South Korean solvent handlers with space-optimized warehousing.
- 15 Gallons:Compact format supports pharmaceutical sampling and pilot-scale production runs where full-batch commitment is uneconomical. Limited penetration outside laboratory and R&D supply chains.
- Custom Sizes:Non-standard capacities address pharmaceutical exact-batch requirements and proprietary chemical formulations with unique density characteristics. Fabrication lead times and certification costs restrict adoption to premium applications.
Operational scale favors 55-gallon standardization; formulation precision favors custom capacities.
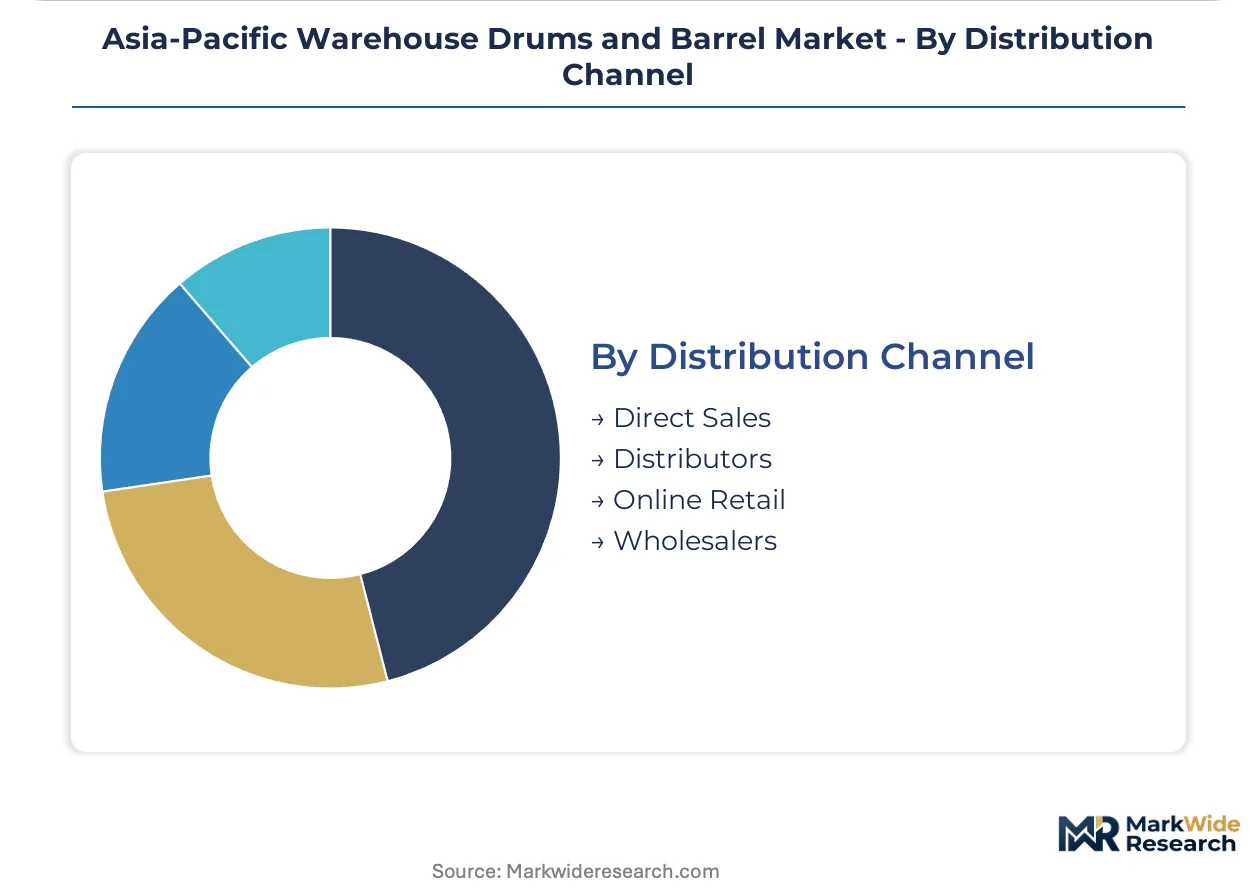
Distribution Channel:
Procurement channel selection reflects customer scale, certification complexity, and inventory management capabilities.
- Direct Sales:Integrated drum manufacturers maintain dedicated account teams for oil majors and multinational chemical processors with volume commitments. Long-term contracts with fixed pricing clauses dominate this channel.
- Distributors:Regional stocking distributors serve mid-size lubricant blenders and food processors with fragmented demand patterns. Inventory carrying costs are offset by reduced order lead times for certified drum procurement.
- Online Retail:Digital procurement platforms gain traction among small-scale chemical handlers and laboratory supply purchasers with sporadic, low-volume requirements. Certification documentation availability limits category expansion.
- Wholesalers:Bulk aggregators serve secondary markets with price-sensitive drum procurement for non-certified applications. Quality inconsistency and limited traceability constrain penetration in regulated end uses.
Contract security favors direct sales; flexibility favors distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification mandates in India and GB/T 325 enforcement in China are tightening product standards across the region, forcing drum fabricators to consolidate production around dual-certified facilities. Vietnam's northern industrial corridor near Haiphong is emerging as a demand concentration point for UN-certified steel drums serving bulk liquid storage expansions.
India
Petrochemical terminals in Gujarat and Maharashtra are expanding intermediate bulk packaging capacity for specialty chemical exports. BIS standards now mandate third-party wall-thickness verification and closure integrity testing for hazardous material containers. Small-scale steel drum producers without testing laboratory partnerships are exiting the certified segment, concentrating supply among integrated manufacturers with captive metrology capabilities in the western industrial belt.
China
GB/T 325 regulations for steel drums are forcing fabricators to retool seam-welding lines to meet stricter wall-thickness specifications. The Yangtze River Delta chemical clusters near Shanghai and Ningbo anchor demand for dual-certified packaging serving cross-border trade. Domestic producers are consolidating supplier bases around facilities capable of simultaneous BIS and GB/T 325 certification for India-bound chemical exports.
Vietnam
Chemical manufacturers in the northern industrial corridor near Haiphong require 1,000 kg load-rated drums for new bulk liquid storage terminals. Certified welders capable of producing UN-compliant steel drums command premium wages, constraining production scale-up. Japanese and South Korean solvent distributors are establishing regional stocking points to serve space-optimized warehousing in the Red River Delta manufacturing zone.
Thailand
Mid-size lubricant blenders in the Eastern Economic Corridor are unbundling drum procurement from logistics services. Returnable drum leasing contracts are displacing outright purchase arrangements among automotive supply chain participants. Food-grade concentrate processors in the Bangkok metropolitan area are switching to multilayer HDPE drums for weight reduction in containerized shipping to ASEAN markets.
South Korea
Extended producer responsibility rules are reshaping reconditioning economics for drum leasing operators with closed-loop collection networks. Specialty chemical distributors in the Ulsan petrochemical complex are adopting multilayer polymer drums for solvent transport at accelerated replacement cycles. Captive reconditioning facilities serving returnable drum fleets are achieving lower turnaround costs than single-use procurement for base oil terminals.
Asia-Pacific Warehouse Drums and Barrel Market Competitive Landscape
On the supply side, the industry is consolidating around integrated manufacturers with captive testing capabilities and reconditioning networks. Tiered competitive positioning separates asset-light leasing operators from capital-intensive fabrication specialists. Three archetypes dominate: pooled container program managers, dual-certified steel drum fabricators, and multilayer polymer specialists. M&A activity concentrates on reconditioning network acquisitions, while capacity expansion targets Vietnam's Haiphong corridor and India's western chemical belt.
Within the integrated fabrication tier, Greif Inc. and Mauser Packaging Solutions exemplify asset-light leasing models that reduce capital barriers for mid-size chemical processors. Time Technoplast Ltd. occupies a position among multilayer polymer specialists competing on corrosion resistance. These three anchors illustrate how certification capabilities and fleet management services determine competitive positioning across Southeast Asian chemical logistics corridors.
| Leading Market Players |
|---|
| Nippon Steel Drums Co. Ltd. |
| Sonoco Products Co. |
| Greif Inc. |
| Balmer Lawrie & Co. Ltd. |
| Skolnik Industries Inc. |
| Mauser Packaging Solutions |
| Time Technoplast Ltd. |
| Sicagen India Ltd. |
| Schutz GmbH & Co. KGaA |
| Others |
Pricing and Supply Chain Analysis
Vietnam's Haiphong industrial corridor anchors regional steel drum fabrication capacity, concentrating supply-side leverage among UN-certified producers serving bulk liquid storage expansions. Cold-rolled steel input costs and certified welder scarcity transmit directly into downstream pricing power for dual-certified fabricators.
Pricing Analysis
Certification level (BIS/GB/T 325 dual-grade) creates the primary spread between premium and standard tiers. Contract-based long-term offtake dominates procurement among oil majors, while spot purchasing serves smaller lubricant blenders. Price differentiation hinges on UN stacking load ratings and captive reconditioning availability. Margins are tightening due to cold-rolled steel volatility that fabricators cannot fully pass through on fixed-price contracts. Mid-size chemical processors show highest price sensitivity; integrated petrochemical terminals least.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk planning for cross-border drum fleets. Manufacturing concentrates in China, India, and Vietnam. Cold-rolled steel coils, HDPE resin, and fiberboard kraft paper constitute core material inputs. Single-source vulnerability persists in specialized seam-welding equipment for UN-compliant production. Distribution runs through regional stocking distributors serving fragmented mid-size demand across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific warehouse drums and barrels are cycling through a petrochemical capital expenditure upswing, with bulk liquid storage expansions across Vietnam and India driving replacement demand.
For Market Incumbents: Build certification moats through simultaneous BIS and GB/T 325 testing laboratory accreditation. Secure captive reconditioning networks in Thailand and India to lower fleet turnaround costs below single-use alternatives. Defend against polymer drum substitution by emphasizing thermal stability in flammable liquid applications. Prioritize vertical integration into cold-rolled steel coil sourcing to buffer margin compression. For New Entrants and Emerging Players: Mid-market lubricant blenders in Indonesia and the Philippines represent the most penetrable entry point, as these customers unbundle drum procurement from logistics services. Asset-light leasing contracts for returnable fleets reduce capital barriers versus integrated fabrication. Target food-grade concentrate processors switching from steel to multilayer HDPE for weight reduction in ASEAN containerized shipping. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with captive metrology and reconditioning capabilities over pure-play fabricators. Long-term viability rests on extended producer responsibility compliance in South Korea and Australia reshaping fleet economics. Monitor certified welder wage inflation in Vietnam's Haiphong corridor as inflection signal for regional production cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | BIS and GB/T 325 testing capabilities unlock India-China cross-border chemical trade corridors. |
| Captive Reconditioning Network | Closed-loop collection facilities in Thailand lower turnaround costs below single-use drum procurement. |
| Multilayer Polymer Capacity | Co-extrusion barrier technology compresses cost gap against steel in corrosive liquid applications. |
| Asset-Light Leasing Expansion | Pooled container programs reduce capital barriers for mid-size chemical processors in Indonesia. |
| Certified Welder Training Pipeline | UN-compliant seam-welding skills scarcity in Vietnam constrains production scale-up without workforce investment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, BIS certification registries, and petrochemical terminal expansion announcements. Interviews with drum fabricator plant managers, procurement leads at specialty chemical distributors, reconditioning network operators, and technical R&D directors informed demand-side validation. Bottom-up capacity modeling triangulated against top-down trade flow analysis.
Forecast inputs span product type segmentation across steel, plastic, fiber, and glass constructions; end-use industries from chemicals to pharmaceuticals; capacity tiers from standard 55-gallon to custom formats; and distribution channels from direct sales through online retail. CAGRs derived from elasticity-adjusted volume projections and value-per-unit trajectories across the analysis window. Cold-rolled steel price indices and certified welder wage data in Vietnam's Haiphong corridor fed industry-specific adjustments.
Macroeconomic conditions sit as an overlay; deviation in petrochemical capital expenditure cycles or ASEAN container shipping rates would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement timelines and substitution elasticity between material types. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Dunnage Racks Market
Industrial Packaging
Fiber Drums Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
MENA Industrial Packaging Market
Industrial Packaging
Bulk Packaging Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Industrial Packaging Market
Industrial Packaging
Dunnage Trays Market
Industrial Packaging
Rigid IBC Market
Industrial Packaging
Corrugated Octabins Market
Industrial Packaging
Transport Racks Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Middle East and Africa Octabin Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Corrugated Automotive Packaging Market
Industrial Packaging
Industrial Jugs Market