
 Dunnage Air Bags Market | 2026-2036
Dunnage Air Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Dunnage Air Bags Market Analysis
AAR certification for railcar load securement is rotating supplier eligibility across North America and Europe. Cordstrap B.V. leverages its multi-layer woven technology to sustain premium positioning in pharmaceutical cold-chain logistics. International Dunnage A.S. anchors Nordic market share through captive polypropylene extrusion capacity. Signode Industrial Group LLC competes via integrated steel strapping and air bag bundling for automotive tier-one suppliers.
Dunnage air bags are inflatable polyethylene or polypropylene cushions, typically 2-8 ply, inflated to 2-8 psi to brace cargo within intermodal containers, railcars, and over-the-road trailers. Their primary purpose is absorbing lateral and longitudinal shock during transit to prevent product damage and reduce insurance claims. Multi-layer polyethylene configurations lead transport applications due to puncture resistance and cost efficiency, while valve-type designs capture fastest growth in automated logistics lines. Pharmaceutical end users concentrate margin pools around custom-form bags with lot-level traceability, whereas standard flat formats dominate mature electronics packaging channels.
FDA traceability rules for pharmaceutical distribution shape custom dunnage specifications in the United States. The EU Green Deal and REACH chemical compliance filter which polypropylene grades qualify for European logistics procurement. EPA freight emission standards indirectly tighten load optimization requirements, pushing shippers toward lighter inflatable solutions. Stakeholders must monitor how California's CARB freight rules and Germany's KBA transport safety directives converge on material certification thresholds.
Market Dynamics
EU Packaging and Packaging Waste Regulation recyclability mandates are forcing polyethylene-to-polypropylene grade conversions across European logistics networks, compressing supplier qualification timelines and rewiring raw material procurement.
Growth Catalysts
- Automotive OEM supplier network density:German automotive clusters operate just-in-time delivery systems requiring standardized load securement protocols that specify dunnage air bag specifications across tier-one and tier-two suppliers.
- FDA traceability mandates:United States pharmaceutical distribution rules now require lot-level tracking on all transport packaging materials, creating specification premiums for custom-form bags with embedded traceability features.
- Railcar AAR certification rotation:North American freight rail safety standards are updating approved supplier lists, opening procurement windows for certified inflatable void-fill systems in intermodal container applications.
Market Restraints
- Polypropylene grade supply concentration:REACH-compliant polymer feedstock availability concentrates among limited European petrochemical producers, creating input cost volatility for bag manufacturers.
- Steel strapping substitution threat:Signode Industrial Group and integrated metal strapping suppliers bundle air bag alternatives with established automotive tier-one supply contracts, locking out inflatable specialists.
- Multi-ply fabrication technical ceiling:Current 8-ply woven configurations face puncture resistance limitations in heavy machinery transport above 40-ton cargo loads, restricting addressable application scope.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:Temperature-controlled biologics distribution networks in the United States and Germany require custom dunnage with thermal insulation properties and FDA-validated materials.
- EU Green Deal material incentives:Recycled content mandates in European logistics procurement create first-mover advantage for suppliers with closed-loop polypropylene recovery systems.
- Automated logistics valve convergence:Integration of RFID-enabled inflation valves with warehouse management systems enables real-time pressure monitoring in automated fulfillment centers.
Industry Challenges
- AAR certification timeline compression:Railcar load securement approval cycles now require 18-24 months of field testing, delaying new product commercialization for inflatable system developers.
- Multi-material recycling infrastructure gaps:Laminated polyethylene-polypropylene woven bags lack dedicated collection streams in most European and North American waste management systems, complicating customer ESG compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dunnage Air Bags Market |
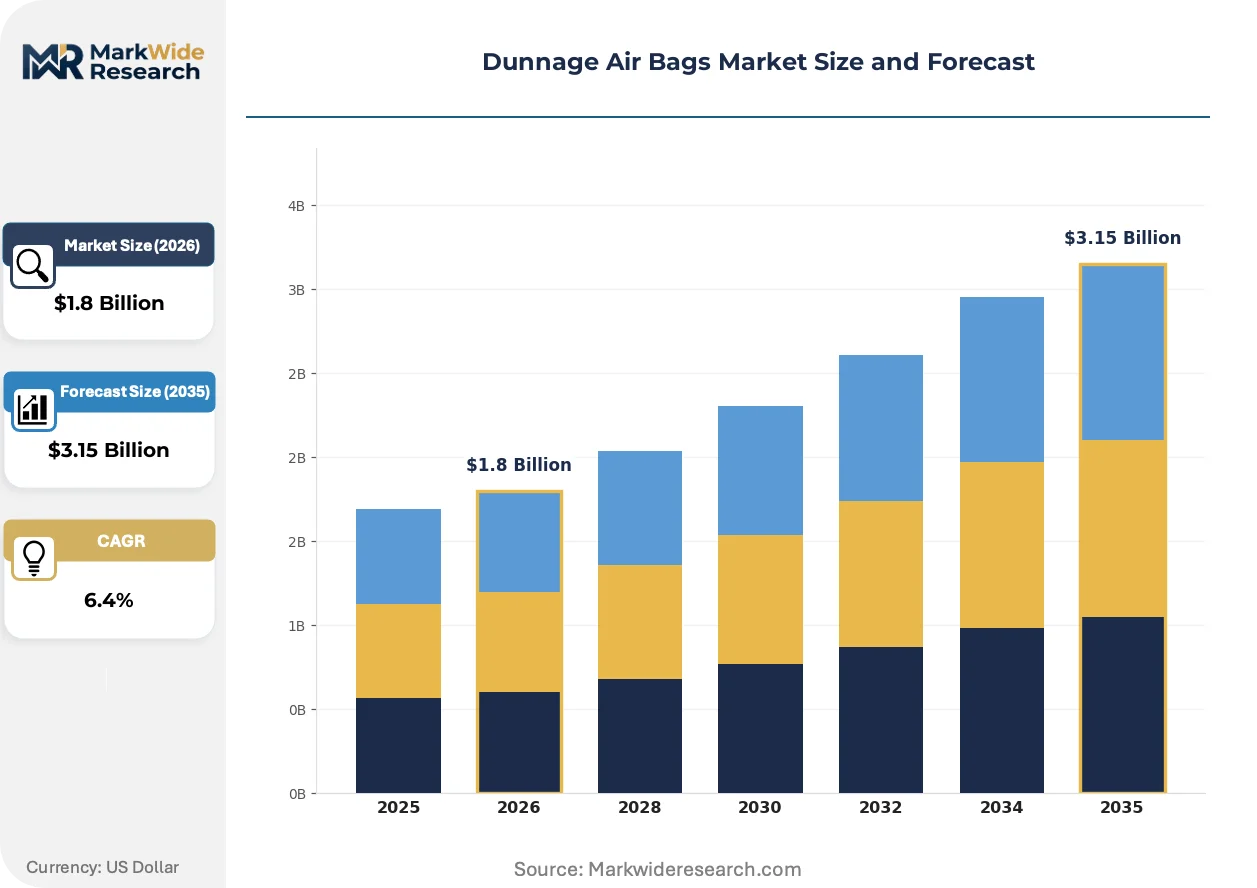
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Multi-layer, Valve Type End User: Automotive, Pharmaceutical, Electronics, Logistics Application: Transport, Storage, Packaging, Shipping Form: Inflatable, Flat, Custom, Standard |
| Companies Covered | Atlas Dunnage, International Dunnage A.S., Cordstrap B.V., Bates Cargo-Pak ApS, Shippers Products Group, Signode Industrial Group LLC, Bulk-Pack, Inc., Green Label Packaging, Litco International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dunnage Air Bags Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are decomposing established supply relationships while automated logistics infrastructure demands new product formats. Three forces are restructuring competitive positioning.
Multi-layer woven polypropylene is decomposing legacy polyethylene dominance in heavy freight applications. Pharmaceutical cold-chain operators in Germany and the United States specify 6-ply and 8-ply woven configurations for puncture resistance during temperature-controlled transport. The technology is decomposing price-based procurement by enabling lot-level traceability integration that commands specification premiums.
REACH chemical compliance and EU Green Deal recycled content thresholds are filtering qualified material grades for European logistics procurement. ECHA substance restrictions now exclude specific polymer additives previously standard in Asian-manufactured bags. German automotive OEMs are responding by consolidating supplier lists to vendors with verified European compound sourcing and third-party recyclability certification.
Buyer specification behavior is rotating from commodity catalog purchasing toward engineered solutions contracting. Large third-party logistics providers in the United States now require collaborative design sessions for lane-specific load securement rather than standard product selection. The shift is most visible in cross-border automotive parts distribution between Mexico and the United States, where cargo damage claim liability is being pushed back to packaging suppliers through performance guarantees.
Dunnage Air Bags Market Segmentation
Dunnage air bag procurement patterns diverge sharply between domestic just-in-time networks and export-heavy containerized lanes. Segment-level specification requirements reflect these operational differences, with automotive clusters demanding standardized formats while pharmaceutical cold-chain operators pursue custom-engineered solutions.
Product Type:
Polyethylene formulations dominate North American over-the-road applications, whereas European procurement tilts toward REACH-compliant polypropylene grades. Asian export corridors absorb multi-layer woven configurations for heavy machinery transits.
- Polyethylene:Two-ply to four-ply extruded configurations provide puncture resistance at sub-5-psi inflation pressures. Demand concentrates in United States cross-border automotive lanes between Michigan and Mexico, where tier-one suppliers specify cost-optimized void-fill for repetitive lane utilization. EPA freight emission standards indirectly favor lighter polyethylene over competing materials.
- Polypropylene:Woven 6-ply and 8-ply structures deliver load-bearing capacity exceeding 40 tons. German automotive OEMs specify these grades for railcar unit-load shipments through KBA-certified protocols. ECHA substance restrictions filter qualified feedstock sources to verified European compounders.
- Multi-layer:Hybrid polyethylene-polypropylene laminates balance cost and puncture resistance for intermodal container applications.
- Valve Type:Rapid-inflation valves integrate with automated warehouse inflation stations in United States e-commerce fulfillment networks.
Polyethylene commands the established base. The steepest expansion runs through valve-type configurations.
End User:
Automotive procurement operates through centralized OEM specification committees, while pharmaceutical buyers negotiate directly with packaging engineers for lot-traceable formats. Electronics distributors favor catalog-standard products with minimal lead times.
- Automotive:Just-in-time delivery systems require standardized load securement across tier-one and tier-two supplier networks. German OEM clusters in Bavaria and Baden-Württemberg specify uniform dunnage dimensions to enable supplier rotation without revalidation. AAR certification cycles compress new vendor qualification timelines.
- Pharmaceutical:Temperature-controlled biologics distribution demands custom-form bags with FDA-validated materials and embedded lot-level traceability. United States cold-chain operators pay specification premiums for thermal insulation properties integrated into 6-ply woven configurations.
- Electronics:Fragile component shipping favors flat-format polyethylene bags with rapid deployment characteristics.
- Logistics:Third-party providers bundle dunnage into lane-specific performance contracts with damage liability transfer.
Automotive anchors volume concentration. Pharmaceutical applications are climbing the fastest.
Application:
Transport applications generate recurring consumable demand, whereas storage and packaging segments involve capital-equipment decisions with extended replacement cycles.
- Transport:Void-fill deployment in intermodal containers, railcars, and over-the-road trailers constitutes the core revenue pool. United States cross-border lanes between Mexico and Texas absorb high volumes of standard-format polyethylene bags.
- Storage:Long-term warehouse bracing applications favor reusable multi-layer configurations with pressure maintenance valves.
- Packaging:Primary packaging integration remains limited to pharmaceutical serialization requirements.
- Shipping:Export-oriented ocean container loading specifies 8-ply woven grades for 40-ton cargo loads.
Transport captures the recurring revenue base. Shipping applications gain share fastest.
Form:
Standard formats move through distribution inventory, while custom specifications require collaborative design cycles with 12-18 week lead times.
- Inflatable:Pre-inflated or on-site inflation options segment by automation level. Automated logistics lines in United States e-commerce hubs specify RFID-enabled pressure monitoring.
- Flat:Pre-pressurized cushions suit rapid-deployment environments with minimal equipment investment. Electronics distributors in Germany favor these for small-lot shipments.
- Custom:Engineered dimensions and material stacks address pharmaceutical cold-chain validation requirements.
- Standard:Catalog dimensions enable spot purchasing through industrial distribution channels.
Standard formats dominate procurement velocity. Custom forms expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and pharmaceutical cold-chain operators concentrate procurement in jurisdictions with dense supplier networks and stringent transport safety protocols. German automotive clusters, United States cross-border logistics corridors, and Nordic pharmaceutical distribution hubs anchor regional demand patterns. Regulatory divergence between REACH-compliant European grades and FDA-validated United States specifications fragments material qualification pathways.
United States
Cross-border automotive lanes between Michigan and Mexico absorb standardized polyethylene void-fill for repetitive tier-one supplier rotations. FDA traceability mandates for pharmaceutical distribution now require lot-level tracking on all transport packaging materials, compressing custom specification timelines. Dallas-Fort Worth e-commerce fulfillment hubs specify RFID-enabled valve systems for automated inflation stations.
Germany
Bavarian and Baden-Württemberg automotive OEM clusters operate just-in-time delivery systems requiring KBA-certified load securement protocols across supplier networks. EU Packaging and Packaging Waste Regulation recyclability mandates are forcing polyethylene-to-polypropylene grade conversions, rewiring raw material procurement. Stuttgart-based tier-one suppliers specify uniform dunnage dimensions to enable supplier rotation without revalidation cycles.
China
Export-oriented manufacturing bases in the Yangtze River Delta absorb multi-layer woven configurations for heavy machinery ocean container transits. MIIT industrial standards for transport packaging materials are converging with international load securement protocols. Shanghai-port logistics providers bundle inflatable void-fill into performance contracts with damage liability transfer clauses.
Netherlands
Rotterdam-Europoort container terminals generate recurring demand for intermodal-grade air bags serving transshipment corridors into German industrial zones. ECHA substance restrictions filter qualified polymer feedstock sources to verified European compounders. Randstad-based third-party logistics providers now require collaborative design sessions for lane-specific load securement rather than catalog purchasing.
Mexico
Nuevo León automotive assembly plants specify standardized dunnage formats for inbound parts from United States tier-one suppliers. NAFTA successor trade provisions maintain cross-border certification reciprocity for AAR-approved load securement systems. Monterrey-based logistics providers face pressure transfer of cargo damage claim liability back to packaging suppliers through performance guarantees.
Dunnage Air Bags Market Vendor Landscape
Player mix skews toward specialized fabricators with captive extrusion capacity and diversified industrial conglomerates with integrated strapping portfolios. The vendor base separates into three strategic tiers: woven polypropylene specialists serving pharmaceutical cold-chain validation requirements, polyethylene extruders optimizing for cost-sensitive automotive lanes, and diversified load-securement providers bundling air bags with complementary restraint systems. Dominant competitive moves include backward integration into polymer compounding to secure REACH-compliant feedstock and geographic expansion through AAR certification acquisition for railcar procurement eligibility.
Among European-based woven specialists, Cordstrap B.V., International Dunnage A.S., and Bates Cargo-Pak ApS occupy positions within the premium-tier segment where multi-layer configurations command specification premiums. These entities exemplify the archetype of regional specialists leveraging proximity to German automotive clusters and Nordic pharmaceutical distribution networks. United States market presence concentrates among diversified industrial suppliers and regional fabricators serving cross-border automotive corridors.
| Leading Market Players |
|---|
| Atlas Dunnage |
| International Dunnage A.S. |
| Cordstrap B.V. |
| Bates Cargo-Pak ApS |
| Shippers Products Group |
| Signode Industrial Group LLC |
| Bulk-Pack, Inc. |
| Green Label Packaging |
| Litco International, Inc. |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month AAR certification cycles compress supplier inventory turns to 45-60 days across North American railcar procurement, concentrating pricing power among incumbent woven-polypropylene specialists with captive extrusion capacity while forcing cost-plus indexation to European polymer feedstock benchmarks.
Pricing Analysis
Cost-plus contracts with polypropylene indexation to European petrochemical benchmarks dominate procurement between German automotive OEMs and tier-one suppliers. Three-tier pricing structure across REACH-certified premium, KBA-validated standard, and non-certified economy levels separates lot-traceable pharmaceutical grades from basic polyethylene void-fill. Pricing pressure stems from steel strapping bundling by integrated metal restraint suppliers in United States cross-border lanes. Electronics distributors exhibit highest price sensitivity due to catalog-standard spot purchasing, whereas pharmaceutical cold-chain operators accept specification premiums for FDA-validated thermal insulation.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp container corridors elevates inbound logistics costs for Asian-manufactured polyethylene grades, forcing German automotive clusters to consolidate procurement around European compounders with verified REACH compliance. Polymer feedstock concentrates in Germany, Belgium, and the Netherlands; woven fabric production draws from captive extrusion in Nordic specialist facilities. Single-source vulnerability runs through limited ECHA-approved additive suppliers for pharmaceutical-grade polypropylene. Distribution runs through tier-one automotive supplier networks with KBA-mandated revalidation protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified AAR certification capacity represents the binding constraint in this market, with only a handful of fabricators possessing both woven-polypropylene expertise and railcar load-securement validation—creating acute scarcity for pharmaceutical and automotive procurement officers seeking dual-qualified suppliers.
For Market Incumbents: Shield market position by accelerating backward integration into REACH-compliant polymer compounding to secure feedstock access against ECHA substance restriction volatility. Prioritize AAR certification maintenance and expansion across North American railcar applications to lock out inflatable specialists lacking field-testing data. Defensive capacity additions in Baden-Württemberg supplier corridors reinforce just-in-time specification control against emerging Nordic competitors. For New Entrants and Emerging Players: AAR certification fast-track through partnership with established railcar operators offers the most penetrable entry vector into North American intermodal procurement. White-space concentrates in United States pharmaceutical cold-chain logistics, where FDA traceability mandates have outpaced supplier qualification capacity. Target automated e-commerce fulfillment hubs in Dallas-Fort Worth with RFID-enabled valve systems as a differentiated go-to-market angle against commodity polyethylene suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because certification moats deepen with each ECHA restriction and AAR testing cycle, entrenching incumbent positions against price-based competition. Acquisition targets should exhibit captive extrusion capacity plus validated European compound sourcing. Monitor AAR approved-supplier-list rotation timing as the critical inflection signal for procurement window openings.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Secures REACH-compliant feedstock access against ECHA additive restrictions filtering Asian imports. |
| AAR Certification Acquisition | Unlocks 18-24 month railcar procurement windows in North American intermodal container lanes. |
| RFID-Enabled Valve Development | Integrates with automated warehouse management systems in United States e-commerce fulfillment networks. |
| Closed-Loop Polypropylene Recovery | Captures EU Green Deal recycled content incentives in German automotive OEM procurement. |
| Pharmaceutical Cold-Chain Validation | Commands specification premiums for FDA-lot-traceable bags in temperature-controlled biologics distribution. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with logistics procurement directors, automotive tier-one supplier quality managers, pharmaceutical cold-chain packaging engineers, and woven-fabric plant managers. Secondary validation drew from AAR certification databases, ECHA substance restriction filings, FDA packaging guidance documents, and KBA transport safety directives. Bottom-up volume modeling across polyethylene, polypropylene, and multi-layer product configurations triangulated against top-down European petrochemical feedstock demand estimates.
Across the analysis window, the forecasting framework modeled demand by material grade, end-use industry, application mode, and regional regulatory cluster. CAGRs derived from segment-level volume build-ups incorporating automotive production forecasts, pharmaceutical cold-chain expansion trajectories, and railcar intermodal growth projections. Industry-specific inputs included AAR certification cycle timing, ECHA substance restriction implementation phases, and EU Packaging and Packaging Waste Regulation compliance deadlines.
Decision-makers should treat outputs as directional under assumptions of sustained AAR certification reciprocity and stable REACH polymer grade availability; material deviation in regulatory timelines or feedstock sourcing would warrant model refresh. Specific risk factors encompass sudden ECHA additive bans, AAR testing protocol changes, and polypropylene supply disruptions from European petrochemical facility outages. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Cone Bottom Tank Market
Industrial Packaging
Bulk Packaging Market
Industrial Packaging
Rigid IBC Market
Industrial Packaging
Bulk Liquid Transport Packaging Market
Industrial Packaging
Industrial Pails Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Corrugated Automotive Packaging Market
Industrial Packaging
Anti-Static Reel Racks Market
Industrial Packaging
Industrial Filling Machine Market
Industrial Packaging
Overpack Drum Market
Industrial Packaging
Nestable Drums Market
Industrial Packaging
Insulated Bin Market
Industrial Packaging
Asia-Pacific Warehouse Drums and Barrel Market
Industrial Packaging
MENA Industrial Packaging Market
Industrial Packaging
Global Industrial Wooden Crates Market
Industrial Packaging
Transport Racks Market