
 Industrial Pails Market | 2026-2036
Industrial Pails Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Pails Market Intelligence
A multi-source procurement strategy for bulk packaging is decoupling large chemical and food producers from reliance on single-supplier contracts. This shift benefits large-scale manufacturers like Mauser Packaging Solutions, which leverages its extensive global production footprint to serve multinational clients. Greif sustains its market position through a dedicated focus on steel pail manufacturing for hazardous materials. Meanwhile, Time Technoplast Ltd. specializes in advanced polymer-based solutions for industrial customers in Asia.
Industrial pails are cylindrical containers, typically with capacities ranging from 5 to 25 liters, designed for the secure transport and storage of bulk materials. Constructed from materials like high-density polyethylene (HDPE) or steel, they provide a durable and often UN-rated solution for containing solids, liquids, and semi-solids. High-density polyethylene represents the dominant material segment due to its cost-effectiveness and chemical resistance. The paints and coatings application provides stable volume, while the pharmaceuticals category offers higher-margin opportunities.
Regulations from bodies like the US Department of Transportation (DOT) and compliance with Europe's REACH framework dictate material composition and transport safety standards. The global ISO 16106 standard specifies performance testing for packaging intended to carry dangerous goods, directly influencing pail design and manufacturing. Producers must now decide whether to invest in advanced recycling-friendly polymers or optimize steel pail reconditioning services to meet sustainability targets.
Market Dynamics
The industrial pails market is defined by the structural tension between demand for cost-effective HDPE containers and intensifying regulatory pressure for circularity. This forces manufacturers to choose between developing advanced recyclable polymers or expanding steel pail reconditioning services to meet sustainability targets.
Growth Catalysts
- Indian Industrial Expansion:Rapid growth in India’s domestic chemical manufacturing and food processing sectors creates consistent, volume-driven demand for industrial pails.
- Paints and Coatings Sector:The global paints and coatings industry provides stable demand for durable, UN-rated pails for secure product transport and storage.
- Advanced HDPE Formulations:Innovations in high-density polyethylene that improve recyclability while maintaining chemical resistance align with mandates like the EU Green Deal.
Market Restraints
- Raw Material Volatility:Price fluctuations for key inputs, particularly steel and high-density polyethylene resin, directly impact manufacturing costs and margin stability.
- Substitution Threat:Flexible intermediate bulk containers (FIBCs) present a viable, lower-weight alternative for transporting certain non-hazardous, high-volume dry goods.
- Certification Costs:The stringent and expensive UN testing protocols specified by standards like ISO 16106 create high barriers for new designs and materials.
Strategic Opportunities
- High-Margin Segments:The pharmaceuticals and specialty chemicals sectors offer higher-margin opportunities for specialized, contamination-free, and certified pails.
- Smart Packaging Integration:Incorporating RFID or QR codes enables enhanced asset tracking and supply chain visibility, especially for high-value or hazardous materials.
- Geographic Expansion:Demand is rising in Southeast Asian manufacturing hubs like Vietnam and Indonesia, where industrial chemical and food production is growing.
Industry Challenges
- Recycled Polymer Sourcing:Securing a consistent supply of high-quality recycled polymers that meet performance and regulatory standards, such as REACH, remains a significant operational hurdle.
- Capital Investment:Upgrading production lines for advanced polymer composites or establishing efficient steel pail reconditioning infrastructure requires substantial capital expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Pails Market |
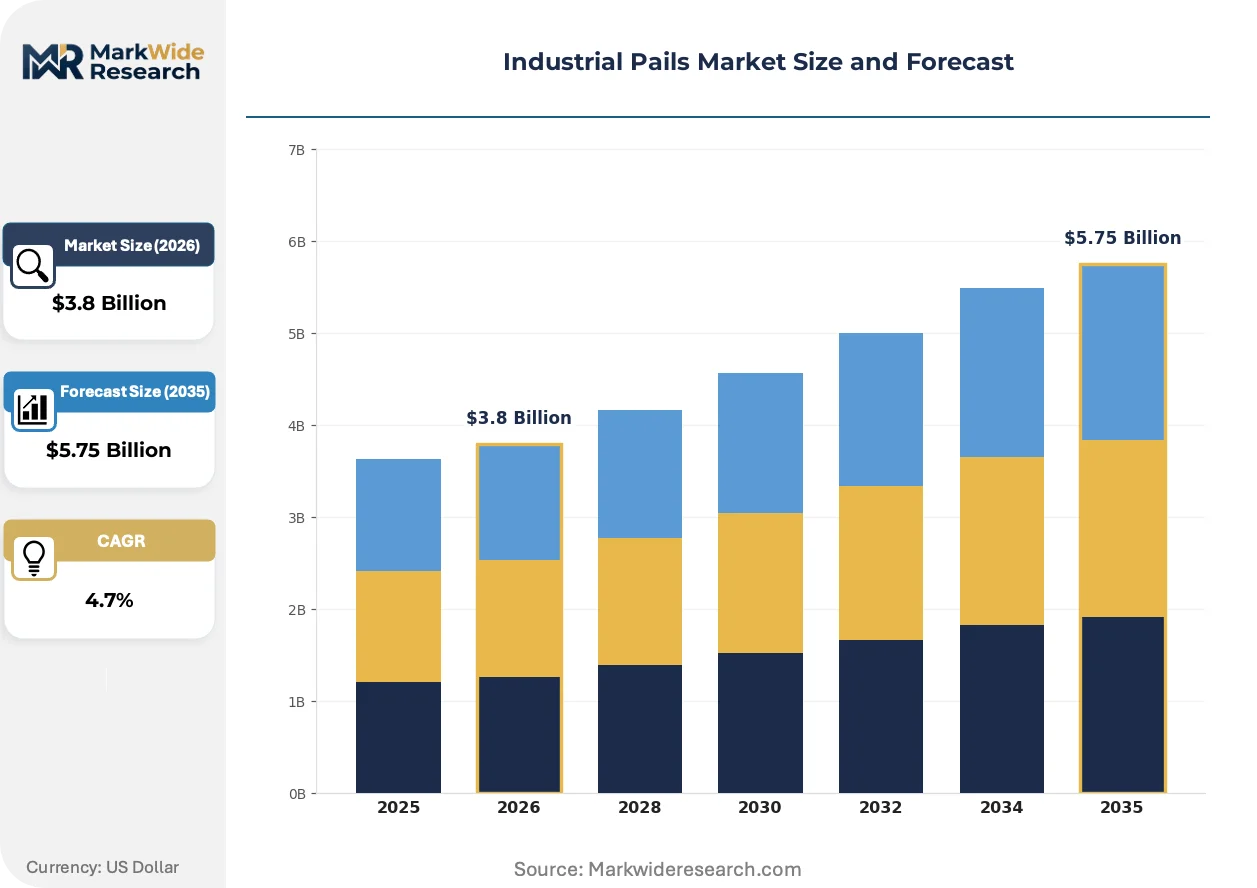
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Steel, Aluminum, High-Density Polyethylene, Polypropylene, Fiberboard Capacity: 5 Liters, 10 Liters, 15 Liters, 20 Liters, 25 Liters Application: Chemicals, Paints & Coatings, Food & Beverage Manufacturing, Pharmaceuticals, Adhesives & Sealants End User Industry: Manufacturing Plants, Construction Firms, Packaging Companies, Laboratories, Oil Refineries |
| Companies Covered | Mauser Packaging Solutions, Berry Global Group, Greif, Time Technoplast Ltd, Schoeller Allibert, FDL Packaging Group, Industrial Container Services, CL Smith, Balmer Lawrie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Pails Market Strategic Shifts & Innovations
Material science advancements are converging with circular economy mandates and digital traceability demands to redefine industrial pail design and lifecycle management. This intersection drives innovation beyond simple containment toward intelligent and sustainable packaging solutions.
Advanced HDPE formulations incorporating post-consumer recycled (PCR) content offer strength and chemical resistance comparable to virgin plastics. Bulk chemical and food ingredient producers are adopting these materials to meet sustainability goals. This material innovation is absorbing market share from traditional steel pails in non-hazardous applications due to lower weight and enhanced recyclability.
Europe's REACH framework and the US Department of Transportation (DOT) hazardous materials rules impose strict controls on chemical substances in packaging. These regulations mandate rigorous testing and documentation, increasing compliance costs and development timelines. Manufacturers of pails for hazardous goods are most affected, prioritizing steel or specialized polymers with established compliance records.
Large-scale buyers are adopting a multi-source model for bulk packaging to mitigate supply risk. This behavior disrupts long-term exclusive agreements with single national providers, favoring suppliers with a flexible, global footprint. The shift is most prominent among multinational corporations in the chemicals sector across North America and Europe.
Industrial Pails Market Segmentation
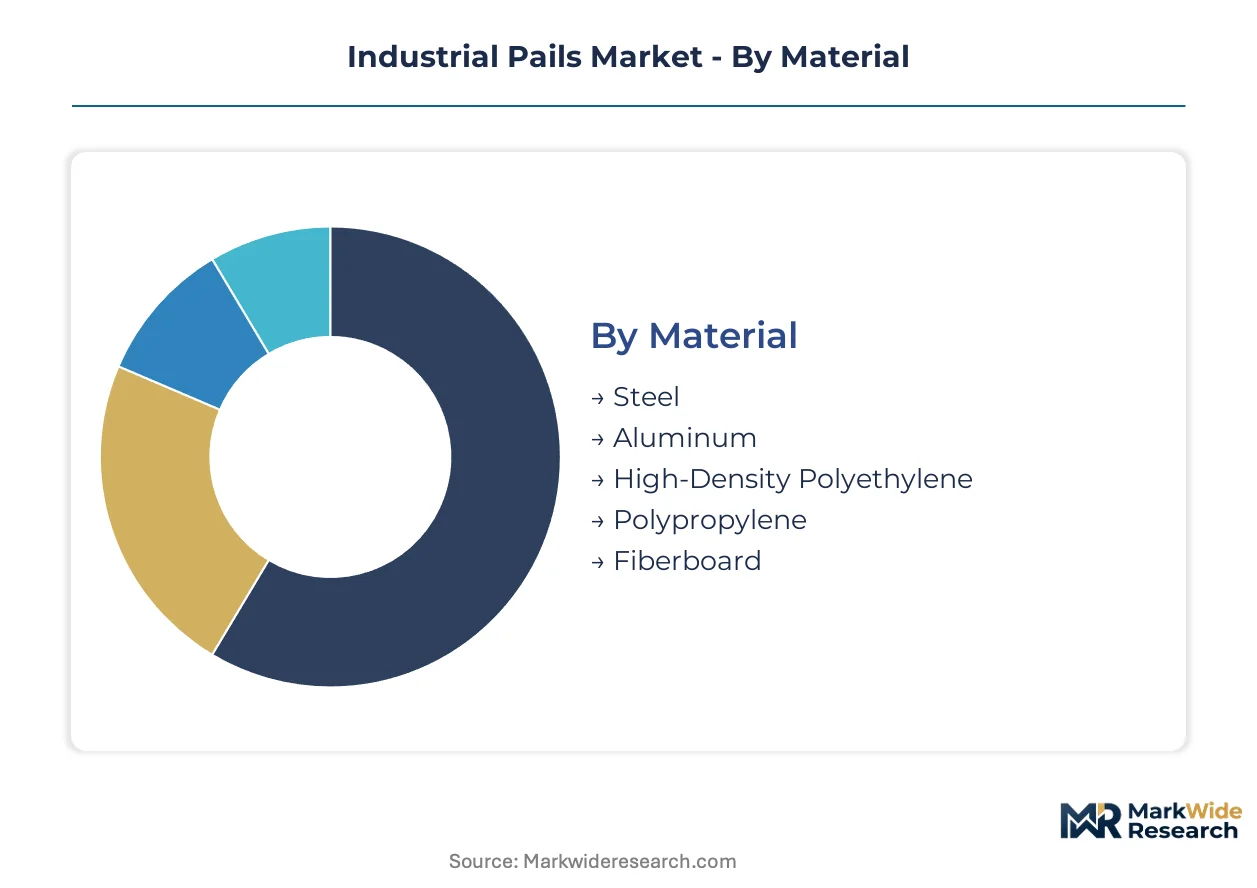
Understanding the industrial pails market through segmentation reveals diverse material requirements, capacity demands, and end-user specifications. This detailed breakdown helps manufacturers tailor product offerings and allocate resources effectively across varied industrial applications.
Material:
The capital intensity of production lines heavily influences material segmentation, with significant investments required for metal forming and polymer injection molding facilities.
- High-Density Polyethylene (HDPE):This polymer offers excellent chemical resistance and cost-effectiveness, making it the dominant material for non-hazardous and general-purpose industrial pails. Demand is concentrating in India's chemical and food processing sectors, driven by its balance of performance and affordability.
- Steel:Steel pails provide superior strength and UN-rated compliance for hazardous materials, often required for paints, solvents, and specialty chemicals. Manufacturers in Europe prioritize steel for reconditioning services, aligning with circular economy mandates.
- Polypropylene:Polypropylene pails offer good chemical resistance and are lighter than HDPE, finding use in specific food and pharmaceutical applications.
- Aluminum:Lightweight and corrosion-resistant, aluminum pails serve niche markets requiring high purity or specific chemical compatibility.
- Fiberboard:These pails are used for dry bulk goods, often where product weight is a concern and chemical resistance is not critical.
Most installed capacity flows through High-Density Polyethylene. Expansion is steepest in Steel.
Capacity:
Market segmentation by capacity reflects the varying bulk packaging needs across different industrial applications and product volumes.
- 20 Liters:This capacity represents a standard size for industrial bulk packaging, widely adopted across the paints, coatings, and general chemical industries. Its demand is consistent in North American and European manufacturing plants for efficient handling and storage.
- 5 Liters:Smaller 5-liter pails cater to specialty chemicals, concentrated additives, and sampling requirements, offering precision for lower-volume applications. The pharmaceuticals sector across Europe and the US frequently utilizes this capacity for high-value ingredients.
- 10 Liters:These pails serve intermediate volume needs, common in the adhesives and sealants market for easier handling.
- 15 Liters:The 15-liter capacity finds application in specific industrial formulations where a medium volume is preferred for transport.
- 25 Liters:As the largest common capacity, 25-liter pails are used for high-volume bulk liquids and solids in the chemical and food processing industries.
The 20 Liters segment captures the largest volume. The 5 Liters segment is gaining share fastest.
Application:
Market segmentation by application highlights the specific performance requirements and regulatory compliance needs for different industrial uses, influencing material choice and design.
- Paints & Coatings:This sector provides stable demand for durable, often UN-rated pails, ensuring secure transport and storage of paint, primers, and industrial coatings. This application drives consistent volume for both steel and HDPE pails in established markets like Germany and the United States.
- Pharmaceuticals:The pharmaceuticals sector demands specialized, contamination-free, and certified pails for active pharmaceutical ingredients and excipients, offering higher-margin opportunities. Strict regulatory frameworks, such as those from the US FDA and Europe's EMA, dictate material and design choices for this application.
- Chemicals:The chemicals segment utilizes a broad range of pails for various industrial and specialty chemicals, with material choice depending on corrosiveness and hazard classification.
- Food & Beverage Manufacturing:This application requires food-grade, often HDPE pails, for ingredients, flavorings, and processed food products, adhering to strict hygiene standards.
- Adhesives & Sealants:Pails for adhesives and sealants need robust construction and chemical compatibility to prevent degradation and ensure product integrity.
Paints & Coatings represents the largest end-use category. Pharmaceuticals offers the highest margin opportunities.
End User Industry:
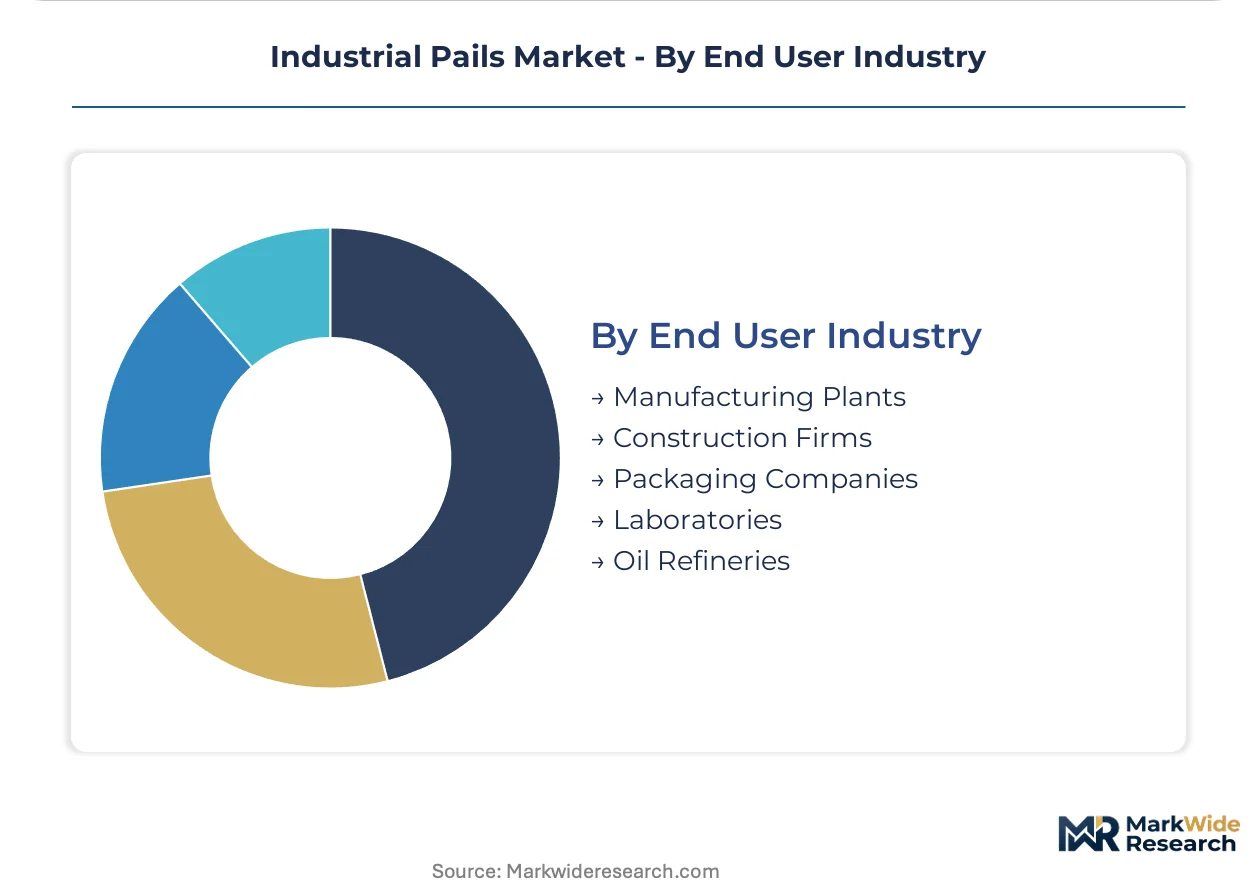
The end-user industry segmentation illustrates how diverse sectors rely on industrial pails for their operational and logistical requirements, from manufacturing to specialized processing.
- Manufacturing Plants:These facilities represent a broad end-user base, consuming pails for raw materials, intermediate products, and finished goods across various industrial processes. Demand from manufacturing plants in Southeast Asian hubs like Vietnam and Indonesia is showing significant expansion.
- Oil Refineries:Oil refineries require specialized, often steel, pails for lubricants, additives, and hazardous by-products, necessitating high durability and UN certification. Operations in the US Gulf Coast and Middle East drive specific demand for these robust containers.
- Construction Firms:Construction firms utilize pails for paints, coatings, sealants, and various building chemicals, emphasizing durability and ease of transport on job sites.
- Packaging Companies:These companies procure pails for re-packaging or as components within larger packaging solutions for their clients.
- Laboratories:Laboratories use smaller capacity pails for chemical reagents, samples, and waste, requiring precise volumes and chemical resistance.
Manufacturing Plants account for the largest volume consumption. Oil Refineries require the most specialized solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial pails market exhibits a regulatory arbitrage, as manufacturers weigh the cost of compliance with stringent environmental standards against the benefits of lower-cost production in regions with less onerous regulations. This dynamic influences investment in advanced materials and reconditioning services. Geographic shifts in manufacturing also impact where pail production concentrates.
India
India's rapid industrial expansion in chemical manufacturing and food processing sectors drives significant demand for industrial pails. The Bureau of Indian Standards (BIS) mandates quality and safety for packaging materials. Production facilities in Maharashtra actively supply these sectors, supporting substantial domestic consumption.
Germany
German demand for industrial pails stems from its robust paints and coatings industry and specialty chemicals sector. Europe's REACH framework and the EU Green Deal significantly influence material selection and recycling efforts. Manufacturers in North Rhine-Westphalia focus on optimizing steel pail reconditioning services.
United States
The United States market sees steady demand from its large paints and coatings and pharmaceuticals industries. US Department of Transportation (DOT) regulations govern the transport of hazardous materials, impacting pail design. Chemical and petrochemical operations along the US Gulf Coast require specialized, UN-rated containers.
Vietnam
Growing industrial chemical and food production fuels significant demand for pails in Vietnam's manufacturing hubs. The country's environmental protection laws increasingly influence packaging material choices for local industries. Manufacturing and logistics centers around Ho Chi Minh City are expanding their capacity for industrial packaging.
Indonesia
Indonesia's expanding food processing and chemical industries generate substantial requirements for industrial pails. National standards (SNI) guide product quality and safety for packaging materials within the country. Industrial zones in West Java and around Jakarta are increasing their procurement of bulk containers.
Industrial Pails Market Key Industry Players
Established producers occupy the standard tier, while emerging entrants pursue niche opportunities in advanced materials and specialized applications. The market structure exhibits a tiered consolidation, with large players leveraging extensive global footprints to serve multinational clients. Strategic archetypes include global diversified suppliers, steel pail specialists, and polymer solution providers focused on regional demand. Capacity expansion and portfolio diversification into higher-margin segments represent dominant competitive moves.
Global packaging specialists such as Mauser Packaging Solutions exemplify the strategy of leveraging an extensive global production footprint to serve multinational clients across diverse sectors. Greif, a long-standing industrial packaging provider, represents the archetype focused on steel pail manufacturing, particularly for hazardous materials requiring UN-rated compliance. Meanwhile, Time Technoplast Ltd. occupies a position as a specialist in advanced polymer-based solutions, catering to industrial customers primarily within the Asian market. These players collectively illustrate the varied approaches to market penetration and specialization.
| Leading Market Players |
|---|
| Mauser Packaging Solutions |
| Berry Global Group |
| Greif |
| Time Technoplast Ltd |
| Schoeller Allibert |
| FDL Packaging Group |
| Industrial Container Services |
| CL Smith |
| Balmer Lawrie |
| Others |
Cost & Logistics Intelligence
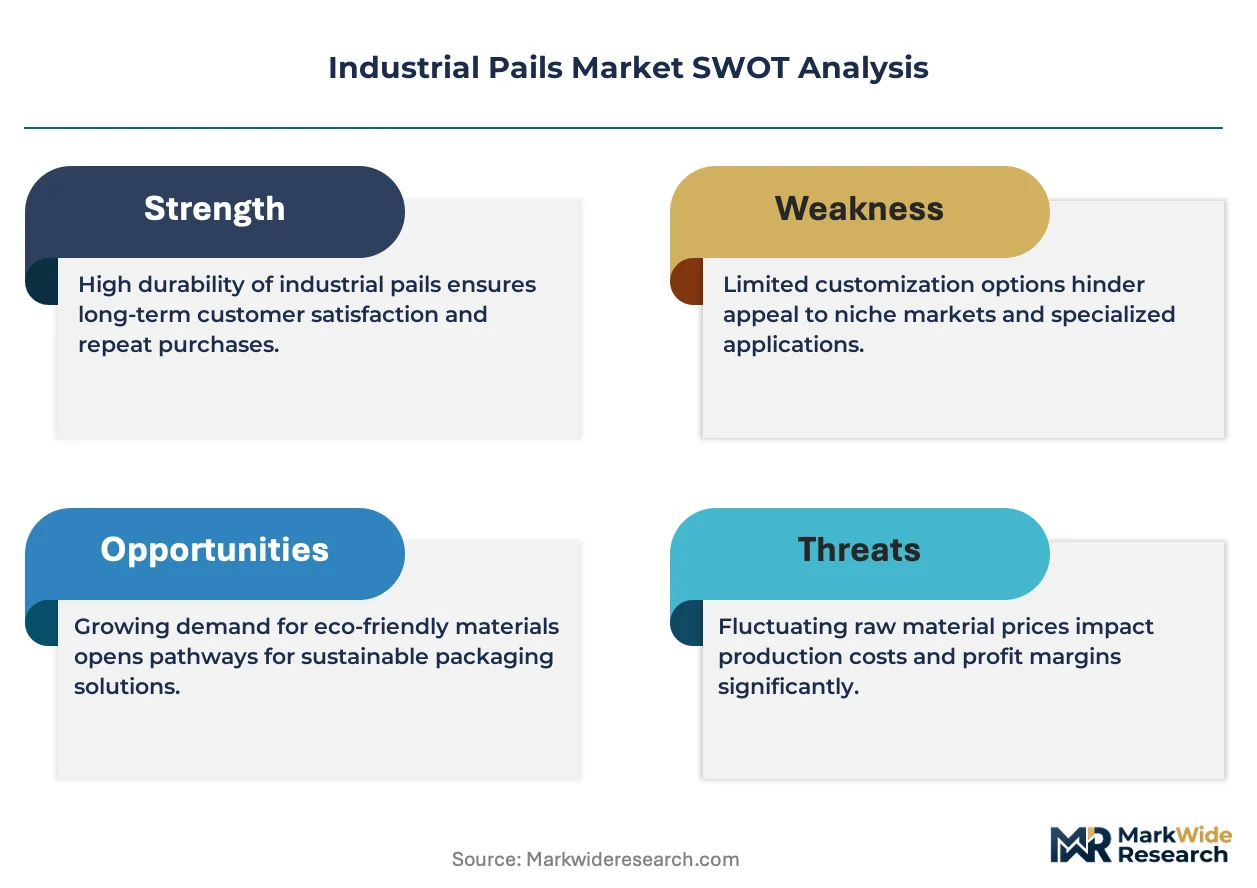
High-density polyethylene resin price volatility directly impacts manufacturing costs, feeding through to contract-based pricing tiers for bulk chemical producers and affecting margins for industrial pail manufacturers.
Pricing Analysis
Input cost pass-through from volatile raw material prices, particularly for steel and HDPE resin, frequently influences industrial pail pricing. The dominant pricing model is contract-based long-term offtake for large volume buyers, with transactional per-unit pricing for smaller orders. Price differentiation stems from UN-rating compliance for hazardous goods and the volume scale of procurement. Pricing pressure stems from the substitution threat posed by flexible intermediate bulk containers. The pharmaceuticals sector exhibits the least price sensitivity, prioritizing specialized, certified pails over cost, while general manufacturing plants are most price-sensitive.
Supply Chain Analysis
HDPE resin supply relies heavily on petrochemical production facilities in North America and Asia, while steel coil production concentrates in China, India, and Europe. Raw material dependencies include both virgin HDPE resin and high-quality post-consumer recycled content. A structural supply chain risk is commodity price volatility for key inputs. Distribution runs through direct sales channels for large industrial clients and regional distributors serving smaller, fragmented buyer bases in countries like India and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a late-cycle quality story, driven by a demand shift toward specialized, high-performance pails with enhanced recyclability and smart features.
For Market Incumbents: To counter raw material volatility and the substitution threat from alternative packaging, incumbents must accelerate investment in advanced recycling-friendly polymers. Expanding steel pail reconditioning services in established European markets also provides a defensive lever. Diversifying the global production footprint, particularly into Southeast Asian manufacturing hubs, mitigates regional supply risks and captures emerging demand.
For New Entrants and Emerging Players: Begin with targeting high-margin segments such as pharmaceuticals and specialty chemicals, which prioritize specialized, contamination-free, and certified pails. A viable go-to-market angle involves offering integrated smart packaging solutions with RFID or QR codes for enhanced asset tracking. Geographic expansion into underpenetrated manufacturing hubs like Vietnam and Indonesia also presents a strategic entry point.
For Investors and Strategic Acquirers: Consolidation pressure builds where capital investment for advanced polymer production or reconditioning infrastructure is substantial. Long-term viability rests on suppliers who can navigate stringent regulatory frameworks and meet circular economy mandates. The ideal acquisition target archetype is a polymer specialist with established compliance records or a reconditioning service provider with strong regional networks. Adoption rates of post-consumer recycled content in pails serve as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Increases market reach and captures growth from expanding industrial production in Vietnam and Indonesia. |
| Investment in Advanced Polymer R&D | Develops materials meeting chemical resistance and recyclability mandates like the EU Green Deal. |
| Optimize Steel Pail Reconditioning Services | Aligns with circular economy targets and extends product lifecycle for hazardous material containers. |
| Integrate Smart Packaging Technologies | Enhances supply chain visibility and asset tracking for high-value or hazardous industrial materials. |
| Acquisition of Specialized Polymer Manufacturers | Expands product portfolio into high-margin segments like pharmaceuticals and specialty chemicals. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Primary research involved conversations with procurement managers, R&D directors, plant managers, and regulatory compliance officers across the industrial pails value chain. Secondary data sources included industry association reports, government trade statistics, and company annual reports, triangulated for accuracy.
The forecast framework employs a segment-weighting approach, analyzing market dynamics across material, capacity, application, end-user industry, and UN-rating compliance level. Compound annual growth rates were derived by extrapolating historical trends, assessing growth catalysts, and incorporating market restraints over the projection horizon. Industry-specific forecast inputs included raw material price forecasts for HDPE and steel, alongside industrial production indices for key manufacturing regions.
Several conditions sit outside the modeled scope, including short-term geopolitical disruptions or unforeseen technological breakthroughs outside current R&D. Forecasts reflect assumptions documented through extensive primary and secondary research. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Nestable Drums Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Dunnage Racks Market
Industrial Packaging
Slip Sheets Market
Industrial Packaging
MENA Industrial Packaging Market
Industrial Packaging
Corrugated Bulk Bins Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Cone Bottom Tank Market
Industrial Packaging
Middle East and Africa Octabin Market
Industrial Packaging
Industrial Bulk Packaging Market
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Fiber Drums Market
Industrial Packaging
Anti-Static Reel Racks Market
Industrial Packaging
Corrugated Octabins Market
Industrial Packaging
Industrial Filling Machine Market
Industrial Packaging
Corrugated Automotive Packaging Market