
 Anti-Static Liners Market | 2026-2036
Anti-Static Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Static Liners Market Outlook
A shift from single-source to multi-source procurement of conductive films is expanding as electronics OEMs diversify supplier bases to mitigate resin price volatility. 3M leverages its patent portfolio in fluoropolymer coatings to anchor premium cleanroom liner demand. Berry Global competes through vertical integration into blown film extrusion, sustaining margin control across polyethylene grades. DuPont de Nemours specializes in high-performance composite liners, positioning its Kapton-derived substrates for aerospace static-dissipative applications.
Anti-static liners are engineered films or sheets incorporating conductive additives—carbon black, metal oxides, or inherently dissipative polymers—manufactured via coextrusion or lamination to maintain surface resistivity between 10^4 and 10^11 ohms per square, primarily shielding sensitive electronic components, active pharmaceutical ingredients, and volatile chemicals from electrostatic discharge damage. Polyethylene formulations dominate unit volume due to cost-efficient extrusion and broad chemical compatibility, though composite structures capture disproportionate margin pools in aerospace and semiconductor cleanrooms where multi-layer barrier performance commands specification premiums. End-user demand from pharmaceutical packaging is accelerating as biologics manufacturers adopt anti-static primary containment for lyophilized and protein-based therapies.
EPA guidelines on volatile organic compound emissions from solvent-based coating processes and FDA cGMP requirements for pharmaceutical primary packaging materials shape formulation choices and manufacturing site qualifications in the United States. ECHA REACH restrictions on carbon black feedstock purity and EU MDR traceability mandates for medical device packaging tighten compliance burdens for exporters serving European electronics and healthcare markets. Stakeholders must monitor evolving surface resistivity test standards under IEC 61340 and ANSI/ESD S20.20 as semiconductor fabrication nodes advance toward sub-3nm architectures where electrostatic sensitivity thresholds tighten measurably.
Market Dynamics
Semiconductor fabrication nodes advancing toward sub-3nm architectures are tightening electrostatic sensitivity thresholds, forcing anti-static liner specifications to compress surface resistivity windows and validate performance across wider temperature and humidity ranges.
Growth Catalysts
- Biologics containment protocols:Protein-based and lyophilized therapies require anti-static primary packaging to prevent electrostatic aggregation of active pharmaceutical ingredients during fill-finish operations.
- REACH carbon black purity mandates:ECHA restrictions on feedstock quality are accelerating qualification of premium conductive additives for medical device and electronics exporters serving European markets.
- Cleanroom expansion in South Korea:Memory and logic chip foundries are scaling Class 10 and Class 1 cleanroom capacity, driving specification-grade liner procurement for wafer shipping containers.
Market Restraints
- Polyethylene resin price volatility:Naphtha-derived feedstock costs fluctuate with crude oil benchmarks, compressing blown film extrusion margins for commodity-grade liner producers.
- Carbon black supply concentration:High-purity conductive grades depend on a limited supplier base in North America and Europe, creating qualification bottlenecks for REACH-compliant formulations.
- Fluoropolymer coating cost barriers:Perfluorinated surface treatments for aerospace applications face raw material scarcity and EPA volatile organic compound scrutiny, limiting adoption outside premium segments.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO cGMP alignment with FDA standards is positioning domestic injectables producers to adopt anti-static primary containment for export markets.
- Inherently dissipative polymer convergence:Polyether block amide and ionomer technologies are displacing carbon black in medical device packaging where particulate shedding is prohibited.
- Direct-to-fab distributor models:Electronics OEMs in Germany and Taiwan are bypassing traditional packaging distributors to secure lot-traceable liner supply with embedded RFID authentication.
Industry Challenges
- IEC 61340-5-1 auditor certification scarcity:Qualified electrostatic discharge control assessors are concentrated in Japan and the United States, delaying facility qualification timelines for Southeast Asian cleanroom operators.
- Multi-layer lamination capex intensity:Coextrusion lines with inline corona treatment and resistivity monitoring require capital commitments that strain mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Static Liners Market |
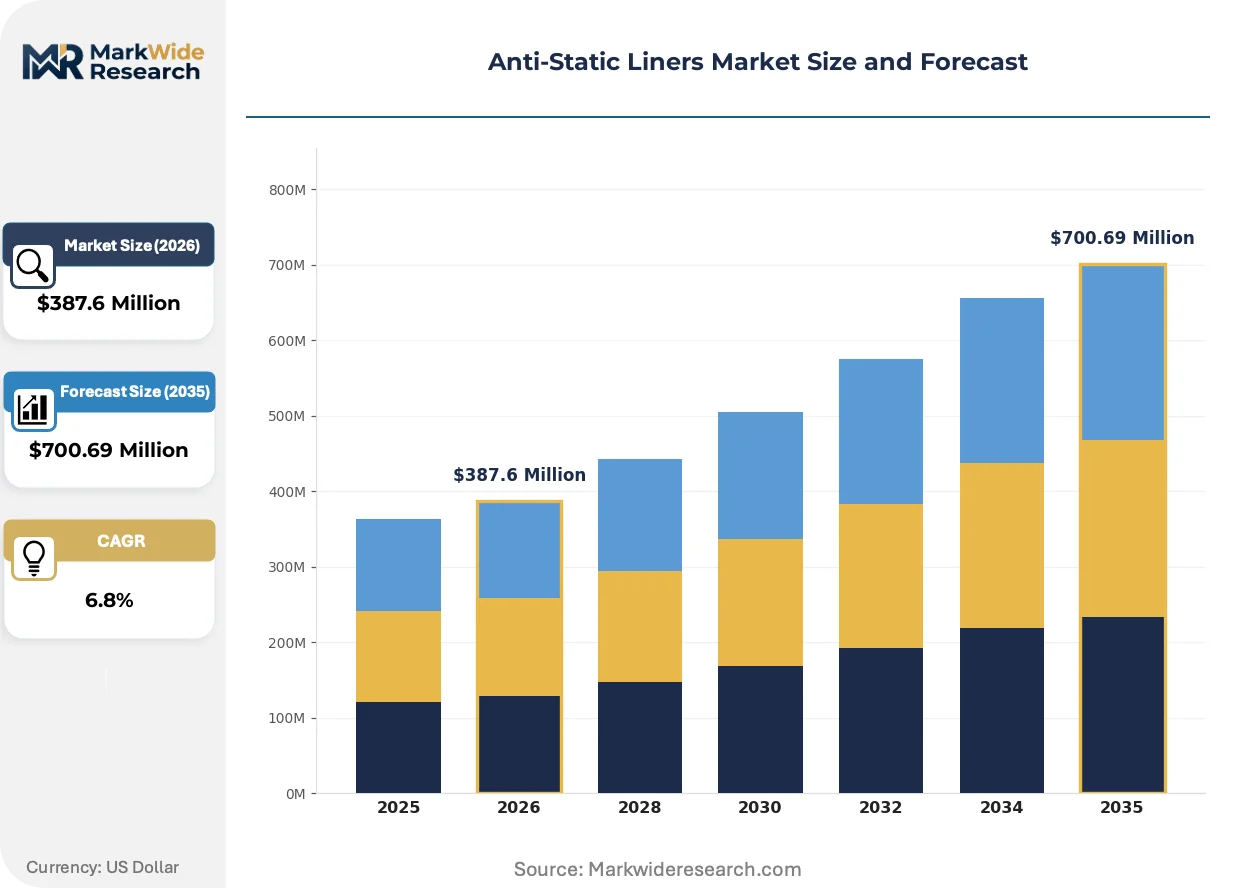
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Composite End User: Electronics, Pharmaceutical, Aerospace, Automotive Thickness: Thin, Medium, Thick, Extra Thick Application: Packaging, Transportation, Storage, Cleanroom |
| Companies Covered | 3M, Sealed Air Corporation, Berry Global, DuPont de Nemours, Amcor plc, Pregis Corporation, Clariant, BASF SE, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Static Liners Market Strategic Shifts
Material science advances and regulatory harmonization efforts are compressing development cycles for next-generation static-dissipative films, while procurement digitization is reshaping how specifications transmit from OEMs to converter networks.
Water-based polyurethane surface coatings with carbon nanotube dispersions are decentralizing cleanroom liner production geography. Korean and Taiwanese electronics packaging specialists are adopting these formulations to eliminate solvent-based curing equipment. The technology is decentralizing manufacturing footprints away from traditional fluoropolymer coating centers in the United States and Germany.
EU MDR traceability mandates for medical device packaging are forcing anti-static liner suppliers to implement serialized production records and blockchain-enabled chain-of-custody documentation. European converters serving orthopedic implant manufacturers face the steepest compliance burdens. The regulation is compressing supplier qualification timelines and favoring vertically integrated film producers with captive resin compounding capabilities.
Electronics OEM procurement teams are consolidating liner specifications across multiple fab locations to leverage volume-based pricing and reduce supplier management overhead. Memory chip manufacturers in South Korea and logic foundries in Taiwan are leading this consolidation. The shift is visible most acutely in semiconductor capital equipment supply chains where single-source qualification for pan-Asian operations is replacing regional supplier fragmentation.
Anti-Static Liners Market Segmentation
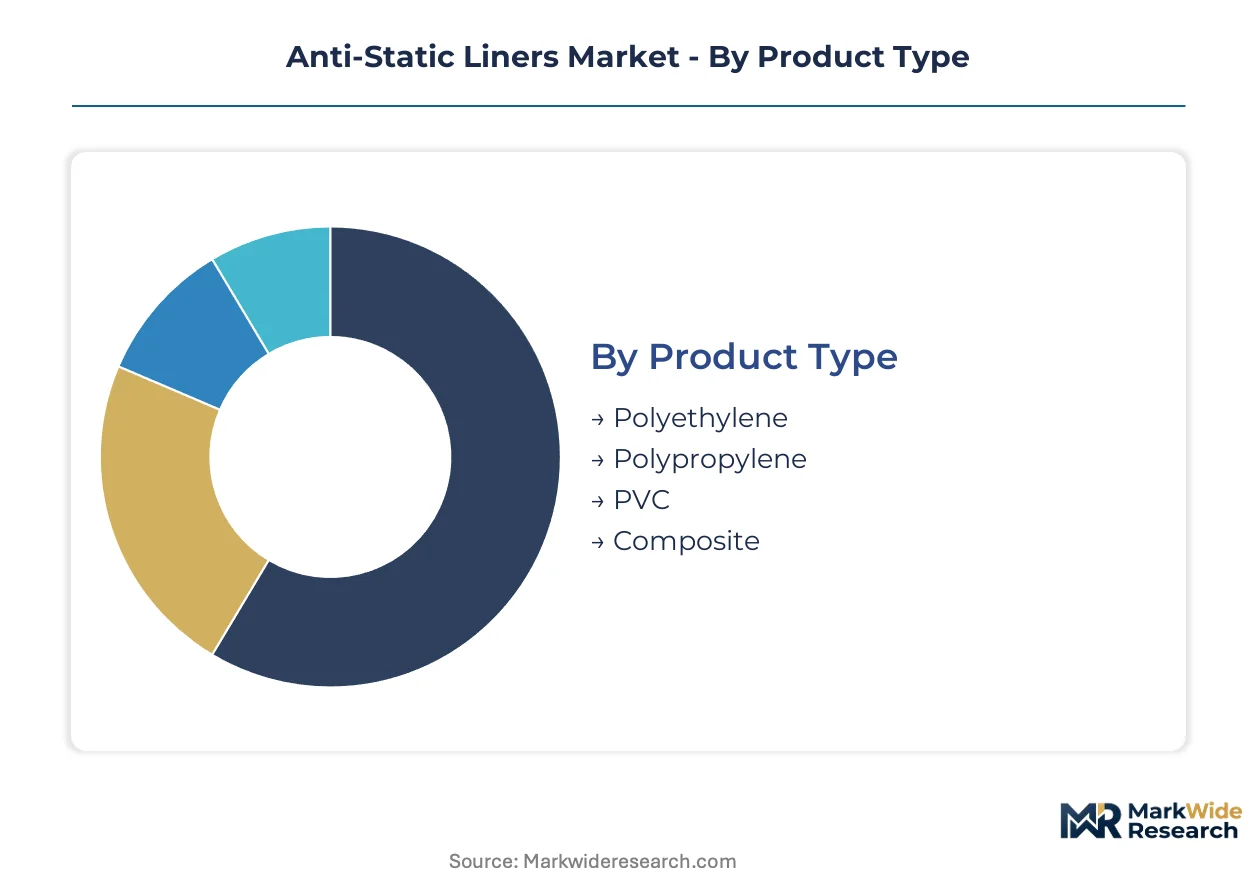
Segmentation in anti-static liners reveals how material chemistry, end-use criticality, and dimensional precision create divergent margin structures. Specification intensity varies dramatically across semiconductor fabs versus commodity electronics logistics.
Product Type:
Customization intensity spans from commodity extrusion to multi-layer barrier engineering, with formulation complexity determining qualification timelines and pricing power.
- Polyethylene:Blown film extrusion of linear low-density grades dominates unit economics, with carbon black loadings between 15-35% achieving surface resistivity targets. Electronics contract manufacturers in South Korea and Taiwan specify this grade for wafer shipping containers, though naphtha feedstock volatility compresses converter margins unpredictably.
- Composite:Multi-layer laminates combining polyimide substrates with fluoropolymer coatings capture specification premiums in aerospace and sub-3nm semiconductor cleanrooms. Demand concentrates at Boeing's Everett facility and ASML's EUV tool supply chain, where outgassing specifications and temperature cycling resistance command 4-5x material cost multiples over commodity films.
- Polypropylene:Biaxially oriented films with inherently dissipative polymer blends serve pharmaceutical blister packaging where carbon black particulate shedding violates FDA cGMP requirements.
- PVC:Calendered formulations with migratory antistatic additives retain niche presence in automotive component trays despite REACH restrictions on plasticizer chemistries.
Most installed capacity flows through Polyethylene. Expansion is steepest in Composite.
End User:
End-use segmentation tracks directly to regulatory burden intensity, with medical device and aerospace applications imposing the steepest traceability and qualification requirements.
- Electronics:Wafer shipping containers, chip trays, and component reels require IEC 61340-5-1 compliant surface resistivity between 10^4 and 10^11 ohms per square. Memory foundries in South Korea and logic fabs in Taiwan are consolidating specifications across pan-Asian operations, reducing qualified supplier lists from 12 to 4-6 per commodity category.
- Pharmaceutical:Anti-static primary containment for lyophilized and protein-based therapies prevents electrostatic aggregation during fill-finish operations. Biologics manufacturers in Germany and Massachusetts are driving adoption as EU MDR traceability mandates and FDA cGMP requirements tighten simultaneously.
- Aerospace:Kapton-derived substrates with static-dissipative coatings serve satellite and aircraft wiring harness applications where outgassing and radiation resistance specifications apply.
- Automotive:Component trays for electric vehicle battery modules and sensor assemblies represent emerging specification volume as EV production scales.
Electronics commands the largest specification volume. Pharmaceutical is climbing the fastest as biologics capacity expands.
Thickness:
Dimensional segmentation aligns with barrier performance requirements and mechanical durability needs across handling cycles.
- Thin:Films below 50 microns serve single-use pharmaceutical pouches and lightweight electronics component packaging where flexibility and material minimization drive selection.
- Medium:50-100 micron gauges balance puncture resistance with cost efficiency for standard semiconductor wafer shipping containers.
- Thick:100-200 micron structures provide structural rigidity for reusable cleanroom tote liners and aerospace component trays.
- Extra Thick:Above 200 micron specifications address heavy-duty transportation dunnage and specialized chemical containment where multi-layer barrier properties integrate with static control.
Medium thickness carries the highest shipment volume. Extra Thick is gaining share fastest in aerospace and chemical logistics applications.
Application:
Application segmentation distinguishes between passive protection and active cleanroom integration, with the latter commanding qualification premiums.
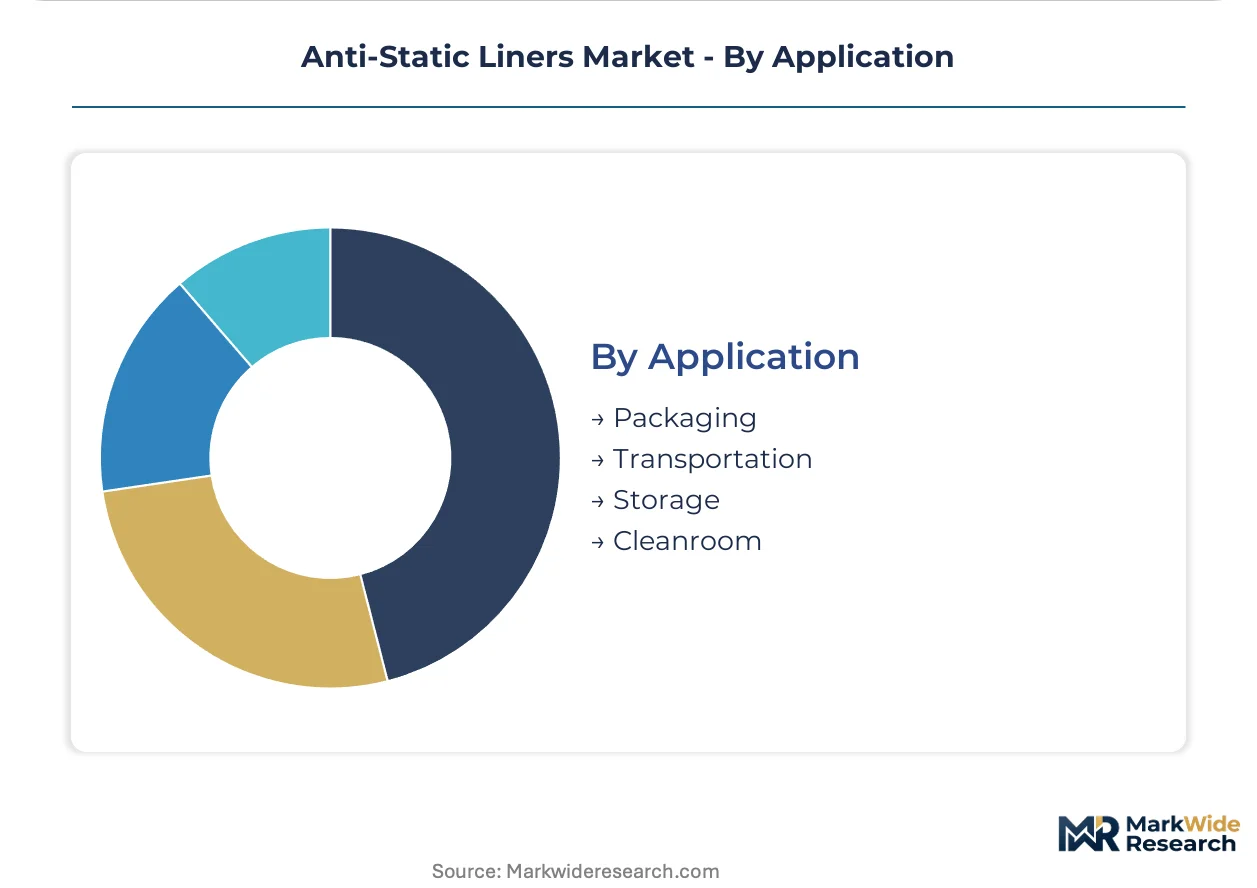
- Cleanroom:Class 10 and Class 1 compatible liners with inline particulate monitoring and lot-traceable RFID authentication serve EUV lithography and advanced packaging operations. South Korean memory foundries are scaling procurement fastest, with direct-to-fab distributor models replacing traditional packaging intermediaries.
- Packaging:Primary and secondary containment for electronics, pharmaceutical, and chemical products represents the broadest volume category, spanning commodity to specification grades.
- Storage:Long-term archival applications for sensitive electronic components and active pharmaceutical ingredients require stable surface resistivity across humidity and temperature cycling.
- Transportation:Dunnage and protective inserts for automotive and aerospace supply chains emphasize puncture resistance and electrostatic discharge protection during multi-modal logistics.
Packaging absorbs the majority of resin volume. Cleanroom is expanding most quickly as semiconductor fabrication nodes advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean memory foundries anchor specification-grade demand as semiconductor fabrication nodes advance toward sub-3nm architectures. Electronics OEM procurement teams in Taiwan and Germany are consolidating supplier bases to reduce qualification overhead across multi-fab operations.
South Korea
Samsung Electronics and SK Hynix are scaling Class 1 cleanroom capacity for EUV lithography, driving lot-traceable liner procurement with embedded RFID authentication. MFDS pharmaceutical cGMP alignment with FDA standards accelerates adoption for biologics export manufacturing. Busan-Ulsan hosts specialized converter operations serving both semiconductor and pharmaceutical packaging demand.
United States
Boeing's Everett facility and SpaceX manufacturing operations in Texas specify Kapton-derived composite liners for aerospace static-dissipative applications. EPA volatile organic compound guidelines constrain solvent-based coating processes, favoring water-based polyurethane formulations. Greater Boston biologics manufacturers in Massachusetts drive anti-static primary containment adoption for protein-based therapies.
Germany
ASML's EUV tool supply chain and orthopedic implant manufacturers impose the steepest EU MDR traceability burdens on liner suppliers. ECHA REACH restrictions on carbon black feedstock purity accelerate qualification of premium conductive additives. Bavaria's cleanroom equipment cluster concentrates specification development for semiconductor capital equipment applications.
China
Yangtze Memory Technologies and SMIC are expanding domestic sourcing of anti-static packaging materials for wafer shipping containers. Evolving GB standards under SAMR tighten surface resistivity testing protocols for electronics exporters. Yangtze River Delta converter networks are scaling coextrusion capacity to serve memory foundry demand.
India
CDSCO cGMP alignment with FDA standards positions domestic injectables producers to adopt anti-static primary containment for export markets. Hyderabad and Bangalore pharmaceutical manufacturing clusters are qualifying inherently dissipative polymer formulations where carbon black particulate shedding is prohibited. Maharashtra's contract manufacturing organizations drive specification-grade procurement for European and North American pharmaceutical clients.
Anti-Static Liners Market Competitive Environment
Global majors compete with regional champions across specification intensity and vertical integration depth. The vendor base stratifies between diversified materials conglomerates with captive resin compounding, specialized film converters with cleanroom certification, and regional packaging distributors with direct-to-fab logistics capabilities. Three archetypes dominate: fluoropolymer coating specialists commanding aerospace premiums, blown film extruders competing on polyethylene grade cost efficiency, and composite laminators serving multi-layer barrier requirements. Competitive moves center on backward integration into resin compounding and geographic expansion through distributor acquisition.
Among diversified materials conglomerates, 3M leverages its patent position in fluoropolymer surface treatments, while DuPont de Nemours occupies the high-performance composite tier through polyimide substrate specialization. Berry Global represents the scale-driven extrusion archetype with blown film capacity across multiple polyethylene grades. These three anchors illustrate how competitive positioning diverges between premium specification capture and commodity volume efficiency.
| Leading Market Players |
|---|
| 3M |
| Sealed Air Corporation |
| Berry Global |
| DuPont de Nemours |
| Amcor plc |
| Pregis Corporation |
| Clariant |
| BASF SE |
| Evonik Industries AG |
| Others |
Value Chain & Pricing Dynamics
Water-based polyurethane coatings with carbon nanotube dispersions are decentralizing cleanroom liner production geography while compressing cost economics for mid-tier converters. This formulation shift simultaneously reduces solvent-based curing capital requirements and fragments supply concentration away from traditional fluoropolymer coating centers in the United States and Germany.
Pricing Analysis
Input-cost pass-through from naphtha-derived polyethylene resin fluctuations dominates pricing volatility for commodity-grade blown film extrusion. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61340-5-1 certified cleanroom liners from general electronics packaging and automotive component trays. Cost compression in standard-grade polyethylene is intensifying because South Korean and Taiwanese OEMs are consolidating supplier lists from twelve to four per category. Electronics contract manufacturers show highest price sensitivity, while aerospace OEMs at Boeing's Everett facility accept 4-5x material cost multiples for Kapton-derived composite specifications.
Supply Chain Analysis
Domestic-content mandates under China's evolving GB standards and India's CDSCO cGMP alignment are reshaping sourcing patterns for export-oriented pharmaceutical and electronics packaging. High-purity conductive carbon black concentrates in North American and European supplier bases, while blown film extrusion capacity clusters in the Yangtze River Delta and Busan-Ulsan corridor. Single-source vulnerability around REACH-compliant carbon black feedstock creates qualification bottlenecks for medical device exporters serving European markets. Distribution runs through direct-to-fab models in South Korea and Taiwan, bypassing traditional packaging intermediaries for lot-traceable supply with embedded RFID authentication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-static liners market functions as a stable compounder anchored by irreversible semiconductor fabrication node advancement toward sub-3nm architectures, which mandates specification-grade procurement regardless of cyclical electronics demand fluctuations.
For Market Incumbents: Deploy captive resin compounding capabilities to defend margin position against naphtha feedstock volatility and emerging water-based coating competitors from Korea and Taiwan. Accelerate IEC 61340-5-1 auditor certification programs in Southeast Asia to capture cleanroom qualification timelines that rivals cannot match. Consolidate distributor networks through acquisition to secure direct-to-fab relationships with Samsung Electronics and SK Hynix memory foundries. For New Entrants and Emerging Players: Inherently dissipative polymer formulations displacing carbon black in medical device packaging offer the most penetrable white-space target, particularly for orthopedic implant manufacturers facing EU MDR traceability mandates. Target Maharashtra contract manufacturing organizations serving European pharmaceutical clients with CDSCO-FDA aligned cGMP documentation capabilities. Pursue qualification partnerships with biologics manufacturers in Greater Boston and Germany as the fastest route to specification credibility. For Investors and Strategic Acquirers: Roll-up economics work for regional cleanroom-certified film converters because OEM procurement consolidation is reducing qualified supplier lists faster than organic capacity expansion can replace them. Five-to-ten year viability hinges on exposure to semiconductor capital equipment supply chains rather than commodity electronics logistics. Monitor ASML EUV tool shipment volumes as the critical inflection signal for specification-grade composite liner demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Additive Compounding | Captive supply of REACH-compliant carbon black secures qualification timelines for European medical device exports. |
| Water-Based Coating Capacity Expansion | Elimination of solvent-based curing equipment reduces EPA VOC compliance burdens and capital intensity. |
| Direct-to-Fab Distribution Model Implementation | Lot-traceable supply with embedded RFID authentication captures South Korean memory foundry procurement consolidation. |
| Inherently Dissipative Polymer R&D Investment | Polyether block amide and ionomer technologies penetrate medical device packaging where particulate shedding is prohibited. |
| IEC 61340-5-1 Auditor Certification Program | Qualified assessor scarcity in Southeast Asia creates service revenue and customer lock-in for facility qualification. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cleanroom operations managers, pharmaceutical packaging engineers, semiconductor procurement leads, and blown film extrusion plant directors with secondary validation through SEC filings, customs and trade data, IEC standard revision documentation, and ECHA REACH restriction updates. Bottom-up demand modeling across end-use segments triangulated against top-down resin consumption estimates from polyethylene grade producers.
Comparable-period anchoring to historical semiconductor fabrication node transitions and cleanroom capacity buildouts structured the projection horizon across material chemistry, thickness specification, and end-use criticality dimensions. CAGRs derived from segment-level volume trajectories weighted by specification intensity premiums, with inputs including ASML EUV tool shipment patterns, MFDS pharmaceutical cGMP inspection schedules, and SAMR GB standard evolution timelines.
The model holds under continued sub-3nm semiconductor node advancement and stable REACH carbon black purity enforcement; deviation in naphtha-crude price correlation or ECHA feedstock restriction scope would shift polyethylene grade margin assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Microwave Packaging Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Global Liquid Packaging Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Packaging Supplies Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Construction Films Market
Packaging Materials
Squeeze Tube Market
Packaging Materials
Tube Packaging Market
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Paint Packaging Market
Packaging Materials
Chemical Packaging Market
Packaging Materials
Reel in Box Market
Packaging Materials
Foil Laminates Market