
 Wooden Crates Market | 2026-2036
Wooden Crates Market Size, Share, and Industry Trends Forecast 2026-2036
Wooden Crates Market Analytics
Southeast Asian plywood mills is decoupling from traditional hardwood feedstocks as plantation eucalyptus expands. Brambles Limited (CHEP) leverages its pooled pallet network to dominate closed-loop logistics for automotive parts. Greif Inc. anchors North American chemical packaging through controlled distribution of custom-built wooden containers. NEFAB specializes in engineered wood crates for semiconductor equipment, competing on vibration-dampening specifications.
Wooden crates are rigid shipping containers fabricated from sawn lumber or engineered panels, typically assembled with nails, screws, or steel banding to withstand compression loads during transit and storage. Standard ISPM-15 heat treatment or methyl bromide fumigation marks compliance for international phytosanitary movement. Pallet formats lead volume due to forklift compatibility and warehouse racking standardization, while engineered wood segments capture margin from aerospace and electronics clients requiring moisture-stable dimensional tolerances. Boxes and bins serve bulk agricultural harvests where ventilation slat design reduces spoilage rates.
The USDA Animal and Plant Health Inspection Service enforces ISPM-15 equivalence agreements that determine which national wood packaging regimes gain US market access, directly shaping exporter compliance costs. The EU Deforestation Regulation and ECHA REACH restrictions on preservative chemistry jointly redirect material sourcing toward certified plantation timber. Stakeholders must monitor emerging national traceability mandates and calibrate supply chain certification investments against destination-market entry requirements.
Market Dynamics
EU Deforestation Regulation geolocation mandates are forcing exporters to rebuild traceability infrastructure from forest gate to port of entry, compressing margins for uncertified suppliers while advantaging plantation-timber networks.
Growth Catalysts
- ISPM-15 Compliance Infrastructure:Heat-treatment capacity expansion at Vietnamese mills near Ho Chi Minh City enables direct US market access for ASEAN exporters.
- Cold-Chain Deepening:Latin American fresh produce exporters are scaling ventilated crate procurement as refrigerated logistics penetrate inland growing regions.
- Semiconductor Equipment Logistics:Vibration-dampening engineered wood specifications are displacing metal alternatives for lithography tool transport.
Market Restraints
- Plantation Timber Bottlenecks:Eucalyptus maturation cycles in Southeast Asia create 7-12 year feedstock lags that constrain plywood mill expansion.
- Methyl Bromide Phase-Out:ECHA REACH restrictions on fumigation chemistry force capital retooling toward heat-treatment kilns.
- Plastic Pallet Substitution:Closed-loop automotive logistics operators are adopting injection-molded alternatives for multi-trip durability.
Strategic Opportunities
- EU Traceability Premium:Geolocation-certified crates command price premiums as EUDR enforcement tightens at Rotterdam and Hamburg ports.
- Aerospace Precision Packaging:Moisture-stable engineered panels are penetrating satellite component logistics where dimensional tolerance is critical.
- Digital Chain-of-Custody:Blockchain-verified certification is emerging as a procurement filter for European retail supply chains.
Industry Challenges
- Treatment Certification Backlogs:ISPM-15 accreditation delays at understaffed national plant protection offices stall export readiness.
- Skilled Joinery Shortage:Precision crate fabrication for semiconductor equipment requires trained carpenters that vocational pipelines fail to replenish.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wooden Crates Market |
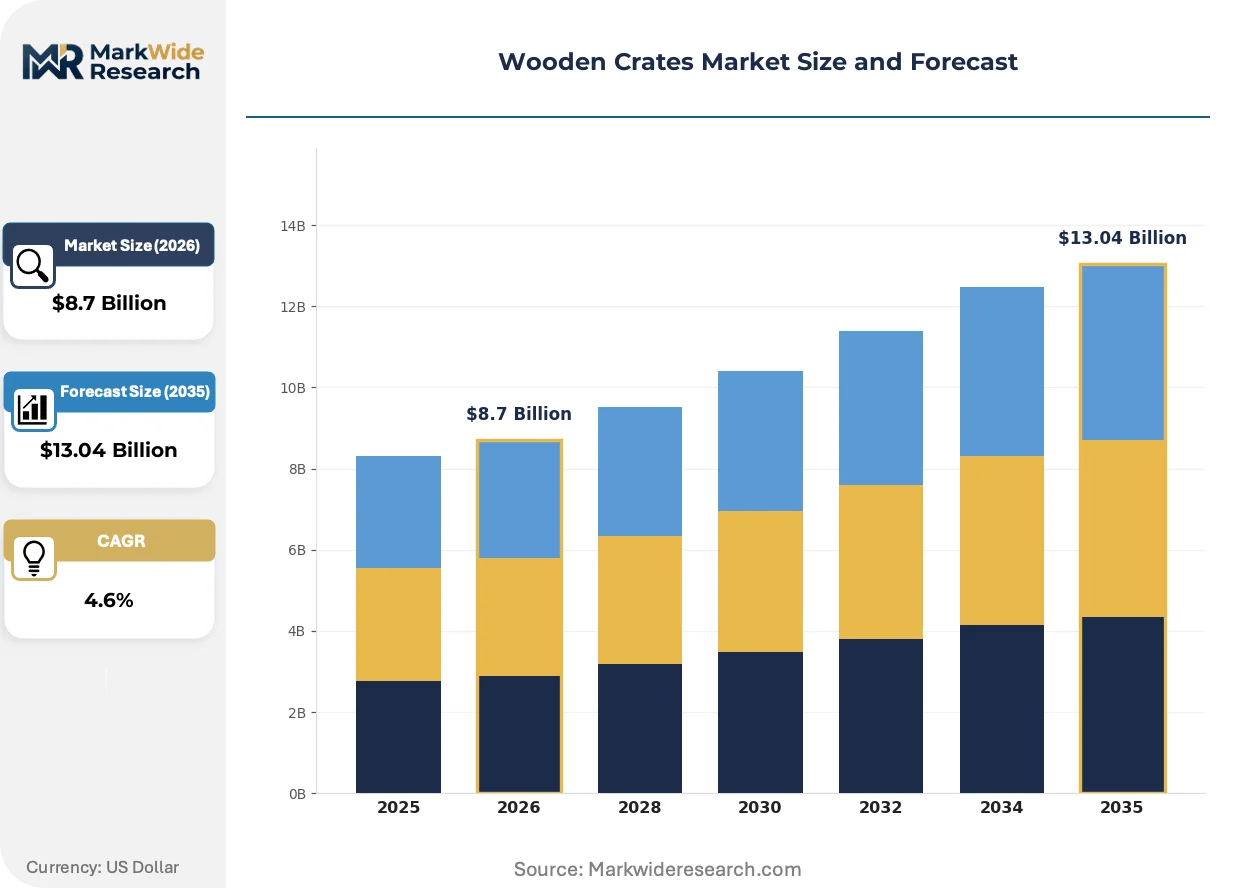
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pallets, Boxes, Bins, Displays Material: Hardwood, Softwood, Plywood, Engineered Wood End User: Agriculture, Retail, Logistics, Manufacturing Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Brambles Limited (CHEP), Greif Inc., Universal Forest Products Inc., NEFAB, PGS Group, PalletOne Inc., Interlake Mecalux, Poole & Sons, Loscam Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wooden Crates Market Evolving Landscape
Traceability technology and material engineering are converging to reconfigure how wooden crates are specified, certified, and procured across high-value logistics corridors.
Engineered laminated panels with calibrated moisture barriers are modularizing crate construction for semiconductor and aerospace shippers. Electronics manufacturers in Taiwan and South Korea specify these panels for repeated ocean-container cycles. The technology is modularizing assembly workflows and compressing lead times for custom dimensions.
EUDR geolocation traceability mandates now require latitude-longitude coordinates for every wood source entering European ports. Sawmills in Vietnam and Indonesia are deploying GPS-stamped chain-of-custody systems to maintain market access. Plantation operators in Binh Duong province are consolidating land-title documentation to satisfy due-diligence requirements.
Buyer consolidation among third-party logistics providers is concentrating procurement authority at fewer decision points. Automotive tier-one suppliers now mandate pooled-crate programs rather than asset ownership. This pattern is most visible in Germany's manufacturing corridors, where Brambles-operated networks displace single-use purchasing.
Wooden Crates Market Segmentation
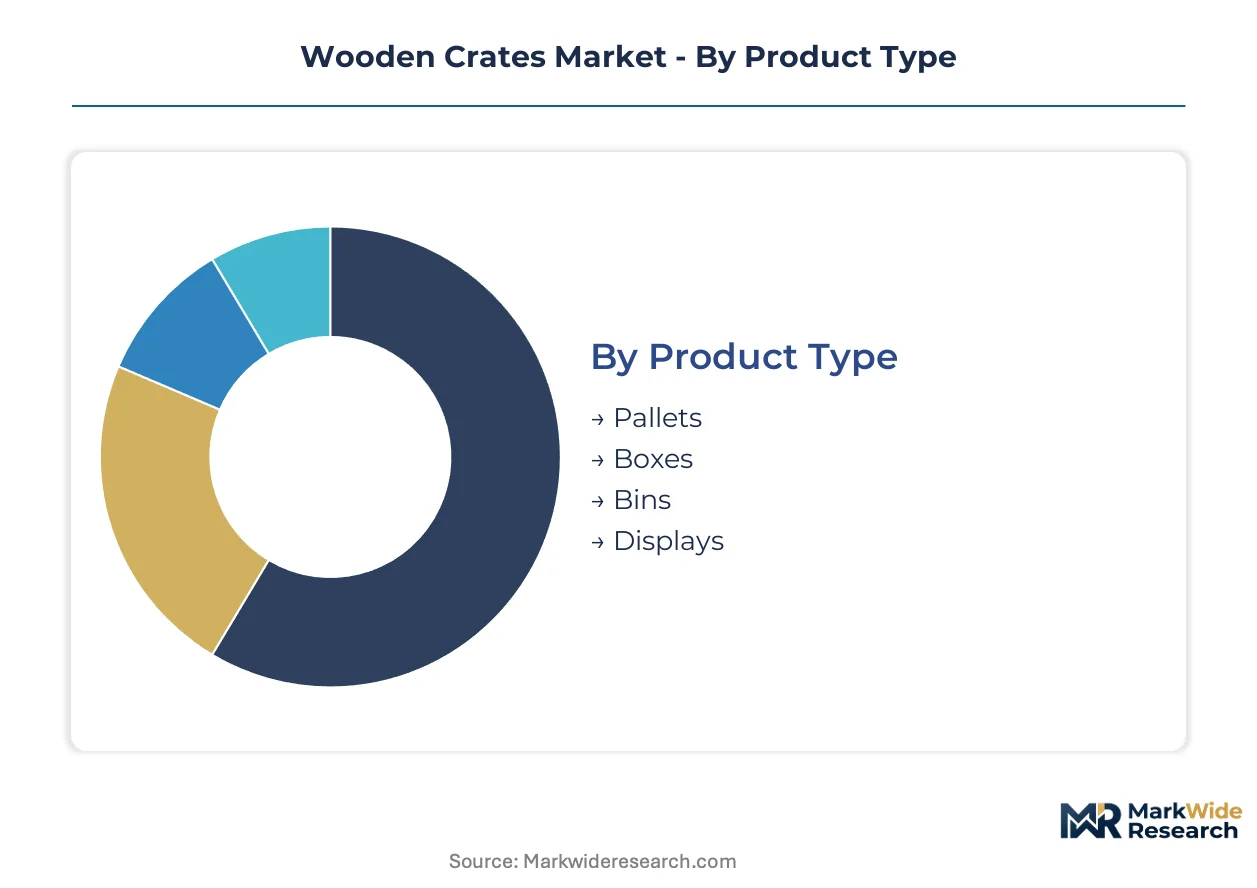
Wooden crate specifications diverge sharply across logistics corridors, with treatment certification, load-bearing requirements, and dimensional tolerances driving procurement decisions. Segmentation reveals how capital deployment and compliance infrastructure concentrate in formats serving high-value, regulated trade lanes.
Product Type:
Capital intensity peaks in formats requiring integrated ISPM-15 treatment infrastructure and multi-modal compatibility.
- Pallets:Standardized 48x40 inch platforms dominate forklift-compatible warehouse racking systems. Demand concentrates in Vietnam's manufacturing corridors near Ho Chi Minh City and Binh Duong province, where heat-treatment kiln networks enable direct US market access under USDA APHIS equivalence agreements.
- Boxes:Rigid six-sided containers with slatted ventilation serve bulk agricultural harvests. Latin American fresh produce exporters are scaling procurement as refrigerated logistics penetrate inland growing regions, with geolocation traceability becoming mandatory for EU port entry.
- Bins:Large-volume containers for loose commodities such as grain or minerals.
- Displays:Finished retail-ready units with branded exterior panels.
Pallets absorb the bulk of installed capacity; boxes are expanding most quickly.
Material:
Feedstock selection determines compliance pathways and moisture stability for precision logistics applications.
- Hardwood:Dense oak and maple provide maximum compression resistance for heavy machinery transport. EU Deforestation Regulation geolocation mandates now require latitude-longitude coordinates for every hardwood source entering Rotterdam and Hamburg ports, compressing margins for uncertified suppliers.
- Engineered Wood:Laminated panels with calibrated moisture barriers modularize crate construction for semiconductor and aerospace shippers. Electronics manufacturers in Taiwan and South Korea specify these for repeated ocean-container cycles where dimensional tolerance is critical.
- Softwood:Plantation pine and fir from certified sources.
- Plywood:Cross-laminated veneer sheets from Southeast Asian mills decoupling from traditional feedstocks.
Hardwood retains the largest production footprint; engineered wood is gaining share fastest.
End User:
Customer procurement authority concentrates in sectors with closed-loop logistics networks and multi-site standardization requirements.
- Logistics:Third-party providers and pooled-crate operators dominate volume procurement. Automotive tier-one suppliers in Germany now mandate asset-light programs rather than ownership, with Brambles-operated networks displacing single-use purchasing across manufacturing corridors.
- Manufacturing:Precision fabrication for semiconductor lithography tools and satellite components requires vibration-dampening specifications that displace metal alternatives. NEFAB and specialized competitors capture margin through moisture-stable dimensional tolerances.
- Agriculture:Bulk harvest handling with ventilation-optimized slat design.
- Retail:Point-of-sale display units with branding surfaces.
Logistics commands the deepest procurement relationships; manufacturing shows the steepest specification escalation.
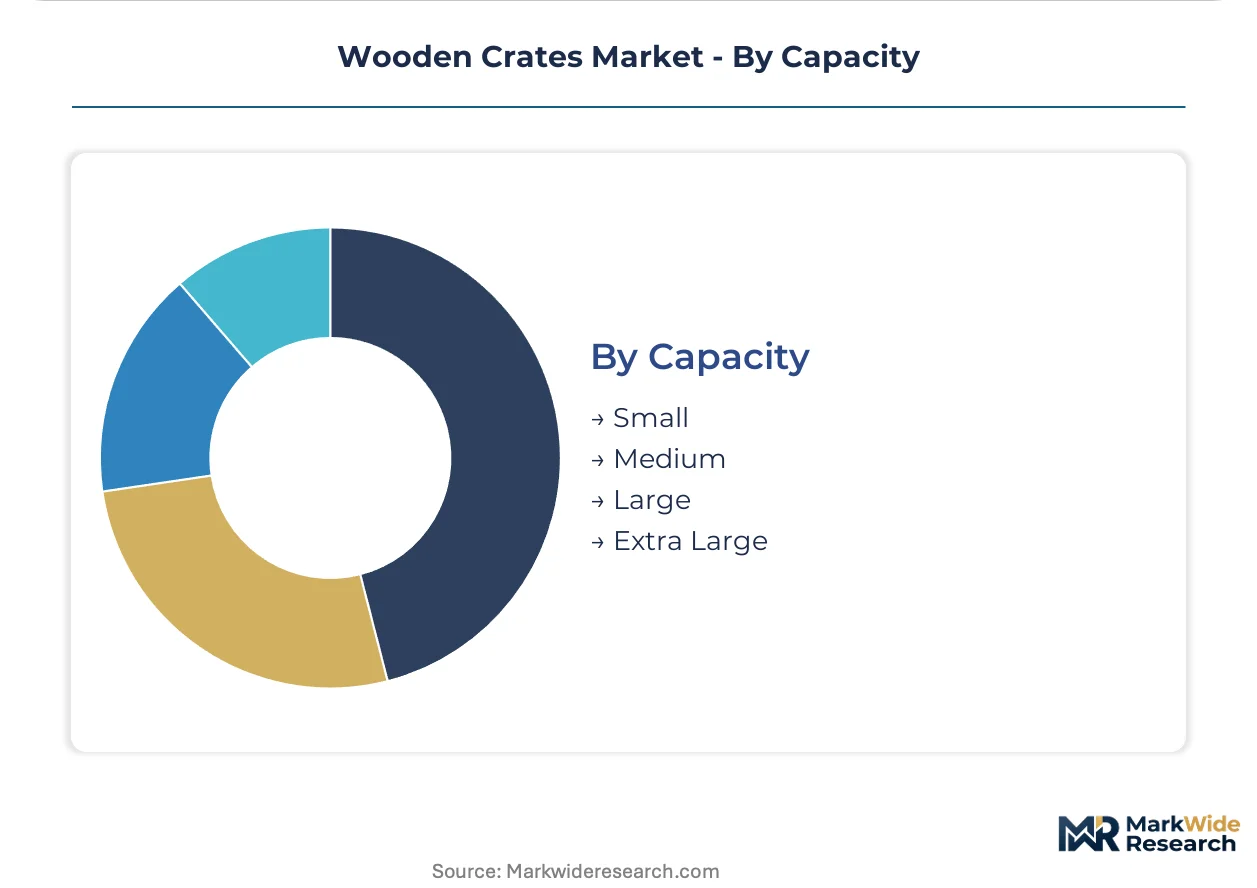
Capacity:
Scale tiers align with handling equipment compatibility and container optimization economics.
- Large:Ocean-container-maximizing dimensions for intermodal efficiency.
- Medium:Standard warehouse racking compatibility.
- Small:Parcel-scale units for last-mile distribution.
- Extra Large:Project cargo formats requiring custom engineering.
Medium capacity handles the highest transaction velocity; large formats are climbing fastest on export lane deepening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plantation eucalyptus feedstocks in Vietnam's Mekong Delta and Binh Duong province anchor Southeast Asian plywood supply, while Brazilian hardwood networks and German automotive logistics clusters shape demand patterns across distinct regulatory environments.
United States
USDA APHIS enforces ISPM-15 equivalence agreements that determine which national wood packaging regimes gain market access, directly shaping exporter compliance costs. The agency's heat-treatment certification requirements concentrate procurement authority among domestic pallet fabricators with captive kiln infrastructure. Demand clusters near Detroit's automotive corridors and California's Central Valley agricultural distribution hubs.
Germany
Automotive tier-one suppliers mandate pooled-crate programs rather than asset ownership, compressing margins for single-use purchasing. ECHA REACH restrictions on preservative chemistry redirect material sourcing toward certified plantation timber. Manufacturing corridors in Bavaria and Baden-Württemberg displace traditional purchasing patterns through Brambles-operated closed-loop networks.
Vietnam
Heat-treatment capacity expansion at mills near Ho Chi Minh City enables direct US market access for ASEAN exporters. Binh Duong province plantation operators consolidate land-title documentation to satisfy EU Deforestation Regulation due-diligence requirements. Sawmills deploy GPS-stamped chain-of-custody systems to maintain European port entry.
Brazil
Fresh produce exporters scale ventilated crate procurement as refrigerated logistics penetrate inland growing regions. Geolocation traceability mandates from European destination markets force reconstruction of forest-gate-to-port infrastructure. São Paulo state agricultural distributors rebuild certification systems to access Rotterdam and Hamburg.
China
Dual carbon goals under MEE oversight redirect plywood mill feedstocks away from native hardwood toward plantation eucalyptus imports. Yangtze River Delta manufacturers specify engineered laminated panels for semiconductor equipment logistics. Cross-laminated veneer production concentrates in Jiangsu and Zhejiang provinces.
Wooden Crates Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue engineered wood specialization and digital traceability certification. The market structures around three tiers: pooled-network operators with asset-light logistics contracts, integrated mill-to-crate fabricators controlling heat-treatment infrastructure, and precision-engineering specialists serving aerospace and semiconductor verticals. Consolidation pressure concentrates procurement authority at fewer decision points as third-party logistics providers mandate multi-site standardization. Competitive moves center on vertical integration into plantation timber sourcing and blockchain-verified chain-of-custody investments.
Within the pooled-network tier, Brambles Limited exemplifies asset-light logistics dominance through closed-loop program structures. Among North American integrated fabricators, Greif Inc. and Universal Forest Products occupy positions anchored in chemical packaging and construction material distribution respectively. Precision-engineering specialists include NEFAB, which represents the vibration-dampening specification segment displacing metal alternatives for lithography tool transport.
| Leading Market Players |
|---|
| Brambles Limited (CHEP) |
| Greif Inc. |
| Universal Forest Products Inc. |
| NEFAB |
| PGS Group |
| PalletOne Inc. |
| Interlake Mecalux |
| Poole & Sons |
| Loscam Ltd. |
| Others |
Value Network & Pricing Analysis
Heat-treatment kiln automation at Vietnamese mills simultaneously compresses per-unit processing costs and concentrates procurement authority among integrated fabricators with captive certification infrastructure. This technological shift rewards operators who bundle ISPM-15 compliance with crate fabrication, while marginalizing traders dependent on third-party treatment services.
Pricing Analysis
Warranty and certification bundling separates full-service providers from unbundled commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects traceability grade and treatment protocol: EUDR-geolocation-certified crates command premiums at Rotterdam and Hamburg, heat-treated standard pallets serve ASEAN-US lanes, and untreated softwood competes on spot markets. Pricing pressure stems from methyl bromide phase-out capital requirements forcing retooling investments. Small agricultural exporters exhibit highest price sensitivity; semiconductor equipment manufacturers prioritize specification compliance over unit cost.
Supply Chain Analysis
EU Deforestation Regulation domestic-content traceability mandates are reshaping sourcing toward plantation-certified feedstocks with GPS-stamped chain-of-custody documentation. Geographic concentration centers on Vietnam, Brazil, and Germany: Binh Duong province mills serve ASEAN export corridors, São Paulo state distributors rebuild certification systems for European port access, and Bavarian automotive clusters anchor closed-loop pallet networks. Raw material dependencies include eucalyptus plantation timber, laminated veneer lumber, and heat-treatment kiln capacity. Single-source vulnerability concentrates in Southeast Asian plywood feedstocks where maturation cycles create 7-12 year supply lags. Distribution runs through third-party logistics providers consolidating procurement authority at fewer decision points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Deforestation Regulation compliance costs are forcing consolidation as uncertified suppliers exit European lanes, concentrating market share among integrated plantation-to-crate operators.
For Market Incumbents: Deploy heat-treatment capacity expansion as the primary defensive lever. Backward integration into Binh Duong province plantation sourcing secures EUDR-compliant feedstock access while Brambles-style pooled-network contracts lock in automotive tier-one relationships. ISPM-15 accreditation backlogs at national plant protection offices threaten export readiness for competitors lacking captive certification infrastructure. For New Entrants and Emerging Players: Blockchain-verified chain-of-custody systems offer a technology-first wedge into European retail procurement filters. White-space targets include semiconductor equipment precision packaging where NEFAB-style vibration-dampening specifications displace metal alternatives, and aerospace satellite component logistics demanding moisture-stable engineered panels. Go-to-market positioning should emphasize digital traceability certification as a procurement differentiator for EUDR-enforcement periods. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by pooled-network operators seeking vertical integration into treatment infrastructure. Long-term viability favors integrated mill-to-crate fabricators controlling heat-treatment kilns and plantation timber sourcing across the analysis window. Acquisition target archetype: mid-cap Vietnamese operators with GPS-stamped chain-of-custody systems and Ho Chi Minh City corridor logistics access. Signal to watch: EUDR enforcement intensity at Rotterdam and Hamburg port inspections as inflection indicator for certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Capacity Expansion | Captive kiln infrastructure at Vietnamese mills enables direct USDA APHIS market access. |
| Plantation Timber Backward Integration | Binh Duong province land-title consolidation satisfies EUDR geolocation due-diligence requirements. |
| Blockchain Chain-of-Custody Deployment | GPS-stamped certification systems penetrate European retail procurement filters. |
| Precision Engineering Specialization | Vibration-dampening specifications displace metal alternatives for semiconductor lithography tools. |
| Pooled-Network Contract Structuring | Brambles-style asset-light programs displace single-use purchasing in German automotive corridors. |
Research Methodology
Trade databases, plantation timber production records, and ISPM-15 accreditation registries formed the secondary backbone. Primary interviews with heat-treatment facility operators, automotive tier-one procurement managers, fresh produce export logistics coordinators, and EU customs compliance officers validated demand patterns and regulatory enforcement timelines. Bottom-up and top-down triangulation cross-referenced mill capacity installations against end-user procurement surveys.
Bottom-up modeling aggregated individual country-level production capacities, treatment facility throughput, and end-use sector procurement volumes. Segmentation dimensions included product type, material grade, end-use vertical, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of plantation timber maturation cycles, cold-chain logistics penetration rates, and semiconductor equipment shipment volumes across the projection horizon.
Several conditions sit outside the modeled scope, including potential EUDR enforcement delays, alternative fumigation chemistry approvals under ECHA REACH, and accelerated plastic pallet substitution in automotive closed-loop systems. Forecasts reflect assumptions regarding plantation eucalyptus yield rates and national plant protection office accreditation processing speeds. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Thermoformed Containers Market
Containers
ISO Container Market
Containers
Lever Lid Tinplate Containers Market
Containers
Feeder Containers Market
Containers
Safety Bottle Tote Carriers Packaging Market
Containers
Foam Hinged Take-Out Containers Market
Containers
Hinged Lid Compostable Container Market
Containers
Container Mouth Inner Seal Market
Containers
Trays Market
Containers
Straight Sided Glass Jar Market
Containers
Reconditioned IBC Market
Containers
PET Hinged Containers Market
Containers
HDPE Containers Market
Containers
Slotted Containers Market
Containers
Single Wall Jars Market
Containers
EPS Shippers Market