
 Transport Racks Market | 2026-2036
Transport Racks Market Size, Share, and Industry Trends Forecast 2026-2036
Transport Racks Market Outlook
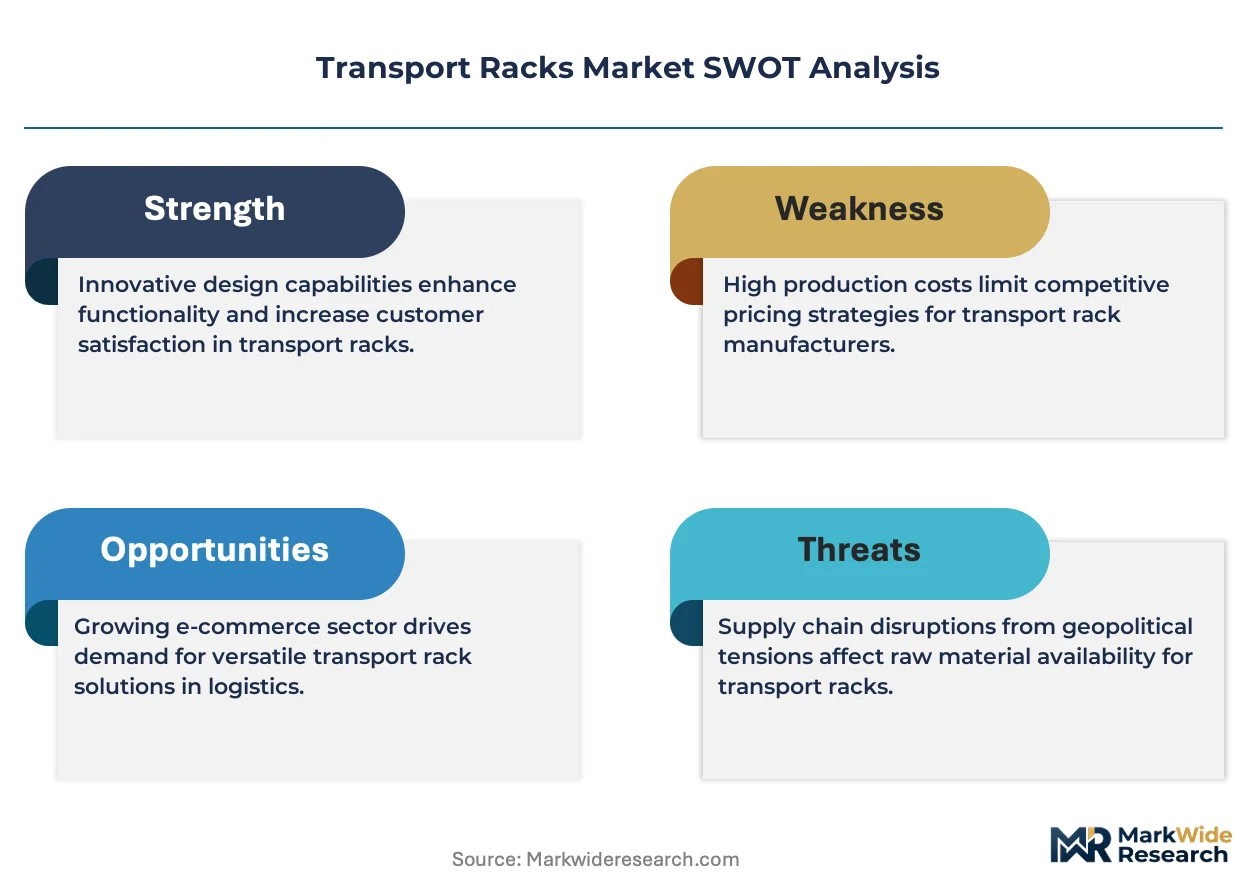
Aftermarket service revenue is fragmenting across installation, maintenance, and accessory bundling as rack systems grow more modular. Thule Group leverages its premium brand architecture to command higher-margin direct-to-consumer channels. Yakima Products, Inc. anchors its position through deep partnerships with outdoor recreation retailers and OEM automotive programs. Hauler Racks, Inc. specializes in commercial-grade steel configurations for contractor and utility vehicle segments.
Transport racks are load-bearing frameworks engineered from aluminum extrusions, steel tubing, or glass-reinforced composites, designed to secure cargo atop or behind passenger and commercial vehicles with specified dynamic load ratings. Roof rack assemblies typically span 1.2 to 1.4 meters in crossbar length and integrate T-slot channels for accessory mounting across bicycle, ski, and cargo box applications. Aluminum roof racks lead product type demand due to their strength-to-weight ratio and corrosion resistance in all-weather deployment. Composite materials represent the fastest-growing material segment as manufacturers pursue weight reduction targets tied to fleet fuel efficiency mandates. Hitch racks occupy the premium margin tier where integrated swing-away mechanisms and electric bike load capacities justify price premiums over trunk-mounted alternatives.
The National Highway Traffic Safety Administration enforces Federal Motor Vehicle Safety Standard 216a for roof crush resistance, directly influencing structural testing protocols for permanent installation rack systems. The EPA's corporate average fuel economy framework penalizes vehicle weight, pushing fleet buyers toward aluminum and composite rack solutions that minimize aerodynamic drag and mass penalties. Stakeholders must monitor evolving cross-border material certification requirements and electrified vehicle payload constraints as battery-electric platforms impose stricter roof load limits that reshape rack engineering specifications.
Market Dynamics
Fleet electrification is compressing roof load allowances on battery-electric vans and trucks, forcing rack manufacturers to reengineer aluminum extrusion profiles and mounting interfaces for reduced mass without sacrificing structural integrity.
Growth Catalysts
- EPA Corporate Average Fuel Economy:Penalties on vehicle weight push commercial fleet buyers toward aluminum and composite rack systems that minimize aerodynamic drag penalties during highway operation.
- Last-mile delivery expansion:E-commerce fulfillment networks in the United States, Germany, and China are retrofitting existing van fleets with modular roof rack configurations for parcel volume optimization.
- Glass-reinforced composites:Material advances in thermoplastic manufacturing are enabling load-bearing crossbars that match steel strength at 40% lower mass, opening OEM fitment on lightweight vehicle platforms.
Market Restraints
- Aluminum price volatility:LME aluminum contract fluctuations directly compress margins on extruded crossbar production, particularly for mid-tier aftermarket suppliers without long-term hedging.
- Roof crush certification backlog:NHTSA FMVSS 216a testing protocols create 8-12 month approval timelines for new permanent-mount rack designs, freezing product launch schedules.
- Integrated factory racks:OEMs are offering factory-installed roof rails as standard equipment on utility vehicle trims, displacing aftermarket retrofit demand in the premium SUV segment.
Strategic Opportunities
- India commercial vehicle retrofit:Underpenetrated contractor and logistics fleets present white space for steel utility rack configurations adapted to tropical corrosion environments.
- Electric bike hitch rack segment:Convergence of 65+ pound e-bike loads with swing-away access mechanisms commands price premiums over conventional trunk-mounted alternatives.
- EU Green Deal material incentives:Recycled aluminum content mandates in automotive components create preferential procurement pathways for rack suppliers with closed-loop extrusion capabilities.
Industry Challenges
- Structural simulation talent scarcity:Finite element analysis expertise for dynamic load testing and crash simulation commands premium salaries, constraining mid-size manufacturer R&D bandwidth.
- Cross-border certification fragmentation:Divergent load-rating standards between NHTSA, KBA, and China's GB protocols force parallel testing programs for global product lines.
- Legacy fleet integration:Rack mounting hardware designed for internal combustion vehicle roof structures requires redesign for battery-electric platforms with relocated chassis hardpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transport Racks Market |
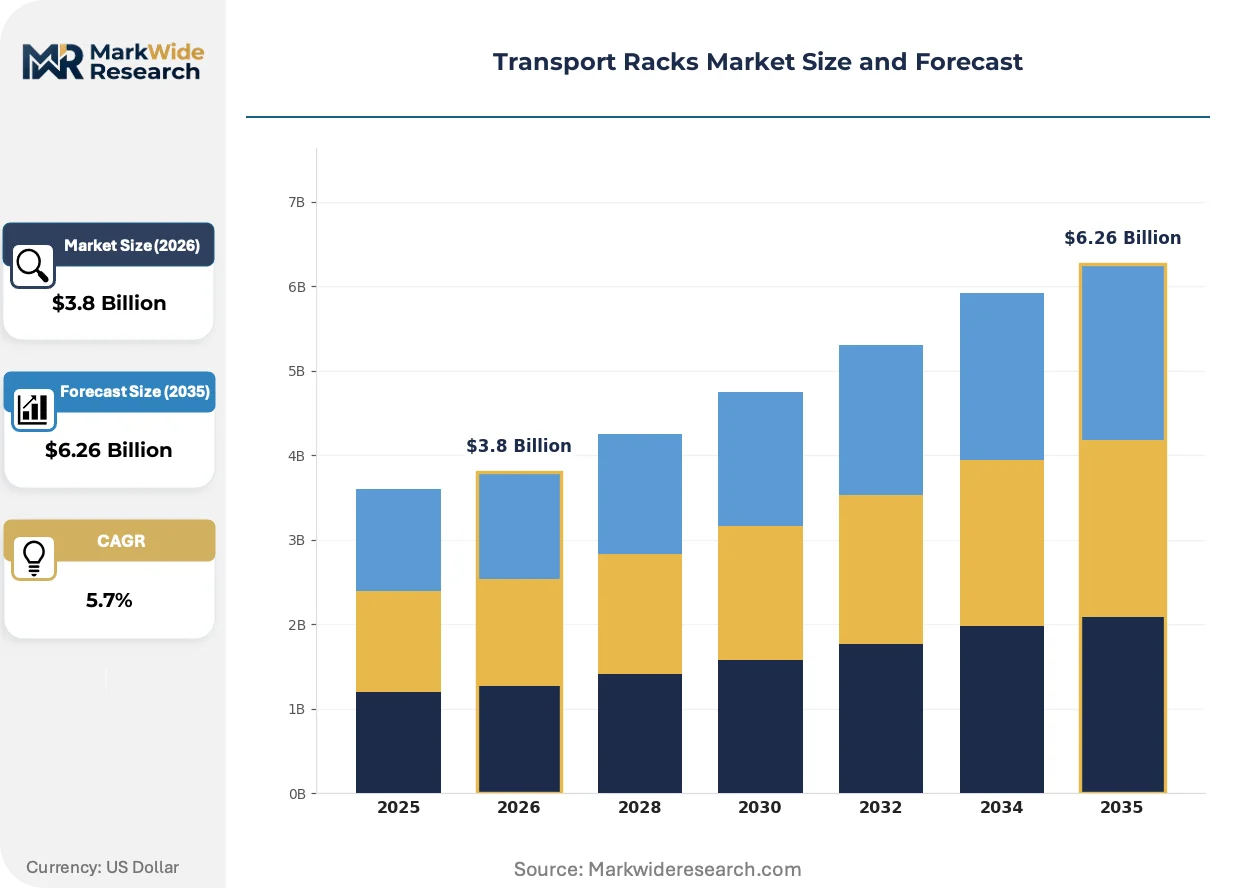
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roof Racks, Hitch Racks, Trunk Racks, Bike Racks Material: Aluminum, Steel, Plastic, Composite End User: Individuals, Commercial Fleet Operators, Rental Agencies, Manufacturers Installation Type: Permanent, Removable, Adjustable, Fixed |
| Companies Covered | Thule Group, Yakima Products, Inc., Hauler Racks, Inc., Cross Tread Industries, Inc., Vanguard Manufacturing, Inc., conTeyor, Deltarack BV, Emtomech B.V., Vestil Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transport Racks Market Strategic Shifts
Material science advances and regulatory pressure on vehicle efficiency are converging to transform rack system architecture, with manufacturers racing to deliver certified solutions before stricter payload limits take effect on electric commercial platforms.
Modular T-slot extrusion systems are migrating from fixed-length crossbar configurations to adjustable-width platforms that accommodate varying vehicle roof spans without SKU proliferation. Fleet procurement managers at major delivery operators are specifying these adaptive systems to reduce spare parts inventory across mixed van populations. This migration from rigid to reconfigurable architectures is compressing supplier development cycles while expanding addressable vehicle fitment per product line.
REACH substance restrictions on hexavalent chromium plating are eliminating traditional steel corrosion protection from European-market rack hardware, forcing suppliers to adopt zinc-nickel or ceramic coating alternatives. The industrial consequence is a 15-20% cost increase on fastener and bracket components that must be absorbed or passed through pricing. German commercial vehicle outfitters are responding fastest, with several major rack suppliers already certifying alternative finishes to maintain KBA type approval.
Direct-to-consumer configuration tools are displacing traditional retail consultation for accessory bundling decisions. Thule Group's online rack-finder algorithms now handle a majority of initial purchase journeys, with physical retailers increasingly relegated to installation fulfillment. This channel compression is most visible in the United States and Nordic markets, where digital-native outdoor recreation buyers expect immediate compatibility verification against vehicle VIN databases.
Transport Racks Market Segmentation
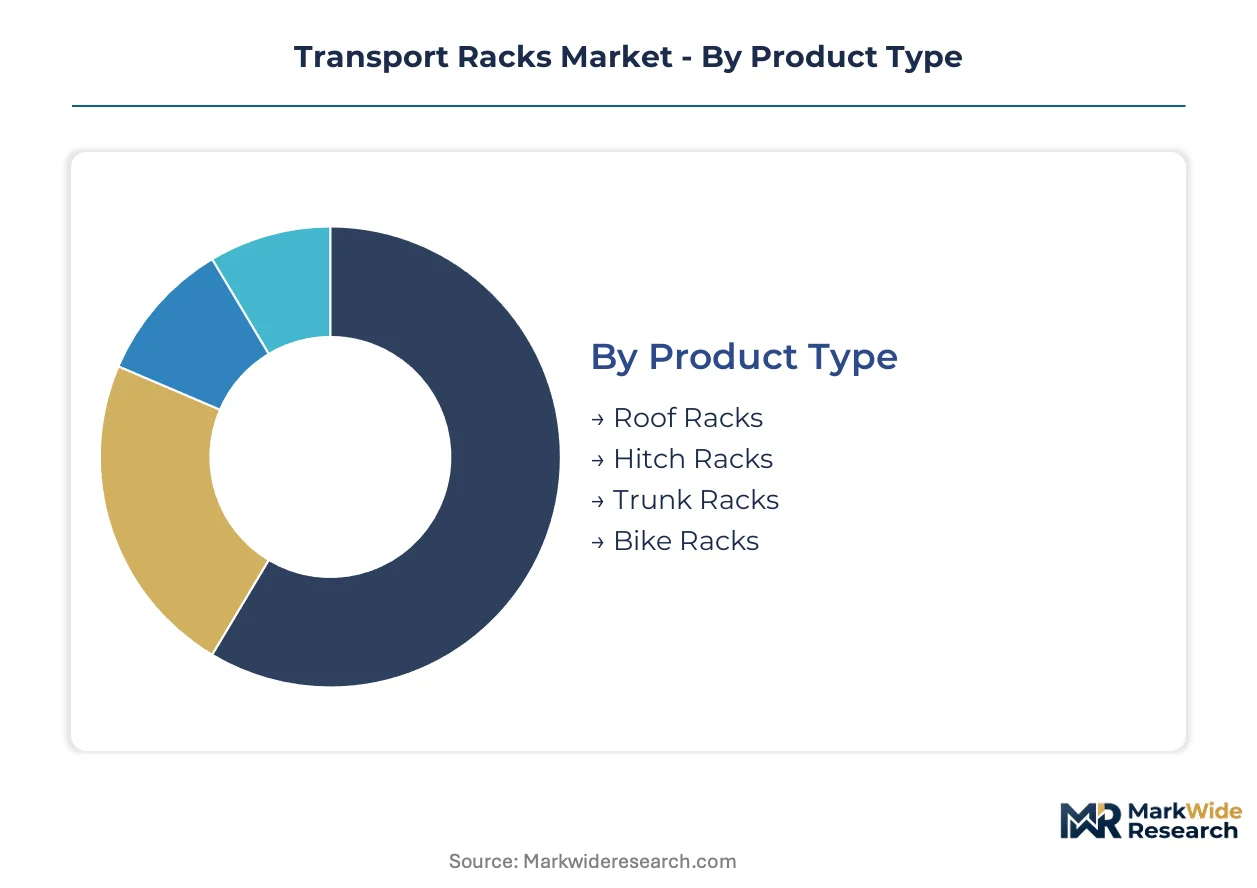
Transport rack purchasing decisions split across vehicle compatibility constraints, payload requirements, and regulatory compliance burdens. Fleet managers weigh total cost of ownership against modular flexibility, while individual buyers prioritize ease of installation and aesthetic integration. Material selection increasingly reflects fuel economy penalties and electrified vehicle weight restrictions.
Product Type:
Application context determines rack architecture selection, with mounting position and load dynamics driving specification divergence across passenger and commercial use cases.
- Roof Racks:Aluminum extrusion frameworks span 1.2 to 1.4 meters with T-slot channels for bicycle, ski, and cargo box mounting. Commercial fleet operators in the United States specify these for last-mile delivery vans where parcel volume optimization outweighs aerodynamic drag penalties.
- Hitch Racks:Receiver-mounted assemblies integrate swing-away mechanisms and 65+ pound electric bike load capacities. These command price premiums over alternatives where rear vehicle access must remain unobstructed during cargo transport.
- Trunk Racks:Strap-mounted configurations attach to rear decklids without permanent hardware. Budget-conscious individual buyers favor these for seasonal recreational use on vehicles lacking factory roof rails.
- Bike Racks:Purpose-built frames accommodate frame geometries from road bicycles to fat-tire mountain bikes. Outdoor recreation retailers bundle these with vehicle-specific fitment kits to reduce return rates.
Roof rack configurations command the established base. The steepest expansion runs through hitch rack segments serving electric bike loads.
Material:
Cost tier positioning and structural performance requirements shape raw material procurement, with regulatory weight penalties accelerating substitution away from traditional steel.
- Aluminum:Extruded 6061-T6 and 6005A alloys deliver strength-to-weight ratios critical for EPA fuel economy compliance. Fleet buyers in Germany prioritize these for corrosion resistance in all-weather deployment across mixed van populations.
- Composite:Glass-reinforced thermoplastic crossbars match steel strength at 40% lower mass. OEM fitment programs are expanding these configurations as battery-electric platforms impose stricter roof load limits.
- Steel:Tubular and stamped configurations persist in contractor-grade utility applications. Indian commercial vehicle outfitters favor galvanized variants for tropical corrosion environments.
- Plastic:Injection-molded components serve non-structural fairings and accessory mounting interfaces. These reduce finished product weight where metal substitution meets cost targets without compromising dynamic load ratings.
Aluminum maintains volume leadership across certified applications. Composite materials are climbing the fastest as electrified fleet specifications tighten.
End User:
Customer type dictates procurement channel, specification complexity, and service bundling requirements across direct-to-consumer and B2B workflows.
- Commercial Fleet Operators:National delivery networks in the United States and Germany specify modular adjustable-width systems to reduce spare parts inventory across mixed van populations. These buyers demand NHTSA FMVSS 216a and KBA type approvals as baseline procurement criteria.
- Individuals:Digital-native outdoor recreation buyers in Nordic markets and the United States complete purchase journeys through online configuration tools. Physical retailers serve increasingly as installation fulfillment nodes rather than consultation points.
- Rental Agencies:Seasonal demand peaks for ski and bicycle tourism drive fleet standardization around quick-install removable configurations. These operators prioritize damage-resistant designs that withstand frequent customer handling.
- Manufacturers:OEM fitment programs require suppliers to integrate rack architecture into vehicle design cycles 24-36 months ahead of production. Factory-installed roof rails as standard equipment on utility vehicle trims are displacing aftermarket retrofit demand in premium segments.
Commercial fleet operators anchor procurement volume. Individual direct-to-consumer channels are gaining share fastest through digital configuration adoption.
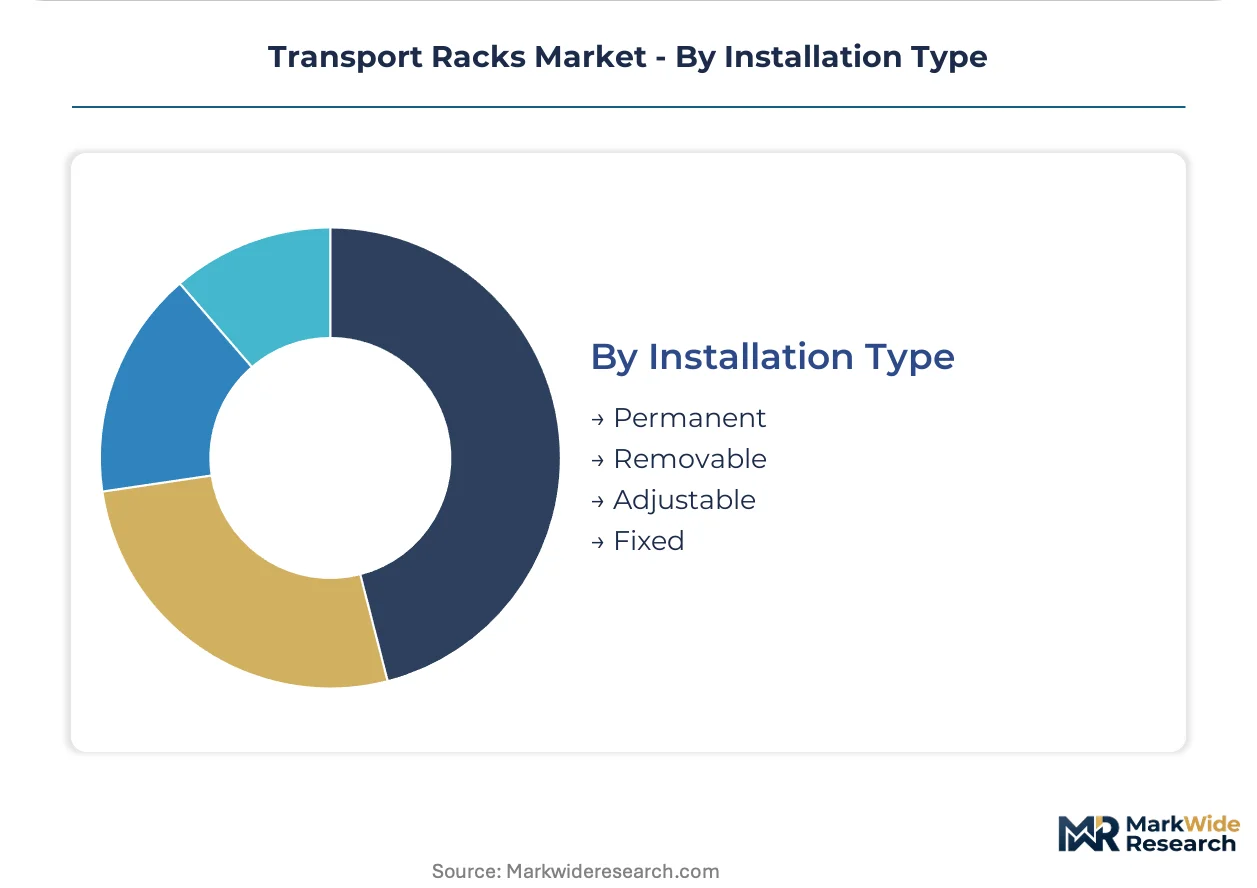
Installation Type:
Mounting permanence determines regulatory testing burden, resale value impact, and compatibility with electrified vehicle roof structures.
- Permanent:Bolt-through installations require NHTSA FMVSS 216a roof crush certification with 8-12 month approval timelines. These configurations withstand maximum dynamic load ratings for commercial applications.
- Removable:Clamp and strap systems enable seasonal use without vehicle modification. Individual buyers favor these where lease agreements prohibit permanent alterations.
- Adjustable:Width-variable crossbar platforms accommodate multiple roof spans without SKU proliferation. Fleet procurement managers specify these to simplify inventory across heterogeneous vehicle populations.
- Fixed:Rigid-length configurations persist in OEM-integrated factory rack programs. These offer lowest cost per unit where vehicle model specificity eliminates reconfiguration requirements.
Permanent installations retain the certified commercial base. Adjustable systems are expanding most quickly through fleet electrification retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion and fabrication capacity clusters in Germany, the United States, and China, with each hub serving distinct regulatory and end-use demand profiles across commercial fleet and consumer recreation segments.
United States
Last-mile delivery networks at Amazon, FedEx, and UPS drive aluminum rack retrofit demand across van fleets. NHTSA FMVSS 216a roof crush standards mandate 8-12 month certification timelines for permanent-mount systems. Manufacturing concentrates in Michigan and Ohio, where automotive supplier infrastructure supports precision extrusion and coating operations for fleet-grade products.
Germany
Commercial vehicle outfitters prioritize KBA type-approved aluminum systems for corrosion resistance in all-weather deployment. EU Green Deal recycled content mandates push suppliers toward closed-loop extrusion capabilities. Industrial activity clusters in Baden-Württemberg and Bavaria, where automotive tier-one suppliers integrate rack architecture into OEM design cycles 24-36 months ahead of production.
China
Domestic e-commerce logistics expansion creates demand for modular steel and aluminum configurations on light commercial vehicles. GB standards for vehicle exterior accessories impose load-rating protocols that diverge from NHTSA and KBA frameworks. Production gravity sits in Yangtze River Delta manufacturing zones, where aluminum extruders serve both domestic fleet buyers and export markets.
India
Underpenetrated contractor and logistics fleets present white space for galvanized steel utility racks adapted to tropical corrosion environments. Central Motor Vehicle Rules govern roof load limits and mounting hardware specifications for commercial retrofits. Activity concentrates in Maharashtra and Gujarat, where automotive component clusters support rack fabrication for domestic commercial vehicle brands.
Transport Racks Market Competitive Environment
Premium-brand specialists and commercial-grade fabricators split the market along price-tier and application-versatility lines. The structure remains moderately consolidated, with three to five players commanding significant share in each major geography while regional specialists serve fleet retrofit niches. Two archetypes dominate: direct-to-consumer lifestyle brands leveraging digital configuration tools, and B2B-focused manufacturers engineering certified systems for fleet procurement managers. Competitive moves center on aluminum extrusion capacity expansion and strategic partnerships with OEM automotive programs.
Within the premium-brand tier, Thule Group and Yakima Products, Inc. exemplify direct-to-consumer positioning through online rack-finder algorithms and outdoor recreation retail channels. Hauler Racks, Inc. anchors the commercial-grade segment, representing specialized fabrication for contractor and utility vehicle applications. These three entities collectively illustrate the market's bifurcation between lifestyle-oriented consumer sales and fleet-certified B2B procurement.
| Leading Market Players |
|---|
| Thule Group |
| Yakima Products, Inc. |
| Hauler Racks, Inc. |
| Cross Tread Industries, Inc. |
| Vanguard Manufacturing, Inc. |
| conTeyor |
| Deltarack BV |
| Emtomech B.V. |
| Vestil Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta freight corridors linking aluminum extrusion plants to Shanghai Port generate cost differentials that cascade through rack manufacturer pricing power and downstream buyer tier stratification across United States, German, and Chinese fleet procurement channels.
Pricing Analysis
Aftermarket installation and maintenance service bundles now drive lifetime value capture for rack system vendors. Three-tier pricing structure across premium, standard, and economy levels separates Thule Group's direct-to-consumer channels from mid-tier aftermarket suppliers and budget trunk-mounted alternatives. Price differentiation hinges on NHTSA FMVSS 216a certification status and aluminum alloy grade specification. Cost compression in mid-tier extruded crossbar production is intensifying because LME aluminum contract volatility erodes hedging-deficient suppliers. Commercial fleet operators exhibit lowest price sensitivity due to total cost of ownership frameworks, while individual seasonal buyers prioritize upfront acquisition cost minimization.
Supply Chain Analysis
Extended payment terms from German automotive tier-one suppliers to aluminum extruders anchor working capital dynamics across the supplier base. Raw material sourcing draws from Chinese bauxite refining, German rolling mill capacity, and United States secondary smelting operations. Critical inputs encompass 6061-T6 aluminum billet, glass-reinforced thermoplastic resin, and zinc-nickel coated fastener hardware. Single-source vulnerability concentrates in Yangtze River Delta extrusion capacity for adjustable-width crossbar platforms. Distribution runs through OEM automotive programs, outdoor recreation retail networks, and direct-to-consumer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transport rack demand sits in early-cycle expansion as battery-electric commercial vehicle retrofit requirements create structural pull for lightweight certified configurations.
For Market Incumbents: Entrench aluminum extrusion capacity in Michigan and Baden-Württemberg manufacturing clusters to defend against composite material substitution threats. Prioritize NHTSA FMVSS 216a and KBA type approval pipeline investment to maintain certification backlog advantages over emerging competitors. Deepen captive supply of closed-loop recycled aluminum content to satisfy EU Green Deal procurement mandates. For New Entrants and Emerging Players: Build out galvanized steel utility rack fabrication for Indian contractor fleets in Maharashtra and Gujarat, where tropical corrosion specifications remain underpenetrated by incumbent aluminum specialists. Target electric bike hitch rack segments through swing-away mechanism engineering partnerships with outdoor recreation retailers. Pursue direct-to-consumer digital configuration tools to bypass established retail channel gatekeepers. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive supplier conglomerates seeking to divest non-core rack architecture divisions amid platform electrification capital reallocation. Long-term viability centers on suppliers with certified lightweight material expertise and OEM program integration capabilities. Monitor NHTSA roof load limit revisions for battery-electric platforms as inflection indicator for composite material adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Aluminum Extrusion | EU Green Deal recycled content mandates create preferential procurement pathways for KBA-certified suppliers. |
| Adjustable-Width Platform Development | Fleet electrification retrofit cycles compress SKU proliferation across mixed van populations at Amazon and UPS. |
| Swing-Away Hitch Mechanism Engineering | 65+ pound electric bike loads command price premiums over conventional trunk-mounted configurations. |
| Direct-to-Consumer Digital Configuration | Thule Group's online rack-finder algorithms displace traditional retail consultation in Nordic and United States markets. |
| Composite Crossbar OEM Fitment | Glass-reinforced thermoplastic platforms match steel strength at reduced mass for battery-electric roof load limits. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across fleet procurement managers at United States delivery networks, German commercial vehicle outfitters, Chinese aluminum extrusion plant managers, and aftermarket service technicians. Secondary validation drew from NHTSA FMVSS 216a certification databases, KBA type approval registries, EPA corporate average fuel economy filings, and EU Green Deal recycled content mandate documentation. Bottom-up unit shipment estimates triangulated against top-down aluminum extrusion capacity utilization data.
Calibration against historical roof rack and hitch rack shipment volumes anchored the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, material composition, end user category, and installation permanence, with additional modeling of vehicle propulsion architecture compatibility. CAGRs were derived from weighted average growth contributions across these segments. Industry-specific inputs included LME aluminum price trajectory assumptions and battery-electric fleet penetration curves.
Sensitivities concentrate around NHTSA roof crush standard revisions, EU REACH substance restriction expansions, and aluminum commodity price volatility. Forecasts reflect documented assumptions regarding electrified vehicle payload constraint evolution and aftermarket channel shift velocity. Macroeconomic contraction, regulatory timeline acceleration, or composite material breakthrough adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Dunnage Trays Market
Industrial Packaging
Overpack Drum Market
Industrial Packaging
Bulk Packaging Market
Industrial Packaging
Industrial Chemical Packaging Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Slip Sheets Market
Industrial Packaging
Global Industrial Wooden Crates Market
Industrial Packaging
Rigid IBC Market
Industrial Packaging
Corrugated Octabins Market
Industrial Packaging
Corrugated Automotive Packaging Market
Industrial Packaging
Industrial Pails Market
Industrial Packaging
Corrugated Bulk Bins Market
Industrial Packaging
Industrial Filling Machine Market
Industrial Packaging
Industrial Bulk Packaging Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Industrial Packaging Market