
 Corrugated Bulk Bins Market | 2026-2036
Corrugated Bulk Bins Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Bulk Bins Market Analysis
Recycled corrugated fiberboard is pivoting toward double-wall and coated board grades as brand owners replace rigid plastic intermediate bulk containers in food and pharmaceutical logistics. Mondi Group leverages captive kraft paper supply across Central European mills to control input costs. Smurfit Kappa Group anchors its position through integrated recycling operations that sustain closed-loop fiber recovery. WestRock Company differentiates via automated box-making technology that reduces lead times for custom bulk bin orders.
Corrugated bulk bins are heavy-duty fiberboard containers engineered with flute profiles ranging from B-flute to triple-wall configurations, designed to transport and store granular, liquid, or palletized loads from fifty to several thousand kilograms. Folding bins dominate procurement volumes due to their flat-ship efficiency and warehouse space savings, while stackable variants command premium positioning in automated distribution centers where vertical density drives throughput. Double-wall board captures the fastest growth trajectory as e-commerce fulfillment networks require enhanced crush resistance for multi-tier stacking without pallet support.
REACH compliance and the EU Packaging and Packaging Waste Regulation mandate recyclability thresholds and extended producer responsibility schemes that redirect procurement toward certified fiber sources. The FDA's food contact substance notifications and ISO 22000 food safety management standards govern pharmaceutical and food-grade bulk bin specifications in North American supply chains. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York, where packaging fee structures will recalibrate total cost of ownership calculations for plastic-to-fiber substitutions.
Market Dynamics
The corrugated bulk bins market is undergoing structural compression as food and beverage processors systematically dismantle single-use plastic intermediate bulk containers from their supply chains, driven by extended producer responsibility mandates and automated warehouse density requirements.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability thresholds and producer responsibility schemes redirect procurement toward certified fiber sources across member states.
- Automotive component logistics:Germany's supply corridors are expanding reusable bulk packaging adoption to reduce packaging waste in just-in-time manufacturing networks.
- Double-wall flute technology:Enhanced crush resistance enables multi-tier stacking without pallet support in e-commerce fulfillment centers.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container feedstock prices fluctuate with municipal collection rates and export demand to Asian paper mills.
- Central European mill concentration:Kraft paper supply consolidates in a narrow geographic band, exposing converters to regional energy price shocks.
- Moisture resistance limitations:Uncoated fiberboard degrades in cold-chain pharmaceutical logistics where condensation cycles repeat.
Strategic Opportunities
- India's pharmaceutical cold chain:CDSCO temperature compliance requirements create entry points for coated bulk bins in vaccine distribution networks.
- California extended producer responsibility:Packaging fee structures recalibrate total cost of ownership calculations for plastic-to-fiber substitutions.
- RFID-embedded smart packaging:Track-and-trace integration with warehouse management systems enables condition monitoring during transit.
Industry Challenges
- ISO 22000 food safety certification timelines:Auditing backlogs delay market entry for new converters targeting pharmaceutical and food-grade specifications.
- Automated box-making capex requirements:Custom order fulfillment demands capital-intensive equipment that mid-tier converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Bulk Bins Market |
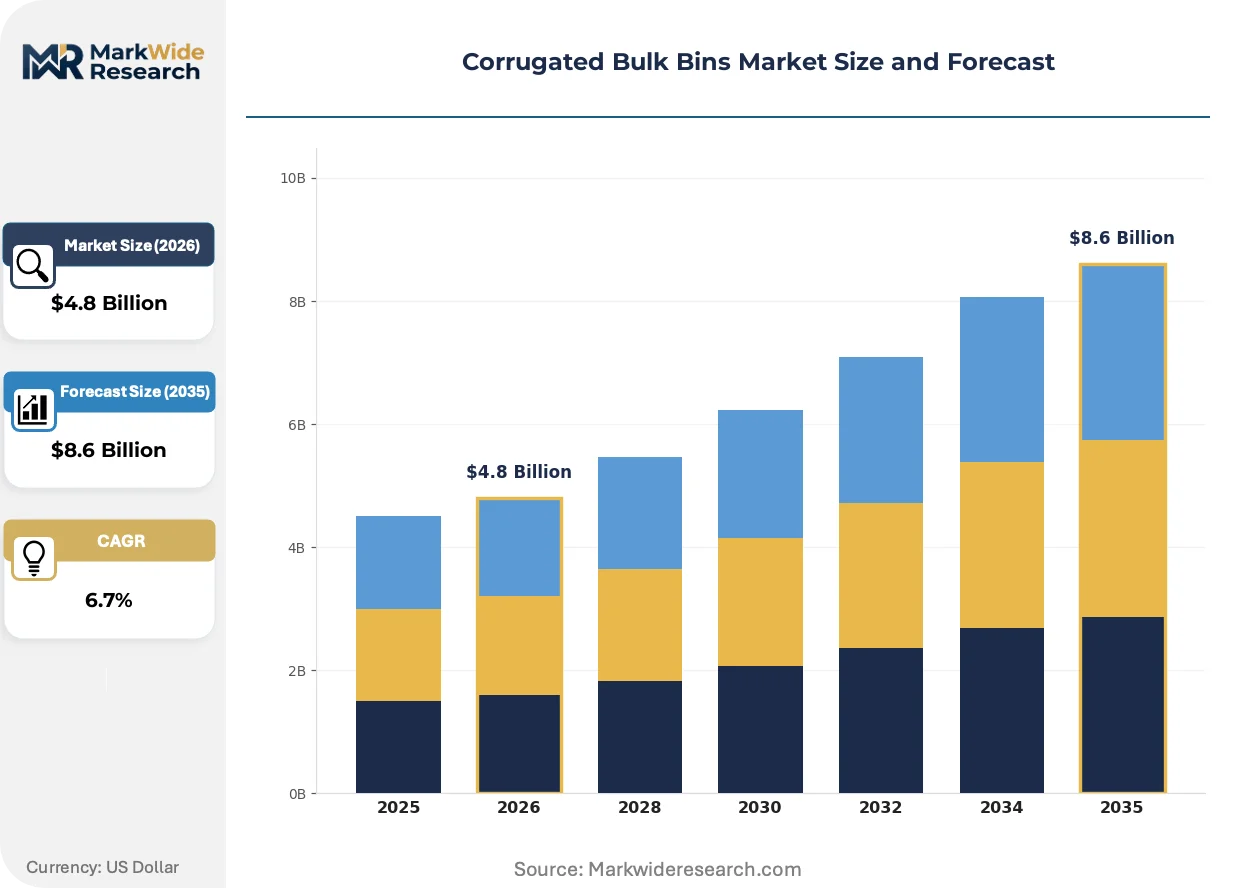
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stackable Bins, Folding Bins, Bulk Boxes, Collapsible Bins Material: Recycle Board, Kraft Paper, Coated Board, Double-Wall Board End User: Food & Beverage, Retail, Agriculture, Pharmaceutical Capacity: Small Size, Medium Size, Large Size, Extra-Large Size |
| Companies Covered | WestRock Company, International Paper Company, Mondi Group, Sonoco Products Company, Greif Inc., Smurfit Kappa Group, DS Smith Plc, Georgia-Pacific LLC, Packaging Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Bulk Bins Market Emerging Trajectories
Corrugated bulk packaging is converging with sensor technology and circular material flows, compressing lead times while embedding compliance documentation directly into container specifications.
Coated barrier technologies are integrating moisture-resistant chemistries into double-wall and triple-wall configurations. Pharmaceutical distributors in the Rhine-Ruhr industrial cluster are adopting these grades for temperature-sensitive APIs. The technology is integrating food contact safety documentation with automated quality assurance systems.
REACH compliance mandates are tightening substance restrictions on coatings and adhesives used in food-contact applications. Industrial consequence includes reformulation costs for converters serving EU markets. Pharmaceutical logistics in Germany and France are responding by consolidating procurement around pre-certified supply chains.
Buyers are compressing supplier qualification cycles from multi-year frameworks to annual re-tendering with sustainability scorecards. Automotive tier-one suppliers in Stuttgart and Wolfsburg are unbundling packaging from logistics contracts to secure fiber-based alternatives. This pattern is most visible in Germany's automotive supply corridors where OEM sustainability targets cascade downward.
Corrugated Bulk Bins Market Segmentation
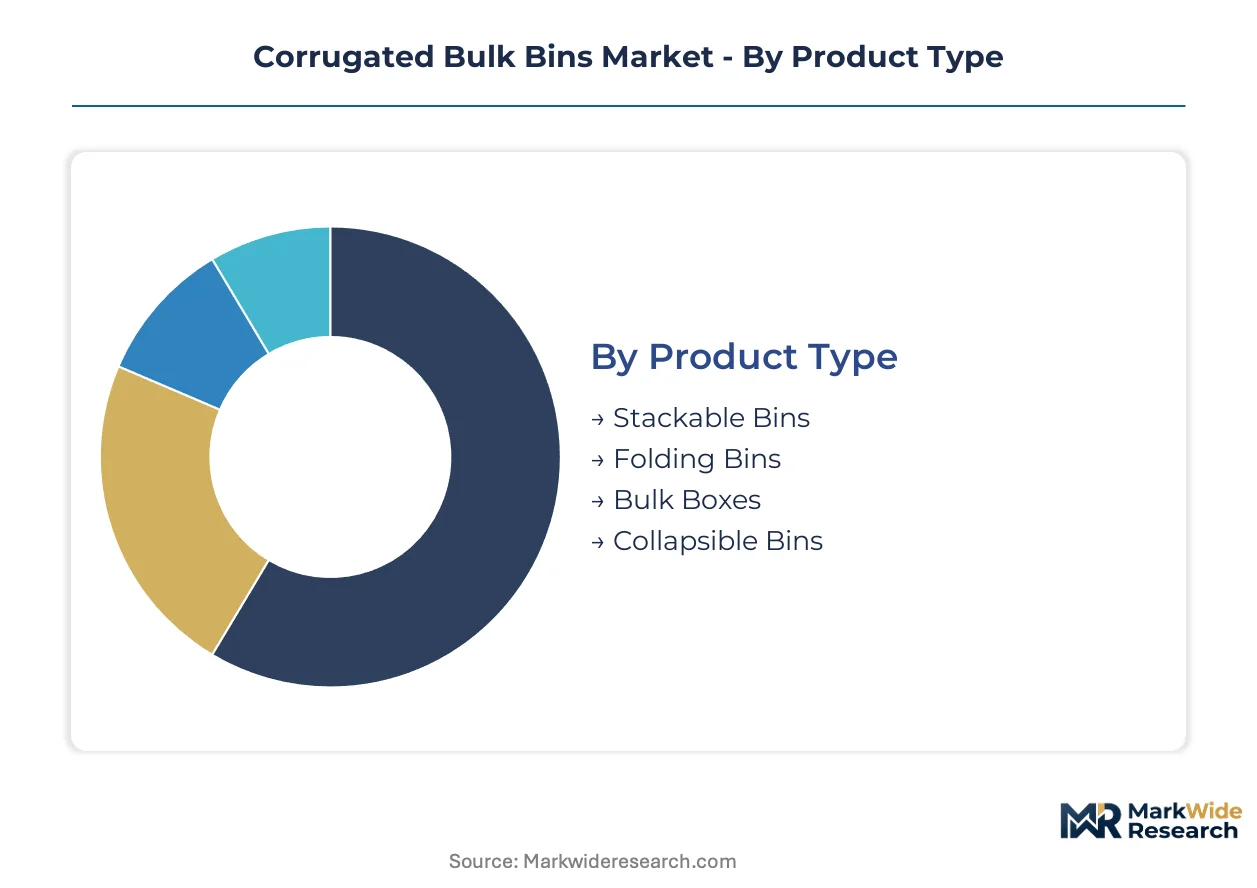
Corrugated bulk bin procurement splits across four structural dimensions. Product type and material grade determine unit economics and reuse cycles. End-user verticals impose divergent compliance requirements. Capacity sizing aligns with warehouse automation density and transport modal constraints.
Product Type:
Replacement cycles accelerate where flat-ship efficiency conflicts with automated handling requirements.
- Folding Bins:Flat-pack designs reduce return freight costs by eighty percent versus rigid alternatives. Food and beverage processors in Germany's Rhine-Ruhr cluster specify these for ingredient consolidation workflows. The format dominates procurement volumes where warehouse space constraints override structural rigidity needs.
- Stackable Bins:Reinforced corner posts and interlocking feet enable vertical stacking to six units high without pallet support. Automated distribution centers in Stuttgart's automotive corridors absorb premium pricing for throughput density gains. REACH-compliant coatings protect load integrity across multi-modal pharmaceutical shipments.
- Collapsible Bins:Quick-assembly designs target seasonal agricultural harvests with minimal storage footprint during off-cycles.
- Bulk Boxes:Fixed-wall configurations serve high-volume grain and mineral applications where return logistics are uneconomical.
Volume placements concentrate in Folding Bins; the faster expansion belongs to Stackable Bins.
Material:
Cost tiers separate commodity fiber from performance-engineered grades.
- Double-Wall Board:Twin flute layers deliver crush resistance exceeding single-wall alternatives by factor of three. E-commerce fulfillment networks in France and the Netherlands specify this grade for multi-tier rack storage without intermediate shelving. The construction supports coated barrier integration for moisture-sensitive pharmaceutical APIs.
- Coated Board:Polymer or wax barriers extend fiber viability through condensation cycles in cold-chain distribution. CDSCO temperature compliance requirements in India's vaccine networks create specification pull for food-contact-certified variants.
- Recycle Board:Post-consumer fiber content satisfies EU Packaging and Packaging Waste Regulation recyclability thresholds at lowest unit cost.
- Kraft Paper:Virgin fiber supply from Central European mills anchors premium positioning where structural consistency cannot tolerate recycled fiber variability.
Procurement weight sits with Recycle Board; the steepest expansion trajectory tracks Double-Wall Board.
End User:
Application-specific compliance documentation fragments supplier qualification pathways.
- Food & Beverage:ISO 22000 certification and FDA food contact substance notifications govern bulk ingredient transport. Processors unbundle packaging from logistics contracts to secure fiber-based alternatives to rigid plastic IBCs under extended producer responsibility frameworks.
- Pharmaceutical:Temperature excursion documentation and batch traceability requirements favor RFID-embedded smart packaging integration. The Rhine-Ruhr industrial cluster consolidates procurement around pre-certified supply chains responding to EMA quality guidelines.
- Agriculture:Seasonal demand spikes and moisture exposure during field storage prioritize cost minimization over reuse cycles.
- Retail:Back-of-store consolidation and reverse logistics for e-commerce returns drive folding format adoption.
Shipment volumes concentrate in Food & Beverage; the sharpest specification escalation appears in Pharmaceutical.
Capacity:
Customer type and handling infrastructure dictate size band selection.
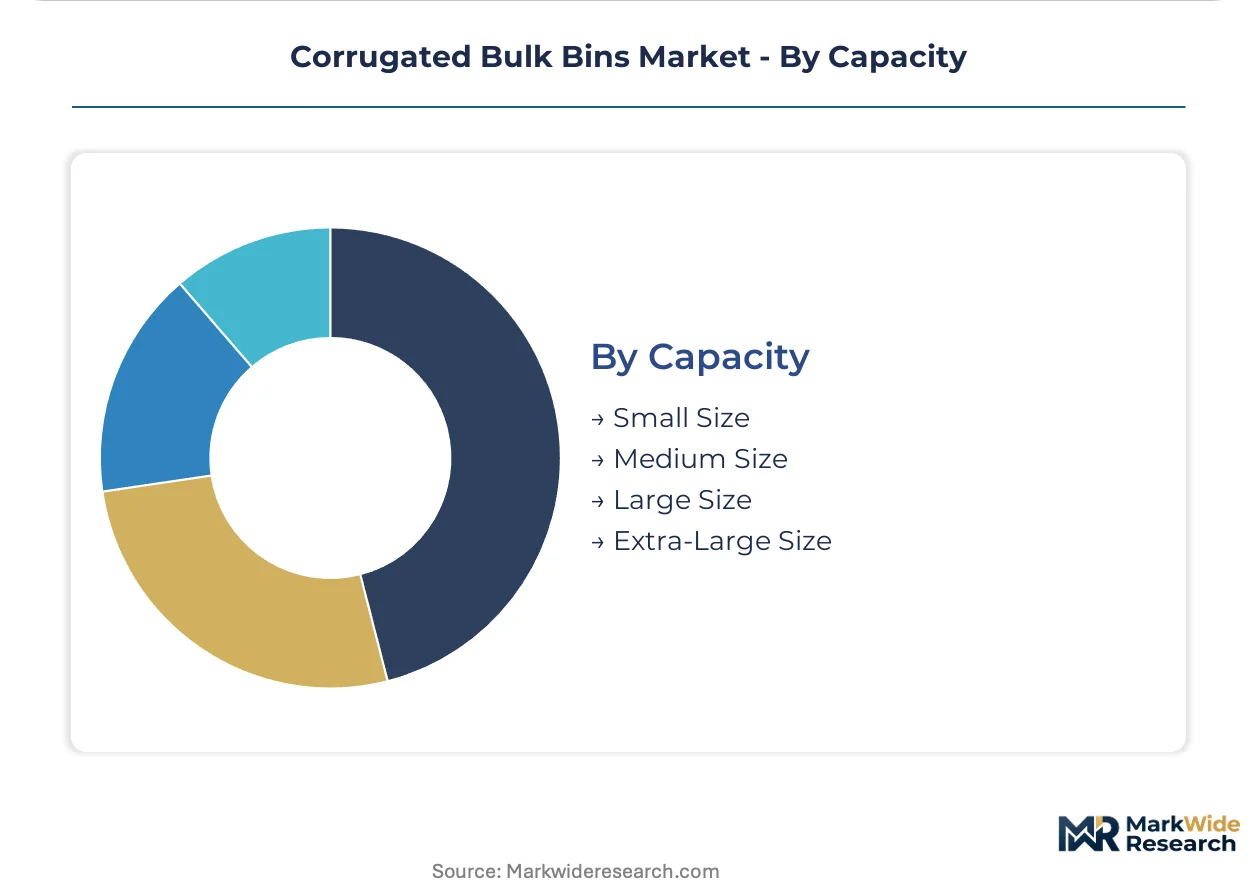
- Large Size:One-thousand-kilogram nominal capacity matches standard pallet footprints for forklift handling in manufacturing feedstock delivery. Germany's automotive tier-one suppliers standardize on this band for just-in-time component sequencing.
- Medium Size:Five-hundred-kilogram capacity bridges manual handling and mechanized warehouse systems. Retail distribution centers deploy these for store replenishment batch sizing.
- Small Size:Sub-fifty-kilogram designs serve pharmaceutical sampling and clinical trial material distribution with individual unit traceability.
- Extra-Large Size:Multi-ton capacities target bulk mineral and agricultural commodity movements where containerization replaces bagged alternatives.
Unit economics favor Large Size deployments; the most rapid format innovation concentrates in Small Size pharmaceutical specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhine-Ruhr industrial cluster tax incentives concentrate corrugated bulk bin procurement around Germany's automotive supply corridors. France's Île-de-France region anchors pharmaceutical logistics demand. India's pharmaceutical cold chain expansion creates specification pull for coated barrier grades.
Germany
Automotive tier-one suppliers in Stuttgart and Wolfsburg unbundle packaging from logistics contracts to secure fiber-based alternatives. The EU Packaging and Packaging Waste Regulation mandates recyclability thresholds that redirect procurement toward certified fiber sources. The Rhine-Ruhr industrial cluster consolidates demand around pre-certified supply chains responding to EMA quality guidelines.
France
E-commerce fulfillment networks in the Netherlands and northern France specify double-wall board for multi-tier rack storage without intermediate shelving. REACH compliance mandates tighten substance restrictions on coatings and adhesives used in food-contact applications. The Île-de-France region anchors pharmaceutical distribution demand for temperature-sensitive APIs.
India
CDSCO temperature compliance requirements in vaccine distribution networks create entry points for coated bulk bins. FSSAI food safety standards govern bulk ingredient transport specifications. Maharashtra's pharmaceutical manufacturing corridor drives specification escalation for RFID-embedded smart packaging with batch traceability integration.
United States
California's extended producer responsibility laws recalibrate total cost of ownership calculations for plastic-to-fiber substitutions. FDA food contact substance notifications govern pharmaceutical and food-grade bulk bin specifications. The Midwest automotive belt standardizes on large-capacity bins for just-in-time component sequencing.
Netherlands
Rotterdam port logistics and distribution networks absorb premium pricing for stackable variants that enable vertical stacking without pallet support. The EU Green Deal circular economy action plan accelerates closed-loop fiber recovery investments. Randstad distribution centers deploy medium-capacity bins for retail replenishment batch sizing.
Corrugated Bulk Bins Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated paper producers commanding premium positioning in pharmaceutical-grade specifications while regional converters capture agricultural and seasonal demand. The vendor base organizes around three strategic archetypes: captive pulp integrators with kraft paper supply control, automated box-making specialists with custom order fulfillment capabilities, and recycling-anchored operators sustaining closed-loop fiber recovery. Competitive moves concentrate on backward integration into kraft paper supply and strategic partnerships with warehouse automation providers.
Among North American integrated producers, WestRock Company and International Paper Company exemplify scale-driven archetypes with automated manufacturing footprints. Mondi Group anchors the European captive supply tier through Central European mill networks. These three entities occupy positions that reflect divergent geographic and vertical strategies rather than direct product rivalry.
| Leading Market Players |
|---|
| WestRock Company |
| International Paper Company |
| Mondi Group |
| Sonoco Products Company |
| Greif Inc. |
| Smurfit Kappa Group |
| DS Smith Plc |
| Georgia-Pacific LLC |
| Packaging Corporation of America |
| Others |
Supply Flow & Price Mechanics
Automated box-making technology adoption is compressing lead times for custom bulk bin orders while simultaneously shifting pricing power toward converters with capital-intensive equipment. This production-method transition favors integrated operators in Germany and the Netherlands that control captive kraft paper supply, leaving mid-tier converters exposed to margin erosion from recycled fiber cost volatility.
Pricing Analysis
Volume placements concentrate in commodity-grade folding bins while margins concentrate in pharmaceutical-certified stackable variants. Three-tier pricing structure across premium, standard, and economy levels separates FDA food-contact-certified grades from ISO 22000 pharmaceutical specifications and untreated agricultural board. Pricing pressure stems from old corrugated container feedstock fluctuations tied to Asian export demand. Agricultural processors in India exhibit highest price sensitivity; Rhine-Ruhr automotive tier-one suppliers absorb premium positioning for traceability-embedded formats.
Supply Chain Analysis
Single-source vulnerability sits with Central European kraft paper mills concentrated in Germany, Poland, and the Czech Republic. Raw material flows draw from municipal recovered fiber collection, virgin pulp imports from Nordic producers, and coating chemical supply from Benelux petrochemical corridors. Tariff exposure on coated barrier chemistries under REACH substance restriction reviews threatens input cost stability. Distribution runs through converter-to-OEM direct contracts in automotive corridors and third-party logistics partnerships in pharmaceutical cold chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Double-wall flute technology with integrated RFID traceability is displacing rigid plastic intermediate bulk containers in pharmaceutical and food-grade logistics, compressing the transition window for fiber-based packaging adoption.
For Market Incumbents: Extend backward integration into captive kraft paper supply to insulate margin structures from OCC feedstock volatility. Invest in automated box-making capacity additions in the Rhine-Ruhr corridor to capture automotive unbundling trends. Pre-certify supply chains under EMA quality guidelines before ISO 22000 auditing backlogs clear.
For New Entrants and Emerging Players: Enter via India's pharmaceutical cold chain expansion, where CDSCO temperature compliance requirements create specification pull for coated bulk bins with limited incumbent penetration. Target Maharashtra's vaccine distribution networks with RFID-embedded smart packaging differentiated by batch traceability integration.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated paper producers seeking automated manufacturing footprints. Long-term viability hinges on converters with pre-certified pharmaceutical supply chains and closed-loop fiber recovery operations. Watch California extended producer responsibility implementation as inflection signal for plastic-to-fiber substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Paper Supply | Captive pulp control insulates Mondi Group and Smurfit Kappa from OCC price volatility in Central European mills. |
| Automated Box-Making Capacity Expansion | WestRock Company's custom order fulfillment technology compresses lead times for automotive tier-one suppliers in Stuttgart. |
| Coated Barrier Technology Development | Moisture-resistant double-wall configurations penetrate Rhine-Ruhr pharmaceutical API distribution under EMA guidelines. |
| RFID-Embedded Smart Packaging Launch | Track-and-trace integration with warehouse management systems enables condition monitoring for CDSCO-compliant vaccine shipments. |
| Closed-Loop Fiber Recovery Investment | Integrated recycling operations sustain circular material flows responding to EU Packaging and Packaging Waste Regulation thresholds. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this corrugated bulk bins market analysis. Primary interviews with packaging procurement managers at automotive OEMs, pharmaceutical logistics directors, corrugated converter operations heads, and sustainability compliance officers combined with FDA food contact substance notifications, EU Packaging and Packaging Waste Regulation implementation documents, and OCC price index reports. Bottom-up shipment data triangulated against top-down pulp and paper capacity estimates.
Granularity-level modeling deployed product-type splits across folding, stackable, collapsible, and bulk box formats; material-grade segmentation across double-wall, coated, recycle, and kraft paper tiers; and end-user verticals spanning food and beverage, pharmaceutical, agriculture, and retail channels. CAGRs derived from historical shipment trajectories and substitution elasticity assumptions for plastic-to-fiber transitions. Forecast inputs incorporated EU extended producer responsibility fee structures and e-commerce fulfillment network automation capex cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under energy price shock scenarios affecting Central European mill economics and accelerated REACH substance restriction timelines. Forecasts reflect documented assumptions on substitution rates and regulatory implementation schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Cone Bottom Tank Market
Industrial Packaging
Industrial Packaging Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Anti-Static Reel Racks Market
Industrial Packaging
Bulk Liquid Transport Packaging Market
Industrial Packaging
Industrial Chemical Packaging Market
Industrial Packaging
Asia-Pacific Warehouse Drums and Barrel Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Industrial Filling Machine Market
Industrial Packaging
Slip Sheets Market
Industrial Packaging
Corrugated Automotive Packaging Market
Industrial Packaging
Bulk Packaging Market
Industrial Packaging
Global Industrial Wooden Crates Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Overpack Drum Market
Industrial Packaging
Rigid IBC Market