
 Global Immunoprotein Diagnostic Testing Market | 2026-2036
Global Immunoprotein Diagnostic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Immunoprotein Diagnostic Testing Market Intelligence
Subscription-based access to proprietary antibody assay panels and analytical software is realigning how clinical laboratories procure and utilize diagnostic technologies. F. Hoffmann-La Roche Ltd leverages its extensive portfolio of automated immunoassay platforms to secure long-term contracts with hospital networks. Siemens Healthineers AG specializes in high-throughput systems for large, centralized diagnostic centers, while Abbott Laboratories differentiates through its strong presence in point-of-care and rapid testing solutions.
Immunoprotein diagnostic testing involves the detection and quantification of specific proteins, such as antibodies or antigens, using highly specific immunological reactions. These tests rely on the binding between an antibody and its antigen, often using labeled reagents to produce a measurable signal like light or color. Among available technologies, ELISA and chemiluminescent immunoassays represent the dominant platforms for high-volume testing. While infectious disease detection constitutes the largest application segment, cancer biomarker identification offers significant future growth potential.
Regulatory frameworks from the US Food and Drug Administration (FDA), the European Medicines Agency (EMA), and China's NMPA govern the approval of in-vitro diagnostic products. These agencies mandate stringent validation for analytical sensitivity, specificity, and clinical performance, directly influencing development timelines and market access. Navigating the evolving requirements for companion diagnostics and the integration of multiplex assays will be a critical determinant of future competitive success.
Market Dynamics
The central force shaping the immunoprotein diagnostic testing market is the convergence of high-sensitivity assay development with stricter regulatory demands for clinical performance. This dynamic compels manufacturers to invest heavily in validating multiplex and companion diagnostics for oncology and infectious diseases.
Growth Catalysts
- Technology Advancement:The development of high-sensitivity chemiluminescent immunoassays (CLIA) and digital ELISA platforms enables earlier and more precise detection of low-abundance protein biomarkers, particularly for cancer and neurological disorders.
- Public Health Policy:National screening programs and healthcare infrastructure investments, especially in China and India, are expanding patient access to advanced diagnostic testing and increasing overall test volumes.
- Expanding Applications:The rising global incidence of chronic and infectious diseases drives consistent demand for established immunoprotein tests while fueling research into novel biomarkers for emerging health threats.
Market Restraints
- High Capital Costs:The significant initial investment required for high-throughput automated immunoassay systems creates a substantial barrier to entry for smaller clinical laboratories and facilities in resource-limited settings.
- Regulatory Hurdles:Stringent and lengthy validation pathways mandated by agencies like the US FDA and under Europe's IVDR can significantly delay the market introduction of new diagnostic tests.
- Technical Limitations:Assay performance can be compromised by issues like antibody cross-reactivity and matrix effects from complex patient samples, requiring extensive optimization and validation to ensure clinical accuracy.
Strategic Opportunities
- Geographic Expansion:Underpenetrated markets in Southeast Asia and Latin America offer significant growth potential as healthcare spending and diagnostic infrastructure improve, creating new demand for immunoprotein tests.
- Multiplex Assay Development:Creating panels that can simultaneously measure a suite of protein biomarkers from a single sample offers a major opportunity in diagnosing complex syndromes like sepsis or autoimmune diseases.
- AI Integration:Applying machine learning algorithms to analyze large datasets from immunoassay platforms can uncover novel patterns and improve the predictive power of diagnostic biomarkers, creating value-added analytical services.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of qualified laboratory technicians and bioinformaticians capable of operating complex immunoassay platforms and interpreting multiplex data hampers operational efficiency.
- Assay Standardization:The lack of harmonization in calibrators and reference materials across different diagnostic platforms leads to inter-laboratory variability, complicating the comparison of patient results and clinical trial data.
- Data Management Compliance:Ensuring the security and privacy of patient data on networked diagnostic instruments, in adherence to regulations like HIPAA and GDPR, presents a continuous operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Immunoprotein Diagnostic Testing Market |
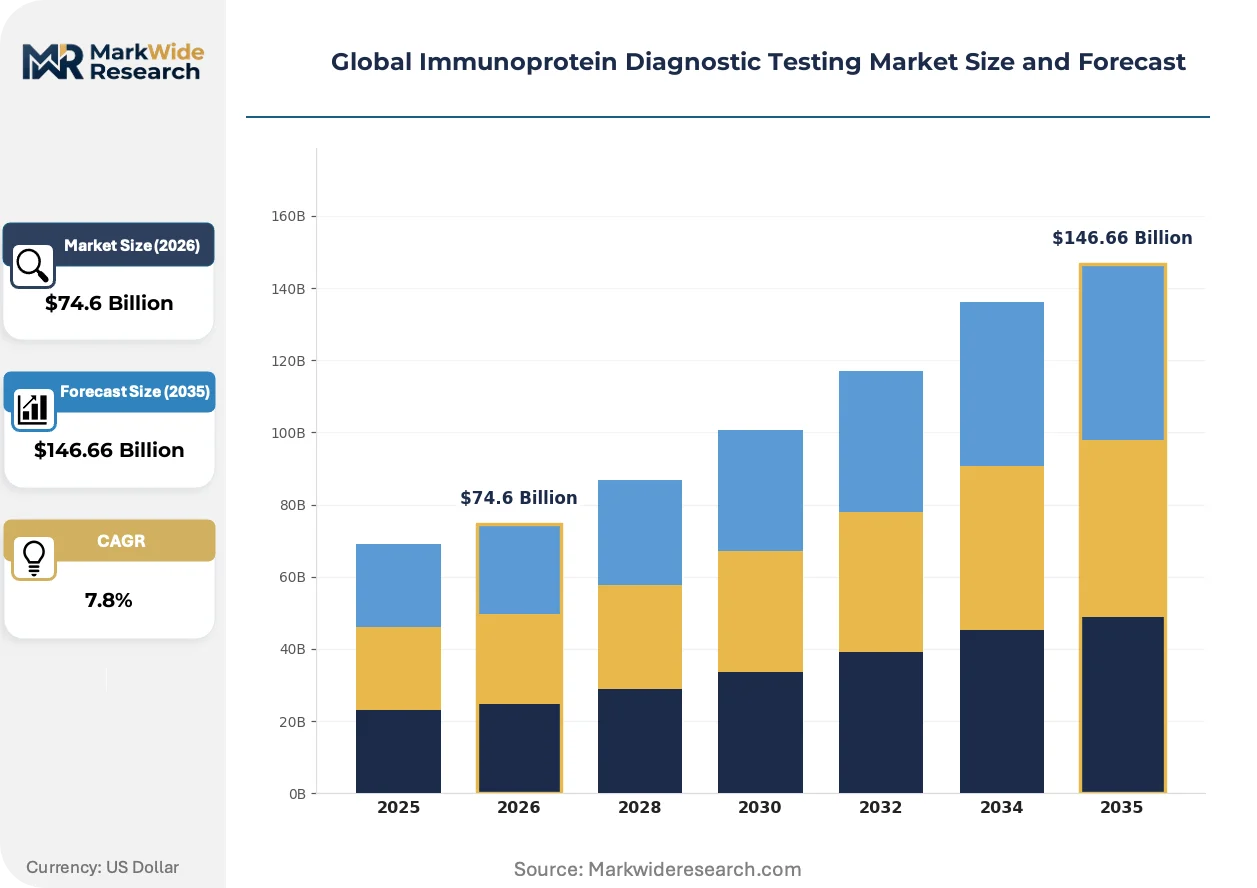
| Market Size in 2026 | $74.6 Billion |
| Market Size in 2035 | $146.66 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibody Assays, Antigen Assays, Enzyme Immunoassays, Radioimmunoassays, Fluorescent Immunoassays, Chemiluminescent Immunoassays Application: Infectious Disease Detection, Autoimmune Disorder Analysis, Allergy Testing, Cancer Biomarker Identification, Transplant Screening, Vaccine Evaluation End User: Clinical Laboratories, Research Institutes, Diagnostic Centers, Biotechnology Firms, Academic Institutions, Contract Research Organizations Technology: Western Blotting, ELISA, Flow Cytometry, Immunofluorescence, Lateral Flow Assays, Multiplex Assays |
| Companies Covered | F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Abbott Laboratories, Thermo Fisher Scientific Inc, Bio-Rad Laboratories, Inc., Danaher Corporation, Agilent Technologies, Inc., PerkinElmer Inc., DiaSorin SPA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Immunoprotein Diagnostic Testing Market Strategic Shifts & Innovations
The market's evolution is defined by a push towards decentralization and digitalization. This movement is fundamentally altering how diagnostic information is generated, analyzed, and integrated into clinical workflows, shifting value from standalone tests to connected data ecosystems.
Microfluidics technology enables rapid immunoprotein testing using minimal sample volumes, often integrated into compact point-of-care (POC) devices. Its adoption is accelerating in emergency departments, outpatient clinics, and remote healthcare settings. This technology is automating previously manual laboratory steps, reducing test turnaround times and enabling faster clinical decisions directly at the patient's side.
New regulatory frameworks, particularly the European Union's In Vitro Diagnostic Regulation (IVDR), are imposing stricter requirements for clinical evidence and post-market surveillance. This action increases the data generation burden for manufacturers throughout a product's lifecycle. Companion diagnostics are most affected, as developers must navigate synchronized approval pathways with both pharmaceutical and IVD regulatory bodies like the EMA and FDA.
A transition toward subscription-based business models for proprietary assay panels and analytical software is gaining traction. This approach disrupts the traditional transactional sale of instruments, replacing it with recurring revenue streams tied to long-term service contracts. The shift is most visible among large, consolidated hospital networks in the United States and Western Europe seeking predictable operational costs and continuous platform upgrades.
Global Immunoprotein Diagnostic Testing Market Segmentation
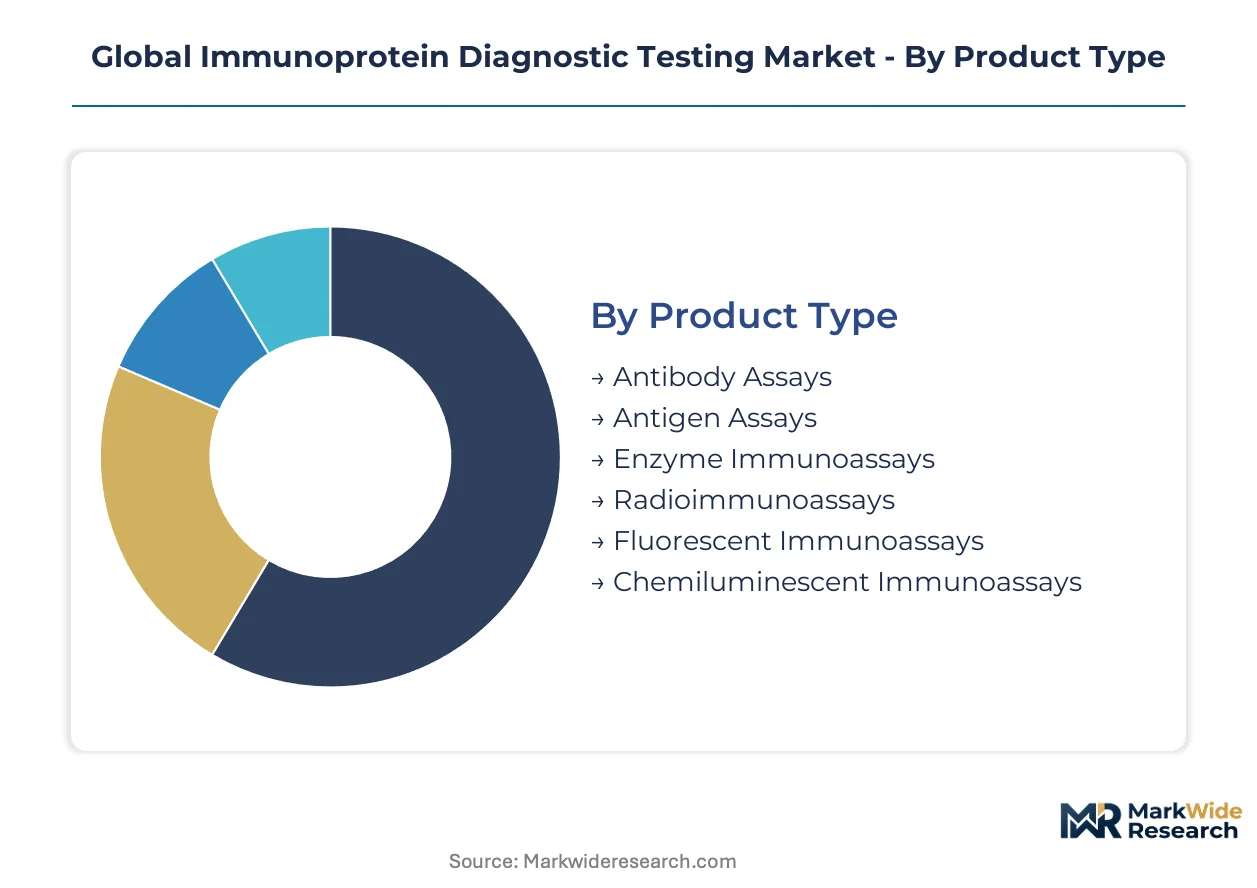
The global immunoprotein diagnostic testing market delineates into several key segments, each reflecting distinct operational characteristics and growth trajectories. Understanding these classifications provides clarity on where innovation is occurring and how market participants are differentiating their offerings. This granular view informs strategic decisions for manufacturers and healthcare providers across diverse applications.
Product Type:
The market for immunoprotein diagnostic products undergoes an upgrade cycle, replacing older technologies with more sensitive and automated platforms. This shift impacts procurement strategies for clinical laboratories seeking enhanced diagnostic capabilities.
- Chemiluminescent Immunoassays:These assays generate a light signal through a chemical reaction, offering superior sensitivity for detecting low-abundance biomarkers. Demand concentrates in specialized laboratories for oncology and infectious disease screening, driven by earlier detection needs.
- Enzyme Immunoassays:ELISA platforms utilize enzyme-linked antibodies to produce a signal, providing a versatile and widely adopted method for protein detection. High-volume diagnostic centers use ELISA for routine infectious disease surveillance, benefiting from cost-effectiveness.
- Antibody Assays:These tests identify specific antibodies in patient samples, crucial for diagnosing autoimmune conditions and assessing immune responses.
- Antigen Assays:Antigen tests directly detect specific antigens from pathogens or disease markers, supporting rapid diagnosis of acute infections.
- Fluorescent Immunoassays:Utilizing fluorescent labels, these assays offer precise quantification and integrate into automated systems for multiplex analysis.
- Radioimmunoassays:Employing radioisotopes, these highly sensitive assays find use in niche applications, particularly for hormones and therapeutic drug monitoring.
Volume placements concentrate in Enzyme Immunoassays; faster expansion belongs to Chemiluminescent Immunoassays.
Application:
The utility of immunoprotein diagnostic testing spans broad medical applications, addressing critical needs across various disease states. Each segment presents unique challenges for assay development and clinical integration, influencing R&D resource allocation.
- Infectious Disease Detection:This segment identifies pathogens or their immune responses, forming the largest application due to persistent global infectious disease burden. National public health programs and hospital laboratories consistently demand these tests.
- Cancer Biomarker Identification:Immunoprotein tests in oncology detect specific protein markers associated with cancer presence, progression, or treatment response. Specialized laboratories leverage these assays for early diagnosis and monitoring treatment efficacy, benefiting from high-sensitivity platforms.
- Autoimmune Disorder Analysis:These applications involve detecting autoantibodies, critical for diagnosing and managing conditions like rheumatoid arthritis and lupus.
- Allergy Testing:Immunoprotein assays quantify allergen-specific antibodies, aiding in the diagnosis and management of allergic reactions.
- Transplant Screening:Tests in this area assess immune compatibility between donor and recipient, minimizing rejection risks in organ transplantation.
- Vaccine Evaluation:Immunoprotein diagnostics measure antibody levels to evaluate vaccine efficacy and population immunity against infectious agents.
Infectious Disease Detection accounts for the largest test volumes; Cancer Biomarker Identification is expanding most quickly.
End User:
The diverse landscape of end-users for immunoprotein diagnostic tests reflects varying operational scales, regulatory environments, and procurement patterns. Each organization type requires tailored solutions, from high-throughput automated systems to specialized platforms.
- Clinical Laboratories:These facilities perform a broad range of diagnostic tests for patient care, serving hospitals and physician offices. They represent the largest end-user segment, consistently demanding robust and efficient immunoassay platforms for routine testing.
- Diagnostic Centers:Often larger and more centralized than clinical laboratories, these centers specialize in high-volume testing, serving multiple healthcare providers. Their focus on efficiency and automation makes them significant purchasers of advanced diagnostic systems.
- Research Institutes:These institutions utilize immunoprotein tests for basic and translational research, exploring novel biomarkers and disease mechanisms.
- Biotechnology Firms:Companies in this sector develop and commercialize new diagnostic assays, often requiring immunoprotein testing for product validation and R&D.
- Academic Institutions:Universities and teaching hospitals use these tests for educational purposes, clinical trials, and fundamental scientific investigations.
- Contract Research Organizations:CROs provide specialized research services to pharmaceutical and biotechnology companies, including extensive immunoprotein testing for clinical studies.
Clinical Laboratories drive the majority of revenue; Diagnostic Centers are increasing their purchasing power.
Technology:
The underlying technologies for immunoprotein diagnostic testing vary significantly in their maturity, throughput, and analytical capabilities. This diversity allows for a wide range of applications, from rapid point-of-care diagnostics to laboratory-based multiplex analyses.
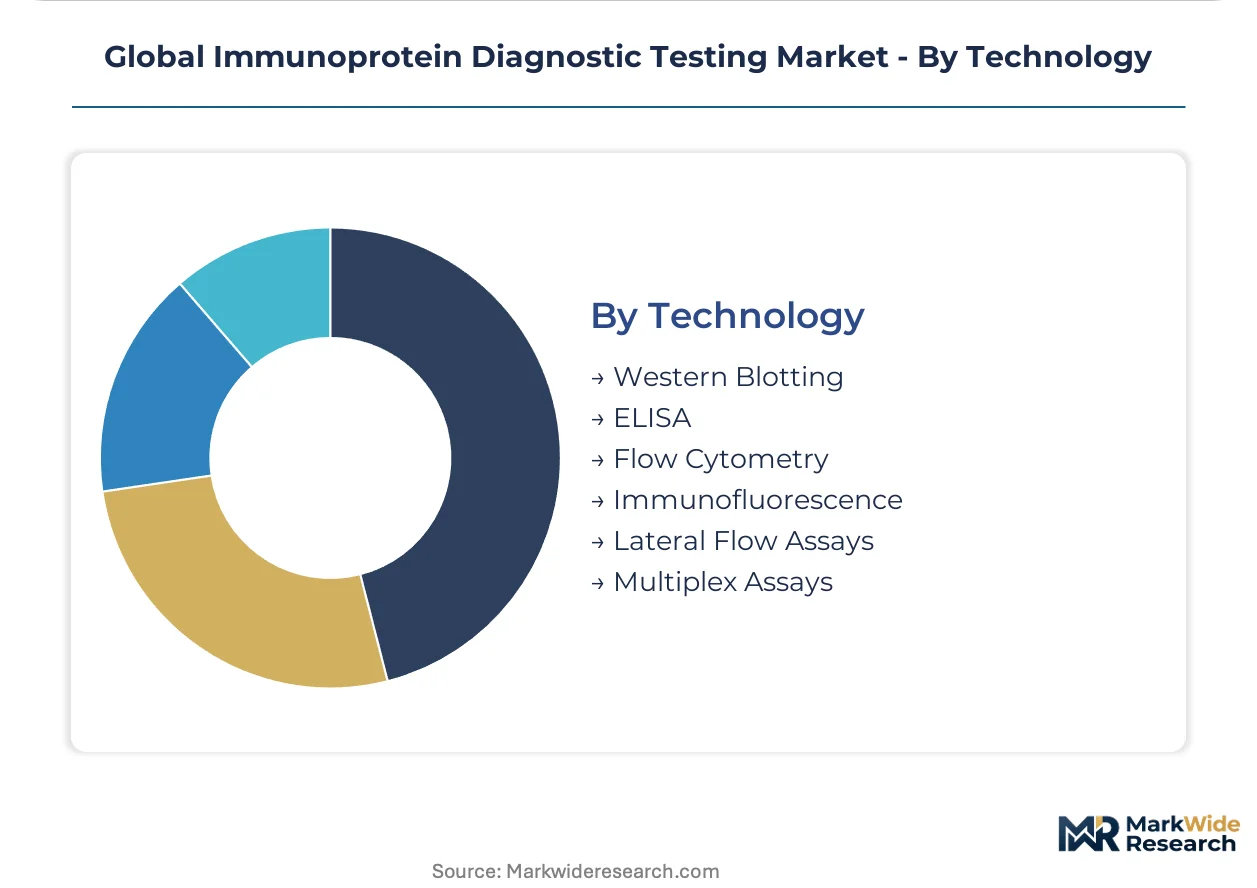
- ELISA:Enzyme-Linked Immunosorbent Assays remain a foundational and widely adopted technology due to versatility, cost-effectiveness, and established high-volume screening protocols. Clinical laboratories and diagnostic centers rely on ELISA for broad infectious disease and hormone testing.
- Multiplex Assays:These advanced platforms simultaneously detect multiple protein biomarkers from a single sample, offering comprehensive diagnostic insights and improved efficiency. Adoption grows in oncology and autoimmune disease diagnostics for superior clinical utility.
- Lateral Flow Assays:These rapid, point-of-care devices provide quick qualitative or semi-quantitative results, widely used for infectious disease screening and pregnancy tests.
- Flow Cytometry:This technology analyzes cell populations by detecting fluorescently labeled antibodies, essential for immunology research and hematological diagnostics.
- Immunofluorescence:Utilizing fluorescent dyes, immunofluorescence visualizes antigens or antibodies in tissue sections or cells, crucial for pathology and autoimmune disease diagnosis.
- Western Blotting:A robust technique for protein detection and characterization, Western Blotting confirms specific protein presence and is often used for confirmatory infectious disease testing.
ELISA maintains its dominance in installed base; Multiplex Assays represent the future trajectory of advanced diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global immunoprotein diagnostic testing market exhibits a clear divide, with high-volume consumption concentrated in developed economies and emerging markets driving significant new demand. Production capabilities are expanding across key regions, influencing supply chain dynamics. This global landscape shapes investment and market access strategies.
United States
Demand for immunoprotein diagnostics stems from advanced healthcare infrastructure and chronic disease prevalence. The US FDA mandates rigorous validation for novel diagnostic tests, influencing development timelines. Major biotech hubs like Boston and San Francisco drive innovation in high-sensitivity assay development.
Germany
Germany's robust healthcare system and research focus fuel demand for precise immunoprotein tests. The European Medicines Agency (EMA) and IVDR framework impose strict requirements for clinical evidence. Munich and Berlin are centers for medical technology and diagnostic instrument manufacturing.
China
China's substantial public and private healthcare investments are expanding access to immunoprotein diagnostic testing. The NMPA regulates in-vitro diagnostic products, shaping market entry and product approvals. Shanghai and Shenzhen host rapidly growing diagnostic companies and research centers.
India
Expanding patient access through national screening programs and improving healthcare infrastructure drives immunoprotein test volumes in India. The CDSCO governs diagnostic product approvals, influencing local manufacturing and distribution. Bengaluru and Hyderabad are emerging as key hubs for diagnostic R&D and production.
Japan
Japan's aging population and focus on preventive medicine generate consistent demand for immunoprotein diagnostics. The PMDA oversees regulatory approvals for medical devices and diagnostics, ensuring product quality. Tokyo and Osaka remain key centers for advanced medical technology and research.
Global Immunoprotein Diagnostic Testing Market Key Industry Players
Top-tier vendors anchor the global immunoprotein diagnostic testing market, while specialized players and regional manufacturers offer niche solutions. The market exhibits a tiered structure, with established multinational corporations dominating automated platforms and agile biotechnology firms focusing on novel biomarker discovery. Strategic archetypes include integrated diagnostic providers and specialized assay developers. Dominant competitive moves involve strategic partnerships for technology co-development and continuous portfolio diversification to address new disease areas.
Within the integrated diagnostic providers archetype, F. Hoffmann-La Roche Ltd exemplifies a company leveraging an extensive portfolio of automated immunoassay platforms. Siemens Healthineers AG occupies a strong position with high-throughput systems for centralized diagnostic centers. Abbott Laboratories represents a key player through its significant presence in point-of-care and rapid testing solutions, catering to diverse clinical needs.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc |
| Bio-Rad Laboratories, Inc. |
| Danaher Corporation |
| Agilent Technologies, Inc. |
| PerkinElmer Inc. |
| DiaSorin SPA |
| Others |
Cost & Logistics Intelligence
The European Union's In Vitro Diagnostic Regulation (IVDR) implementation gates both qualified supply and premium-tier pricing access for immunoprotein diagnostic products. This mandate increases data generation burdens for manufacturers, directly impacting market entry and product costs.
Pricing Analysis
Margin tightening in high-throughput immunoassay systems reflects significant capital investment requirements and ongoing R&D costs. The dominant pricing structure involves a hybrid of per-unit transactional sales for routine tests and subscription-based models for proprietary assay panels and analytical software. Price differentiation stems from assay sensitivity for early detection and the level of automation offered by diagnostic platforms. Buyer price sensitivity is highest among smaller clinical laboratories and those in resource-limited settings, while large hospital networks prioritize long-term value and predictable operational costs.
Supply Chain Analysis
Single-source vulnerability sits with specialized reagent and antibody manufacturers, which are critical inputs for immunoprotein tests. Geographic supply concentration includes China, Germany, and India, which are expanding production capabilities for diagnostic components and systems. Raw material dependencies center on highly specific antibodies, labeled reagents, and microfluidic chips. Assay standardization, specifically the lack of harmonized calibrators and reference materials, presents a structural risk. Distribution runs through direct sales channels to clinical laboratories and diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with players pursuing enhanced control over diagnostic platforms and data analytics capabilities.
For Market Incumbents:Hedge against market fragmentation by consolidating automated immunoassay platforms and securing long-term service contracts with hospital networks. Diversify product portfolios to include high-sensitivity chemiluminescent immunoassays and multiplex assays, addressing the threat of emerging specialized diagnostic firms. Invest heavily in R&D for AI integration to enhance biomarker predictive power. Strengthen regulatory affairs teams to navigate evolving requirements from agencies like the US FDA and EMA, ensuring continuous market access.
For New Entrants and Emerging Players:Capture white-space opportunities in underpenetrated markets like Southeast Asia and Latin America by offering cost-effective point-of-care solutions. Focus on developing novel multiplex assay panels for complex conditions such as sepsis or autoimmune diseases, leveraging microfluidics technology. Target resource-limited settings with rapid testing devices for infectious disease screening. A go-to-market angle emphasizing ease of use and rapid turnaround times will resonate with outpatient clinics and emergency departments.
For Investors and Strategic Acquirers:Increased regulatory approvals for companion diagnostics is the leading indicator that validates advanced assay development and market growth. The long-term viability of this market is strong, driven by the persistent global burden of chronic and infectious diseases. Target acquisition archetypes include specialized assay developers with unique biomarker intellectual property, AI-driven data analytics firms, and microfluidics technology innovators. Outcomes are best read as a band of plausibility, not a single trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Microfluidics Innovators | Integrates rapid testing capabilities for point-of-care diagnostics, enhancing Abbott Laboratories' market reach. |
| Investment in AI-Powered Analytics | Unlocks novel biomarker patterns from large datasets, improving predictive power for Siemens Healthineers AG. |
| Development of Multiplex Assay Panels | Offers comprehensive diagnostic insights from single samples, critical for F. Hoffmann-La Roche Ltd's oncology portfolio. |
| Expansion into Underserved Geographic Markets | Captures new demand in regions with improving healthcare infrastructure, extending Bio-Rad Laboratories' footprint. |
| Strengthening Regulatory Compliance Teams | Ensures timely product approvals under stringent frameworks like the IVDR for Thermo Fisher Scientific Inc. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. This approach combined extensive primary interviews with clinical laboratory directors, diagnostic center managers, R&D scientists, and regulatory affairs specialists. We triangulated insights from these stakeholders with data from FDA filings, EMA submissions, NMPA guidelines, and specialized industry reports, applying both bottom-up and top-down validation.
Market volume and value were modeled at a granular level across product type, application, end-user, technology, and regional regulatory compliance. The analytical framework projected market trajectories over the projection horizon, with compound annual growth rates derived from historical trends and future projections. Industry-specific forecast inputs included global disease incidence rates and evolving healthcare spending trends in key economies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory changes, technological breakthroughs, and global health crises. Forecasts reflect assumptions regarding market dynamics and competitive landscapes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Critical Care Diagnostics Market
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
Global Yersiniosis Diagnostics and Treatment Market
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
Global Artificial Intelligence (AI) in Diagnostics Market
Diagnostics
Anatomic Pathology Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
Asia-Pacific Radioimmunoassay Market
Diagnostics
IVD Antibody Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Asia-Pacific Ovarian Cancer Diagnostics Market
Diagnostics
Veterinary Diagnostics Market
Diagnostics
Home Diagnostics Market
Diagnostics
Hepatitis Test Solution and Diagnosis Market