
 Global Coagulation Analyzers Market | 2026-2036
Global Coagulation Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coagulation Analyzers Market Foresight
The EU In Vitro Diagnostic Regulation is broadening replacement demand across European clinical laboratories as legacy coagulation analyzers face recertification deadlines. Siemens Healthineers leverages its installed base of hemostasis systems to sustain service revenue streams across German and French hospital networks. Sysmex Corporation anchors its competitive position through dedicated R&D investment in automated coagulation workflows for high-throughput laboratories.
Coagulation analyzers are electromechanical diagnostic instruments that measure blood clotting parameters including prothrombin time, activated partial thromboplastin time, and fibrinogen concentration using optical, electrochemical, or mechanical detection methods to guide anticoagulant therapy and surgical readiness assessments. PT/INR analyzers dominate routine clinical volume in anticoagulation clinics, while whole blood coagulation analyzers capture expanding demand in point-of-care emergency settings where rapid turnaround overrides laboratory precision requirements. Optical methods lead technology adoption due to established reagent ecosystems, though electrochemical approaches gain traction in portable handheld devices designed for ambulatory and battlefield applications.
The FDA governs premarket clearance pathways for coagulation analyzers through the 510(k) process, while the EU MDR and IVDR impose strengthened clinical evidence requirements that extend approval timelines for new instrument platforms. Japan's PMDA maintains distinct quality management system inspections that shape market entry strategies for multinational manufacturers. Stakeholders must monitor evolving harmonization efforts between FDA and EU regulatory frameworks to anticipate streamlined conformity assessment opportunities.
Market Dynamics
Centralized laboratory consolidation across integrated health networks is compressing purchasing cycles and elevating throughput requirements as the dominant structural force reshaping analyzer procurement specifications.
Growth Catalysts
- EU IVDR Recertification Mandates:Legacy devices face mandatory replacement deadlines across German and French hospital laboratories, accelerating instrument turnover.
- Anticoagulation Clinic Expansion:Outpatient PT/INR monitoring networks in the United States are scaling automated testing capacity to manage direct oral anticoagulant patient volumes.
- Mechanical Detection Methods:Whole blood viscoelastic testing platforms are penetrating emergency departments and surgical suites where rapid turnaround supersedes laboratory precision.
Market Restraints
- Reagent Ecosystem Lock-In:Optical method dominance creates captive supply relationships that elevate lifetime ownership costs and complicate vendor switching.
- European Supply Concentration:Critical photodetector and precision pump components concentrate among specialized German and Swiss component suppliers.
- IVDR Clinical Evidence Burden:Extended approval timelines for new instrument platforms delay market entry and compress returns on R&D investment.
Strategic Opportunities
- India Diagnostic Infrastructure:Tier-two and tier-three cities present underpenetrated demand for compact, mid-throughput analyzers as laboratory networks expand beyond metropolitan centers.
- Battlefield and Ambulatory Point-of-Care:Electrochemical handheld devices address military and remote care settings where laboratory infrastructure is absent.
- Artificial Intelligence Convergence:Machine learning algorithms for coagulation pattern recognition are integrating with analyzer software to reduce manual result interpretation.
Industry Challenges
- IVDR Technical Documentation:Clinical performance study requirements for Class C devices demand specialized regulatory affairs expertise that strains mid-tier manufacturer capabilities.
- Legacy LIS Integration:Hospital information system interoperability with proprietary analyzer data formats creates implementation friction and extended deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coagulation Analyzers Market |
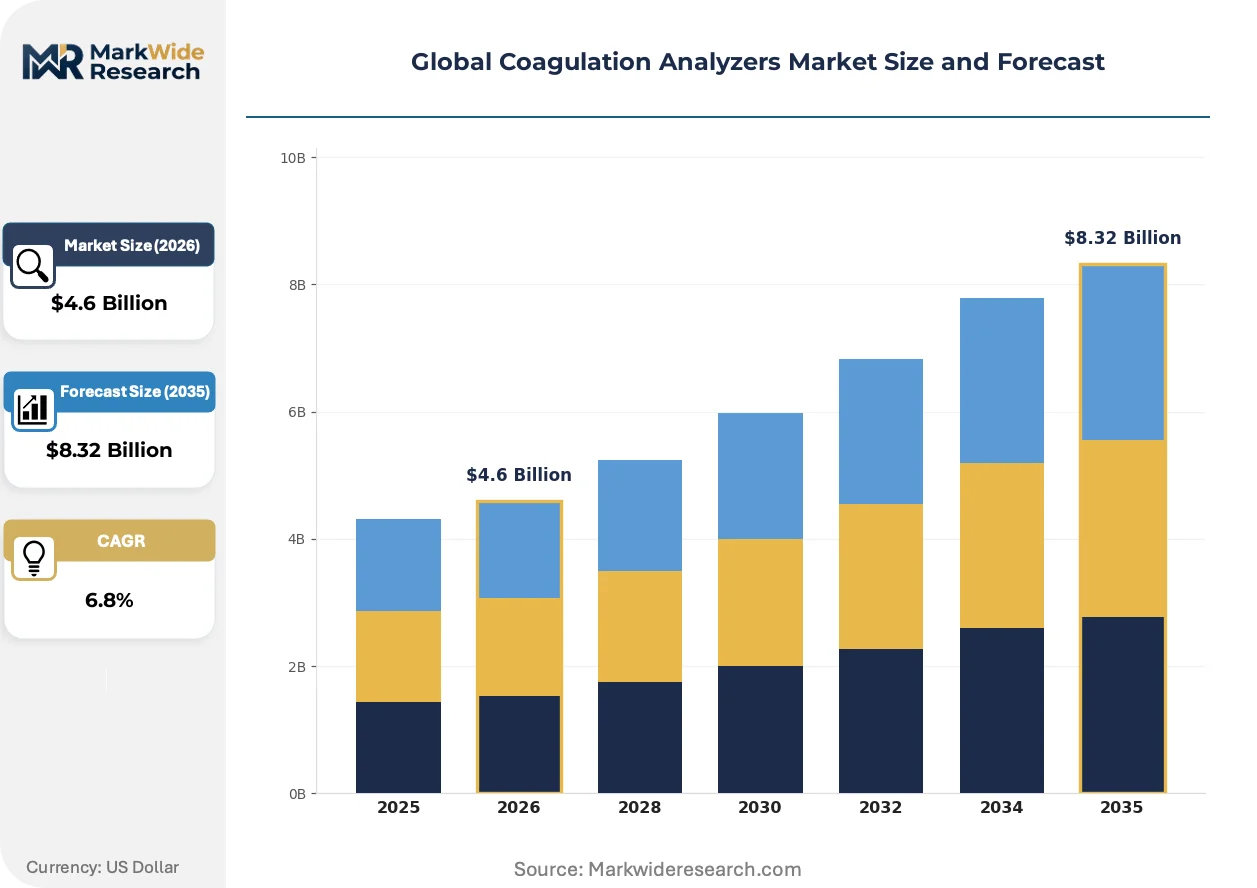
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $8.32 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PT/INR Analyzers, APTT Analyzers, Whole Blood Coagulation Analyzers, Handheld Coagulation Analyzers End User: Hospitals, Diagnostic Laboratories, Blood Banks, Research Institutions Technology: Optical Methods, Electrochemical Methods, Mechanical Methods, Image Analysis Application: Surgery, Hematology, Cardiovascular, Emergency Care |
| Companies Covered | F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Sysmex Corporation, Werfen, Diagnostica Stago, Abbott Laboratories, Thermo Fisher Scientific, Nihon Kohden Corporation, Helena Laboratories Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coagulation Analyzers Market Shifts & Advancements
Automation architectures and detection methodologies are converging to compress turnaround times while regulatory frameworks elevate clinical evidence thresholds for new platform introductions.
Microfluidic cartridge systems are integrating electrochemical sensing elements into single-use disposable formats that eliminate calibration drift and reduce maintenance intervals. Emergency departments in the United States and Japan are adopting these platforms for trauma and perioperative coagulopathy assessment. The technology is integrating rapid diagnostic workflows into settings where traditional laboratory infrastructure cannot be deployed.
Japan's PMDA has tightened quality management system inspection protocols for hemostasis devices, extending premarket review timelines and elevating documentation standards for software-controlled instruments. Domestic manufacturers are restructuring regulatory affairs functions to accommodate intensified post-market surveillance obligations. Multinational entrants are responding by establishing captive regulatory representation in Tokyo to navigate inspection scheduling and response protocols.
Consolidated procurement by regional laboratory networks in the United States is compressing vendor evaluation cycles and elevating total-cost-of-ownership analytics over instrument acquisition price. Integrated delivery networks are unbundling service contracts from hardware purchases and negotiating multi-site maintenance agreements separately. This pattern concentrates most acutely in the Midwest and Southeast regions where hospital system mergers have created super-regional laboratory hubs commanding substantial purchasing leverage.
Global Coagulation Analyzers Market Segmentation
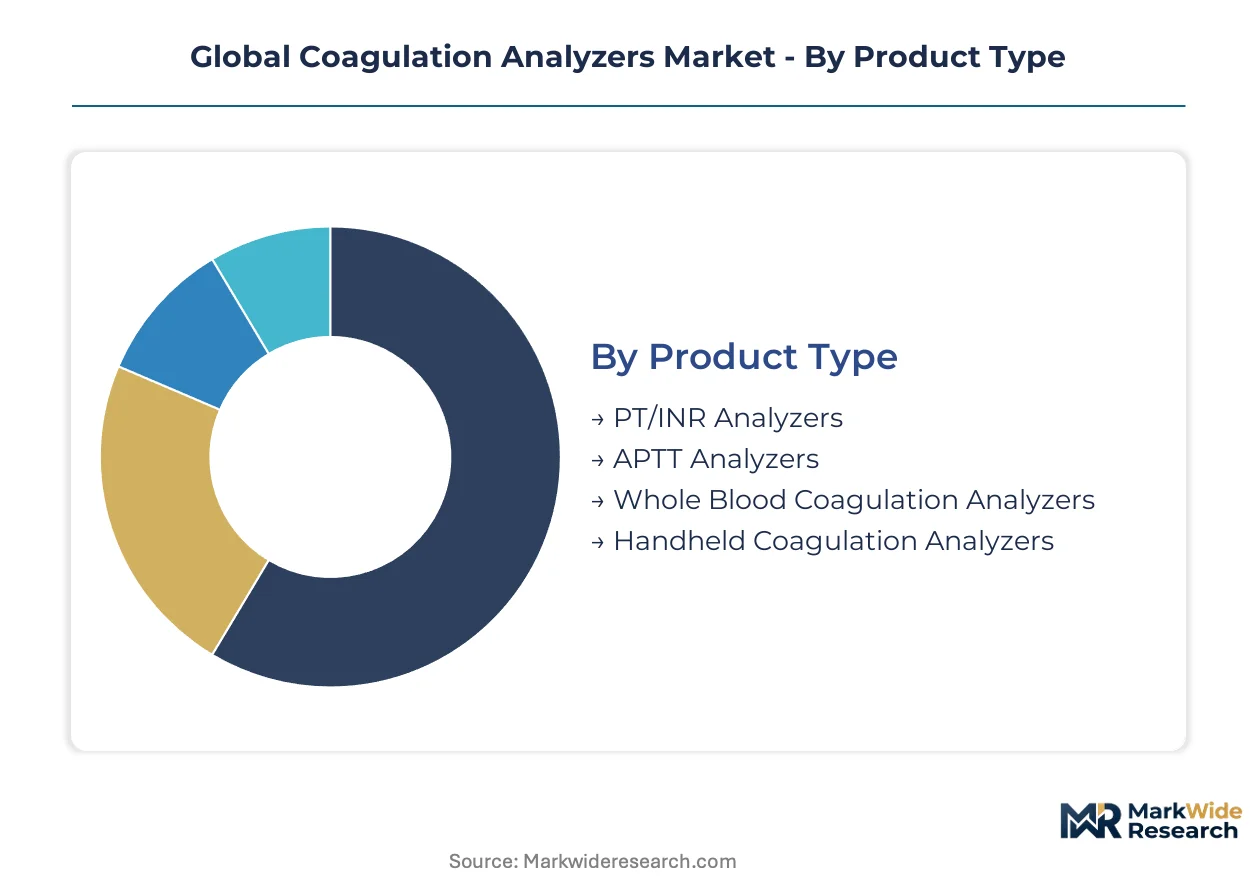
Segmentation in coagulation analyzers reveals distinct regulatory pathways and procurement economics across product architectures. Each category carries specific certification burdens that shape manufacturer R&D allocation and customer switching costs.
Product Type:
IVDR Class C designation applies to automated systems requiring clinical performance studies, while handheld devices fall under lighter conformity routes that compress approval timelines.
- PT/INR Analyzers:Benchtop systems measure prothrombin time and international normalized ratio using optical clot detection. Anticoagulation clinics in the United States deploy these for warfarin monitoring as direct oral anticoagulant patient volumes expand.
- APTT Analyzers:Activated partial thromboplastin time instruments assess intrinsic pathway function through automated sample handling. German hospital laboratories are replacing legacy units ahead of EU IVDR recertification deadlines.
- Whole Blood Coagulation Analyzers:Viscoelastic testing platforms deliver rapid hemostasis assessment in surgical settings.
- Handheld Coagulation Analyzers:Portable electrochemical devices enable point-of-care testing where laboratory infrastructure is absent.
PT/INR Analyzers sit at the top of the volume ranking, with Handheld Coagulation Analyzers climbing the fastest.
End User:
Procurement authority concentrates differently across settings, with integrated health networks commanding price leverage that standalone facilities cannot replicate.
- Hospitals:Centralized laboratory hubs within merged health systems consolidate analyzer purchasing across multiple sites. The Midwest and Southeast United States exhibit the most pronounced super-regional laboratory consolidation.
- Diagnostic Laboratories:Independent reference labs compete on turnaround time and specialized test menus. Commercial laboratories in India are expanding into tier-two and tier-three cities with mid-throughput platforms.
- Blood Banks:Transfusion services require high-reliability screening for donor unit compatibility.
- Research Institutions:Academic medical centers drive adoption of novel detection methodologies.
Hospitals dominate installed base share, though Diagnostic Laboratories are expanding most quickly in emerging markets.
Technology:
Detection methodology determines reagent ecosystem lock-in and service revenue potential over instrument lifetime.
- Optical Methods:Photometric clot detection dominates high-throughput laboratory installations. Established reagent supply relationships elevate switching costs for customers.
- Electrochemical Methods:Amperometric sensing enables miniaturization for portable and disposable formats. Japanese emergency departments are adopting these platforms for trauma assessment.
- Mechanical Methods:Viscoelastic measurement captures whole blood clot dynamics without sample preparation.
- Image Analysis:Computer vision algorithms automate clot endpoint determination.
Optical Methods command the largest installed base, with Electrochemical Methods gaining share fastest in point-of-care segments.
Application:
Clinical setting dictates throughput requirements, turnaround time sensitivity, and reimbursement dynamics.
- Surgery:Perioperative coagulopathy assessment demands rapid viscoelastic testing. United States trauma centers are integrating these workflows into massive transfusion protocols.
- Hematology:Specialized coagulation laboratories manage complex diagnostic workups for bleeding disorders.
- Cardiovascular:Anticoagulation monitoring supports atrial fibrillation and mechanical valve patient management.
- Emergency Care:Point-of-care testing overrides laboratory precision when speed determines clinical outcomes.
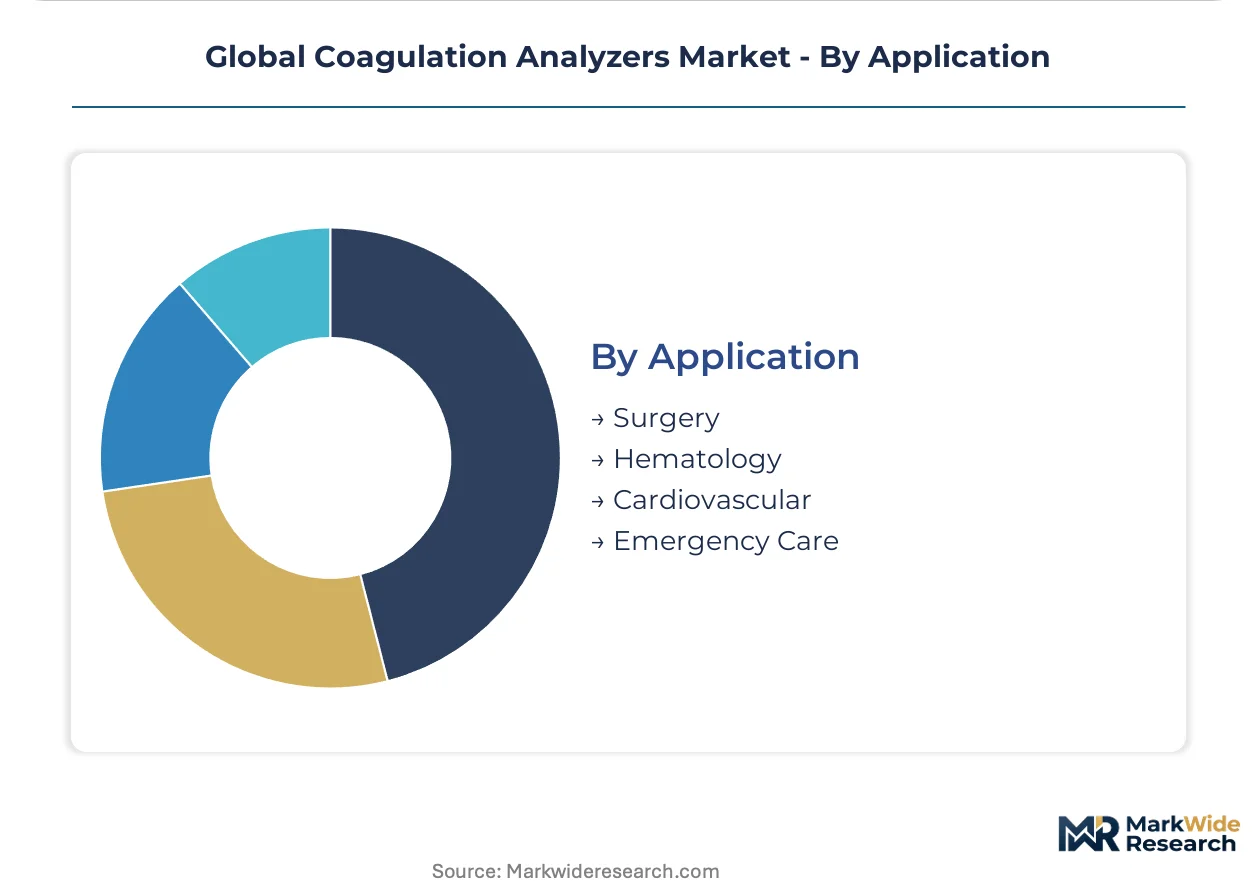
Surgery leads procedure-linked analyzer deployment, while Emergency Care shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hematology technologists and clinical laboratory scientists concentrate in Germany, Japan, and the United States, anchoring regional testing capacity and instrument procurement authority. These workforce clusters shape analyzer specification demands and vendor relationships across their respective health systems.
United States
Integrated delivery networks in the Midwest and Southeast are consolidating laboratory services into super-regional hubs commanding substantial purchasing leverage. FDA 510(k) premarket clearance pathways govern new instrument introductions, with recent guidance tightening software validation requirements. Hospital system mergers in Texas and Florida have created centralized procurement entities managing analyzer fleets across dozens of sites.
Germany
University hospital laboratories in Bavaria and North Rhine-Westphalia are replacing legacy coagulation analyzers ahead of EU IVDR recertification deadlines. The country's national pharmaceutical regulator, BfArM, coordinates with notified bodies on Class C device conformity assessments. Siemens Healthineers maintains deep installed base relationships across German hospital networks, sustaining service revenue streams.
Japan
Emergency departments in Tokyo and Osaka are adopting viscoelastic testing platforms for trauma coagulopathy assessment. PMDA has intensified quality management system inspection protocols, extending premarket review timelines for software-controlled instruments. Domestic manufacturers are restructuring regulatory affairs functions in Yokohama to accommodate post-market surveillance obligations.
India
Commercial diagnostic laboratories are expanding into tier-two and tier-three cities with mid-throughput analyzer platforms. CDSCO medical device rules require import licenses and quality certifications for foreign-manufactured instruments. Laboratory networks in Maharashtra and Karnataka are deploying compact systems to serve previously underserved urban peripheries.
France
Public hospital laboratories in Île-de-France and Auvergne-Rhône-Alpes are modernizing hemostasis testing infrastructure under regional health authority procurement frameworks. ANSM oversees clinical performance study requirements for Class C IVD devices. Diagnostica Stago anchors domestic manufacturing and service capabilities from its base in the Paris region.
Global Coagulation Analyzers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the coagulation analyzer landscape, with integrated diagnostics conglomerates maintaining instrument manufacturing capabilities while specialized firms focus on reagent chemistry and software development. The market structure tilts toward consolidation at the high-throughput laboratory tier, with mid-tier and point-of-care segments retaining more fragmented competitive dynamics. Three archetypes dominate: diversified medtech conglomerates with broad installed bases, hematology specialists with deep hemostasis expertise, and emerging point-of-care disruptors leveraging electrochemical miniaturization. Competitive moves center on IVDR compliance investments and multi-site service contract unbundling.
Among diversified diagnostics conglomerates, F. Hoffmann-La Roche Ltd and Siemens Healthineers AG exemplify the integrated-systems archetype, anchoring competitive positions through extensive installed bases and captive reagent ecosystems. Sysmex Corporation occupies a distinct position as a hematology-focused specialist with dedicated R&D investment in automated coagulation workflows. These three entities represent contrasting strategic postures: Roche and Siemens leverage breadth across diagnostic modalities, while Sysmex concentrates technical resources within hemostasis and related blood analysis domains.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Sysmex Corporation |
| Werfen |
| Diagnostica Stago |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Nihon Kohden Corporation |
| Helena Laboratories Corporation |
| Others |
Supply & Pricing Matrix
Super-regional laboratory procurement hubs in the United States Midwest and Southeast command substantial purchasing leverage, compressing vendor margins and forcing unbundling of hardware from service contracts. This buyer concentration has shifted pricing power toward consolidated health networks while elevating total-cost-of-ownership analytics over acquisition price.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the installed base, with premium tiers anchored by IVDR Class C certification and integrated reagent ecosystems. Price differentiation hinges on throughput capacity and after-sales service bundling, with German and Swiss component sourcing elevating production costs for precision optical systems. Cost compression in mid-tier benchtop segments is intensifying because Indian and Chinese manufacturers are expanding regional assembly capacity. Standalone diagnostic laboratories exhibit the highest price sensitivity, while merged hospital systems leverage volume scale for preferential terms.
Supply Chain Analysis
Direct-to-hospital channels handle super-regional laboratory demand, while distributor networks serve standalone clinics and emerging market expansion. Critical photodetector and precision pump components concentrate among specialized German and Swiss suppliers, with microfluidic cartridge substrates drawing from Japanese polymer specialists. Single-source vulnerability for high-precision optical elements creates exposure to export licensing delays. Distribution runs through captive service organizations for premium tiers and third-party logistics for economy segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU IVDR recertification mandate functions as a regulatory compounder, accelerating replacement cycles across European hospital laboratories and compressing vendor evaluation timelines. This structural demand driver elevates compliance investments above pure price competition.
For Market Incumbents: Acquire specialized regulatory affairs capabilities to navigate IVDR technical documentation burdens for Class C devices. Consolidate service contract portfolios across German and French hospital networks before recertification deadlines crystallize vendor relationships. Electrochemical handheld disruptors threaten point-of-care margins; defend through rapid microfluidic platform development.
For New Entrants and Emerging Players: Begin with compact mid-throughput analyzers for Indian tier-two and tier-three cities where laboratory network expansion outpaces incumbent coverage. Target battlefield and ambulatory point-of-care segments where laboratory infrastructure absence creates white-space demand. Pursue CDSCO import license pathways to establish manufacturing partnerships before foreign competitors deepen local presence.
For Investors and Strategic Acquirers: Diversified diagnostics conglomerates are the most active acquirer in this space, seeking hemostasis specialists to fill portfolio gaps. The five-to-ten year viability window favors platforms with embedded AI pattern recognition and disposable cartridge economics. Monitor PMDA inspection protocol evolution as a signal for Japanese market access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Investment | BfArM-coordinated Class C clinical performance studies extend approval timelines and elevate capital requirements. |
| Microfluidic Cartridge Development | Japanese emergency department adoption of single-use electrochemical formats eliminates calibration drift maintenance. |
| Multi-Site Service Contract Unbundling | Midwest and Southeast integrated delivery networks negotiate maintenance separately from hardware procurement. |
| AI Pattern Recognition Integration | Machine learning algorithms for coagulation result interpretation reduce manual technologist workload. |
| India CDSCO Import License Pathway | Maharashtra and Karnataka laboratory networks require quality certifications for foreign-manufactured instrument deployment. |
Research Methodology
Bottom-up hospital and diagnostic laboratory modeling reconciled against top-down instrument shipment tracking forms the analytical core. Primary interviews with hematology technologists, biomedical engineers, GPO contracts managers, and regulatory affairs specialists were validated against secondary sources including FDA 510(k) filings, EU IVDR notified body documentation, PMDA quality management inspection records, and hospital procurement databases. This dual-structure approach enables cross-verification of installed base estimates against reagent consumption patterns.
Historical trendline analysis of replacement cycles and regulatory deadline clustering informed projection mechanics across the analysis window. Segmentation dimensions span product architecture, detection methodology, end-user setting, and geographic regulatory cluster. CAGRs were derived from instrument unit economics and service revenue attachment rates. Forecast inputs incorporate IVDR recertification deadline phasing and Indian laboratory network expansion trajectories.
Several conditions sit outside the modeled scope, including unannounced regulatory framework revisions, supply chain disruptions affecting German photodetector suppliers, and abrupt shifts in anticoagulation therapy protocols. Forecasts reflect base-case assumptions regarding IVDR implementation timelines and health system merger momentum. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Kidney Cancer Diagnostics Market
Diagnostics
Japan in-Vitro Diagnostics Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
Cervical Cancer Diagnostic Tests Market
Diagnostics
Europe Lung Cancer Diagnostics Market
Diagnostics
Cushing's Syndrome Diagnostics and Therapeutics Market
Diagnostics
Global Meningitis Diagnostic Testing Market
Diagnostics
Liver Function Tests Market
Diagnostics
Global Blood Culture Tests Market
Diagnostics
Europe Ovarian Cancer Diagnostics Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
GCC in-Vitro Diagnostics Market
Diagnostics
Europe in Vitro Diagnostics (IVD) Market