
 Global Yersiniosis Diagnostics and Treatment Market | 2026-2036
Global Yersiniosis Diagnostics and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Yersiniosis Diagnostics and Treatment Market Foresight
Capital-intensity divergence between automated molecular diagnostics platforms and conventional culture-based methods is redrawing competitive boundaries in yersiniosis detection. Thermo Fisher Scientific leverages its integrated supply chain for PCR assay components to sustain pricing power across clinical laboratory channels. Bio-Rad Laboratories differentiates through specialized enzyme immunoassay formats that anchor its position in food safety testing workflows.
Yersiniosis diagnostics and treatment encompasses laboratory and clinical methods for detecting Yersinia enterocolitica and Yersinia pseudotuberculosis through serological, molecular, or culture-based techniques, followed by antimicrobial or supportive therapeutic intervention; PCR assays amplify pathogen-specific DNA sequences with turnaround times under 24 hours, displacing slower culture confirmation in acute care settings. Diagnostic Kits command the largest product type share due to recurring consumable demand, while Molecular Diagnostics technology captures the fastest expansion as hospitals replace legacy microbial culture protocols with automated nucleic acid extraction systems. Public Health Agencies represent a concentrated end-user segment where epidemiological surveillance mandates create sustained procurement volumes for antibody tests and culture media.
FDA clearance pathways for in vitro diagnostic devices shape product development timelines and commercial access for US market entrants, while EMA's In Vitro Diagnostic Regulation enforces stricter clinical evidence standards across European Economic Area states. WHO guidelines on integrated foodborne disease surveillance influence national laboratory capacity investments in low- and middle-income settings. Stakeholders must monitor evolving multiplex panel approvals that combine yersiniosis detection with broader enteric pathogen screening.
Market Dynamics
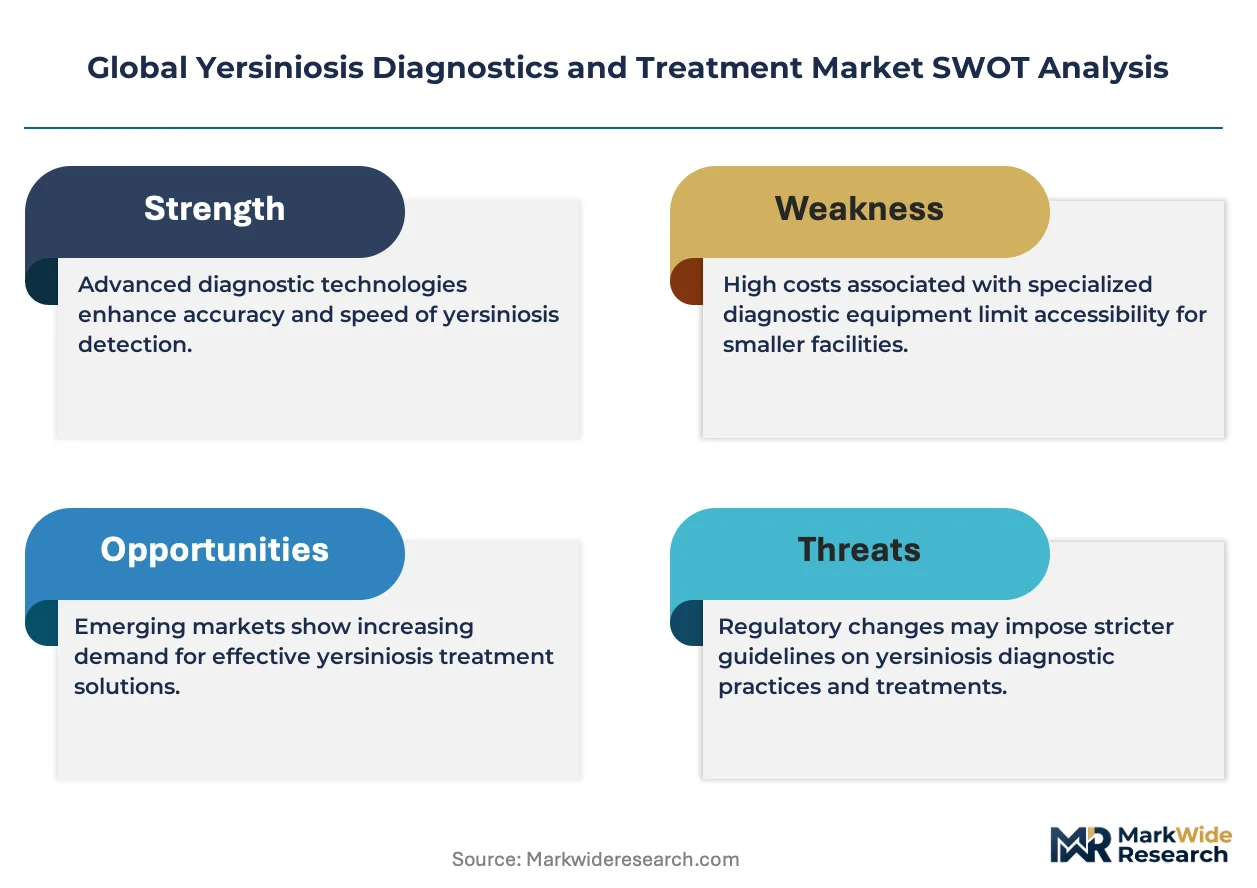
Automated nucleic acid extraction systems are compressing turnaround times for Yersinia detection below six hours, forcing clinical laboratories to retire batch-processed culture workflows and reallocate capital toward integrated molecular platforms.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated premarket notification reviews for multiplex enteric panels reduce time-to-commercialization for PCR assay developers targeting acute care settings.
- Food safety testing laboratories:Regulatory mandates for pathogen surveillance in ready-to-eat meat products sustain recurring demand for serological confirmation kits across industrial testing workflows.
- Whole-genome sequencing integration:Public health agencies deploy WGS for outbreak traceback, expanding procurement volumes for complementary molecular diagnostic consumables.
Market Restraints
- Reagent supply concentration:Taq polymerase and fluorescent probe manufacturing clusters in Germany and the United States create single-source vulnerability for assay producers.
- EMA IVDR clinical evidence requirements:Stricter performance validation standards for Class C in vitro diagnostic devices extend regulatory timelines and inflate development costs.
- Culture-based confirmation persistence:Antimicrobial susceptibility testing still requires viable isolates, preventing full displacement of slow conventional methods in therapeutic decision workflows.
Strategic Opportunities
- India's laboratory capacity expansion:FSSAI-mandated food testing infrastructure investments create entry points for automated extraction platform vendors in emerging surveillance markets.
- Point-of-care molecular miniaturization:Battery-operated PCR devices enable same-shift detection in rural clinics lacking centralized laboratory access.
- WHO Global Foodborne Infections Network:Capacity-building grants for national reference laboratories in low-income settings generate demand for standardized antibody test kits.
Industry Challenges
- Bioinformatics specialist scarcity:Interpretation of sequencing data for Yersinia subtyping requires trained personnel that clinical laboratories struggle to recruit and retain.
- Multiplex panel validation complexity:Demonstrating analytical specificity across cross-reactive enteric pathogens strains regulatory submission resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Yersiniosis Diagnostics and Treatment Market |
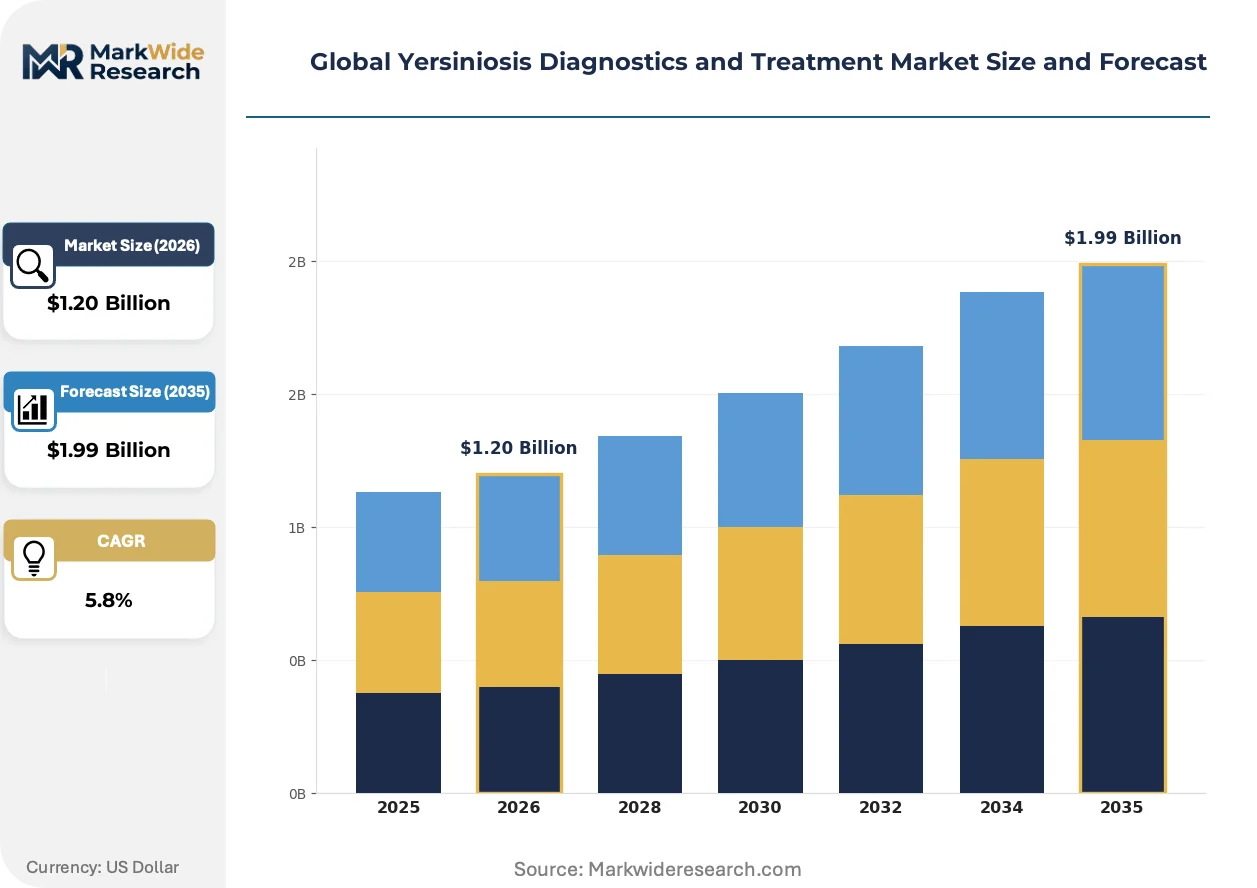
| Market Size in 2026 | $1.20 Billion |
| Market Size in 2035 | $1.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Therapeutic Agents, Antibody Tests, PCR Assays, Culture Media Application: Food Safety Testing, Clinical Diagnosis, Veterinary Diagnostics, Water Quality Analysis, Epidemiological Surveillance End User: Clinical Laboratories, Research Institutions, Hospitals, Veterinary Clinics, Public Health Agencies Technology: Enzyme Immunoassay, Molecular Diagnostics, Immunofluorescence, Microbial Culture, Biosensor Technology |
| Companies Covered | Laboratory Corporation of America Holdings, Bio-Rad Laboratories, Surmodics IVD, Pfizer, F. Hoffmann-La Roche Ltd, Mikrogen GmbH, Hologic, Thermo Fisher Scientific, CerTest Biotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Yersiniosis Diagnostics and Treatment Market Shifts & Advancements
Diagnostic modality convergence is collapsing the traditional separation between pathogen identification and antimicrobial resistance profiling, compressing the clinical decision window from days to hours.
CRISPR-based nucleic acid detection is decomposing the cost structure of reference laboratory confirmation. Hospital systems in Japan and South Korea deploy CRISPR-Cas12 assays for Y. enterocolitica screening alongside conventional PCR, enabling same-day result reporting that eliminates admission isolation precautions. This technology is decomposing the economic viability of send-out testing models that previously captured premium pricing for complex pathogen workups.
REACH restrictions on hazardous substances in diagnostic manufacturing are forcing reagent reformulation across European supply chains. ECHA substance-of-very-high-concern listings targeting specific buffer components compel manufacturers to validate alternative chemistries without compromising assay sensitivity. In vitro diagnostic producers with early REACH compliance certification capture preferential procurement status from EEA-based clinical laboratory networks.
Consolidated purchasing by integrated delivery networks is compressing vendor margins and service expectations. Large US health systems negotiate multi-year sole-source agreements for enteric pathogen panels, displacing the fragmented spot-buying patterns that previously sustained smaller assay specialists. This concentration is most visible in the Northeast and Midwest, where hospital merger activity has created super-regional laboratory entities with standardized testing menus.
Global Yersiniosis Diagnostics and Treatment Market Segmentation
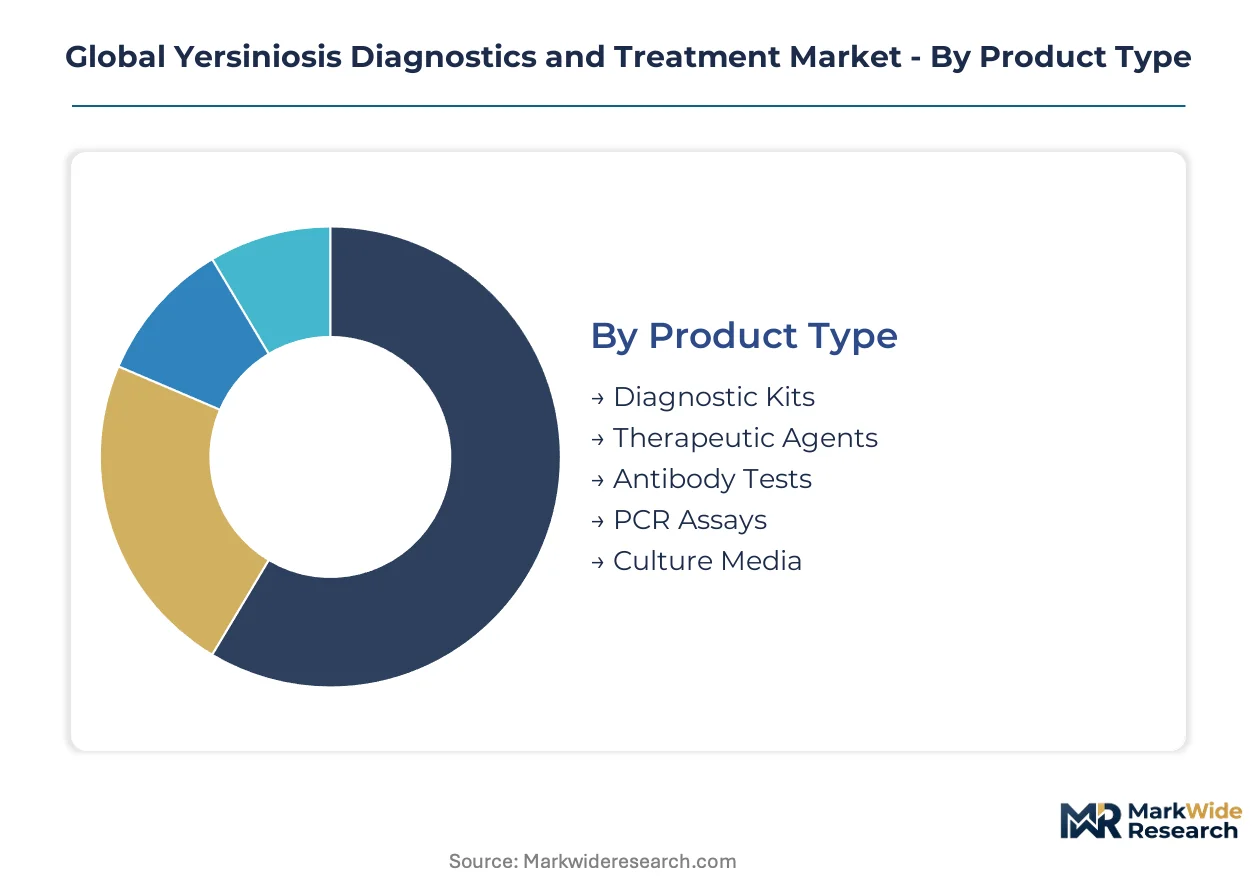
Segmentation in yersiniosis diagnostics reveals distinct procurement patterns across clinical, industrial, and public health channels. Product mix varies sharply between centralized reference laboratories requiring high-throughput molecular platforms and field-based veterinary operations dependent on rapid antibody tests. Channel-specific regulatory requirements further fragment vendor go-to-market strategies.
Product Type:
Channel distribution diverges between consumable-heavy clinical workflows and capital-intensive public health infrastructure. Diagnostic Kits and PCR Assays flow predominantly through hospital procurement networks, while Culture Media and Antibody Tests serve food safety and veterinary channels with distinct pricing structures.
- Diagnostic Kits:Enzyme immunoassay and lateral flow formats dominate hospital laboratory menus for routine enteric pathogen screening. Recurring consumable demand from high-volume clinical laboratories in the United States and Germany sustains manufacturer revenue stability despite single-digit price erosion.
- PCR Assays:Real-time nucleic acid amplification reagents with pathogen-specific primer-probe sets enable sub-6-hour turnaround times. Automated platform compatibility requirements in Japanese and South Korean hospital systems are accelerating displacement of legacy culture confirmation protocols.
- Therapeutic Agents:Fluoroquinolone and third-generation cephalosporin formulations for severe yersiniosis cases.
- Antibody Tests:Serological detection kits for epidemiological screening and convalescent-phase confirmation.
- Culture Media:Selective enrichment formulations for food safety and environmental monitoring applications.
By volume, Diagnostic Kits lead. By growth pace, PCR Assays are climbing the fastest.
Application:
Cost tier separation distinguishes premium molecular diagnostics in clinical settings from economy-grade serological methods in veterinary and environmental surveillance. Regulatory stringency varies by application, with food safety testing facing the most intensive third-party validation requirements.
- Clinical Diagnosis:Acute care settings prioritize rapid molecular detection to guide antimicrobial therapy initiation and isolation protocol decisions. Hospital systems in Japan deploy same-day PCR turnaround to eliminate unnecessary patient cohorting.
- Food Safety Testing:Regulatory-mandated pathogen surveillance in ready-to-eat meat products drives recurring demand for ISO-certified detection methods. Industrial laboratories in Germany face EFSA-validated performance standards for Yersinia enumeration in pork products.
- Epidemiological Surveillance:National reference laboratory networks for outbreak detection and traceback.
- Veterinary Diagnostics:Farm-level screening for Yersinia in livestock and companion animal populations.
- Water Quality Analysis:Environmental monitoring for Yersinia in recreational and potable water sources.
Food Safety Testing captures the largest procurement volumes. Clinical Diagnosis shows the steepest expansion trajectory as hospitals replace culture-based workflows.
End User:
Customer type determines contract structure, with integrated health systems negotiating multi-year sole-source agreements while public health agencies operate on grant-funded procurement cycles. Margin profiles differ sharply between high-volume clinical laboratory contracts and fragmented veterinary clinic purchases.
- Clinical Laboratories:High-throughput reference facilities and hospital-based labs process thousands of enteric panels annually. Consolidated purchasing by US integrated delivery networks in the Northeast and Midwest compresses vendor margins while demanding extended service commitments.
- Public Health Agencies:National and subnational epidemiological surveillance programs maintain strategic stockpiles for outbreak response. WHO Global Foodborne Infections Network capacity-building grants generate demand for standardized antibody test kits in low-income reference laboratories.
- Hospitals:Acute care facilities with on-site microbiology capabilities.
- Research Institutions:Academic and government laboratories conducting pathogenesis and virulence studies.
- Veterinary Clinics:Private and government veterinary diagnostic facilities.
Clinical Laboratories represent the dominant revenue pool. Public Health Agencies are gaining share fastest through pandemic-preparedness infrastructure investments.
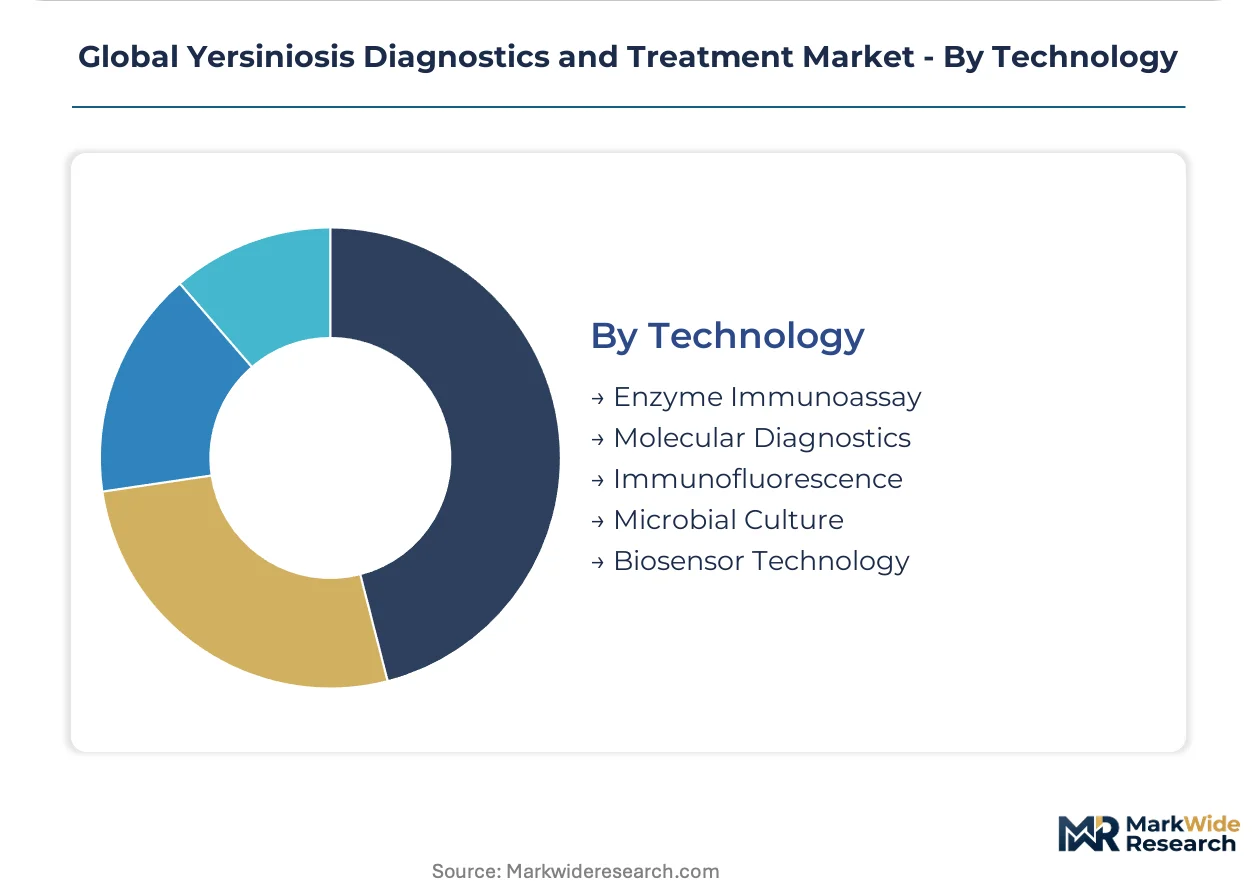
Technology:
Maturity gradients separate established microbial culture methods from emerging biosensor platforms, with molecular diagnostics occupying the commercial sweet spot of validated performance and automatable throughput. Supply concentration in reagent manufacturing creates vendor lock-in effects across technology categories.
- Molecular Diagnostics:Nucleic acid extraction, amplification, and detection systems encompassing real-time PCR and emerging CRISPR-based formats. Automated platform adoption in South Korean hospital laboratories is compressing turnaround times below 4 hours for enteric pathogen panels.
- Enzyme Immunoassay:Antigen and antibody detection using horseradish peroxidase or alkaline phosphatase conjugates. Food safety testing workflows in German industrial laboratories rely on EIA formats for cost-effective batch screening of meat product samples.
- Microbial Culture:Conventional isolation and biochemical identification methods.
- Immunofluorescence:Direct and indirect fluorescent antibody techniques for reference confirmation.
- Biosensor Technology:Electrochemical and optical transduction platforms for point-of-care deployment.
Microbial Culture retains the largest installed base. Molecular Diagnostics is expanding most quickly as capital investment shifts toward nucleic acid automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in yersiniosis diagnostics concentrates in German and Japanese procurement networks, while US hospital systems extract volume discounts through consolidated purchasing that compresses margins for assay vendors.
United States
FDA 510(k) pathway streamlining accelerates premarket notification reviews for multiplex enteric panels. Integrated delivery networks in the Northeast and Midwest negotiate multi-year sole-source agreements for enteric pathogen panels. Boston and Minneapolis anchor super-regional laboratory entities with standardized testing menus.
Germany
EMA IVDR clinical evidence requirements enforce stricter performance validation standards for Class C in vitro diagnostic devices. REACH restrictions on hazardous substances force reagent reformulation across European supply chains. Berlin and Munich host industrial laboratories facing EFSA-validated performance standards for Yersinia enumeration in pork products.
Japan
PMDA regulatory frameworks shape molecular diagnostic platform approvals with emphasis on automated throughput validation. Hospital systems deploy same-day PCR turnaround to eliminate unnecessary patient cohorting. Tokyo and Osaka metropolitan laboratories lead adoption of battery-operated PCR devices for rural clinic networks.
India
FSSAI-mandated food testing infrastructure investments create entry points for automated extraction platform vendors. WHO Global Foodborne Infections Network capacity-building grants generate demand for standardized antibody test kits. Mumbai and Delhi national reference laboratories expand epidemiological surveillance procurement.
South Korea
MFDS regulatory alignment with international nucleic acid testing standards accelerates automated platform adoption. Hospital laboratories compress turnaround times below 4 hours for enteric pathogen panels. Seoul Capital Area health systems pioneer CRISPR-Cas12 assay deployment alongside conventional PCR workflows.
Global Yersiniosis Diagnostics and Treatment Market Competitive Landscape
Concentration sits with diversified life science conglomerates controlling integrated supply chains for PCR assay components. Thermo Fisher Scientific leverages captive manufacturing of Taq polymerase and fluorescent probes to sustain pricing power across clinical laboratory channels. Three strategic archetypes dominate: vertically integrated platform vendors, specialized enzyme immunoassay producers, and reference laboratory networks with in-house assay development. Competitive moves center on multiplex panel regulatory submissions and sole-source contract capture through multi-year service commitments.
Among US-based diversified diagnostics conglomerates, Laboratory Corporation of America Holdings exemplifies the reference laboratory network archetype with integrated assay development and clinical service delivery. Bio-Rad Laboratories occupies a position within the specialized immunoassay tier, while Thermo Fisher Scientific anchors the vertically integrated platform segment. Mikrogen GmbH represents the European molecular specialist archetype. Pfizer and F. Hoffmann-La Roche Ltd sit within the pharmaceutical-therapeutic vector of the competitive map.
| Leading Market Players |
|---|
| Laboratory Corporation of America Holdings |
| Bio-Rad Laboratories |
| Surmodics IVD |
| Pfizer |
| F. Hoffmann-La Roche Ltd |
| Mikrogen GmbH |
| Hologic |
| Thermo Fisher Scientific |
| CerTest Biotec |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day reagent inventory cycles in clinical laboratory networks concentrate pricing power with Taq polymerase manufacturers in Germany and the United States, while automated platform vendors extract premium positioning through sole-source consumable lock-in.
Pricing Analysis
The customization-premium spread separates configured-to-order PCR assay bundles from standard diagnostic kits, with three-tier pricing structure across premium, standard, and economy levels anchored by FDA clearance tier and automation compatibility. Price differentiation hinges on ISO 15189 certification status and volume scale, with consolidated purchasing by US integrated delivery networks intensifying cost compression in the standard tier. Academic medical centers show lowest price sensitivity due to grant-funded procurement, while veterinary clinics face acute budget constraints. Pricing pressure stems from REACH-mandated reagent reformulation costs passing through European supply chains.
Supply Chain Analysis
Inventory buffers for fluorescent probes and specialized enzymes rarely exceed forty-five days, exposing assay producers to disruption risk from concentrated manufacturing in Germany, the United States, and Japan. Raw material dependencies center on Taq polymerase, FAM-labeled probes, and magnetic bead formulations, with single-source vulnerability for thermostable polymerase strains. Tariff exposure on Chinese-sourced buffer components compounds logistics chokepoint risk at Rotterdam and Long Beach ports. Distribution runs through authorized distributor networks serving hospital procurement committees and public health agency tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market cycles with foodborne illness surveillance funding rounds, with pandemic-preparedness infrastructure investments currently lifting procurement volumes across national reference laboratory networks.
For Market Incumbents: Consolidate position through backward integration into probe chemistries and captive Taq polymerase production, insulating margin structures from reagent supply shocks. Lock in multi-year sole-source agreements with Northeast and Midwest integrated delivery networks before competitive multiplex panel approvals fragment purchasing. Prioritize EMA IVDR Class C certification investment to capture preferential procurement status across European Economic Area clinical laboratory networks. For New Entrants and Emerging Players: Lead with point-of-care molecular miniaturization targeting rural clinic networks in India and Southeast Asia, where centralized laboratory access gaps persist. Battery-operated PCR devices for same-shift yersiniosis detection represent the most penetrable white-space, with WHO Global Foodborne Infections Network capacity-building grants providing non-dilutive market entry capital. Partner with established IVD distributors for regulatory navigation and hospital system credentialing. For Investors and Strategic Acquirers: Long-term, this sits as a defensive infrastructure play because foodborne disease surveillance mandates create non-discretionary procurement demand insulated from reimbursement volatility. Target acquisition candidates with validated multiplex enteric panels and existing FDA 510(k) clearances, where regulatory sunk costs create moats. Watch CRISPR-based assay cost curves as the inflection signal—same-day result reporting at reference-laboratory quality collapses send-out testing economics and redirects capital toward integrated platform vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Panel Regulatory Submission | FDA 510(k) pathway streamlining accelerates premarket notification reviews for enteric pathogen combinations. |
| Automated Platform Integration | South Korean hospital laboratories compress turnaround times below four hours through nucleic acid extraction automation. |
| REACH Compliance Certification | ECHA substance-of-very-high-concern listings force reagent reformulation capturing preferential EEA procurement status. |
| Point-of-Care Miniaturization | Battery-operated PCR devices enable same-shift detection in rural Indian clinics lacking centralized laboratory infrastructure. |
| Whole-Genome Sequencing Partnership | Public health agency WGS deployment for outbreak traceback expands complementary molecular diagnostic consumable volumes. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital laboratory directors, clinical microbiologists, food safety testing managers, public health epidemiologists, and IVD regulatory affairs specialists. Secondary validation drew from FDA 510(k) premarket notification databases, EMA IVDR technical documentation summaries, FSSAI food testing infrastructure reports, and WHO Global Foodborne Infections Network capacity assessments. Bottom-up procurement volume estimates triangulated against top-down national surveillance spending allocations.
Across the analysis window, the forecasting framework modeled product type segmentation, technology modality adoption curves, end-user procurement patterns, and geographic regulatory cluster dynamics. CAGRs were derived from segment-level volume trajectories weighted by pricing tier evolution and platform replacement cycles. Forecast inputs incorporated automated nucleic acid extraction penetration rates and multiplex panel approval timelines.
The analysis sits within stated boundaries; outcomes outside sustained pandemic-preparedness funding levels or significant regulatory pathway disruption would require recalibration. Forecasts reflect documented assumptions regarding surveillance infrastructure investment continuity and molecular diagnostic platform replacement cadence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Asia-Pacific Ovarian Cancer Diagnostics Market
Diagnostics
DNA Probes - Based Diagnostics Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Global Serological Testing Market
Diagnostics
Precision Diagnostics Market
Diagnostics
Fructosamine Reagents Market
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
Middle East and Africa Ovarian Cancer Diagnostics Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Cellular Health Screening Market
Diagnostics
North America Breast Cancer Screening Tests Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
Fungal Antigens Market
Diagnostics
Veterinary Diagnostics Market
Diagnostics
Home Diagnostics Market
Diagnostics
Artificial Intelligence in IVD Market