
 US Pharmaceutical Warehousing Market | 2026-2036
US Pharmaceutical Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
US Pharmaceutical Warehousing Market Insights
Texas is fragmenting pharmaceutical warehousing capacity as Gulf Coast distribution hubs multiply to serve expanding biomanufacturing corridors. United Parcel Service Inc. leverages its healthcare campus network to anchor temperature-validated last-mile delivery. FedEx Corp. sustains dominance in time-critical pharmaceutical shipments through its Memphis superhub infrastructure. DHL Supply Chain competes by specializing in clinical trial logistics and direct-to-patient distribution channels.
US pharmaceutical warehousing encompasses the receipt, storage, handling, and distribution of drug products under validated temperature and humidity conditions, typically maintaining 15°C to 25°C for controlled room temperature products and 2°C to 8°C for cold chain items, with primary purpose of preserving product integrity from manufacturer release through wholesale and retail dispensing. Temperature-controlled storage leads service type revenue pools due to biologic drug proliferation, while cold chain logistics represents the fastest-expanding segment driven by mRNA and cell therapy distribution requirements. Warehouse management systems anchor technology investment as operators integrate automated storage with real-time inventory visibility to satisfy DSCSA compliance deadlines.
FDA serialization mandates under DSCSA, EPA refrigerant management rules affecting cold chain equipment, and OSHA workplace safety standards governing hazardous drug handling collectively shape facility design, technology procurement, and operational compliance costs for US pharmaceutical warehouse operators. Stakeholders must monitor evolving state-level pharmaceutical distribution licensing requirements and prepare for potential federal cold chain integrity regulations that would mandate continuous temperature monitoring data retention across all distribution nodes.
Market Dynamics
FDA DSCSA serialization deadlines are compressing technology procurement cycles as warehouse operators race to deploy track-and-trace infrastructure before enforcement phases eliminate grandfathered inventory handling. This regulatory pressure cascade is forcing simultaneous capital deployment across validation, automation, and data retention systems.
Growth Catalysts
- Biologics Cold Chain Expansion:Cell therapy and mRNA manufacturing corridors in Texas and North Carolina are pulling validated 2°C to 8°C capacity into new construction. Hospital systems and infusion centers anchor this demand as specialty distribution networks deepen.
- DSCSA Compliance Infrastructure:The FDA's November 2024 enhanced drug distribution security requirements mandate unit-level traceability. Warehouse operators must install serialization-enabled warehouse management systems to maintain wholesale distribution licensure.
- Port-Anchored Logistics Clusters:The New Jersey-Pennsylvania corridor concentrates pharmaceutical imports through Port Newark and Port of Philadelphia. This geographic density supports shared cold storage infrastructure and intermodal connectivity.
Market Restraints
- Refrigerant Regulatory Cost Pressure:EPA rules on hydrofluorocarbon phase-down are forcing cold chain equipment replacement. Retrofitting existing 2°C to 8°C chambers with compliant refrigeration systems strains facility capital budgets.
- Specialized Talent Scarcity:Qualified validation engineers and temperature-mapping specialists command premium compensation. The shallow labor pool for pharmaceutical Good Distribution Practice compliance limits facility expansion velocity.
- Real Estate Concentration Risk:Temperature-controlled warehouse construction concentrates in high-land-cost Northeast and California markets. Limited suitable sites near biomanufacturing clusters inflate per-square-foot development costs.
Strategic Opportunities
- Direct-to-Patient Distribution Channels:Specialty pharmacy and home infusion models bypass traditional wholesale tiers. Clinical trial logistics providers are repurposing this infrastructure for commercial cell therapy delivery.
- Automated Storage Convergence:Robotic shuttle systems integrated with real-time environmental monitoring collapse labor intensity in high-SKU facilities. Early adopters in the Midwest are achieving throughput density unavailable in conventional rack configurations.
- Gulf Coast Biomanufacturing Corridors:Texas state tax incentives for life sciences manufacturing are pulling warehouse development southward. Greenfield campuses near Houston and Dallas-Fort Worth offer modern cold chain specifications absent in legacy Northeast facilities.
Industry Challenges
- Legacy System Integration Complexity:Warehouse management system upgrades must interface with decade-old enterprise resource planning installations. Data architecture mismatches between serialization platforms and inventory databases delay DSCSA compliance certification.
- Continuous Temperature Monitoring Certification:Installing validated wireless sensor networks across multi-temperature zones requires extensive IQ/OQ/PQ documentation. FDA inspectors are intensifying scrutiny of temperature excursion response protocols during routine audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pharmaceutical Warehousing Market |
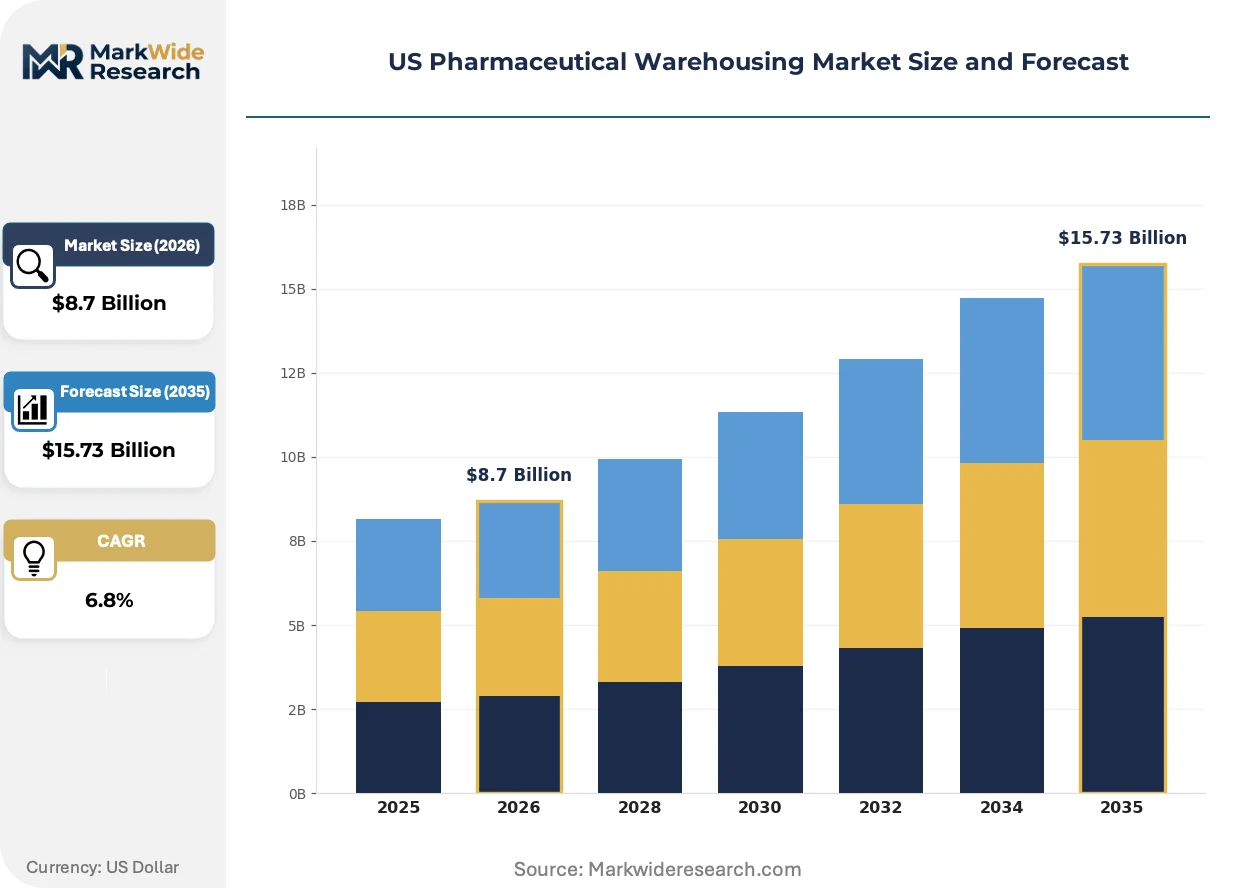
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Temperature-Controlled Storage, Cold Chain Logistics, Distribution Services, Inventory Management Technology: Warehouse Management Systems, RFID Tracking, Automated Storage, Blockchain Solutions End User: Pharmaceutical Manufacturers, Retail Pharmacies, Healthcare Providers, Online Pharmacies Packaging Type: Vials, Ampoules, Blisters, Pouches |
| Companies Covered | United Parcel Service Inc., FedEx Corp., DHL Supply Chain, Lineage Logistics, Americold Logistics, United States Cold Storage, CEVA Logistics, Owens and Minor Inc., C H Robinson Worldwide Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pharmaceutical Warehousing Market Trends and Innovations
Technology deployment in pharmaceutical warehousing is collapsing traditional validation timelines as automated systems compress the gap between installation and regulatory approval. Three developments are restructuring competitive requirements.
Autonomous mobile robots equipped with temperature-controlled payload carriers are collapsing the labor cost structure of high-throughput distribution centers. Regional wholesalers serving hospital systems in the Southeast are deploying these systems ahead of national competitors. The technology is collapsing facility break-even thresholds for mid-volume operators previously excluded from automation economics.
FDA enforcement discretion letters on DSCSA interoperability are hardening into binding guidance. The agency's 2024 policy clarification on electronic data exchange standards is forcing warehouse operators to abandon paper-based exception handling. Cold chain facilities in California and Florida are prioritizing cloud-native track-and-trace platforms to satisfy anticipated inspection intensity.
Consolidated procurement by integrated delivery networks is compressing vendor qualification cycles. Hospital systems in the Northeast are awarding multi-year warehousing contracts contingent on real-time inventory visibility API access. This behavior is most visible among academic medical centers consolidating specialty pharmacy operations under single distribution agreements.
US Pharmaceutical Warehousing Market Segmentation
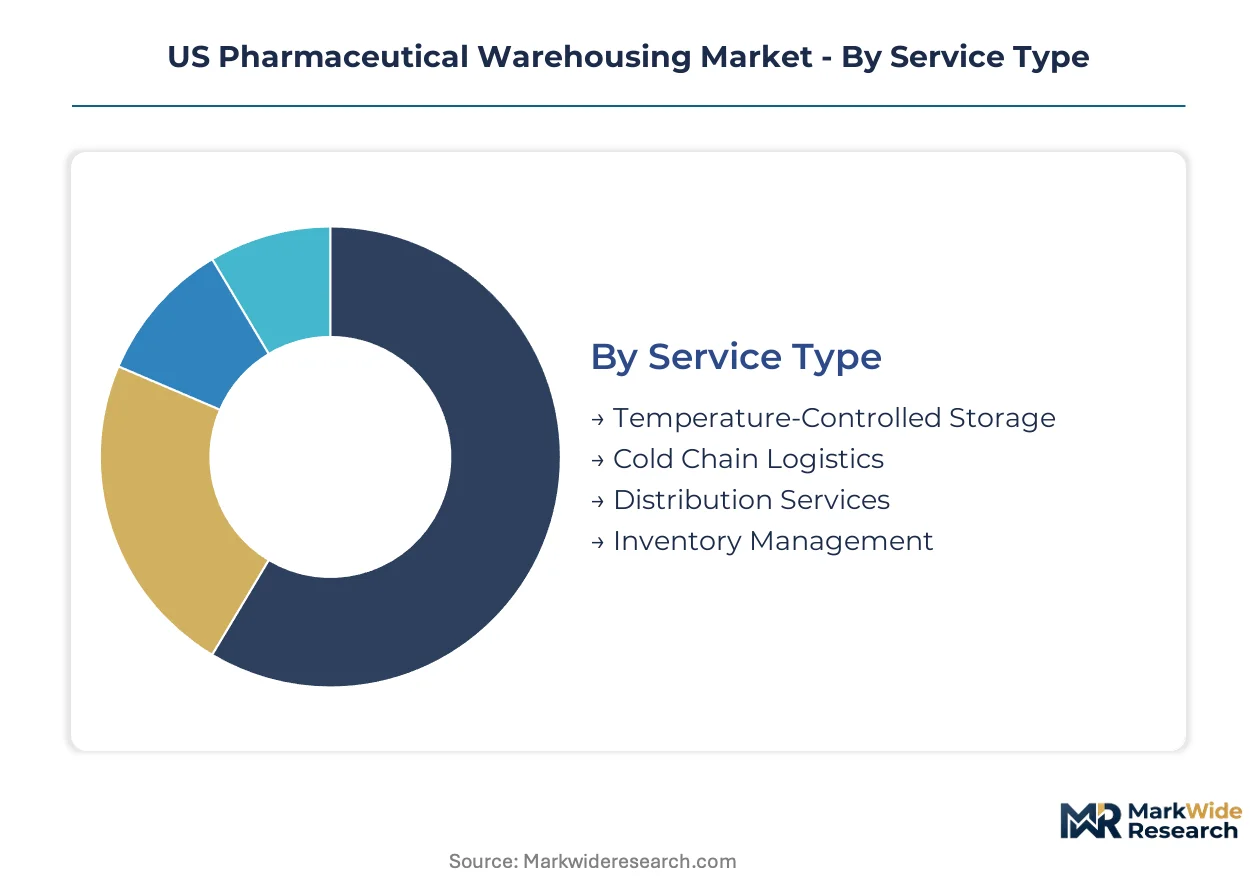
Pharmaceutical warehousing operators configure service portfolios around temperature sensitivity, regulatory validation tiers, and end-user distribution velocity. Segment boundaries shift as biologics proliferation and DSCSA compliance deadlines force infrastructure specialization across storage modalities and technology stacks.
Service Type:
Service configurations span ambient handling through ultra-cold preservation, with facility capital allocation tracking drug product thermal requirements.
- Temperature-Controlled Storage:Maintains 15°C to 25°C controlled room temperature conditions for small-molecule tablets and capsules. Hospital systems in the Northeast corridor anchor demand as specialty distribution networks consolidate under integrated delivery network procurement.
- Cold Chain Logistics:Validated 2°C to 8°C distribution for biologics, vaccines, and cell therapies. Texas and North Carolina biomanufacturing corridors are pulling capacity into greenfield construction as mRNA manufacturing scales.
- Distribution Services:Cross-dock and fulfillment operations linking manufacturers to wholesale and retail channels. FDA DSCSA serialization mandates are forcing unit-level traceability integration.
- Inventory Management:Real-time stock visibility and demand forecasting services. Online pharmacies and specialty pharmacy operators are contracting for API-accessible inventory dashboards.
The dominant share belongs to Temperature-Controlled Storage, while Cold Chain Logistics is expanding most quickly as biologics displace small-molecule volume.
Technology:
Capital deployment concentrates on validation-heavy infrastructure satisfying FDA data integrity requirements and EPA refrigerant phase-down timelines.
- Warehouse Management Systems:Serialization-enabled platforms integrating DSCSA track-and-trace with environmental monitoring. Warehouse operators are racing deployment cycles ahead of enforcement phase deadlines.
- Automated Storage:Robotic shuttle systems and autonomous mobile robots collapsing labor intensity in high-SKU facilities. Midwest operators are achieving throughput density unavailable in conventional rack configurations.
- RFID Tracking:Item-level identification for inventory accuracy and counterfeit detection. Retail pharmacy chains are mandating RFID compliance in vendor qualification protocols.
- Blockchain Solutions:Distributed ledger architectures for supply chain transparency and provenance verification. Clinical trial logistics providers are piloting patient-direct distribution on blockchain rails.
Warehouse Management Systems command the largest investment pools, though Automated Storage is gaining share fastest as labor scarcity intensifies.
End User:
Customer segments diverge on validation requirements, order frequency, and temperature sensitivity, with procurement consolidation reshaping vendor selection criteria.
- Pharmaceutical Manufacturers:Require GMP-adjacent storage and release testing capabilities. New Jersey-Pennsylvania cluster concentration supports just-in-time API and finished goods staging.
- Healthcare Providers:Hospital systems and infusion centers demand validated cold chain for biologics administration. Academic medical centers are consolidating specialty pharmacy operations under single distribution agreements.
- Retail Pharmacies:High-velocity replenishment of controlled room temperature products. Chain consolidation is compressing vendor qualification cycles to multi-year contracts.
- Online Pharmacies:Direct-to-patient fulfillment requiring temperature-validated last-mile handoff. Home infusion models are repurposing clinical trial logistics infrastructure.
Pharmaceutical Manufacturers retain the deepest contractual relationships, while Healthcare Providers are driving the steepest expansion trajectory as hospital-system specialty pharmacy integration accelerates.
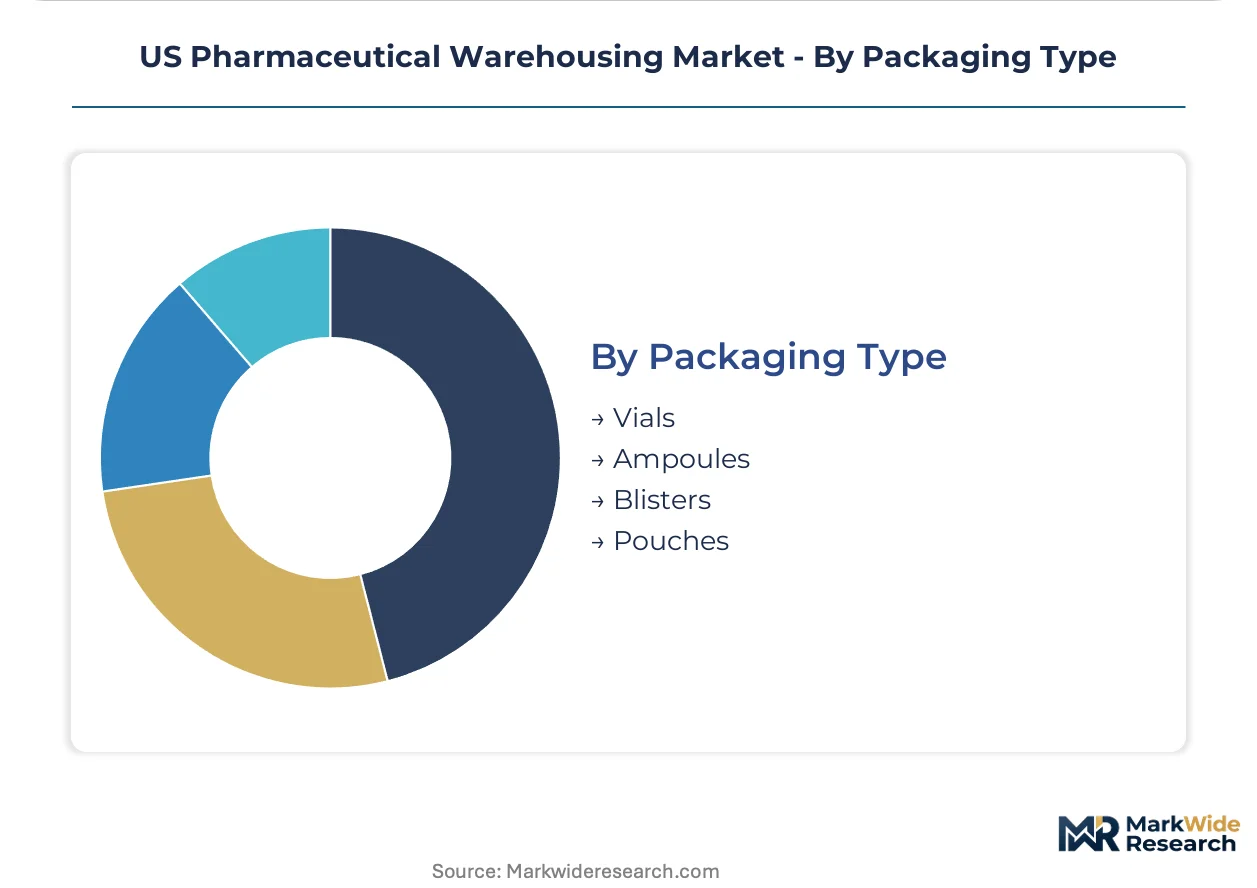
Packaging Type:
Primary packaging formats dictate handling protocols, storage density, and environmental monitoring granularity across warehouse zones.
- Vials:Glass or polymer containers for injectable biologics and vaccines. Cold chain validation requirements concentrate demand in 2°C to 8°C chambers with continuous temperature monitoring.
- Blisters:Unit-dose packaging for oral solid dosage forms. Controlled room temperature storage dominates with DSCSA serialization applied at the unit level.
- Ampoules:Single-use glass containers for parenteral solutions. Fragility constraints limit automated handling adoption in legacy facilities.
- Pouches:Flexible packaging for powders, granules, and unit-dose solids. E-commerce pharmacy fulfillment favors pouch configurations for dimensional efficiency.
Vials command premium handling infrastructure investment, while Blisters scale across the broadest facility footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical warehousing capacity clusters along three distinct corridors shaped by port access, biomanufacturing investment, and hospital system density. The Northeast corridor retains import dominance while Texas and North Carolina emerge as cold chain growth poles.
Northeast Corridor
The New Jersey-Pennsylvania logistics cluster anchors import volume through Port Newark and Port of Philadelphia. FDA DSCSA enforcement timelines compress technology deployment cycles for warehouse operators serving this corridor. Shared cold storage infrastructure and intermodal rail connectivity support just-in-time distribution to hospital systems concentrated in Greater New York and Philadelphia.
Texas Gulf Coast
Biomanufacturing expansion in Houston and Dallas-Fort Worth pulls validated 2°C to 8°C capacity into greenfield construction. State tax incentives for life sciences manufacturing accelerate warehouse development timelines. Modern campus specifications exceed legacy Northeast facilities in automation density and continuous temperature monitoring coverage.
North Carolina Research Triangle
Cell therapy and mRNA manufacturing corridors in Durham and Raleigh generate specialized cold chain demand. Academic medical centers and contract manufacturers co-locate to minimize temperature excursion risk in biologics transfer. Warehouse operators compete on GMP-adjacent staging capabilities and rapid release testing integration.
California
Los Angeles and San Francisco Bay Area facilities serve Pacific Rim import flows and domestic biotech manufacturing. EPA refrigerant phase-down rules force accelerated equipment replacement in aging cold chain infrastructure. Cloud-native track-and-trace platforms dominate technology procurement ahead of anticipated FDA inspection intensity.
Midwest Distribution Hubs
Chicago and Indianapolis anchor national distribution networks with lower land costs than coastal markets. Robotic shuttle systems achieve throughput density unavailable in conventional rack configurations. Regional wholesalers serving hospital systems deploy automation ahead of national competitors to collapse break-even thresholds.
US Pharmaceutical Warehousing Market Competitive Landscape
Integrated logistics networks and specialized cold chain operators split the market along service complexity lines. Parcel carriers with healthcare campuses compete against dedicated pharmaceutical 3PLs on temperature-validated last-mile capabilities. Three archetypes dominate: global express networks with healthcare verticals, dedicated pharmaceutical 3PLs with GMP expertise, and food-cold-chain specialists repurposing infrastructure for pharma. Competitive moves concentrate on automated storage deployment and multi-year hospital system contract consolidation.
Among integrated logistics networks, United Parcel Service Inc., FedEx Corp., and DHL Supply Chain occupy positions defined by hub infrastructure and healthcare campus density. These carriers exemplify the scale-driven archetype, leveraging superhub networks for time-critical pharmaceutical shipments. Specialized cold chain operators including Lineage Logistics and Americold Logistics represent the infrastructure-heavy tier, with temperature-validated warehouse networks serving biologics manufacturers. The competitive dynamic hinges on DSCSA compliance certification speed and real-time inventory visibility API capabilities demanded by consolidated hospital procurement.
| Leading Market Players |
|---|
| United Parcel Service Inc. |
| FedEx Corp. |
| DHL Supply Chain |
| Lineage Logistics |
| Americold Logistics |
| United States Cold Storage |
| CEVA Logistics |
| Owens and Minor Inc. |
| C H Robinson Worldwide Inc. |
| Others |
Pricing and Supply Chain Analysis
Refrigerant equipment manufacturers in China and Germany anchor cold chain infrastructure costs, concentrating margin capture upstream while US warehouse operators absorb EPA-mandated retrofit cycles downstream. This supplier concentration creates pricing asymmetry where specialized 2°C to 8°C chamber costs transmit directly to facility development budgets without downstream negotiation leverage.
Pricing Analysis
FDA DSCSA serialization mandates dictate the pricing tier structure across warehouse management system procurement, separating GMP-validated platform providers from commodity software vendors. Three-tier pricing stratifies across enterprise-grade serialization suites, mid-market compliance modules, and basic inventory tracking systems. Cost compression in mid-market tiers intensifies as regional wholesalers consolidate procurement under integrated delivery network contracts. Hospital systems exhibit lowest price sensitivity due to patient safety liability exposure, while independent retail pharmacies face acute margin pressure from chain consolidation.
Supply Chain Analysis
Upgraded refrigeration compressors and aluminum coil stock feed from concentrated Chinese and German manufacturing bases, tethering US cold chain construction timelines to trans-Pacific shipping windows. Warehouse management system software draws from Indian development centers and US West Coast cloud infrastructure. Single-source vulnerability concentrates in specialized validation engineering talent pools. Distribution runs through hub-and-spoke networks anchored by Memphis, Louisville, and Newark superhub facilities serving last-mile pharmaceutical delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
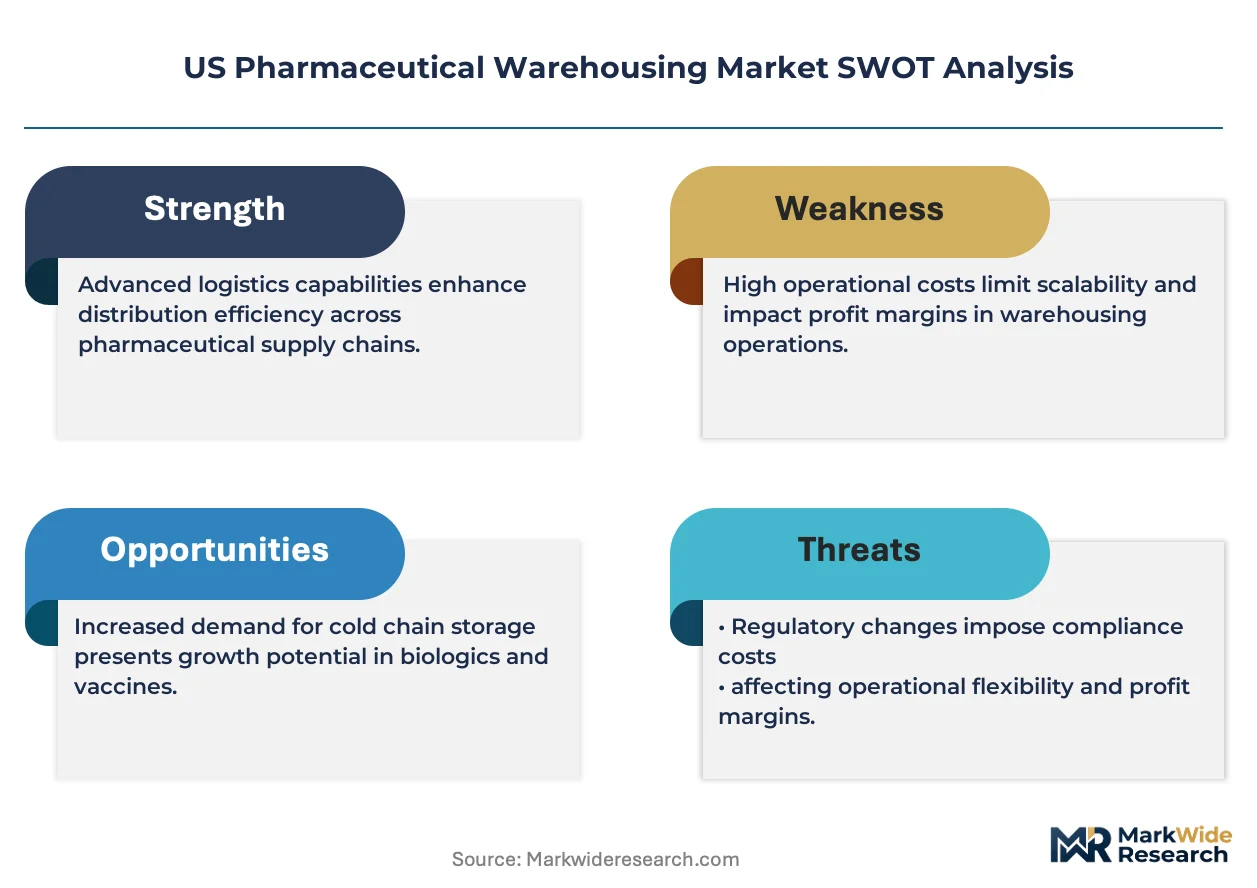
US pharmaceutical warehousing is approaching a platform-economics inflection as DSCSA interoperability standards harden into binding data-exchange protocols, forcing warehouse operators into API-centric ecosystem positioning rather than standalone facility competition.
For Market Incumbents: Harden serialization-enabled warehouse management system deployment ahead of FDA enforcement phase completion, prioritizing cloud-native architectures over on-premise legacy upgrades. Consolidate temperature-mapping specialist talent through acquisition or exclusive contracting to defend against Gulf Coast greenfield competitors. Vertical integration into clinical trial logistics software creates defensive moats against parcel carrier healthcare campus expansion.
For New Entrants and Emerging Players: Texas Gulf Coast biomanufacturing corridors offer the most penetrable geography, with state tax incentives compressing facility development timelines against Northeast land-cost barriers. Target cell therapy direct-to-patient distribution as the highest-velocity entry segment, repurposing existing food-cold-chain infrastructure through rapid GMP-adjacent certification. Lead with automated storage robotics as differentiation against legacy rack configurations in Midwest distribution hubs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pharmaceutical 3PLs holding FDA validation certificates but limited automation density, presenting buy-and-build consolidation platforms. Five-to-ten-year viability hinges on DSCSA compliance certification speed rather than geographic footprint scale. Watch FDA inspection intensity in California and Florida as the signal indicating enforcement phase acceleration and valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| DSCSA Compliance Infrastructure Deployment | Serialization-enabled warehouse management systems anchor wholesale distribution licensure retention under FDA enforcement timelines. |
| Automated Storage Robotics Integration | Robotic shuttle systems collapse labor intensity while achieving throughput density unavailable in conventional pharmaceutical rack configurations. |
| Gulf Coast Greenfield Campus Development | Texas state tax incentives accelerate validated cold chain construction serving Houston and Dallas-Fort Worth biomanufacturing corridors. |
| Direct-to-Patient Distribution Channel Buildout | Specialty pharmacy and home infusion models bypass traditional wholesale tiers using repurposed clinical trial logistics infrastructure. |
| Continuous Temperature Monitoring Certification | Validated wireless sensor networks across multi-temperature zones satisfy intensifying FDA scrutiny of excursion response protocols. |
Research Methodology
The analysis maps temperature-controlled storage, cold chain logistics, distribution services, and inventory management segments, each validated through warehouse operations directors, regulatory compliance officers, hospital procurement managers, and pharmaceutical manufacturer supply chain leads. Primary interview findings triangulate against FDA DSCSA guidance documents, EPA refrigerant phase-down rulemakings, state pharmaceutical distribution licensing databases, and SEC 10-K filings from publicly traded logistics operators. Bottom-up facility capacity counts and top-down pharmaceutical flow estimates converge through iterative stakeholder cross-checking.
Assumptions hold FDA enforcement discretion letters hardening into binding guidance, EPA refrigerant regulations maintaining current phase-down schedules, and biomanufacturing investment continuing across Texas and North Carolina corridors. Segmentation models incorporate service type, technology stack, end-user category, and packaging format dimensions. CAGRs derive from facility construction pipeline analysis, temperature-validated square footage absorption rates, and drug product thermal sensitivity shifts in manufacturer pipelines. Input assumptions include DSCSA compliance deadline adherence rates and cold chain equipment replacement cycles.
The forecast holds incumbent behavior within observed patterns; aggressive automation deployment by Midwest regional wholesalers or accelerated FDA enforcement would shift outcomes materially. Cross-checking against Port of Philadelphia and Port Newark import volume data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
Global Dementia Drugs Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Ceftriaxone Sodium (API) Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Microparticle Injectables Market
Pharmaceuticals
Cefdinir API Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
Europe Contraceptives Market
Pharmaceuticals
Cardiometabolic Drugs Market
Pharmaceuticals
Pharmaceutical Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market