
 Reactive Arthritis Treatment Market | 2026-2036
Reactive Arthritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Reactive Arthritis Treatment Market Analytics
A capital-intensity divergence between large-cap biologic manufacturers and mid-size specialty firms is bifurcating competitive dynamics in reactive arthritis therapeutics. Pfizer sustains broad manufacturing scale across small-molecule and biologic platforms, enabling cost-efficient supply of established DMARD formulations. AbbVie differentiates through deep immunology specialization, leveraging decades of rheumatology pipeline investment to anchor prescriber loyalty in seronegative spondyloarthropathies. Velcura Therapeutics competes as a development-stage entity, navigating early-stage clinical validation with targeted mechanism approaches.
Reactive arthritis treatment encompasses pharmacological management of post-infectious autoimmune joint inflammation, typically involving combination regimens that modulate cytokine signaling and suppress synovial inflammatory cascades. The primary therapeutic objective centers on achieving sustained remission of peripheral arthritis, enthesitis, and extra-articular manifestations while preventing progressive joint damage. Injectable biologics command the dominant margin pool within delivery mode segments, reflecting manufacturing complexity and cold-chain logistics requirements that create natural barriers to commoditization. Oral NSAIDs retain the largest prescription volume across product type categories, though generic saturation constrains pricing power for originator brands. DMARDs represent the fastest-expanding category, driven by rheumatology's shift toward early immunomodulation in post-infectious arthritis protocols.
The FDA governs biologic licensing and biosimilar interchangeability standards, while the EMA's MDR framework shapes device-drug combination product requirements for auto-injector delivery systems. These regulatory structures directly determine market access timelines, post-market surveillance obligations, and manufacturing quality benchmarks that influence competitive positioning. Reimbursement authorities in Germany through the G-BA and France via the HAS increasingly condition biologic access on demonstrated non-response to conventional DMARD therapy, tightening step-therapy requirements. Stakeholders must monitor evolving pharmacovigilance mandates and real-world evidence expectations that will reshape post-approval commitment burdens and lifecycle management strategies.
Market Dynamics
Biologic manufacturing concentration among a handful of contract development and manufacturing organizations is reshaping supply security calculations for reactive arthritis therapeutics, forcing sponsors to diversify their supplier base or absorb capacity premiums.
Growth Catalysts
- FDA Accelerated Approval Pathways:Streamlined biosimilar entry timelines compress competitive response cycles and expand therapeutic options for seronegative spondyloarthropathy patients.
- Hospital Outpatient Expansion:Ambulatory infusion center networks in the United States deploy cold-chain infrastructure that enables same-day biologic administration without inpatient admission.
- Early Immunomodulation Protocols:Rheumatology societies now recommend DMARD initiation within eight weeks of symptom onset, expanding addressable patient populations for disease-modifying therapy.
Market Restraints
- Biologic Cold-Chain Costs:Temperature-controlled logistics for monoclonal antibodies impose per-dose distribution expenses that erode margin at the pharmacy benefit level.
- European Step-Therapy Mandates:Germany's G-BA and France's HAS require documented conventional DMARD failure before biologic reimbursement authorization, delaying revenue recognition.
- Small-Molecule Generic Saturation:NSAID and corticosteroid commoditization eliminates pricing power for originator brands in first-line reactive arthritis management.
Strategic Opportunities
- Auto-Injector Device Convergence:Combination products integrating prefilled syringes with wearable electronics enable home administration and reduce infusion center dependency.
- Real-World Evidence Mandates:Post-approval pharmacovigilance requirements create demand for registry infrastructure and data analytics partnerships.
- India Manufacturing Expansion:CDSCO-aligned facilities offer cost-competitive biologic production for export markets with emerging rheumatology specialist networks.
Industry Challenges
- Biosimilar Interchangeability Standards:FDA switching study requirements demand additional clinical investment beyond analytical biosimilarity, complicating development economics.
- Rheumatology Workforce Constraints:Specialist density gaps in secondary US markets delay diagnosis and compress the window for early biologic intervention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reactive Arthritis Treatment Market |
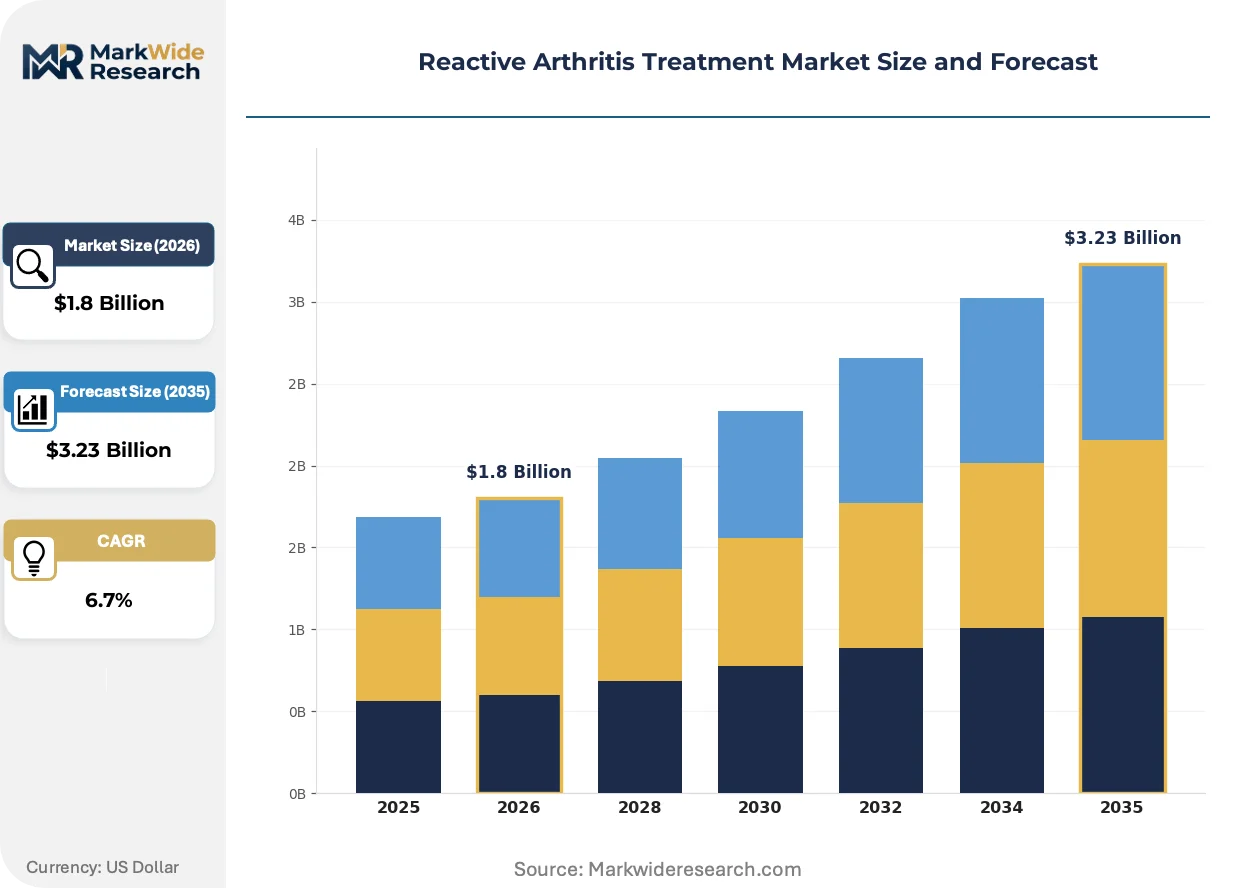
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NSAIDs, Corticosteroids, DMARDs, Analgesics Therapy Area: Rheumatology, Immunology, Pain Management, Orthopedics Delivery Mode: Injectable, Oral, Topical, Infusion Patient Type: Pediatric, Adult, Elderly, Others |
| Companies Covered | F. Hoffmann-La Roche Ltd, Teva Pharmaceutical Industries Ltd, Pfizer, Novartis AG, Amgen Inc, Johnson & Johnson Services, Velcura Therapeutics, Bristol-Myers Squibb Company, AbbVie Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reactive Arthritis Treatment Market Evolving Landscape
Mechanism-driven patient stratification is replacing empirical prescribing in reactive arthritis, with biomarker-guided therapy selection emerging as the dominant clinical decision framework across academic medical centers.
Next-generation IL-17 and IL-23 pathway inhibitors is bifurcating the biologic landscape into cytokine-specific and dual-target modalities. Academic rheumatology departments in the United States and Germany are adopting these agents for enthesitis-predominant phenotypes. The technology is bifurcating prescriber loyalty between mechanism-naive biologics and targeted immunology platforms with companion diagnostic potential.
EMA's Medical Device Regulation framework now governs auto-injector combination products for reactive arthritis biologics, imposing clinical performance validation requirements that exceed prior CE-marking standards. Manufacturers must demonstrate human factors equivalence across patient populations. Injectable TNF inhibitors face the steepest compliance burden given their mature device portfolios requiring retrospective validation.
Site-of-care migration from hospital infusion centers to home administration is compressing the traditional pharmacy benefit management channel. United States commercial payers are unbundling drug reimbursement from administration fees, redirecting volume toward specialty pharmacy distribution. This shift is most visible in employer-sponsored plans with integrated pharmacy and medical benefit administration.
Reactive Arthritis Treatment Market Segmentation
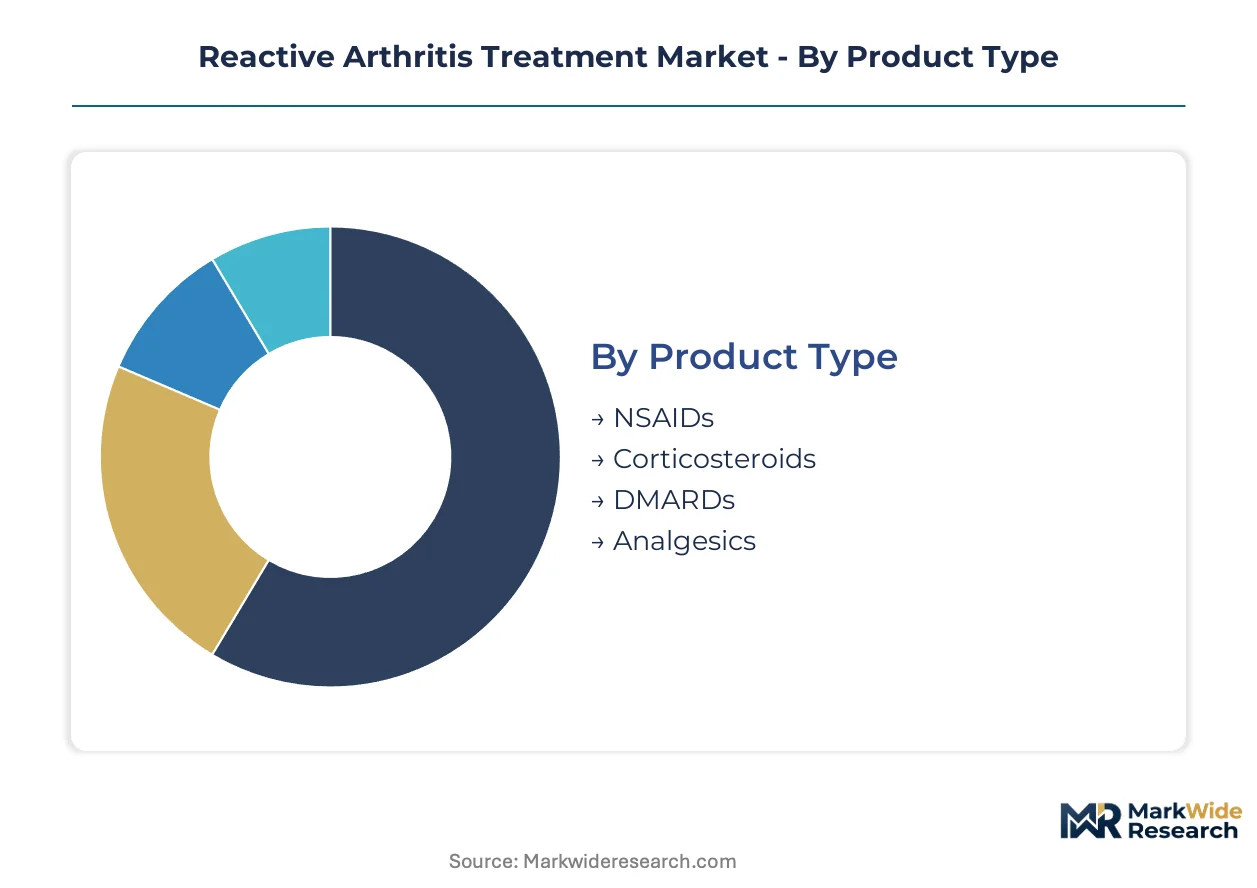
Reactive arthritis therapeutics fragment across mechanism, delivery, and patient stratification dimensions that determine reimbursement pathways and prescriber decision frameworks. Understanding segment interdependencies reveals where formulation innovation intersects with care setting economics.
Product Type:
Demand for oral formulations concentrates in United States retail pharmacy networks, while injectable biologics drive export revenue from European manufacturing clusters.
- NSAIDs:Non-steroidal anti-inflammatory compounds remain the first-line pharmacological intervention for peripheral arthritis and enthesitis. United States primary care networks generate the dominant prescription volume, though generic saturation eliminates originator pricing power. Volume concentrates with ibuprofen and naproxen formulations in employer-sponsored pharmacy benefit plans.
- Corticosteroids:Systemic and intra-articular glucocorticoid preparations provide rapid symptom suppression during acute flares. German rheumatology outpatient clinics deploy depot methylprednisolone for bridging therapy, constrained by EMA pharmacovigilance mandates on cumulative exposure limits.
- DMARDs:Synthetic and biologic disease-modifying agents anchor early immunomodulation protocols in academic medical centers.
- Analgesics:Non-opioid and opioid pain management adjuncts address refractory symptoms outside inflammatory pathways.
NSAIDs hold the largest share; momentum sits with DMARDs.
Therapy Area:
Cost tier stratification separates hospital-based specialty infusion from community rheumatology practice prescribing.
- Rheumatology:Board-certified specialists coordinate multi-agent regimens combining conventional and biologic DMARDs. United States academic medical centers in Boston and San Francisco anchor clinical trial recruitment for next-generation IL-17 pathway inhibitors. Prescriber concentration in tertiary referral networks shapes manufacturer key account strategies.
- Immunology:Cross-disciplinary management addresses systemic autoimmunity beyond joint-specific manifestations. French hospital networks integrate dermatology and gastroenterology consultation for extra-articular reactive arthritis phenotypes. Reimbursement through HAS evaluation frameworks requires demonstrated non-response to conventional therapy.
- Pain Management:Anesthesiology and physical medicine specialists address residual symptoms after inflammatory control.
- Orthopedics:Surgical and non-surgical musculoskeletal specialists manage structural complications and rehabilitation protocols.
Rheumatology commands premium pricing; immunology represents the steepest expansion trajectory.
Delivery Mode:
Patient compliance patterns favor oral administration in pediatric and elderly populations, while working-age adults drive self-injection device adoption.
- Injectable:Prefilled syringes and auto-injector devices enable home administration of biologic monoclonal antibodies. United States specialty pharmacy distribution networks now capture the majority of adalimumab and etanercept volume, displacing traditional infusion center revenue. Cold-chain logistics requirements create natural barriers to commoditization.
- Oral:Tablet and capsule formulations dominate maintenance therapy for conventional DMARDs and NSAIDs. Indian pharmaceutical manufacturing clusters supply cost-competitive methotrexate and sulfasalazine to Southeast Asian and African export markets. Bioequivalence standards under CDSCO oversight determine market access timelines.
- Topical:Transdermal and local delivery systems address enthesitis and limited joint involvement.
- Infusion:Intravenous biologic administration persists for rituximab and abatacept in hospital outpatient settings.
Oral formulations retain the largest prescription base; injectable biologics gain share fastest.
Patient Type:
Volume concentration sits with working-age adults, while pediatric and elderly subpopulations drive unmet need for age-appropriate formulation development.
- Pediatric:Juvenile reactive arthritis requires weight-based dosing and pediatric-specific safety data for biologic authorization. German pediatric rheumatology centers in Heidelberg and Munich anchor European referral networks for enthesitis-related arthritis variants. EMA pediatric investigation plans mandate age-stratified clinical trial enrollment.
- Adult:Patients aged 18-64 represent the dominant addressable population for both conventional and biologic therapy. United States commercial payers condition biologic access on documented conventional DMARD failure through pharmacy benefit prior authorization protocols. Employment status influences site-of-care preferences between infusion centers and home administration.
- Elderly:Polypharmacy considerations and infection risk profile complicate immunomodulator selection in patients over 65.
- Others:Pregnancy, immunocompromised status, and comorbid conditions requiring individualized therapeutic approaches.
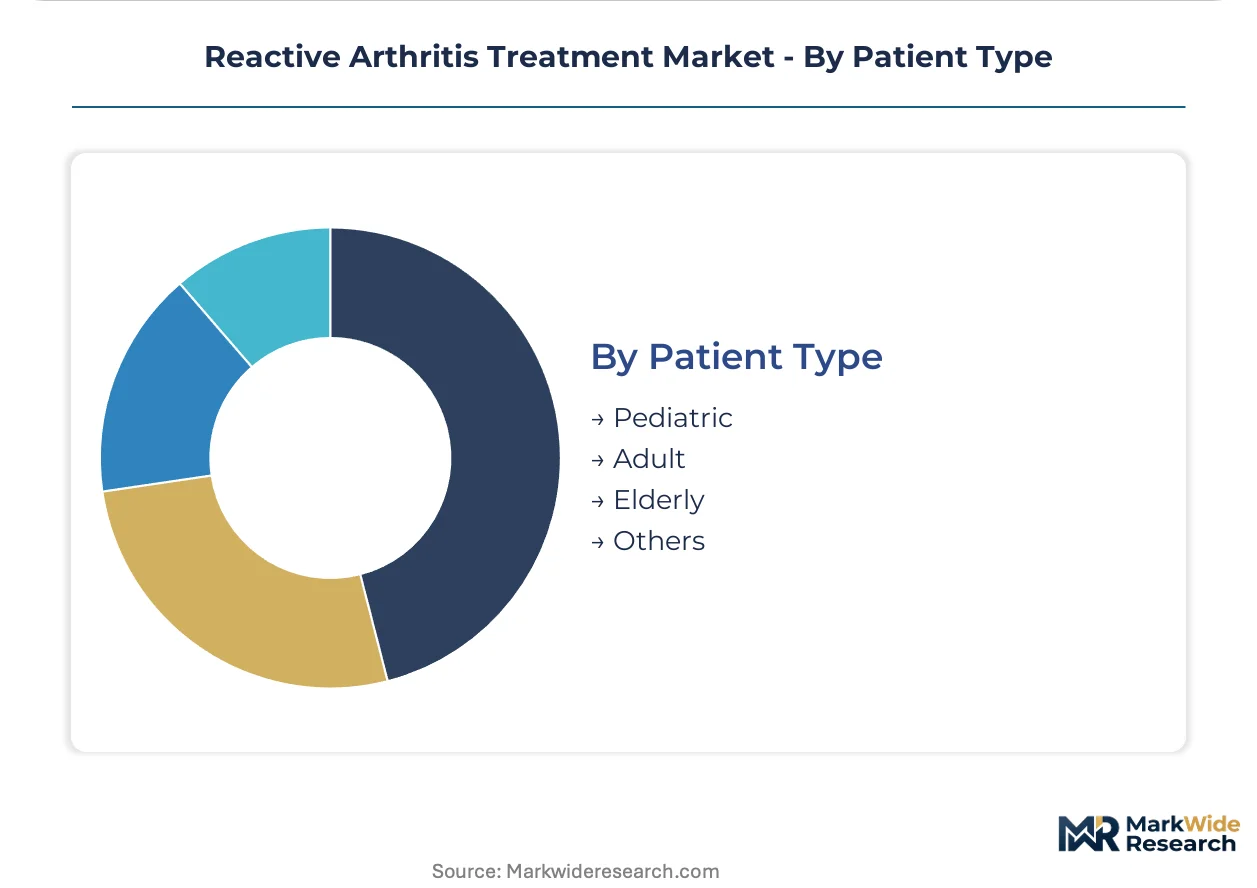
Adult patients hold the largest share; pediatric indications represent the most significant unmet clinical need.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with United States commercial payers absorbing biologic premiums while Indian and Southeast Asian markets prioritize cost-competitive conventional DMARDs. European reimbursement authorities impose the tightest step-therapy constraints, compressing biologic access timelines.
United States
Rheumatology specialist density in Boston and San Francisco anchors clinical trial recruitment for IL-17 pathway inhibitors. The FDA's accelerated approval pathways for biosimilars reshape competitive entry dynamics. Hospital outpatient departments in the Pacific Northwest deploy cold-chain infrastructure enabling same-day biologic administration.
Germany
Academic medical centers in Heidelberg and Munich coordinate multi-agent regimens for seronegative spondyloarthropathies. The G-BA mandates documented conventional DMARD failure before biologic reimbursement authorization. Pediatric rheumatology networks in Bavaria anchor European referral capacity for enthesitis-related arthritis variants.
India
CDSCO-aligned manufacturing clusters supply cost-competitive methotrexate and sulfasalazine to Southeast Asian and African export markets. The national pharmaceutical regulator enforces bioequivalence standards determining market access timelines. Pharmaceutical production concentrates in Maharashtra and Gujarat for oral DMARD formulation.
France
French hospital networks integrate dermatology and gastroenterology consultation for extra-articular reactive arthritis phenotypes. The HAS conditions biologic access on demonstrated non-response to conventional therapy through evaluation frameworks. Île-de-France academic centers anchor clinical decision frameworks for mechanism-driven patient stratification.
United Kingdom
London and Southeast England rheumatology departments adopt next-generation cytokine-specific agents for enthesitis-predominant phenotypes. The MHRA governs biologic licensing standards aligned with post-Brexit regulatory autonomy. Midlands and North England specialist density gaps delay diagnosis and compress early intervention windows.
Reactive Arthritis Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the reactive arthritis therapeutics landscape. Large-cap biologic manufacturers command manufacturing scale and cold-chain logistics infrastructure, while mid-size specialty firms concentrate on immunology-specific pipeline development. The market structures around three archetypes: diversified pharmaceutical conglomerates, immunology-focused biotech specialists, and development-stage mechanism innovators. Competitive moves center on auto-injector device convergence for home administration and real-world evidence partnerships for post-approval pharmacovigilance.
Among diversified pharmaceutical conglomerates, Pfizer and AbbVie occupy positions reflecting distinct strategic foundations. Pfizer exemplifies broad manufacturing scale across small-molecule and biologic platforms. AbbVie represents deep immunology specialization anchored by decades of rheumatology pipeline investment. Velcura Therapeutics sits within the development-stage tier, navigating early-stage clinical validation with targeted mechanism approaches.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Teva Pharmaceutical Industries Ltd |
| Pfizer |
| Novartis AG |
| Amgen Inc |
| Johnson & Johnson Services |
| Velcura Therapeutics |
| Bristol-Myers Squibb Company |
| AbbVie Inc |
| Others |
Value Network & Pricing Analysis
FDA biosimilar interchangeability standards gate both manufacturer qualification and price differentiation simultaneously, requiring analytical similarity plus switching studies that compress margin structures for entrants while protecting originator pricing power through clinical validation burdens.
Pricing Analysis
Administration service bundling drives lifetime value through infusion center fees and specialty pharmacy management contracts. Pricing stratifies across premium biologic tiers with companion diagnostic protocols, standard self-injection devices, and economy-positioned conventional DMARDs. Cost compression in oral NSAIDs intensifies due to Indian and Chinese generic saturation. Employer-sponsored plans in the United States show highest price sensitivity, while German G-BA-mandated step-therapy creates inelastic demand for documented non-responders.
Supply Chain Analysis
Cold-chain inventory requirements extend lead times for monoclonal antibodies beyond conventional pharmaceutical distribution cycles. Manufacturing concentrates in United States biologic clusters, German precision device facilities, and Indian API synthesis hubs. Supply security hinges on single-source dependencies for sterile fill-finish capacity and temperature-controlled logistics networks. Tariff exposure on Chinese-sourced injection devices creates margin vulnerability. Distribution runs through United States specialty pharmacy networks and European hospital outpatient procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways for biosimilars constitute a regulatory inflection that compresses competitive response cycles and rewards agile manufacturing scale-up, positioning reactive arthritis therapeutics for high-growth disruption through mechanism-driven patient stratification.
For Market Incumbents: Consolidate manufacturing scale advantages through backward integration into sterile fill-finish capacity and captive cold-chain logistics networks. Anchor prescriber loyalty via real-world evidence partnerships with academic medical centers in Boston and Heidelberg. Defend against IL-17 pathway inhibitor displacement by embedding companion diagnostic protocols within existing TNF inhibitor franchises. For New Entrants and Emerging Players: Home administration support services represent a service-layer gap where incumbents under-serve working-age adult populations seeking infusion center alternatives. Target employer-sponsored plans with integrated pharmacy and medical benefit administration for auto-injector combination products. Penetrate Indian and Southeast Asian export markets through CDSCO-aligned manufacturing partnerships offering cost-competitive conventional DMARDs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologic auto-injector combination products due to EMA MDR compliance burdens and FDA switching study requirements. Long-term viability favors platform acquisitions with validated device portfolios and established rheumatology prescriber relationships. Monitor biosimilar interchangeability determinations as the critical signal for competitive pricing pressure inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Auto-Injector Device Convergence | Wearable electronics integration enables home administration and reduces United States infusion center dependency. |
| Real-World Evidence Partnership | Registry infrastructure with academic medical centers satisfies EMA pharmacovigilance mandates and anchors prescriber loyalty. |
| India Manufacturing Expansion | CDSCO-aligned facilities offer cost-competitive biologic production for Southeast Asian and African export markets. |
| Biosimilar Interchangeability Pursuit | FDA switching studies expand therapeutic options while compressing originator margin protection timelines. |
| Mechanism-Driven Patient Stratification | IL-17 and IL-23 pathway specificity differentiates prescribing in enthesitis-predominant phenotypes across German and United States academic centers. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchors the qualitative findings against secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient population modeling and top-down therapeutic category sizing provide triangulation checks across the analysis window.
Sensitivity analysis tests volume and value outputs across treatment line, dosage form, administration route, and patient population segmentation dimensions. CAGRs derive from epidemiological prevalence projections, biologic penetration rate assumptions, and pricing trajectory modeling through the projection horizon. Forecast inputs include rheumatology specialist density mapping and step-therapy compliance rate assumptions by national reimbursement authority.
Forecasts assume regulatory continuity in FDA accelerated approval pathways and EMA MDR device frameworks; material policy shifts in biosimilar interchangeability standards or pediatric investigation plan mandates would require re-modeling. Outputs reflect modeling assumptions about cold-chain logistics cost trajectories and biosimilar entry timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Global Pheochromocytoma Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Global Prurigo Nodularis Treatment Market
Specialty Medicine
Adult Malignant Glioma Therapeutics Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market
Specialty Medicine
Hypothyroidism Market
Specialty Medicine
Endometriosis Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Radiation Toxicity Treatment Market
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market