
 Omics-Based Clinical Trials Market | 2026-2036
Omics-Based Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Omics-Based Clinical Trials Market Intelligence
Biopharmaceutical sponsors is unwinding reliance on traditional chemocentric trial models toward precision-medicine archetypes that stratify patients by molecular profile. Thermo Fisher Scientific anchors its position through captive supply of next-generation sequencing platforms purpose-built for clinical-grade variant detection. Charles River Laboratories differentiates via in-house production of genetically characterized model organisms that shorten preclinical omics validation cycles.
Omics-based clinical trials integrate multi-omic molecular profiling—genomics, proteomics, metabolomics, and transcriptomics—into prospective human studies to identify predictive biomarkers, stratify responder populations, and monitor pharmacodynamic endpoints with nucleotide-level resolution. Genomics commands the largest share of current protocol spend as whole-exome sequencing becomes standard in oncology basket trials, while metabolomics represents the fastest-expanding technology layer as sponsors seek circulating small-molecule signatures for early toxicity signals. Phase II trials absorb disproportionate omics investment because go-no-go decisions at this stage depend heavily on biomarker-defined efficacy signals that reshape downstream development economics.
FDA biomarker qualification programs and EMA's qualification of novel methodologies jointly shape protocol design standards, with both agencies now requiring pre-specified omics analysis plans as condition for accelerated assessment pathways. ISO 14155 and ICH E6(R2) impose data integrity and source-verification requirements that drive sponsor demand for CLIA-certified laboratory partners with validated bioinformatics pipelines. Stakeholders must decide whether to build captive sequencing capacity or outsource to platform-agnostic contract research organizations as regulatory scrutiny of algorithm-derived endpoints intensifies.
Market Dynamics
Precision-medicine protocols now require nucleotide-level patient stratification, forcing sponsors to rebuild trial infrastructure around CLIA-certified sequencing pipelines and pre-specified bioinformatics analysis plans.
Growth Catalysts
- FDA Biomarker Qualification Programs:Accelerated assessment pathways now mandate omics endpoints, compressing Phase II go-no-go timelines for oncology sponsors.
- Transcriptomics Integration:Adaptive basket trials deploy RNA sequencing to identify responder populations in real time, reshaping enrollment criteria mid-protocol.
- United States Infrastructure Concentration:Academic medical centers and CROs co-locate sequencing capacity near patient populations, shortening sample-to-data turnaround.
Market Restraints
- Illumina Platform Dependence:Sequencing hardware concentration creates single-supplier vulnerability for clinical-grade variant detection workflows.
- ISO 14155 Compliance Burden:Data integrity and source-verification requirements impose validation costs that exclude mid-tier sponsors from omics-enabled protocols.
- Bioinformatics Talent Scarcity:Shortage of computational biologists with clinical regulatory experience slows pipeline deployment across sponsor organizations.
Strategic Opportunities
- Metabolomics Toxicity Signatures:Circulating small-molecule profiling offers early safety signals that reduce late-stage attrition in immuno-oncology programs.
- EMA Qualification of Novel Methodologies:European accelerated pathways for proteomic endpoints create first-mover positioning for sponsors with validated mass spectrometry workflows.
- Multi-Omic Data Integration:Convergence of genomics, proteomics, and metabolomics layers enables synthetic responder definitions that single-modal assays cannot capture.
Industry Challenges
- Algorithm-Derived Endpoint Scrutiny:Regulators now demand full transparency in variant-calling pipelines, forcing sponsors to rebuild black-box bioinformatics into auditable decision trees.
- Captive versus Outsourced Capacity:Stakeholders face capital allocation decisions between building in-house sequencing infrastructure and platform-agnostic CRO partnerships under intensifying CLIA oversight.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omics-Based Clinical Trials Market |
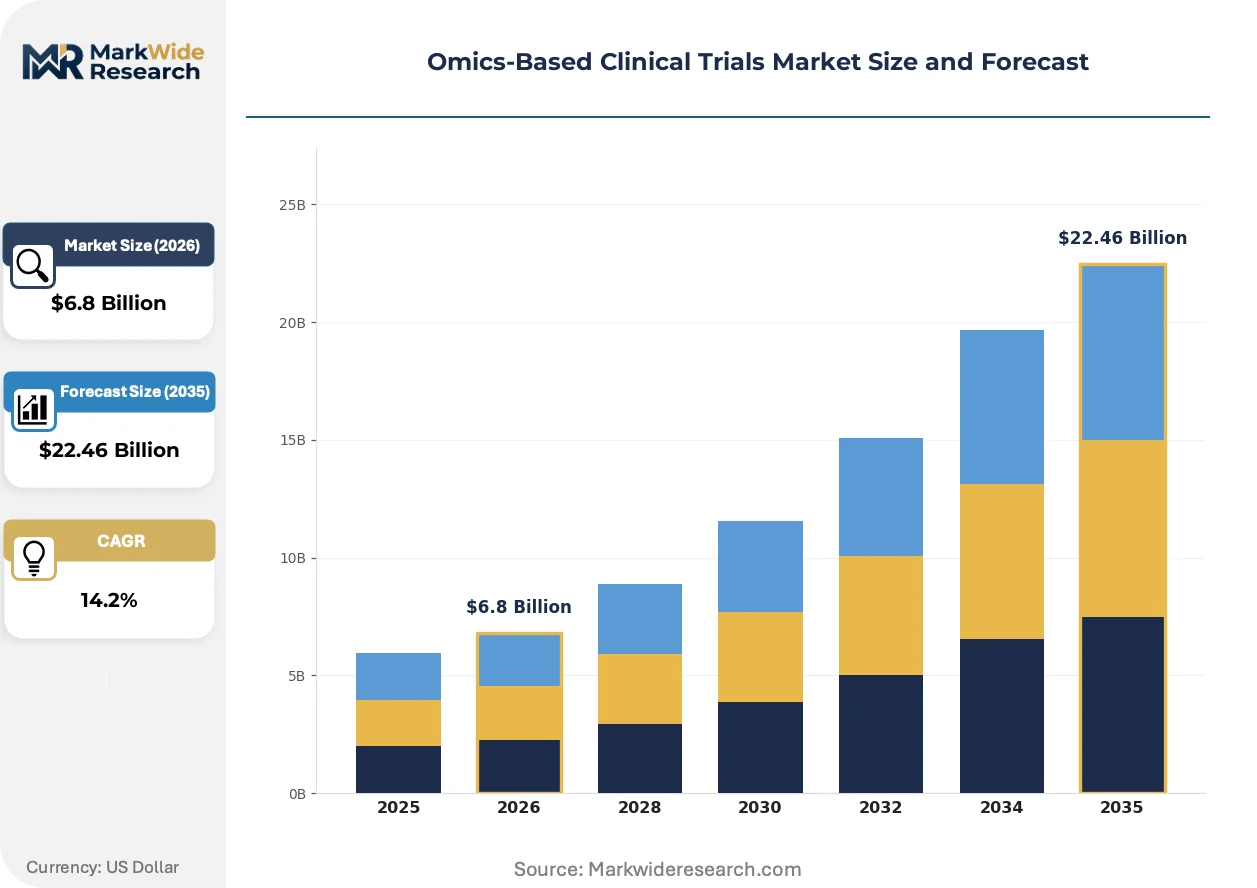
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Genomics, Proteomics, Metabolomics, Transcriptomics Trial Phase: Preclinical, Phase I, Phase II, Phase III Application: Oncology, Neurology, Cardiovascular, Infectious Diseases Study Design: Randomized Controlled Trials, Observational Studies, Cohort Studies, Case-Control Studies |
| Companies Covered | Parexel International Corporation, Thermo Fisher Scientific Inc., Charles River Laboratories, ICON plc, SGS SA, Eli Lilly and Company, Pfizer Inc., Laboratory Corporation of America, Novo Nordisk A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omics-Based Clinical Trials Market Strategic Shifts & Innovations
Protocol design is fragmenting from fixed chemocentric models toward adaptive molecular frameworks that regenerate enrollment criteria based on real-time biomarker readouts.
Single-cell RNA sequencing is decomposing bulk-tumor expression profiles into clonal-resolution maps that reveal heterogeneity-driven resistance mechanisms. Oncology sponsors at the Phase I-II boundary now require single-cell layers in basket trial protocols. This resolution is decomposing traditional RECIST endpoints into molecular response signatures that predict survival months earlier than imaging.
EMA's qualification of novel methodologies now runs parallel to FDA biomarker programs, creating dual-track validation requirements for sponsors seeking transatlantic trial harmonization. European sponsors must pre-specify proteomic analysis plans to access PRIME designation. This regulatory layering most affects immuno-oncology developers running parallel US-EU Phase II programs.
Site selection criteria now weight proximity to sequencing infrastructure more heavily than traditional patient density metrics. Academic medical centers with captive CLIA labs command premium investigator fees. This geographic re-prioritization concentrates trial volume in Boston, San Francisco, and Research Triangle Park corridors where sequencing capacity outstrips national averages.
Omics-Based Clinical Trials Market Segmentation
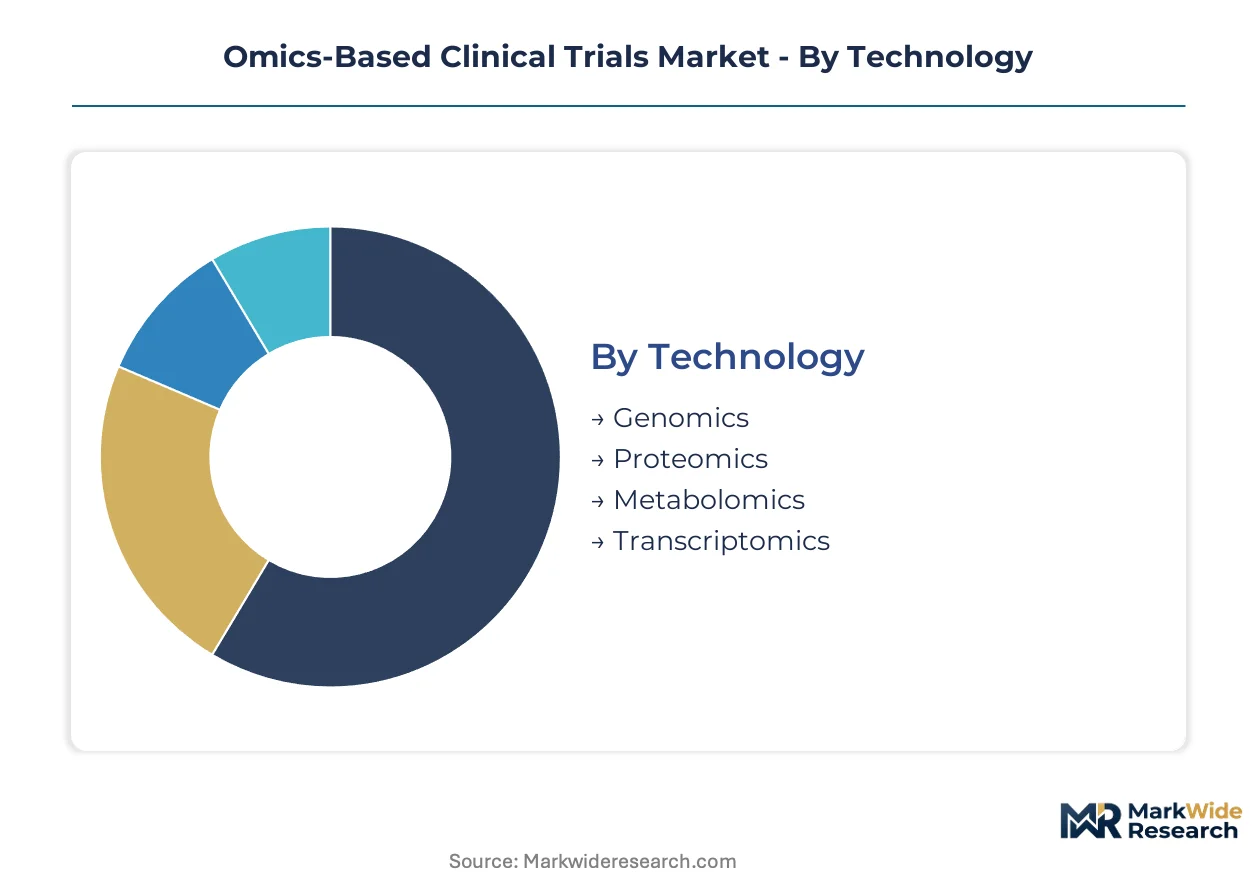
Omics-based clinical trials fragment across four intersecting dimensions that determine regulatory pathway, infrastructure investment, and biomarker validation requirements. Each segmentation layer carries distinct CLIA certification demands and FDA or EMA pre-submission obligations that reshape sponsor procurement decisions.
Technology:
FDA biomarker qualification programs and EMA's qualification of novel methodologies impose divergent validation standards across molecular profiling platforms, forcing sponsors to align technology selection with target market access strategy.
- Genomics:Whole-exome and whole-genome sequencing protocols dominate oncology basket trials through nucleotide-level variant detection. United States academic medical centers concentrate demand where CLIA-certified infrastructure co-locates with patient recruitment pools.
- Transcriptomics:RNA sequencing enables real-time responder stratification in adaptive protocols. Phase II sponsors deploy transcriptomic layers to regenerate enrollment criteria mid-trial based on expression signatures.
- Proteomics:Mass spectrometry workflows qualify for EMA PRIME designation pathways when pre-specified in European protocols.
- Metabolomics:Circulating small-molecule profiling captures early toxicity signals in immuno-oncology programs.
Genomics handles the majority of throughput; metabolomics is the fastest mover on share.
Trial Phase:
Capital allocation intensity varies sharply across development stages, with biomarker-defined go-no-go decisions compressing economic risk into specific protocol boundaries.
- Phase II:Absorbs disproportionate omics investment as sponsors depend on molecular efficacy signals to reshape downstream development economics. Adaptive designs with real-time biomarker readouts concentrate here.
- Phase I:Single-cell RNA sequencing layers now standard at the Phase I-II boundary for clonal-resolution resistance mapping. Dose-escalation protocols incorporate pharmacodynamic endpoints with nucleotide-level resolution.
- Preclinical:Genetically characterized model organisms shorten validation cycles before human studies.
- Phase III:Confirmatory trials require pre-specified omics analysis plans as condition for accelerated assessment pathways.
Phase II commands the largest share of omics-enabled protocol spend; Phase I is expanding most quickly as single-cell resolution becomes standard.
Application:
Disease-area biology dictates the optimal omics modality mix, with molecular heterogeneity driving technology selection.
- Oncology:Basket and umbrella trials deploy multi-omic integration to capture synthetic responder definitions. FDA accelerated approval pathways mandate pre-specified genomic stratification in solid tumor protocols.
- Neurology:Cerebrospinal fluid proteomics and metabolomics face blood-brain barrier penetration challenges that limit peripheral biomarker utility.
- Cardiovascular:Circulating metabolite panels track myocardial injury with faster kinetic profiles than troponin alone.
- Infectious Diseases:Host transcriptomic response signatures differentiate viral from bacterial etiology for antimicrobial stewardship trials.
Oncology maintains the deepest omics protocol penetration; infectious diseases is climbing the fastest as pandemic preparedness funding flows into host-response biomarker development.
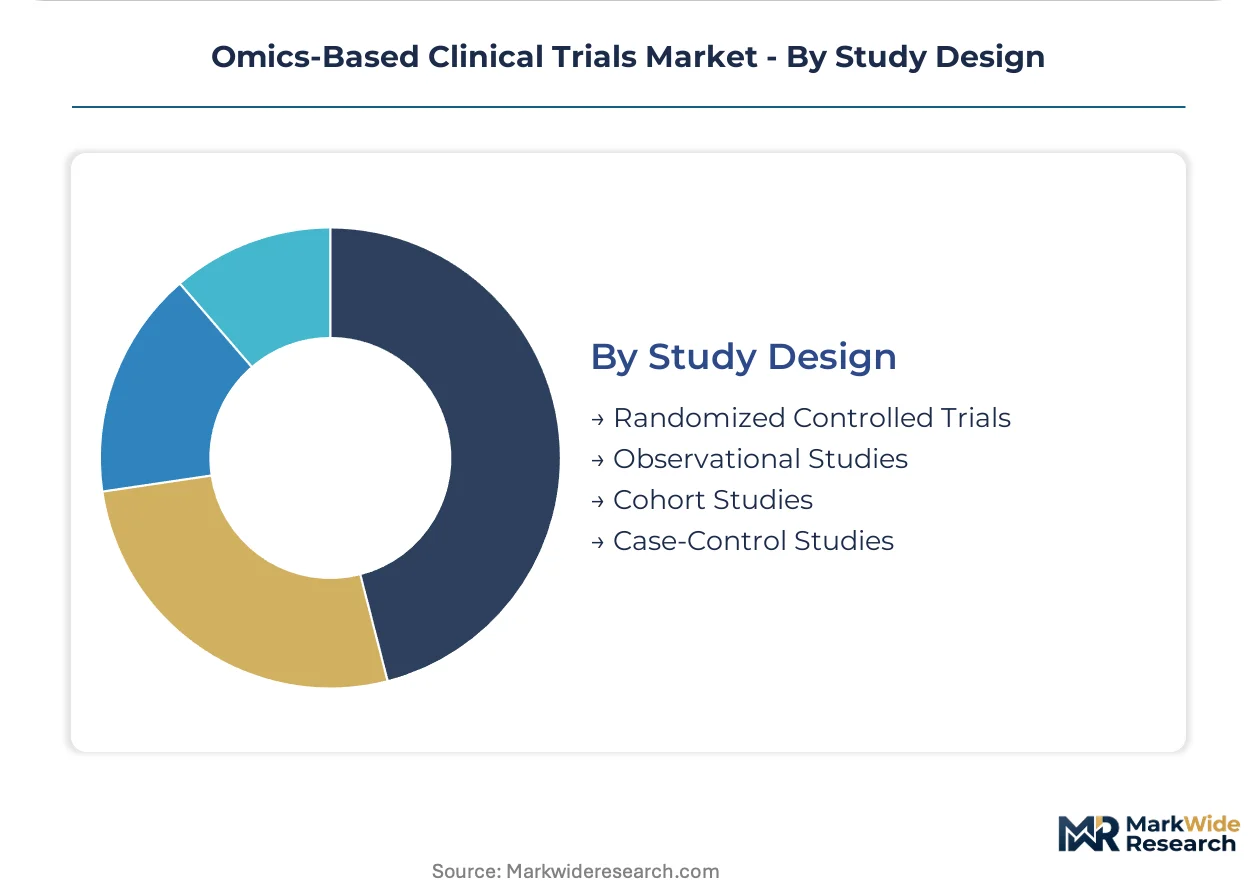
Study Design:
Regulatory scrutiny of algorithm-derived endpoints reshapes permissible statistical frameworks for omics-enabled evidence generation.
- Randomized Controlled Trials:Remain the gold standard for regulatory submission despite adaptive complexity. ICH E6(R2) imposes data integrity requirements that drive demand for validated bioinformatics pipelines.
- Observational Studies:Real-world evidence frameworks incorporate prospective omics collection to supplement interventional trial data.
- Cohort Studies:Longitudinal molecular profiling tracks pharmacodynamic trajectories across extended follow-up periods.
- Case-Control Studies:Retrospective biospecimen analysis enables discovery-phase biomarker hypothesis generation with limited regulatory utility.
Randomized controlled trials dominate regulatory-grade throughput; observational studies are gaining share fastest as real-world evidence pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sequencing infrastructure concentrates where academic medical centers and contract research organizations cluster near patient recruitment pools. The United States absorbs the dominant share of omics-enabled protocol investment, while European and Asia-Pacific markets expand through regulatory harmonization efforts.
United States
FDA biomarker qualification programs compress Phase II timelines for oncology sponsors deploying transcriptomic stratification. The agency's accelerated approval pathways mandate pre-specified genomic analysis plans as a condition for priority review. Boston, San Francisco, and Research Triangle Park corridors command premium investigator fees where CLIA-certified labs outstrip national sequencing capacity.
Germany
EMA's qualification of novel methodologies drives proteomic endpoint validation for sponsors seeking PRIME designation. The country's national pharmaceutical regulator enforces ISO 14155 data integrity requirements that favor platform-agnostic laboratory partnerships. Munich and Heidelberg academic medical centers anchor multi-omic protocol execution for transatlantic trial harmonization.
United Kingdom
Genomics England's infrastructure investments position NHS trusts as preferred sites for basket trial enrollment. The Medicines and Healthcare products Regulatory Agency aligns with FDA biomarker standards to streamline dual-track submissions. London and Cambridge clusters concentrate single-cell RNA sequencing capacity for Phase I-II boundary studies.
China
NMPA's novel drug review reforms accelerate local sponsor adoption of Western precision-medicine protocols. The national medical products regulator now recognizes CLIA-equivalent laboratory certifications for imported biomarker data. Shanghai and Beijing biotech parks attract multinational Phase II programs seeking parallel Asia-Pacific enrollment.
Switzerland
Swissmedic's streamlined qualification procedures attract sponsors requiring rapid proteomic endpoint validation. The national regulatory agency coordinates with EMA on multi-omic analysis plan pre-submissions. Basel and Zurich pharmaceutical corridors integrate metabolomics layers into immuno-oncology safety monitoring protocols.
Omics-Based Clinical Trials Market Key Industry Players
Concentration sits with integrated life sciences conglomerates and specialized contract research organizations. Tiered competition separates platform-owning conglomerates from service-only CROs and mid-tier biopharmaceutical sponsors building captive capacity. Strategic archetypes include sequencing-hardware suppliers, full-service clinical trial operators, and genetically characterized model organism producers. Dominant competitive moves span backward integration into bioinformatics pipelines and geographic co-location of laboratory infrastructure near patient recruitment hubs.
Among full-service CROs, Parexel International Corporation and ICON plc exemplify the platform-agnostic service model that sponsors deploy to avoid single-supplier sequencing dependence. Thermo Fisher Scientific Inc. anchors the hardware-supplier archetype through captive next-generation sequencing platforms purpose-built for clinical-grade variant detection. Charles River Laboratories occupies a specialist position in preclinical validation, shortening genetically characterized model organism production cycles before human studies commence.
| Leading Market Players |
|---|
| Parexel International Corporation |
| Thermo Fisher Scientific Inc. |
| Charles River Laboratories |
| ICON plc |
| SGS SA |
| Eli Lilly and Company |
| Pfizer Inc. |
| Laboratory Corporation of America |
| Novo Nordisk A/S |
| Others |
Cost & Logistics Intelligence
CLIA certification requirements gate both laboratory qualification and pricing tier structure, forcing sponsors to pay premiums for validated bioinformatics pipelines while excluding mid-tier competitors from omics-enabled protocols entirely.
Pricing Analysis
ISO 14155 dictates the pricing tier structure across three certification levels: premium CLIA-plus-GCP validated labs command investigator fee multiples, standard CLIA-certified facilities serve mainstream Phase II programs, and non-certified research-grade providers compete only for preclinical discovery work. Price differentiation hinges on regulatory validation depth and bioinformatics transparency—sponsors now demand auditable variant-calling pipelines as a condition for protocol inclusion. Cost compression in the standard tier is intensifying because platform-agnostic CROs compete aggressively for adaptive oncology contracts. Academic medical centers with captive sequencing infrastructure show least price sensitivity, while emerging biotech sponsors face effective exclusion from transcriptomics-enabled trials due to upfront validation costs.
Supply Chain Analysis
Port congestion on trans-Pacific lanes elevates inbound logistics costs for sequencing consumables and mass spectrometry reagents, compressing margins for CROs without long-term supplier contracts. Hardware supply concentrates in the United States, China, and Germany, where Illumina, Thermo Fisher, and BGI Genomics manufacture next-generation sequencing platforms. Raw material dependencies span semiconductor chips for signal detection, specialty biochemical reagents for library preparation, and noble gases for mass spectrometry ionization. Single-source vulnerability permeates the sequencing hardware layer—Illumina's dominant market position in clinical-grade instruments creates supply continuity risk for sponsors locked into proprietary flow cell formats. Distribution runs through direct manufacturer partnerships with academic medical centers and full-service CRO networks, bypassing traditional pharmaceutical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Omics-based clinical trials represent a service-attach opportunity where bioinformatics analysis subscriptions and longitudinal biomarker monitoring contracts expand faster than sequencing hardware sales, creating recurring revenue pools that reshape vendor economics.
For Market Incumbents: Secure exclusive partnerships with academic medical centers possessing captive CLIA infrastructure, locking in preferred site status before competitors replicate the co-location model. Deepen bioinformatics talent pipelines through computational biology training programs that address regulatory-experienced staff scarcity. Platform-agnostic CROs threaten hardware suppliers by decoupling sequencing services from instrument purchases, making backward integration into validated analysis pipelines essential for margin defense. For New Entrants and Emerging Players: Anchor in metabolomics toxicity monitoring for immuno-oncology programs, where circulating small-molecule profiling remains underpenetrated relative to genomic stratification. European sponsors seeking EMA PRIME designation present the most penetrable entry point, as proteomic endpoint validation requirements outstrip current mass spectrometry service capacity. A go-to-market angle emphasizing dual-track FDA-EMA qualification support differentiates against US-centric incumbents. For Investors and Strategic Acquirers: FDA biomarker qualification program expansion reshapes the acquisition landscape by elevating the strategic value of laboratories with pre-submission track records and validated variant-calling pipelines. Target acquisition archetypes include mid-tier CROs possessing CLIA certification but lacking bioinformatics scale, where technology tuck-ins transform cost centers into margin-accretive service layers. Watch EMA qualification of novel methodologies timeline as the signal for European market inflection—accelerated proteomic endpoint approvals would trigger sponsor procurement shifts toward validated mass spectrometry providers.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Partnership | Co-locating sequencing capacity near patient recruitment pools shortens sample-to-data turnaround for adaptive trials. |
| Bioinformatics Pipeline Validation | Auditable variant-calling algorithms satisfy FDA scrutiny of algorithm-derived endpoints in oncology protocols. |
| Multi-Omic Data Integration | Converging genomics, proteomics, and metabolomics layers enables synthetic responder definitions single-modal assays cannot capture. |
| EMA PRIME Designation Support | Pre-specified proteomic analysis plans accelerate European accelerated assessment pathways for immuno-oncology sponsors. |
| Single-Cell RNA Sequencing Capacity | Clonal-resolution resistance mapping at the Phase I-II boundary decomposes bulk-tumor profiles into survival-predictive signatures. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, clinical operations directors, and biomarker scientists at pharmaceutical sponsors and CROs; and secondary validation against FDA biomarker qualification filings, EMA qualification of novel methodologies submissions, ClinicalTrials.gov protocol registries, and ISO 14155 audit records. Bottom-up triangulation aggregated site-level sequencing capacity and investigator fee structures, while top-down reconciliation tested aggregate market estimates against disclosed R&D spending patterns in sponsor SEC filings.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmented projections across technology modality, trial phase, therapeutic application, and study design archetype. CAGRs derived from fitted growth curves incorporating regulatory pathway acceleration rates, infrastructure investment cycles, and biomarker adoption S-curves. Industry-specific forecast inputs included FDA accelerated approval pathway utilization rates and single-cell RNA sequencing protocol penetration at Phase I-II boundaries.
Material uncertainties—regulatory qualification timeline delays, sequencing platform technology transitions, and bioinformatics talent supply constraints—sit outside the modeled envelope. Forecasts reflect documented assumptions about EMA-FDA harmonization progress and sponsor capital allocation preferences between captive capacity and outsourced services. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
AI in Clinical Trials Market
Clinical Research
US Clinical Trials Market
Clinical Research
Non-Alcoholic Steatohepatitis Clinical Trials Market
Clinical Research
Global Clinical Trial Support Services Market
Clinical Research
Esource and Clinical Trials Market
Clinical Research
Real World Evidence Linkage Services Market
Clinical Research
Ecoa, Esource & Clinical Trials Market
Clinical Research
Clinical Trial Logistics Market
Clinical Research
Clinical Trial Management Services Market
Clinical Research
AI-Based Clinical Trial Solutions for Patient Matching Market
Clinical Research
North America Clinical Trials Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
Healthcare Contract Research Organization Market
Clinical Research
North America Contract Research Organization Market
Clinical Research
Preclinical CRO Market
Clinical Research
US Virtual Clinical Trials Market