
 Critical Care Diagnostics Market | 2026-2036
Critical Care Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Critical Care Diagnostics Market Analytics
Software-defined maintenance subscriptions is expanding as a recurring revenue layer that redefines capital equipment sales in critical care settings. Abbott Laboratories leverages extensive service networks to lock in long-term hospital contracts. Siemens Healthineers anchors its position through predictive uptime guarantees tied to remote monitoring platforms. Danaher Corporation competes by bundling consumable reorders with tiered service agreements that reduce total cost-of-ownership calculations for buyers.
Critical care diagnostics encompasses rapid-turnaround laboratory and near-patient testing systems designed to guide life-sustaining interventions, typically requiring sample-to-result intervals under fifteen minutes and analytical precision within clinically actionable ranges. Blood gas analyzers and point-of-care testing represent the most deeply penetrated product categories, while mass spectrometry adoption is accelerating fastest among technology platforms as hospitals pursue broader metabolite profiling from single sample inputs. Sepsis and cardiac care applications command disproportionate investment attention due to their direct linkage to mortality reduction metrics that shape reimbursement and quality ratings.
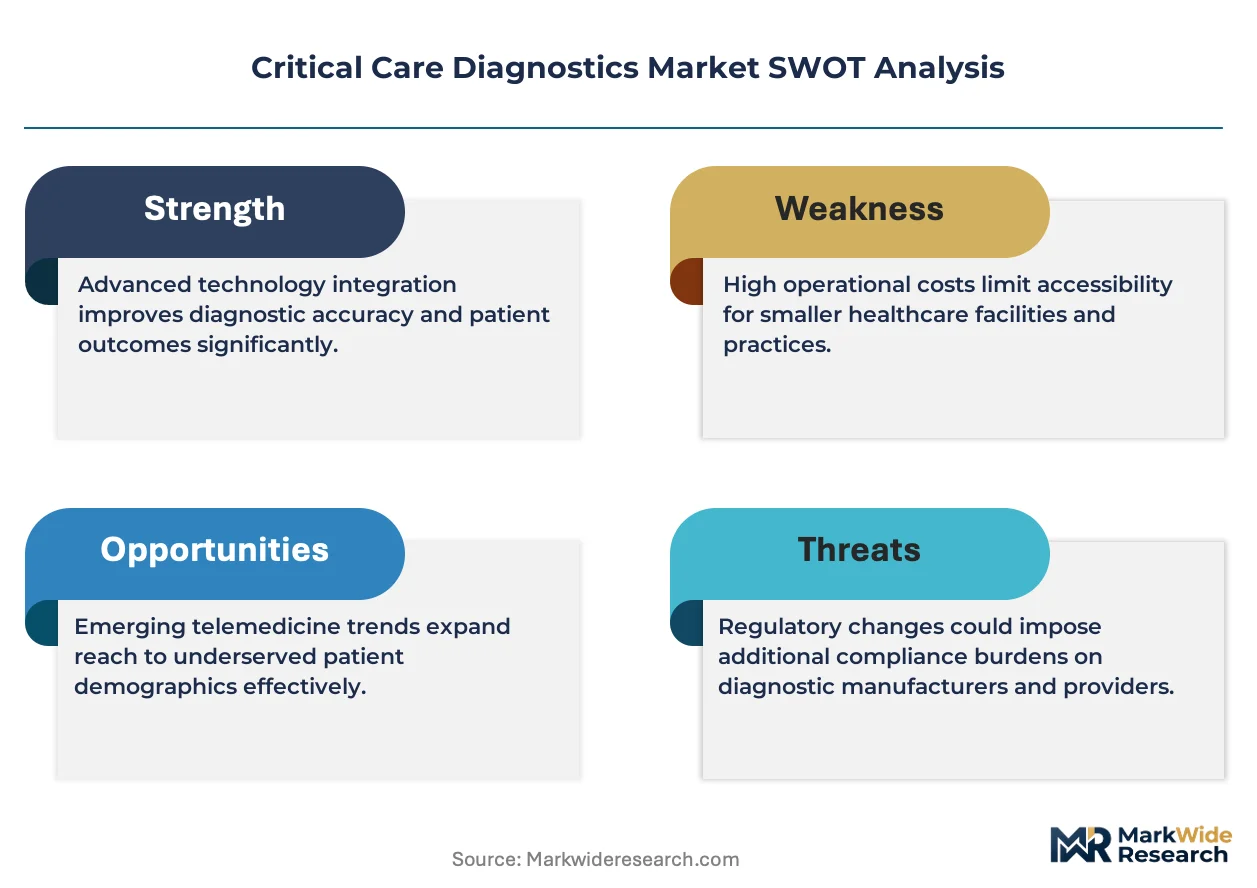
FDA premarket notification pathways and Clinical Laboratory Improvement Amendments standards shape device commercialization timelines and analytical performance claims for US manufacturers, while ISO 15189 accreditation requirements influence international competitive positioning. The EU In Vitro Diagnostic Regulation is forcing substantial technical documentation upgrades that favor established players with dedicated regulatory affairs infrastructure. Stakeholders must weigh the trade-off between platform consolidation for operational efficiency and maintaining modular instrument flexibility to accommodate emerging biomarker panels.
Market Dynamics
Hospital emergency departments are consolidating point-of-care testing footprints to compress sample-to-result intervals below fifteen minutes, forcing manufacturers to re-architect platform designs around speed and analytical precision rather than standalone instrument sales.
Growth Catalysts
- CLIA-waived test expansion:The Clinical Laboratory Improvement Amendments pathway accelerates commercialization timelines for moderate-complexity devices, enabling broader deployment in satellite clinics and urgent care settings.
- Sepsis mortality reduction mandates:CMS quality metrics tie reimbursement to rapid pathogen identification, creating institutional pressure to adopt blood culture identification systems with accelerated turnaround.
- Mass spectrometry miniaturization:Benchtop systems now deliver metabolite profiling from single sample inputs, displacing multi-instrument workflows in tertiary care laboratories.
Market Restraints
- Reagent supply concentration:Specialty chemistries and calibration materials depend on a limited supplier base in Germany and Japan, exposing procurement to geopolitical friction and batch consistency risks.
- EU MDR documentation burden:The In Vitro Diagnostic Regulation requires extensive clinical evidence packages that extend technical file preparation by eighteen to twenty-four months for novel biomarker panels.
- Fluorescent immunoassay substitution:Molecular amplification methods are capturing share in respiratory pathogen detection, compressing addressable volume for traditional lateral flow formats.
Strategic Opportunities
- India's district hospital tier:The PLI scheme for medical devices incentivizes domestic manufacturing of blood gas analyzers, creating first-mover advantages in underpenetrated secondary care networks.
- AI-augmented result interpretation:Machine learning integration with hematology analyzers is automating morphological classification, reducing specialist pathologist dependency in resource-constrained settings.
- Remote monitoring service contracts:Predictive uptime guarantees tied to cloud-connected platforms are displacing break-fix maintenance models, locking in recurring revenue streams.
Industry Challenges
- Multiplex assay validation complexity:Simultaneous detection of sepsis biomarkers requires extensive cross-reactivity testing that extends FDA premarket notification timelines.
- Laboratory information system integration:Point-of-care devices must navigate heterogeneous HL7 FHIR implementations across health networks, delaying deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Critical Care Diagnostics Market |
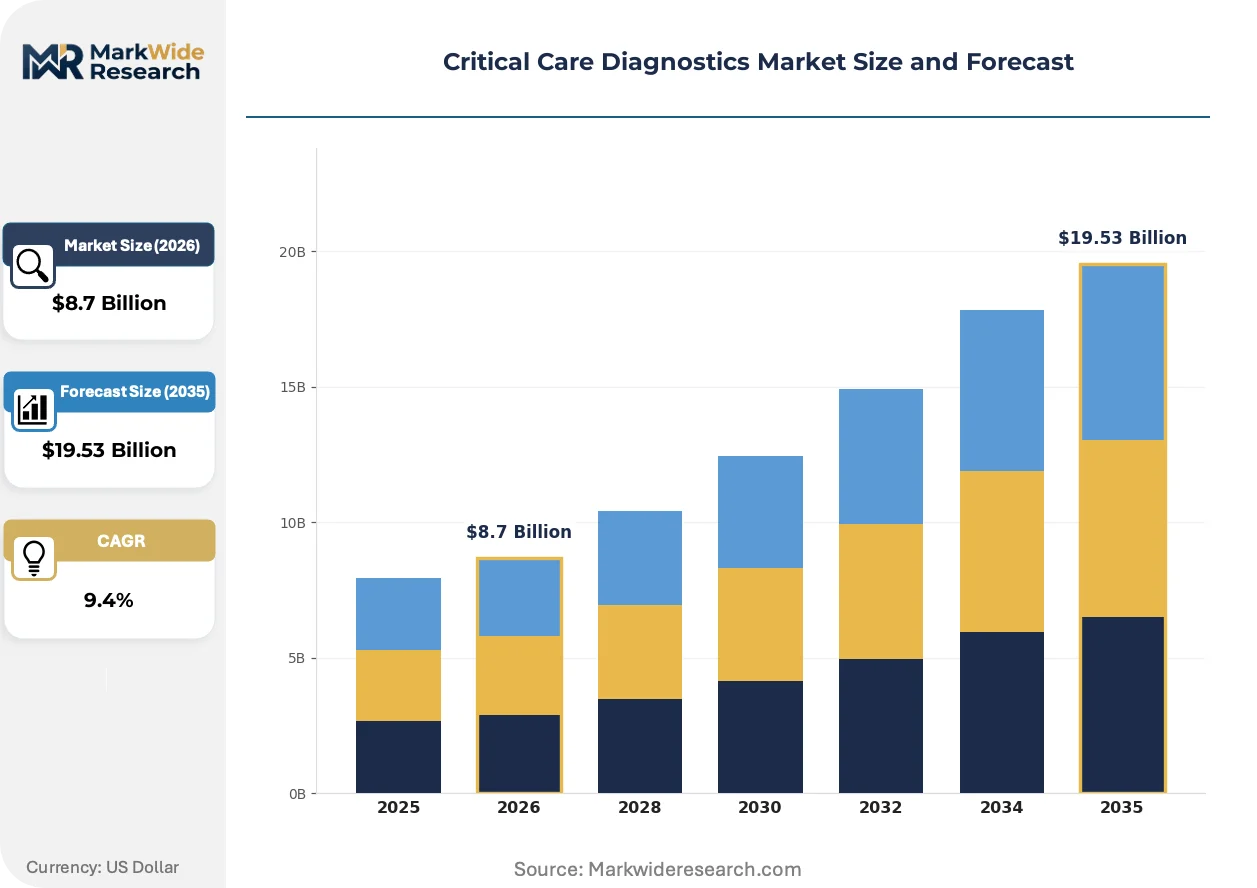
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Gas Analyzers, Hematology Analyzers, Electrolyte Analyzers, Point-of-Care Testing Technology: Electrochemical, Colorimetric, Fluorescence, Mass Spectrometry Application: Cardiac Care, Neurology, Respiratory, Sepsis End User: Hospitals, Diagnostic Laboratories, Home Healthcare, Emergency Medical Services |
| Companies Covered | Abbott Laboratories, Siemens Healthineers, F. Hoffmann-La Roche Ltd, Danaher Corporation, bioMérieux, Becton, Dickinson and Company, Sysmex Corporation, Thermo Fisher Scientific, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Critical Care Diagnostics Market Evolving Landscape
Automation architectures are compressing manual workflow steps while regulatory frameworks force documentation upgrades that favor established technical infrastructures. Demand patterns are rotating toward integrated service models that bundle consumables with uptime guarantees.
Microfluidic cartridge systems are automating pre-analytical sample processing steps that previously required trained laboratory technologists. Tertiary care networks in the United States and Germany are standardizing on these platforms to reduce operator-to-operator variability. The technology is automating quality control sequences that previously demanded dedicated full-time equivalents.
The EU In Vitro Diagnostic Regulation is mandating post-market surveillance systems with annual safety reporting cycles that exceed previous vigilance requirements. Manufacturers must now maintain qualified person roles for regulatory compliance that smaller entrants cannot resource. Blood gas and electrolyte testing segments face the steepest documentation burdens due to their highest-risk classification.
Health system procurement committees are consolidating vendor relationships under multi-year enterprise agreements that specify minimum reagent volume commitments. Traditional distributor networks in France and the United Kingdom are losing share to direct manufacturer contracts. This concentration is most visible in integrated delivery networks across Texas and California, where single-source agreements now cover eighty percent of point-of-care testing spend.
Critical Care Diagnostics Market Segmentation
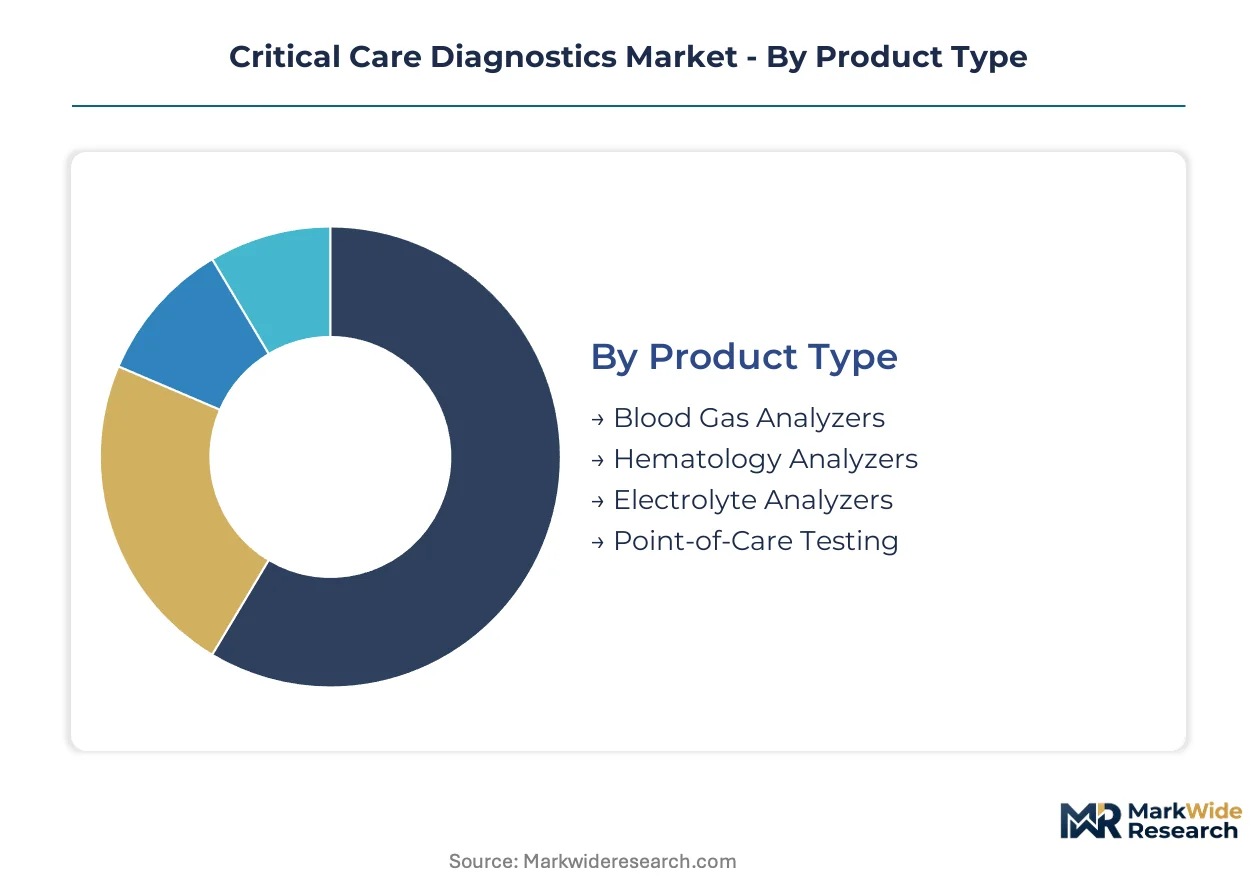
Critical care diagnostics segmentation reveals how procurement committees prioritize platform consolidation against specialized testing requirements. Upgrade cycles and replacement timelines vary dramatically across product architectures and care settings.
Product Type:
Replacement cycles for capital equipment accelerate as health networks consolidate vendor relationships under enterprise agreements.
- Blood Gas Analyzers:These systems measure pH, oxygen, and carbon dioxide levels in arterial blood samples with turnaround under two minutes. Demand concentrates in United States emergency departments where CMS quality metrics tie reimbursement to rapid acid-base assessment. The upgrade cycle shortens as integrated delivery networks standardize on single-vendor platforms.
- Hematology Analyzers:Automated cell counters process complete blood counts with differential analysis for coagulation monitoring. Hospital laboratories in Germany and Japan drive replacement demand toward AI-augmented morphological classification capabilities. Regulatory pressure from EU MDR documentation burdens favors established technical infrastructures.
- Electrolyte Analyzers:Ion-selective electrode systems quantify sodium, potassium, and chloride concentrations.
- Point-of-Care Testing:CLIA-waived cartridge platforms enable non-laboratory personnel to perform critical assays at the bedside.
Volume placements concentrate in Blood Gas Analyzers; the faster expansion belongs to Point-of-Care Testing.
Technology:
Cost tier differentiation separates premium precision platforms from standardized workflow solutions.
- Electrochemical:Ion-selective and amperometric sensors dominate blood gas and electrolyte measurement with minimal maintenance requirements. United States hospital procurement committees favor these systems for their predictable total cost-of-ownership calculations. The technology anchors mid-tier pricing in saturated installed bases.
- Mass Spectrometry:Benchtop systems now deliver metabolite profiling from single sample inputs previously requiring multi-instrument workflows. Tertiary care networks in Germany adopt these platforms for sepsis biomarker panels. Miniaturization trends compress capital expenditure thresholds for mid-sized laboratories.
- Colorimetric:Enzymatic reaction detection provides cost-effective chemistry analysis for routine panels.
- Fluorescence:Immunoassay platforms face substitution pressure from molecular amplification methods in respiratory pathogen detection.
Electrochemical systems maintain the largest installed base; Mass Spectrometry is climbing the fastest among capital investments.
Application:
Application segmentation tracks mortality reduction mandates that shape institutional procurement priorities.
- Sepsis:Rapid pathogen identification systems compress turnaround from positive blood culture to species-level diagnosis. United States hospitals face CMS quality metrics that tie reimbursement to time-to-appropriate-antibiotic administration. The application commands disproportionate investment attention relative to test volume.
- Cardiac Care:Troponin and natriuretic peptide testing guides acute coronary syndrome and heart failure management. Emergency departments in Texas and California integrated delivery networks standardize on high-sensitivity assays. Reagent volume commitments dominate enterprise agreement negotiations.
- Respiratory:Blood gas and ventilator-associated panel testing supports mechanical ventilation management.
- Neurology:Cerebrospinal fluid analysis and therapeutic drug monitoring serve intensive care settings.
Cardiac Care generates the highest test frequency; Sepsis platforms are gaining share fastest on mortality reduction incentives.
End User:
Customer type segmentation reflects divergent uptime requirements and operator competency levels.
- Hospitals:Integrated delivery networks consolidate point-of-care testing under centralized laboratory governance with predictive service contracts. United States health systems in California and Texas now cover eighty percent of spend through single-source agreements. Procurement committees prioritize platform interoperability with existing laboratory information systems.
- Diagnostic Laboratories:Reference laboratories process high-complexity panels requiring specialized technologist certification. Germany and Japan maintain concentrated supplier relationships for specialty chemistries and calibration materials. EU MDR post-market surveillance obligations favor established regulatory affairs infrastructure.
- Emergency Medical Services:Pre-hospital testing requires ruggedized portable platforms with simplified operator interfaces.
- Home Healthcare:Remote monitoring applications expand for chronic disease management outside acute settings.
Hospital placements dominate capital equipment volume; Emergency Medical Services represents the steepest expansion trajectory as pre-hospital networks upgrade capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and Japan for specialty chemistries and calibration materials, while consumption tilts toward the United States where integrated health networks consolidate procurement under centralized contracts.
United States
Emergency departments in Texas and California are standardizing point-of-care testing platforms under single-source agreements covering eighty percent of spend. FDA premarket notification pathways and CLIA-waived test expansion accelerate deployment timelines for moderate-complexity devices. The Greater Boston cluster anchors reference laboratory processing for high-complexity sepsis biomarker panels.
Germany
Tertiary care networks drive replacement demand toward AI-augmented hematology analyzers with automated morphological classification. EU MDR documentation burdens favor established players with dedicated regulatory affairs infrastructure. The Munich-Stuttgart corridor concentrates mass spectrometry miniaturization R&D for benchtop metabolite profiling systems.
Japan
Hospital laboratories maintain concentrated supplier relationships for ion-selective electrode systems and electrochemical sensors. PMDA consultation procedures shape analytical validation standards for novel biomarker panels. The Osaka-Kobe industrial zone anchors production of fluorescent immunoassay components facing substitution pressure from molecular methods.
India
District hospital tiers present first-mover opportunities under the PLI scheme incentivizing domestic blood gas analyzer manufacturing. CDSCO medical device rules govern import licensing for critical care platforms. The Maharashtra-Gujarat corridor is consolidating contract manufacturing for cartridge-based point-of-care systems.
United Kingdom
Integrated care systems are migrating laboratory procurement from traditional distributor networks toward direct manufacturer contracts. MHRA post-market surveillance aligns with EU MDR vigilance requirements for high-risk device classifications. The Cambridge-London corridor concentrates digital pathology integration with critical care diagnostics workflows.
Critical Care Diagnostics Market Competitive Landscape
Top-tier vendors anchor enterprise service contracts with predictive uptime guarantees, while mid-tier specialists compete on modular flexibility and reagent bundling. The vendor base stratifies across three archetypes: diversified conglomerates with extensive service networks, precision-focused instrument manufacturers, and consumable-centric suppliers with tiered pricing structures. M&A activity targets regulatory affairs infrastructure and remote monitoring platform capabilities. Geographic expansion into India's district hospital tier is accelerating under production-linked incentive schemes.
Among diversified health technology conglomerates, Abbott Laboratories, Siemens Healthineers, and Danaher Corporation occupy positions defined by recurring revenue architectures. Abbott leverages extensive service networks to lock in long-term hospital contracts. Siemens anchors market presence through cloud-connected predictive maintenance platforms. Danaher competes via consumable reorder bundling that reduces total cost-of-ownership calculations for procurement committees. These three exemplify the shift from capital equipment sales toward software-defined subscription models.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Siemens Healthineers |
| F. Hoffmann-La Roche Ltd |
| Danaher Corporation |
| bioMérieux |
| Becton, Dickinson and Company |
| Sysmex Corporation |
| Thermo Fisher Scientific |
| Bayer AG |
| Others |
Value Network & Pricing Analysis
Mass spectrometry miniaturization is compressing capital expenditure thresholds while simultaneously concentrating production among German and Japanese precision optics suppliers, creating asymmetric pricing power for component vendors and forcing downstream manufacturers into long-term offtake commitments to secure allocation.
Pricing Analysis
Margin tightening in mid-tier electrochemical systems reflects procurement committee consolidation under enterprise agreements with minimum reagent volume commitments. The dominant pricing structure is contract-based long-term offtake bundled with predictive service subscriptions. Price differentiation separates FDA-cleared platforms from CLIA-waived bedside devices, with brand premium and after-sales uptime guarantees as secondary drivers. Cost-down pressure on cartridge-based point-of-care platforms accelerates as integrated delivery networks standardize on single-vendor footprints. Diagnostic laboratories in Germany and Japan exhibit lowest price sensitivity due to regulatory compliance requirements, while India's district hospital tier demonstrates highest sensitivity to total cost-of-ownership calculations.
Supply Chain Analysis
Dual-sourcing requirements for ion-selective electrode membranes and fluorescent immunoassay components mandate multi-supplier qualification across German, Japanese, and select United States specialty chemical producers. Raw material dependencies center on precision-machined sensor substrates, calibration-grade reference gases, and high-purity reagent chemistries. Supply chain risk traces to single-source vulnerability for PMDA-validated reference materials used in Japanese laboratory accreditation. Distribution runs through direct manufacturer contracts displacing traditional distributor networks in France and the United Kingdom, with health system procurement committees consolidating eighty percent of point-of-care testing spend under centralized governance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR documentation burdens are forcing weaker regulatory affairs teams toward exit, consolidating competitive positions among established technical infrastructures with dedicated qualified person roles.
For Market Incumbents: Anchor enterprise service contracts with predictive uptime guarantees tied to cloud-connected platforms, displacing break-fix maintenance models that smaller competitors cannot resource. Deepen backward integration into specialty reagent manufacturing to reduce exposure to German and Japanese supply concentration. Lock in long-term hospital contracts through consumable reorder bundling that raises switching costs for procurement committees evaluating modular alternatives. For New Entrants and Emerging Players: The price-point gap between premium mass spectrometry platforms and economy-tier lateral flow devices creates entry space for benchtop metabolite profiling systems targeting mid-sized United States laboratories. Target India's district hospital tier under PLI scheme incentives for domestic blood gas analyzer manufacturing, where first-mover advantages remain unclaimed. Deploy CLIA-waived cartridge platforms with simplified operator interfaces to penetrate urgent care settings outside centralized laboratory governance. For Investors and Strategic Acquirers: Exit pathways concentrate in regulatory affairs infrastructure acquisitions, as EU MDR post-market surveillance obligations favor established technical documentation capabilities. Long-term viability over the projection horizon hinges on recurring revenue architectures displacing capital equipment sales. Monitor CMS quality metric expansions beyond sepsis and cardiac care as the inflection signal for platform consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Upgrade | Post-market surveillance systems with annual safety reporting cycles exceed previous vigilance requirements for blood gas classifications. |
| AI-Augmented Hematology Platform Launch | Machine learning integration automates morphological classification, reducing specialist pathologist dependency in resource-constrained settings. |
| Remote Monitoring Service Contract Expansion | Predictive uptime guarantees tied to cloud-connected platforms displace break-fix maintenance models across integrated delivery networks. |
| India PLI Scheme Manufacturing Footprint | Domestic blood gas analyzer production creates first-mover advantages in underpenetrated secondary care networks. |
| Mass Spectrometry Miniaturization R&D | Benchtop systems deliver metabolite profiling from single sample inputs, compressing capital expenditure thresholds for mid-sized laboratories. |
Research Methodology
FDA 510(k) premarket notification databases, CMS Medicare reimbursement schedules, and EU MDR technical documentation filings formed the secondary backbone, cross-referenced with primary interviews involving hospital laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads at IVD manufacturers. Bottom-up triangulation against top-down spending analysis validated segment-level estimates across product architectures and care settings.
Historical trendline analysis of replacement cycles and upgrade patterns informed the projection framework across the analysis window, with segmentation modeling covering technology platforms, application areas, end-user categories, and regional regulatory clusters. CAGRs were derived from installed base evolution and consumable attach rate trajectories, incorporating sepsis mortality reduction mandates and CLIA-waived test expansion as demand-side inputs.
Underlying measurement precision varies by segment; blood gas and electrolyte testing carry tighter precision than emerging mass spectrometry applications due to established regulatory pathways. Forecasts reflect assumptions about health network consolidation velocity and reagent supply stability. Deviation in EU MDR enforcement timelines or PMDA consultation backlogs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Urinalysis Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Global Hemostasis Diagnostics Market
Diagnostics
India in-Vitro Diagnostics Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
Fructosamine Reagents Market
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
Multiplex Molecular Diagnostics Market
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
Global Chlamydia Infection Diagnostics Market