
 Asia-Pacific Ovarian Cancer Diagnostics Market | 2026-2036
Asia-Pacific Ovarian Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ovarian Cancer Diagnostics Market Outlook
Japanese reagent manufacturers is shifting toward polymerase chain reaction-based ovarian cancer panels to serve domestic hospital networks. F. Hoffmann-La Roche Ltd. anchors its Asia-Pacific diagnostics franchise through centralized laboratory partnerships in Australia and South Korea. Thermo Fisher Scientific Inc. extends its regional footprint via localized production of next-generation sequencing consumables. Illumina Inc. competes on instrument placement density across Singaporean and Taiwanese clinical genomics hubs.
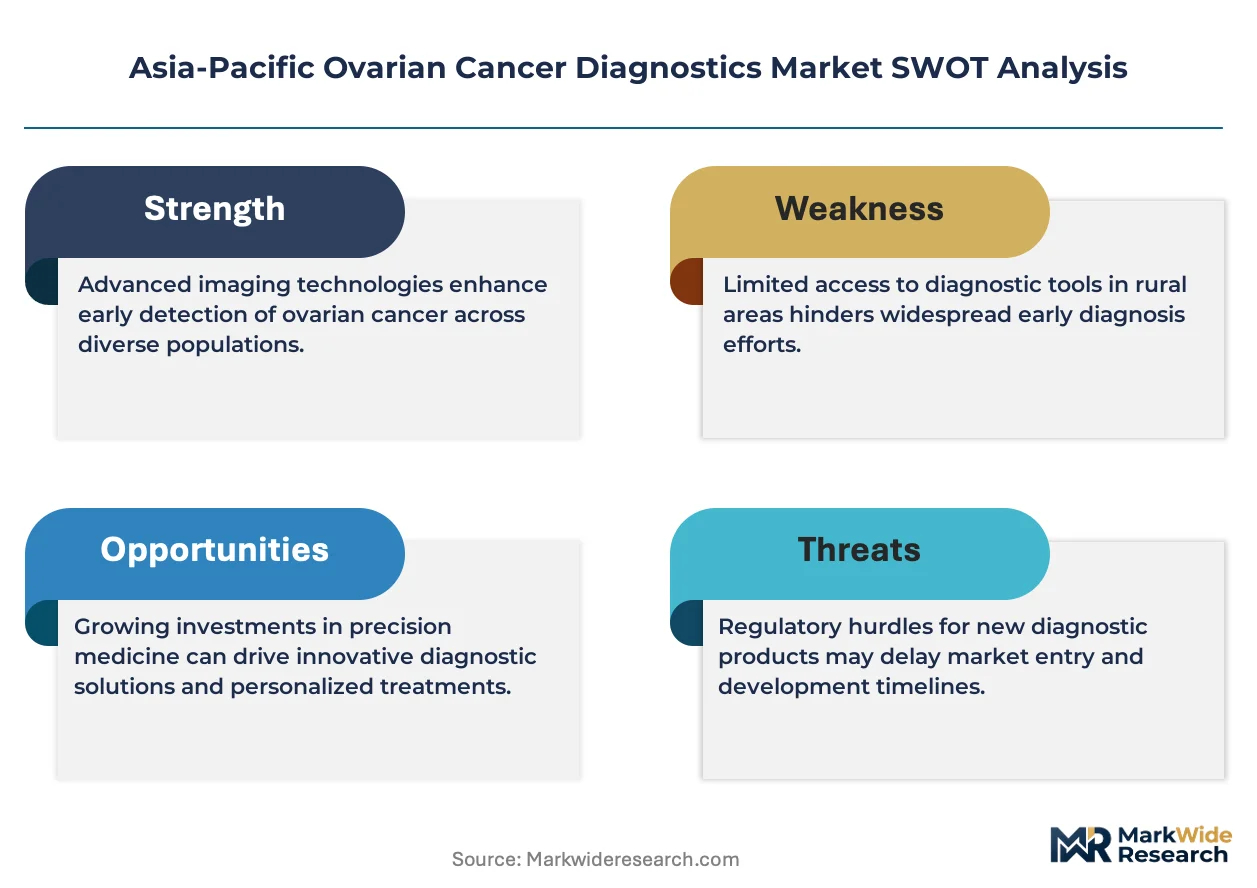
Ovarian cancer diagnostics encompasses imaging, biomarker analysis, genetic profiling, and ultrasound modalities used to detect, classify, and monitor epithelial ovarian tumors. Molecular diagnostics platforms sequence BRCA1/2 and other susceptibility genes to stratify hereditary risk and guide PARP inhibitor eligibility in precision oncology workflows. Biomarker testing currently leads clinical adoption because CA-125 and HE4 assays integrate into routine gynecologic surveillance with lower capital requirements than imaging systems. Genetic testing represents the fastest-expanding segment as Asian health systems build hereditary cancer screening programs and oncologists demand pharmacogenomic data for therapy selection.
Japan's PMDA regulates in vitro diagnostic reagents under the Pharmaceutical and Medical Device Act, mandating clinical performance documentation that shapes product development timelines for entrants. Australia's TGA aligns with EU IVDR convergence timelines, creating dual-compliance burdens for multinational suppliers seeking Asia-Pacific market access. China's NMPA revised its innovative medical device approval channel to include companion diagnostics, accelerating registration for biomarker-linked assays. Stakeholders must monitor harmonization gaps between national regulatory frameworks as cross-border laboratory networks expand reference testing across the region.
Market Dynamics
Japan's PMDA accelerated approval pathways for companion diagnostics are compressing product development cycles and reshaping competitive entry timing across Asia-Pacific molecular diagnostics. This regulatory velocity is forcing manufacturers to front-load clinical validation investments while creating first-mover advantages for biomarker assay developers.
Growth Catalysts
- Hereditary screening mandates:China's NMPA innovative device channel now explicitly includes companion diagnostics, accelerating registration timelines for BRCA-linked assays. Provincial health commissions in Guangdong and Jiangsu are funding population-level genetic screening pilots.
- PARP inhibitor eligibility protocols:Oncology departments across Australia's centralized cancer centers are embedding germline mutation testing into first-line treatment workflows. This creates pull-through demand for sequencing consumables.
- Centralized laboratory networks:Singapore's clinical genomics hubs are consolidating reference testing volumes, achieving instrument placement density that supports next-generation sequencing panel economics. This infrastructure concentration lowers per-test costs for hospital networks.
Market Restraints
- Reagent import dependency:Southeast Asian hospital laboratories rely on cold-chain logistics for polymerase chain reaction master mixes, exposing operations to shipping disruptions and currency volatility against the US dollar.
- Specialist pathologist scarcity:Molecular tumor board interpretation requires dual-trained gynecologic oncologists and genomic counselors, a credential combination concentrated in Tokyo, Seoul, and Sydney metropolitan clusters.
- Capital intensity of imaging systems:Magnetic resonance imaging and positron emission tomography platforms for ovarian lesion characterization require dedicated radiopharmaceutical production facilities, limiting deployment to tertiary referral centers.
Strategic Opportunities
- Indonesia's diagnostic gap:Java's private hospital chains are building captive laboratory capacity to serve uninsured patient segments, creating demand for mid-throughput immunoassay analyzers with lower capital requirements than sequencing platforms.
- Thailand's medical tourism pivot:Bangkok's international hospitals are marketing comprehensive cancer screening packages to regional high-net-worth individuals, bundling CA-125 testing with transvaginal ultrasound and genetic counseling.
- Cross-border telepathology:Taiwanese digital pathology platforms are enabling remote immunohistochemistry interpretation for Philippine provincial hospitals, circumventing local specialist shortages through real-time consultation networks.
Industry Challenges
- Multi-jurisdiction quality certification:Reagent manufacturers must simultaneously maintain TGA alignment with EU IVDR, PMDA Pharmaceutical and Medical Device Act documentation, and NMPA innovative channel requirements, fragmenting regulatory affairs staffing.
- Liquid biopsy assay standardization:Circulating tumor DNA detection sensitivity varies across pre-analytical workflows, complicating multi-site clinical trials and delaying biomarker validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ovarian Cancer Diagnostics Market |
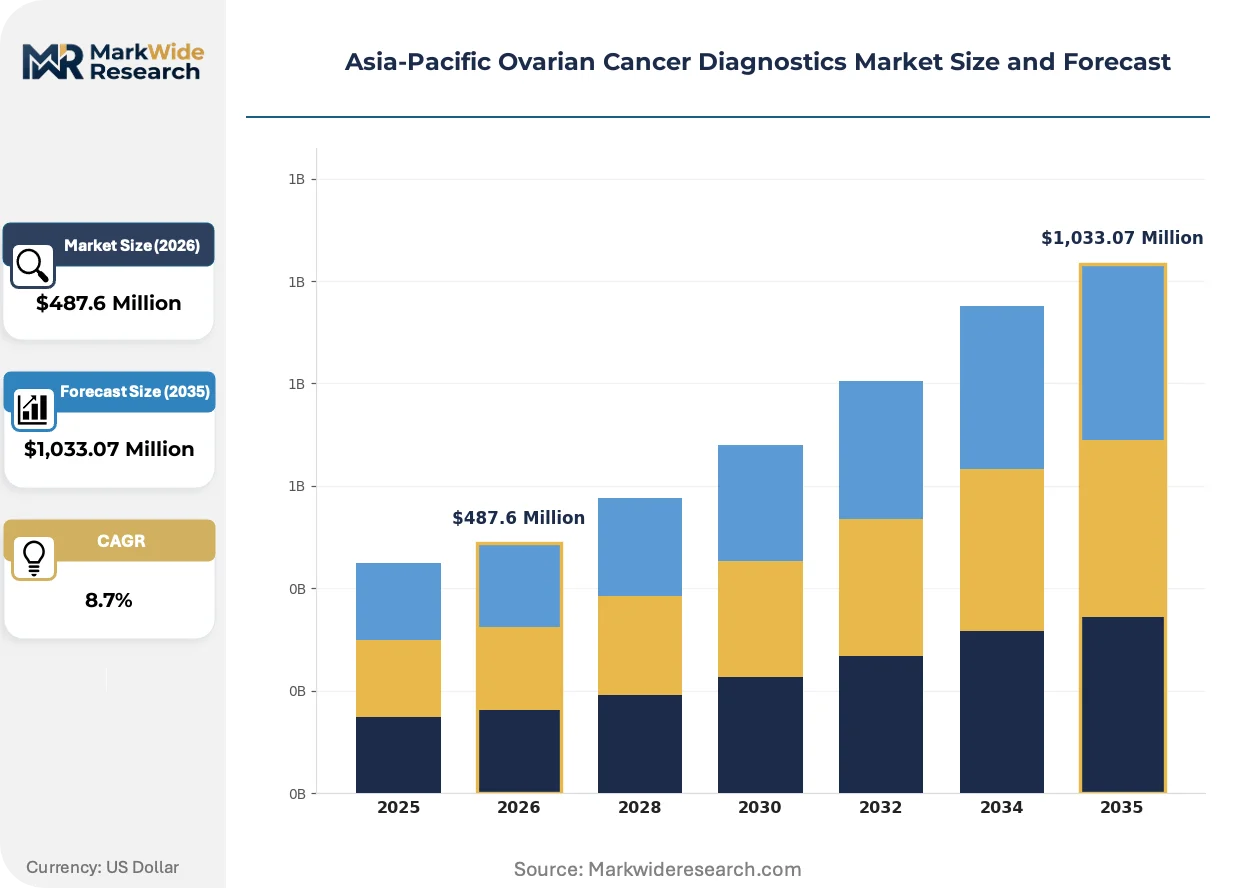
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Tests, Biomarkers, Genetic Testing, Ultrasound Technology: Molecular Diagnostics, Immunohistochemistry, Radiology, PCR End User: Research Laboratories, Hospitals, Diagnostic Centers, Clinics Application: Screening, Diagnosis, Monitoring, Prognosis |
| Companies Covered | AstraZeneca, Thermo Fisher Scientific Inc., F. Hoffmann-La Roche Ltd., GE HealthCare Technologies Inc., Abbott Laboratories, Eli Lilly and Company, GlaxoSmithKline Plc, Illumina Inc., Bristol-Myers Squibb Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ovarian Cancer Diagnostics Market Strategic Shifts
Asia-Pacific ovarian cancer diagnostics is experiencing platform convergence between imaging and molecular modalities, with artificial intelligence-assisted ultrasound interpretation emerging alongside expanded genetic testing menus. This dual trajectory is compressing diagnostic timelines while fragmenting vendor competitive positions.
Next-generation sequencing-based multi-gene panels are expanding into routine gynecologic surveillance workflows across South Korean university hospitals. Seoul National University Hospital and Asan Medical Center have embedded BRCA1/2 plus homologous recombination deficiency testing into platinum-sensitive recurrence protocols. This platform shift is expanding into community oncology settings as regional reference laboratories achieve College of American Pathologists-equivalent accreditation.
Australia's TGA alignment with EU IVDR convergence timelines is extending compliance documentation requirements for multinational reagent suppliers. Dual-framework obligations are compressing product launch windows and favoring established registrants with dedicated regulatory affairs infrastructure. In vitro diagnostic manufacturers with existing European notified body relationships are responding by prioritizing Australian market entry ahead of Southeast Asian expansion.
Hospital procurement committees across China's tier-one cities are consolidating vendor relationships for imaging and molecular diagnostics into single-source framework agreements. This concentration is displacing fragmented purchasing across departmental silos and favoring suppliers with comprehensive platform portfolios. Beijing and Shanghai municipal health commissions are most visible in this consolidation, with standardized equipment specifications reducing site-by-site negotiation overhead.
Asia-Pacific Ovarian Cancer Diagnostics Market Segmentation
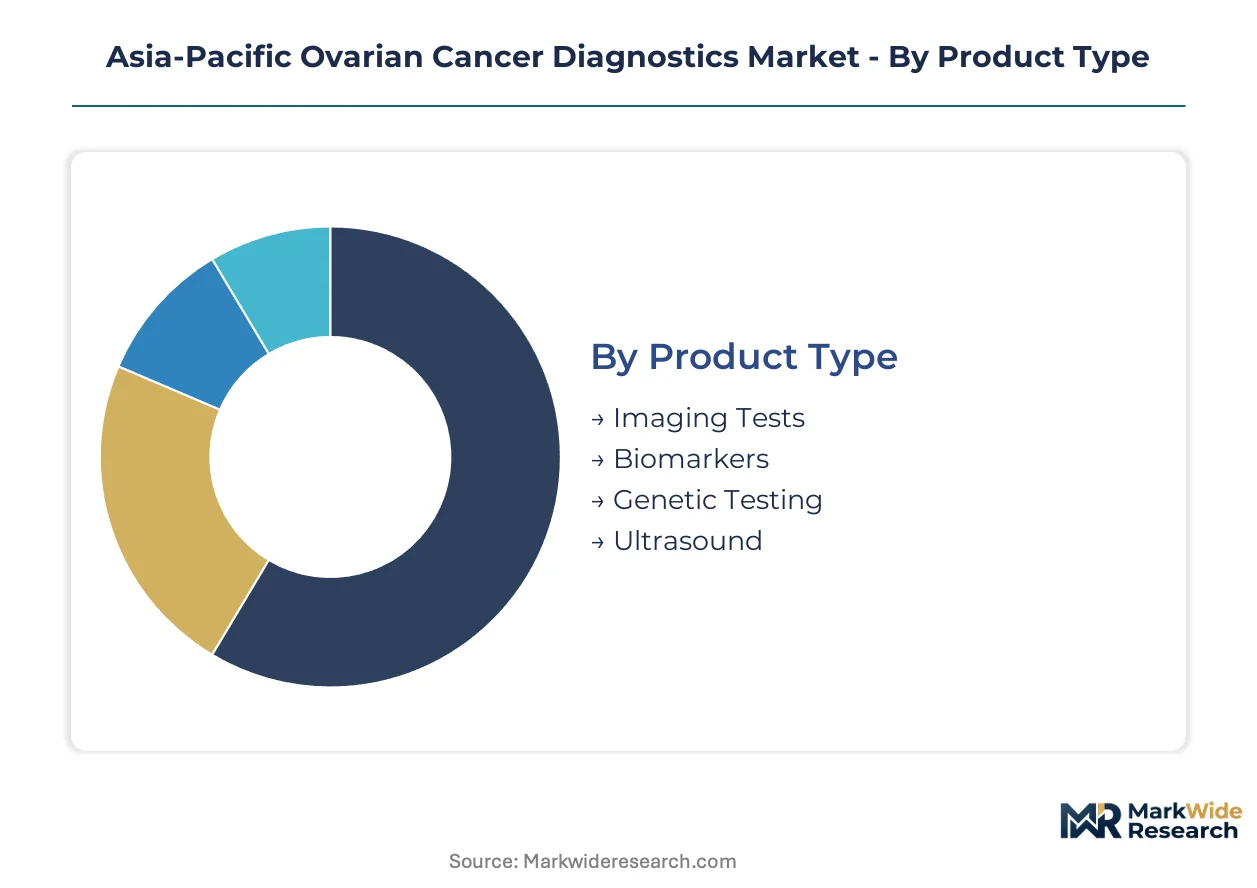
Diagnostic platform selection across Asia-Pacific reflects divergent capital availability, specialist density, and reimbursement structures. Segmentation reveals how tier-one cities concentrate molecular testing while provincial markets sustain imaging and biomarker workflows.
Product Type:
Capital intensity and reimbursement tiers separate buyers into high-investment sequencing platforms versus lower-barrier immunoassay systems.
- Imaging Tests:Magnetic resonance imaging and positron emission tomography platforms characterize ovarian lesions through radiopharmaceutical uptake patterns and tissue contrast differentiation. Australia's centralized cancer centers in Sydney and Melbourne deploy these systems for platinum-sensitive recurrence staging, constrained by dedicated cyclotron facility requirements that limit provincial hospital access.
- Biomarkers:Serum protein assays measuring CA-125 and HE4 concentrations require minimal capital expenditure and integrate into routine gynecologic surveillance protocols. China's tier-one municipal hospitals process the highest assay volumes through automated immunoassay analyzers, driven by provincial health commission screening mandates in Guangdong and Jiangsu.
- Genetic Testing:Next-generation sequencing panels for BRCA1/2 and homologous recombination deficiency stratification.
- Ultrasound:Transvaginal sonography with Doppler flow assessment for adnexal mass characterization.
Biomarker testing leads volumes today; genetic testing is gaining share fastest.
Technology:
Workflow automation requirements and interpretive complexity distinguish laboratory infrastructure tiers across the region.
- Molecular Diagnostics:Automated nucleic acid extraction and sequencing platforms enable multi-gene panel analysis with standardized bioinformatics pipelines. Singapore's clinical genomics hubs achieve instrument placement density that supports next-generation sequencing economics, consolidating reference testing volumes from Malaysian and Indonesian hospital networks.
- PCR:Polymerase chain reaction-based ovarian cancer panels deliver rapid turnaround for BRCA mutation screening with lower per-sample costs than comprehensive sequencing. Japanese reagent manufacturers are shifting domestic production toward these assays to serve hospital networks under PMDA Pharmaceutical and Medical Device Act compliance timelines.
- Immunohistochemistry:Antibody-based protein expression profiling for tumor subtype classification.
- Radiology:Computed tomography and magnetic resonance imaging interpretation for metastatic staging.
PCR dominates installed base; molecular diagnostics shows steepest expansion trajectory.
End User:
Patient volume concentration and specialist availability determine procurement authority and platform selection criteria.
- Hospitals:Tertiary referral centers with gynecologic oncology departments consolidate imaging, biomarker, and genetic testing capabilities under single-site frameworks. Seoul National University Hospital and Asan Medical Center embed homologous recombination deficiency testing into treatment protocols, creating template workflows for South Korean community oncology expansion.
- Diagnostic Centers:Independent reference laboratories achieve scale economics through multi-hospital specimen consolidation. Bangkok's private laboratory chains serving medical tourism markets bundle CA-125 testing with transvaginal ultrasound and genetic counseling for regional high-net-worth patient segments.
- Research Laboratories:Academic medical centers conducting biomarker validation and clinical trial specimen analysis.
- Clinics:Community gynecology practices performing initial screening and referral coordination.
Hospitals capture the majority of value; diagnostic centers are expanding most quickly.
Application:
Clinical utility and reimbursement coding separate preventive screening from therapeutic decision-support testing.
- Diagnosis:Definitive characterization of adnexal masses through multimodal imaging and tissue biopsy analysis. Japan's PMDA accelerated approval pathways for companion diagnostics are compressing biomarker assay validation timelines, enabling faster integration of predictive testing into first-line treatment selection.
- Monitoring:Serial biomarker measurement and imaging surveillance for recurrence detection post-primary therapy. Australia's oncology departments embed germline mutation tracking into platinum-sensitive recurrence protocols, sustaining consumable demand for sequencing platforms.
- Screening:Population-level asymptomatic detection through serum biomarker and ultrasound protocols.
- Prognosis:Risk stratification for survival outcomes based on molecular subtype and treatment response markers.
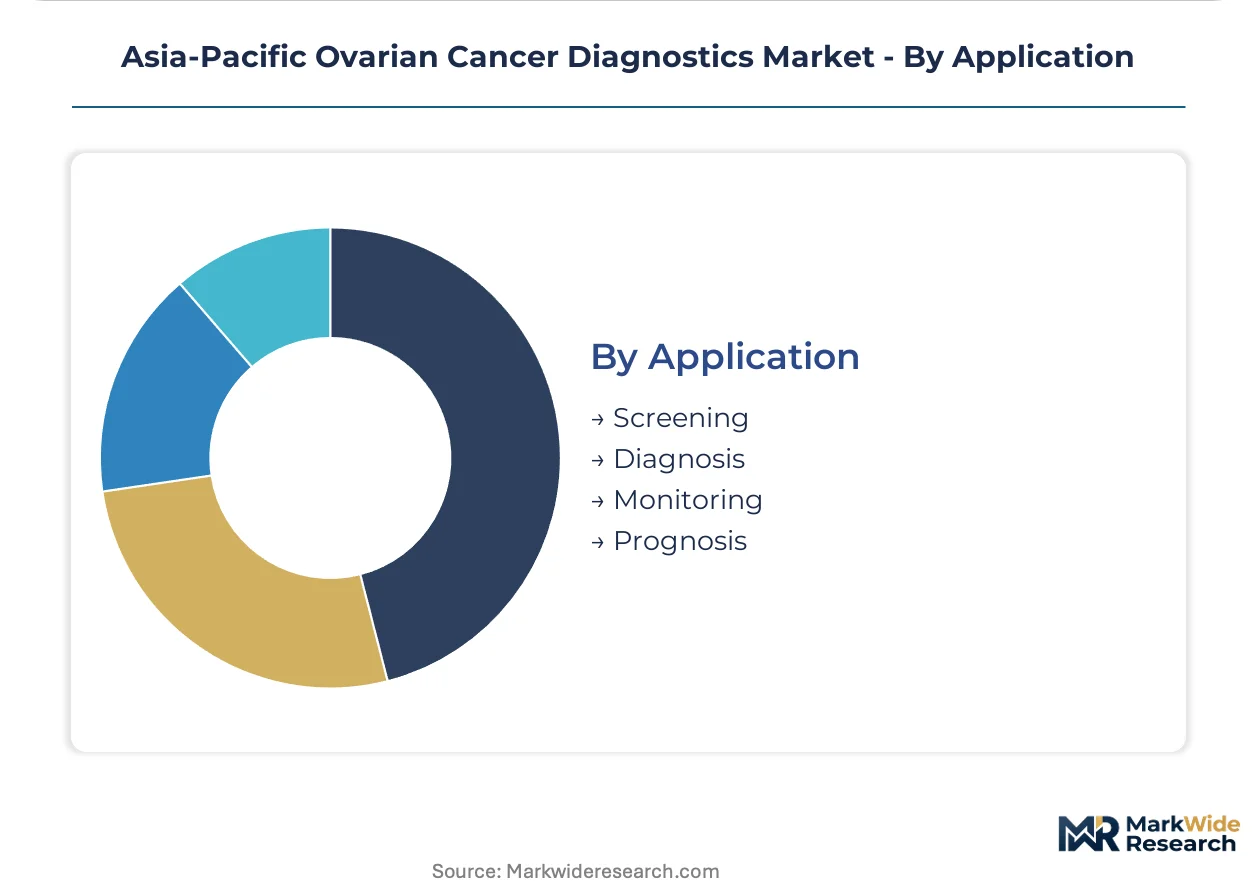
Diagnosis commands current spending; monitoring is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting diagnostic reagent production toward jurisdictions with streamlined approval pathways. PMDA's accelerated companion diagnostic channel and NMPA's innovative device designation create compliance-cost differentials that manufacturers exploit through localized manufacturing strategies.
China
Centralized cancer centers in Beijing and Shanghai drive imaging and genetic testing volumes through municipal procurement frameworks. NMPA's innovative medical device approval channel explicitly includes companion diagnostics, compressing registration timelines for BRCA-linked assays. Guangdong and Jiangsu provincial health commissions fund population-level genetic screening pilots that expand molecular diagnostic adoption.
Japan
Domestic hospital networks sustain demand for polymerase chain reaction-based ovarian cancer panels with rapid turnaround requirements. PMDA regulates in vitro diagnostic reagents under the Pharmaceutical and Medical Device Act, mandating clinical performance documentation that shapes product development timelines. Tokyo metropolitan clusters concentrate dual-trained gynecologic oncologists and genomic counselors capable of molecular tumor board interpretation.
Australia
Sydney and Melbourne centralized cancer centers deploy magnetic resonance imaging and positron emission tomography platforms for platinum-sensitive recurrence staging. TGA alignment with EU IVDR convergence timelines extends compliance documentation requirements, favoring established registrants with dedicated regulatory affairs infrastructure. Germline mutation testing embeds into first-line treatment workflows, creating pull-through demand for sequencing consumables.
South Korea
Seoul National University Hospital and Asan Medical Center have embedded BRCA1/2 plus homologous recombination deficiency testing into platinum-sensitive recurrence protocols. MFDS regulatory frameworks support regional reference laboratories achieving College of American Pathologists-equivalent accreditation. This platform shift expands into community oncology settings as standardized workflows reduce interpretive complexity.
Singapore
Clinical genomics hubs consolidate reference testing volumes from Malaysian and Indonesian hospital networks, achieving instrument placement density that supports next-generation sequencing panel economics. The city-state's procurement committees favor suppliers with comprehensive platform portfolios spanning imaging and molecular modalities. Cross-border specimen logistics leverage Singapore's cold-chain infrastructure to serve Southeast Asian markets with reagent import dependencies.
Asia-Pacific Ovarian Cancer Diagnostics Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue point-of-care and decentralized testing configurations. The market structures around three tiers: multinational conglomerates with centralized laboratory partnerships, regional reagent manufacturers with PMDA-compliant domestic production, and specialized genomics platforms competing on bioinformatics differentiation. Consolidation pressure intensifies as hospital procurement committees in China's tier-one cities migrate toward single-source framework agreements. Dominant competitive moves include strategic partnerships with academic medical centers for clinical validation and geographic expansion through reference laboratory network consolidation.
Within the multinational tier, F. Hoffmann-La Roche Ltd. and Thermo Fisher Scientific Inc. exemplify archetypes built on centralized laboratory partnerships and localized consumable production respectively. Illumina Inc. occupies a position defined by instrument placement density across clinical genomics hubs. These entities represent competitive anchors rather than exhaustive market coverage, with their positioning reflecting broader patterns of platform consolidation and regional manufacturing investment visible across the Asia-Pacific diagnostics sector.
| Leading Market Players |
|---|
| AstraZeneca |
| Thermo Fisher Scientific Inc. |
| F. Hoffmann-La Roche Ltd. |
| GE HealthCare Technologies Inc. |
| Abbott Laboratories |
| Eli Lilly and Company |
| GlaxoSmithKline Plc |
| Illumina Inc. |
| Bristol-Myers Squibb Company |
| Others |
Value Chain & Pricing Dynamics
China's tier-one municipal hospital procurement committees concentrate purchasing authority for imaging and molecular diagnostics platforms, compressing vendor margins through single-source framework agreements that favor comprehensive platform portfolios over point solutions.
Pricing Analysis
Distributor margins for reagent kits vary by cold-chain handling requirements and regulatory documentation tiers. Three-tier pricing structure across premium, standard, and economy levels separates CAP-accredited reference laboratories from provincial hospital networks and uninsured patient segments in Indonesia. Cost compression in PCR master mixes is intensifying because Japanese reagent manufacturers are shifting domestic production toward localized panel assembly. Provincial hospital laboratories exhibit highest price sensitivity; Singaporean clinical genomics hubs demonstrate lowest due to consolidated specimen volumes.
Supply Chain Analysis
Direct-to-hospital channels handle high-throughput sequencing platform demand from Australian centralized cancer centers and South Korean university hospitals. Reagent production concentrates in Japan, Singapore, and China. Supply chains draw from specialized enzyme manufacturers, fluorophore suppliers, and synthetic oligonucleotide providers. Single-source vulnerability persists for polymerase chain reaction thermostable enzymes sourced from specific biotech suppliers. Distribution runs through regional reference laboratory networks that consolidate specimens from Indonesian and Philippine provincial hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's PMDA accelerated approval pathways for companion diagnostics create a regulatory-cost differential against Australia's TGA-EU IVDR dual compliance burden, rewarding manufacturers who front-load clinical validation investments in Tokyo metropolitan clusters.
For Market Incumbents: Cement centralized laboratory partnerships in Australia and South Korea to lock in sequencing consumable demand before NMPA innovative channel registrations proliferate domestic Chinese competitors. Expand CAP-equivalent accreditation for regional reference laboratories to defend against emerging point-of-care molecular diagnostic entrants. Prioritize backward integration into reagent manufacturing to offset currency volatility against the US dollar for Southeast Asian cold-chain logistics. For New Entrants and Emerging Players: Begin with Indonesia's private hospital chains building captive laboratory capacity for uninsured patient segments, where mid-throughput immunoassay analyzers face lower capital barriers than sequencing platforms. Target Thailand's medical tourism market through Bangkok international hospitals bundling CA-125 testing with transvaginal ultrasound. Pursue cross-border telepathology partnerships with Taiwanese digital pathology platforms to circumvent specialist pathologist scarcity in Philippine provincial markets. For Investors and Strategic Acquirers: Multinational diagnostic conglomerates with established PMDA and NMPA regulatory affairs infrastructure are the most active acquirer in this space, seeking specialized genomics platforms with bioinformatics differentiation. The long-term viability window favors targets with College of American Pathologists-equivalent accreditation and instrument placement density in Singaporean clinical genomics hubs. Watch for NMPA innovative device designations for BRCA-linked companion diagnostics as an inflection indicator for molecular diagnostic platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Regulatory Approval Pathway | PMDA accelerated channels compress biomarker assay validation timelines for Tokyo hospital networks. |
| Hospital System Partnership | Seoul National University Hospital templates embed homologous recombination deficiency testing into community oncology workflows. |
| Software Companion Development | Artificial intelligence-assisted ultrasound interpretation converges imaging and molecular diagnostic platforms. |
| Reimbursement Strategy | Guangdong provincial health commission genetic screening pilots expand molecular diagnostic adoption through public funding. |
| Geographic Expansion | Singapore clinical genomics hubs consolidate Malaysian and Indonesian reference testing volumes through cold-chain infrastructure. |
Study Parameters
Direct dialogue with gynecologic oncologists, hospital procurement managers, biomedical engineers, and regulatory affairs specialists combined secondary validation through PMDA approval databases, NMPA innovative device registries, and Australian TGA conformity assessment documentation. Bottom-up and top-down triangulation cross-referenced hospital equipment procurement records with reagent import trade data and centralized cancer center capacity disclosures.
Bottom-up modeling segmented the market by diagnostic platform, technology workflow, end-user facility type, and clinical application across the analysis window. Top-down validation employed macroeconomic healthcare expenditure trends and oncology drug approval patterns to bound growth trajectories. CAGRs derived from instrument placement density economics, biomarker test volume elasticities, and PARP inhibitor eligibility protocol expansion rates.
Caveats apply where NMPA regulatory harmonization delays, liquid biopsy assay standardization failures, or specialist pathologist training bottlenecks could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Europe in Vitro Diagnostics (IVD) Market
Diagnostics
Melioidosis Diagnostic Market
Diagnostics
Global Kidney Cancer Diagnostics Market
Diagnostics
Veterinary Rapid Diagnostic Tests Market
Diagnostics
Global Lyme Disease Diagnostic Market
Diagnostics
Global Pelvic Floor Diagnostic Testing Market
Diagnostics
Animal Diagnostics Market
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market
Diagnostics
Paper Based Diagnostic Test Kits Market
Diagnostics
Diagnostic Reagents Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
In Vitro Diagnostic Substrate Market
Diagnostics
Europe Lung Cancer Diagnostics Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Preterm Birth Diagnostic Test Kits Market
Diagnostics
Glaucoma Diagnostics Market