
 South Asia Renewable Energy Market | 2026-2036
South Asia Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
South Asia Renewable Energy Market Analytics
Market Context
Multi-source equipment procurement is consolidating around domestic module manufacturers and regional EPC contractors. Adani Green Energy Limited anchors India's utility-scale pipeline through backward integration into solar cell production. Tata Power Solar Systems Ltd leverages its rooftop installation network to compete across the residential-commercial boundary. Suzlon Energy Ltd sustains wind turbine refurbishment demand despite solar's faster capacity additions.
Technical Definition and Structural Segments
South Asia renewable energy encompasses electricity generation from solar photovoltaics, onshore wind, run-of-river hydro, and agricultural biomass feedstocks, with photovoltaic systems typically deploying crystalline silicon modules at 18-22% conversion efficiency across tropical insolation zones of 4.5-6.5 kWh/m²/day. The technology serves grid decarbonization, rural electrification, and industrial cost hedging against volatile imported fuel prices. Solar dominates installed capacity across the region, while offshore wind represents the fastest-growing technology segment as Sri Lanka and India advance seabed lease frameworks. Agricultural end users command distinct margin pools through biomass cogeneration and solar-powered irrigation, though on-grid installations capture the largest absolute revenue share.
Regulatory Frame and Outlook
India's CEA mandates renewable purchase obligations for state distribution companies, while Bangladesh's Sustainable and Renewable Energy Development Authority sets feed-in tariff floors; both frameworks shape offtake certainty and project finance viability. Sri Lanka's PUCSL regulates grid access queues, creating interconnection bottlenecks that delay commercial operation dates. Stakeholders must monitor how India's PLI scheme revision affects module pricing and whether Pakistan's Nepra adjusts upfront tariffs to attract foreign equity.
Market Dynamics
India's PLI scheme revision is compressing module import dependency and forcing domestic cell-to-module integration across the solar value chain. Bangladeshi textile mills are accelerating direct renewable procurement to hedge volatile LNG import costs.
Growth Catalysts
- India's PLI scheme for solar manufacturing:Domestic cell and wafer production incentives are reducing import reliance for utility-scale developers. Module assembly lines in Gujarat and Tamil Nadu are scaling to capture the subsidy window.
- Bangladeshi textile sector power demand:Garment exporters facing RE100 commitments are contracting dedicated solar capacity through group captive structures. Dhaka-based spinning mills anchor this offtake segment.
- Sri Lanka seabed lease frameworks:Offshore wind development rights allocation is opening new capacity corridors along the Mannar and Pottuvil coastlines. The Ceylon Electricity Board is prioritizing these zones for grid evacuation planning.
Market Restraints
- Polysilicon supply concentration:Chinese ingot and wafer producers control upstream crystalline silicon feedstock. Indian module assemblers face margin compression when polysilium spot prices spike.
- Sri Lankan grid interconnection queues:PUCSL-regulated connection timelines stretch commercial operation dates by 18-24 months for solar and wind projects. Developer equity is locked in pre-revenue phases.
- Run-of-river hydro seasonality:Monsoon variability in Nepal and Bhutan limits capacity factors for Himalayan hydropower exports to India. Dry-season output gaps require thermal backup contracting.
Strategic Opportunities
- Pakistan distributed solar underpenetration:Nepra's net metering framework covers less than 2% of commercial rooftop potential. Karachi and Lahore industrial estates represent untapped aggregation targets for solar leasing models.
- Agricultural biomass cogeneration:Rice husk and bagasse-fired plants in Punjab and Sindh can displace diesel irrigation pumps. Sugar mill complexes offer captive feedstock and existing grid evacuation infrastructure.
- India-Green Hydrogen Mission convergence:Electrolyzer manufacturing incentives under the National Hydrogen Mission are creating demand anchors for renewable power purchase agreements. Gujarat and Rajasthan solar parks are positioning as hydrogen hub feedstock suppliers.
Industry Challenges
- Grid-code compliance for inverter synchronization:India's CEA technical standards for voltage ride-through and frequency response require specialized engineering talent. EPC contractors face certification delays and commissioning cost overruns.
- Land acquisition for utility-scale solar:Gujarat's Charanka and Bhadla park expansions encounter pastoralist displacement disputes and revenue record fragmentation. Developers absorb extended legal clearance timelines.
Report Scope
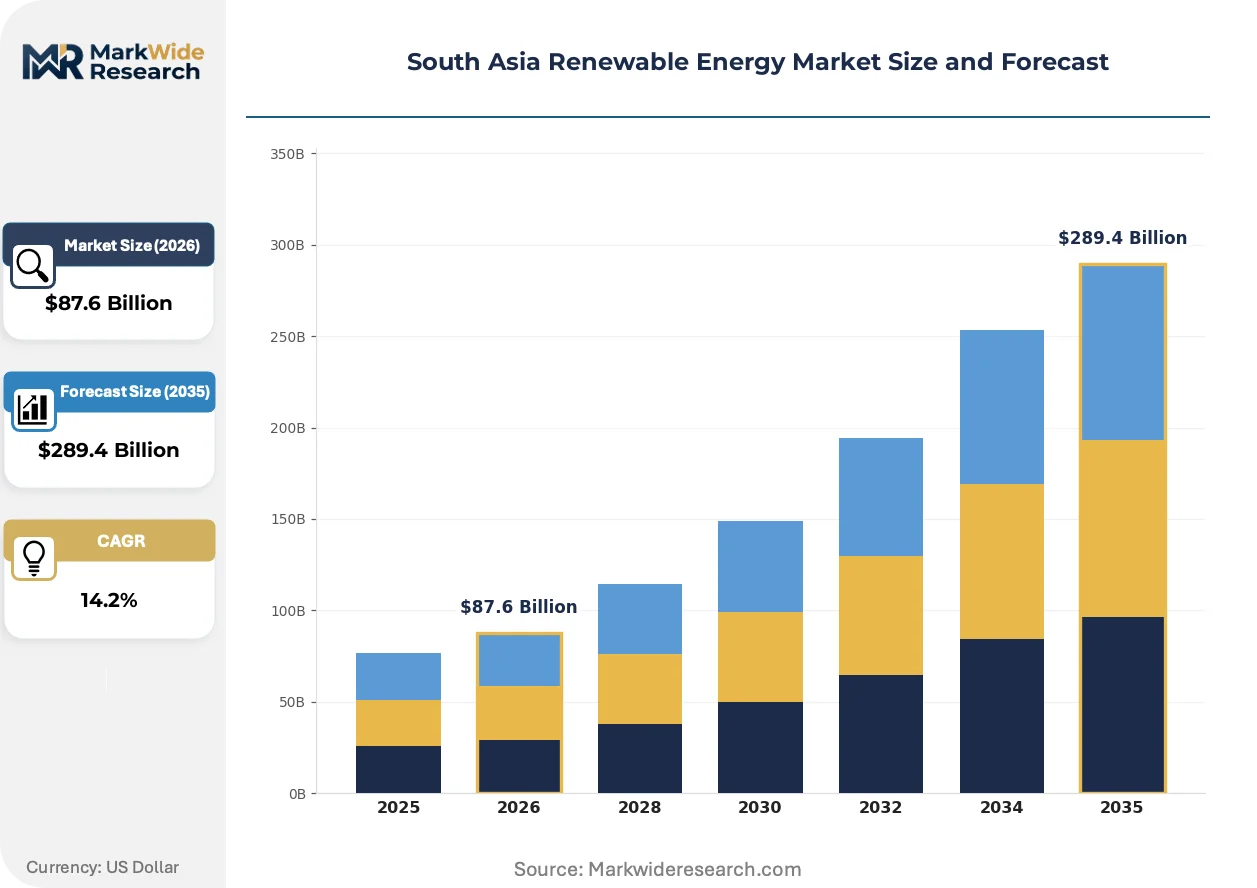
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Asia Renewable Energy Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar, Wind, Biomass, Hydro Technology: Photovoltaics, Concentrated Solar Power, Offshore Wind, Geothermal End User: Residential, Industrial, Commercial, Agricultural Installation: On-Grid, Off-Grid, Hybrid, Community |
| Companies Covered | Tata Power Solar Systems Ltd, Adani Green Energy Limited, ReNew Power Limited, Regen Renewables (Pvt) Ltd, Sindicatum Renewable Energy India Private Limited, Greenko Group Plc, Suzlon Energy Ltd, Sembcorp Industries Limited, ACME Solar Holding Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Asia Renewable Energy Market Evolving Landscape
Topcon and heterojunction cell architectures are reshaping module efficiency benchmarks across tropical high-insolation zones. Bangladesh and Pakistan are accelerating regulatory frameworks for wheeling and banking arrangements.
Topcon solar cells are overtaking PERC technology in Indian utility-scale procurement. Gujarat Solar Park developers are specifying 580W+ bifacial modules with 22.5% conversion efficiency. This cell architecture is compressing levelized cost thresholds for coal-displacement bids in CEA tenders.
Bangladesh's SREDA feed-in tariff revision is mandating domestic content ratios for solar projects above 10MW. The new framework requires 30% local sourcing for modules and 50% for balance-of-system components. Dhaka-based EPC firms are consolidating around regional inverter and mounting system suppliers to meet compliance.
Group captive power purchase agreements are displacing traditional utility offtake for Bangladeshi textile clusters. Narayanganj and Gazipur garment hubs are aggregating demand through special purpose vehicles to contract dedicated solar capacity. This procurement model is most visible in export-oriented spinning and dyeing units facing buyer-mandated renewable targets.
South Asia Renewable Energy Market Segmentation
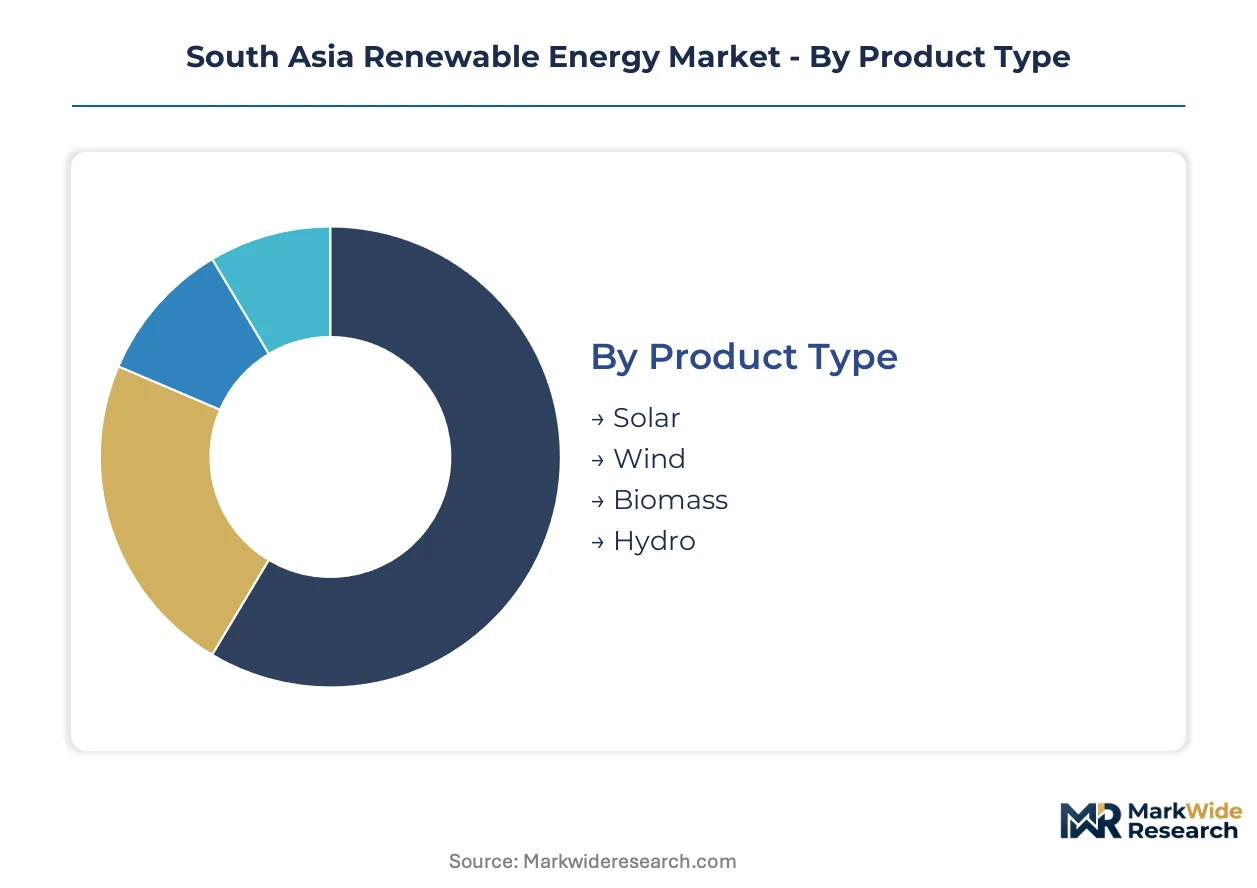
Segmentation reveals how technology cost curves and regulatory frameworks allocate capital across South Asia's renewable buildout. Understanding these divisions exposes where module manufacturing incentives, textile sector procurement, and agricultural electrification programs concentrate returns.
Product Type:
Supply concentration in crystalline silicon manufacturing tilts procurement toward solar across Bangladeshi textile clusters and Indian utility-scale tenders.
- Solar:Crystalline silicon modules at 18-22% conversion efficiency dominate procurement volumes. Gujarat's solar parks anchor regional deployment, while Bangladeshi garment exporters contract dedicated capacity through group captive structures to meet RE100 commitments.
- Wind:Onshore turbines sustain refurbishment demand in Tamil Nadu and Karnataka corridors despite solar's faster capacity additions. Suzlon Energy's domestic nacelle assembly captures recurring maintenance revenue from aging installations.
- Biomass:Rice husk and bagasse cogeneration displaces diesel irrigation pumps across Punjab and Sindh sugar mill complexes.
- Hydro:Run-of-river installations in Nepal and Bhutan face monsoon variability that limits dry-season export capacity to Indian grids.
Today's leader: Solar. Tomorrow's challenger: Wind.
Technology:
Cost tier differentiation separates mass-deployed photovoltaics from capital-intensive concentrated solar and offshore alternatives.
- Photovoltaics:Topcon and heterojunction cell architectures are displacing PERC benchmarks across tropical high-insolation zones. Indian utility-scale developers now specify 580W+ bifacial modules with 22.5% conversion efficiency.
- Concentrated Solar Power:Thermal storage integration suits Rajasthan's dispatchable power requirements but requires water access that constrains siting.
- Offshore Wind:Sri Lanka's seabed lease frameworks along Mannar and Pottuvil coastlines are opening new capacity corridors with Ceylon Electricity Board grid evacuation prioritization.
- Geothermal:Limited tectonic activity restricts viable reservoir access to Himalayan fringe zones with sparse transmission infrastructure.
Photovoltaics commands current procurement volumes. Offshore wind holds the steepest expansion trajectory as seabed allocations advance.
End User:
Customer type determines financing structure, with industrial offtake favoring group captive arrangements over residential net metering.
- Industrial:Narayanganj and Gazipur textile hubs aggregate demand through special purpose vehicles to contract dedicated solar capacity, bypassing utility tariff volatility.
- Residential:Rooftop penetration remains constrained by distribution company creditworthiness and net metering caps in Pakistan's Nepra framework.
- Commercial:Karachi and Lahore industrial estates represent untapped aggregation targets for solar leasing models under current regulatory limits.
- Agricultural:Solar-powered irrigation and biomass cogeneration command distinct margin pools through captive feedstock access and existing grid evacuation infrastructure.
Industrial buyers anchor current procurement. Agricultural applications are gaining share fastest as irrigation electrification programs scale.
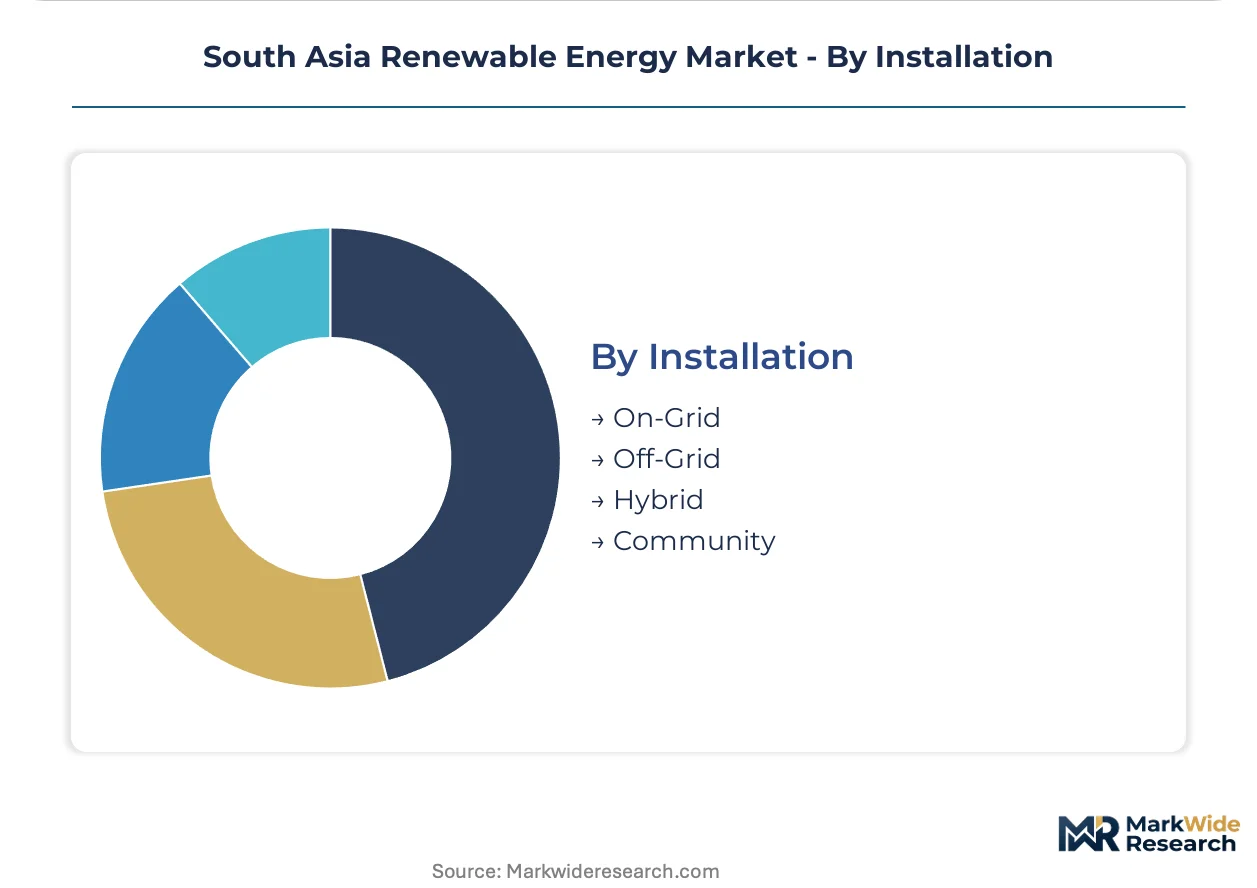
Installation:
Grid access availability dictates whether projects connect to state distribution networks or operate autonomously.
- On-Grid:India's CEA renewable purchase obligations mandate procurement by state distribution companies, creating baseline demand certainty for utility-scale developers.
- Off-Grid:Rural electrification gaps in Pakistan's Balochistan and Afghanistan border regions sustain standalone solar-home-system deployment.
- Hybrid:Battery-backed configurations address Sri Lankan grid instability and Bangladeshi gas supply interruptions for critical commercial loads.
- Community:Shared solar models aggregate residential and small commercial demand in peri-urban clusters with fragmented land ownership.
On-grid installations dominate absolute revenue. Hybrid systems are expanding most quickly as storage costs decline and grid reliability concerns persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's solar parks anchor South Asia's renewable deployment through integrated manufacturing corridors and utility-scale capacity corridors. The region spans five national markets with divergent regulatory maturity and industrial offtake patterns.
India
Western states concentrate photovoltaic deployment through Gujarat's Charanka and Bhadla solar parks alongside Rajasthan's hydrogen hub feedstock positioning. The Central Electricity Authority mandates renewable purchase obligations for state distribution companies, creating baseline procurement certainty. Tamil Nadu and Karnataka sustain onshore wind refurbishment demand through aging turbine fleets.
Bangladesh
Narayanganj and Gazipur textile clusters drive group captive solar procurement as garment exporters face RE100 compliance deadlines. The Sustainable and Renewable Energy Development Authority sets feed-in tariff floors and now mandates domestic content ratios above 10MW. Dhaka-based spinning mills anchor dedicated capacity contracting through special purpose vehicles.
Sri Lanka
Mannar and Pottuvil coastal zones attract offshore wind development rights allocation under seabed lease frameworks advancing through 2024. The Public Utilities Commission of Sri Lanka regulates grid access queues that stretch commercial operation dates by 18-24 months. Ceylon Electricity Board prioritizes these corridors for evacuation infrastructure planning.
Pakistan
Karachi and Lahore industrial estates represent underpenetrated commercial rooftop aggregation targets beneath Nepra's net metering caps. The National Electric Power Regulatory Authority maintains upfront tariff structures that foreign equity monitors for adjustment signals. Balochistan border regions sustain standalone solar-home-system deployment for rural electrification gaps.
Nepal
Run-of-river Himalayan installations face monsoon variability that limits dry-season export capacity to Indian grids. The country's hydropower export framework depends on seasonal thermal backup contracting arrangements. Dry-season output gaps constrain year-round revenue certainty for cross-border transmission projects.
South Asia Renewable Energy Market Competitive Landscape
Global majors compete with regional champions across module manufacturing and utility-scale development rights. Market structure tilts toward consolidated domestic cell-to-module integration under India's PLI scheme, with fragmented EPC contracting at the project execution tier. Three archetypes dominate: integrated renewable majors with backward cell production, rooftop-focused distributed installers, and wind turbine refurbishment specialists. Competitive intensity centers on manufacturing scale expansion and group captive offtake contracting.
Among India-anchored integrated developers, Adani Green Energy Limited and Tata Power Solar Systems Ltd exemplify divergent strategic positioning within the same regulatory environment. Adani Green Energy occupies the utility-scale pipeline anchor archetype through captive solar cell production. Tata Power Solar Systems sits within distributed installation networks spanning residential-commercial boundaries. ReNew Power Limited represents the independent power producer model competing for CEA tender allocations. Suzlon Energy Ltd anchors the wind turbine refurbishment and maintenance revenue stream despite photovoltaic's faster capacity additions.
| Leading Market Players |
|---|
| Tata Power Solar Systems Ltd |
| Adani Green Energy Limited |
| ReNew Power Limited |
| Regen Renewables (Pvt) Ltd |
| Sindicatum Renewable Energy India Private Limited |
| Greenko Group Plc |
| Suzlon Energy Ltd |
| Sembcorp Industries Limited |
| ACME Solar Holding Limited |
| Others |
Value Network & Pricing Analysis
Bangladeshi textile mills mandating RE100 compliance are forcing module suppliers toward group captive contracting structures that compress margins and demand localized balance-of-system sourcing. This procurement shift rewards EPC firms with established Dhaka logistics networks while squeezing pure-play developers dependent on utility-scale tariffs.
Pricing Analysis
Polysilicon spot volatility passes through directly to Indian module assemblers lacking captive wafer supply, compressing margins when Chinese ingot prices spike. Three-tier pricing separates premium heterojunction modules with enhanced tropical warranties from standard Topcon units and economy-grade PERC inventory liquidating from stranded project pipelines. Pricing pressure stems from Bangladesh's SREDA-mandated domestic content ratios requiring 30% local sourcing. Industrial offtakers in Narayanganj garment clusters exhibit highest price sensitivity, while Gujarat hydrogen hub developers accept premium tiers for bankability.
Supply Chain Analysis
Regional distribution centers in Mundra and Chennai anchor hub-and-spoke module logistics for Indian utility-scale deployment. Geographic supply concentrates in China for polysilicon ingots and wafers, India for cell-to-module assembly under PLI incentives, and Vietnam for glass and aluminum framing. Raw material dependencies include metallurgical-grade silicon, silver paste for cell metallization, and ethylene-vinyl acetate encapsulant sheets. Single-source vulnerability in Chinese polysilicon purification exposes margin volatility. Distribution runs through EPC contractor networks with direct mill relationships in Bangladesh and utility liaison offices in Gujarat.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Module efficiency tier migration toward heterojunction architectures creates margin expansion for cell-to-module integrators capturing premium procurement. Cost compression in balance-of-system components amplifies this spread for EPC firms with captive mounting and cabling supply.
For Market Incumbents: Anchor manufacturing scale in Gujarat and Tamil Nadu corridors to defend against PLI scheme expiration and emerging Indonesian module competition. Prioritize backward integration into solar cell production to insulate margin from polysilicon spot volatility. Lock group captive offtake with Bangladeshi textile clusters through multi-year contracting ahead of SREDA tariff revisions. For New Entrants and Emerging Players: Capture Pakistan's distributed solar whitespace beneath Nepra's net metering caps, where Karachi and Lahore industrial estates show sub-2% rooftop penetration. Target agricultural biomass cogeneration in Punjab and Sindh sugar mill complexes with captive feedstock access and existing grid evacuation. Deploy solar leasing models with integrated financing to bypass distribution company creditworthiness constraints. For Investors and Strategic Acquirers: Asymmetric upside sits with electrolyzer manufacturing specialists positioned for India-Green Hydrogen Mission procurement. Long-term viability hinges on renewable power purchase agreement anchors with Gujarat and Rajasthan solar park operators. Watch PLI scheme revision timing as inflection signal for domestic module pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solar Cell Production | PLI scheme recipients in Gujarat and Tamil Nadu capture margin from polysilicon volatility. |
| Group Captive Power Purchase Agreement | Narayanganj textile mills bypass utility tariffs while meeting RE100 compliance deadlines. |
| Offshore Wind Seabed Lease Acquisition | Mannar and Pottuvil corridor rights position developers for Ceylon Electricity Board prioritization. |
| Electrolyzer Manufacturing Scale-Up | National Hydrogen Mission incentives create demand anchors for Rajasthan solar park output. |
| Agricultural Biomass Cogeneration Deployment | Punjab sugar mill complexes displace diesel irrigation with captive rice husk feedstock. |
Research Methodology
Bottom-up industrial offtake modeling reconciled against top-down module manufacturing capacity tracking forms the analytical core. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators were validated against secondary sources including IEA renewable deployment databases, CEA regulatory filings, and SREDA tariff notifications. Cross-referencing Bangladeshi textile procurement disclosures with Gujarat solar park interconnection queues enabled demand-supply reconciliation.
Historical capacity addition trendlines across solar, wind, and biomass segments informed projection elasticity parameters. Segmentation modeling spanned technology type, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived from installer shipment data triangulated against tender award volumes and commercial operation date announcements. Hydrogen hub feedstock demand and PLI scheme utilization rates served as industry-specific forecast inputs.
Regulatory revision, polysilicon supply disruption, and currency volatility are the dominant revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy in South America Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
Renewable Heating Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Azerbaijan Renewable Energy Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
Green Energy Lighting Market
Renewable Energy
Norway Renewable Energy Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Hybrid Power System Market
Renewable Energy
Solar Farm Market
Renewable Energy
Solar PV and Wind Energy Market
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
Drones in Renewable Energy Market