
 Renewable Energy MRO Market | 2026-2036
Renewable Energy MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Energy MRO Market Insights
Certified wind turbine technician availability is redrawing competitive boundaries across the Renewable Energy MRO landscape. Siemens Energy AG leverages its European service hub network to anchor long-term contracts in offshore wind. General Electric sustains dominance in North American wind MRO through its digital predictive analytics platform. Mitsubishi Heavy Industries Ltd competes aggressively in Asian geothermal maintenance with specialized high-temperature component expertise.
Renewable Energy MRO encompasses the inspection, repair, overhaul, and replacement of components in solar arrays, wind turbines, biomass plants, and geothermal facilities to sustain designed energy output and extend asset life cycles. Preventive maintenance schedules typically align with manufacturer warranty terms and seasonal generation windows to minimize revenue loss during peak resource periods. Predictive maintenance is capturing margin pools fastest as vibration monitoring and thermal imaging reduce unplanned downtime in wind assets. Solar corrective maintenance remains structurally fragmented due to distributed rooftop geometries and regional installer density variations.
The EU Green Deal and F-Gas Regulation are tightening refrigerant and insulation standards for geothermal heat pump systems across member states. The EPA enforces Clean Air Act compliance for biomass combustion emissions, directly shaping overhaul scope and catalyst replacement cycles in US facilities. OSHA fall-protection mandates govern wind turbine tower access protocols, elevating labor costs and certification requirements for service providers. Stakeholders must weigh predictive technology deployment against legacy corrective maintenance revenue streams as asset owners demand outcome-based service agreements.
Market Dynamics
Aging wind turbine fleets across Europe and North America are forcing asset owners to renegotiate service contracts toward performance-based uptime guarantees rather than traditional time-and-materials billing. This contractual pivot is compressing margins for corrective maintenance providers while elevating predictive analytics capabilities as a competitive differentiator.
Growth Catalysts
- EU Green Deal enforcement:Member states are mandating tighter uptime requirements for offshore wind installations, accelerating demand for preventive maintenance scheduling and component lifecycle management.
- Geothermal heat pump expansion:F-Gas Regulation compliance requirements across Germany, France, and Italy are driving overhaul cycles for refrigerant systems and insulation retrofits.
- Drone-based blade inspection:Automated aerial thermography is reducing tower climb frequency and cutting inspection costs for onshore wind operators in Spain and Denmark.
Market Restraints
- Specialized technician scarcity:GWO-certified blade repair specialists concentrate in Northern Europe, creating service bottlenecks for Southern European and North American fleet expansions.
- Copper and rare earth price volatility:Generator rewind and power electronics replacement costs fluctuate with commodity markets, complicating fixed-price contract structures.
- Grid interconnection delays:Transmission upgrade backlogs in Germany and the UK strand completed wind assets, deferring revenue-triggered maintenance triggers.
Strategic Opportunities
- Polish and Romanian onshore wind:Emerging turbine clusters in Eastern Europe lack mature service ecosystems, opening first-mover contract positions for predictive maintenance platforms.
- Solar-plus-storage hybrid retrofits:DC-coupled battery integration is creating new inverter and power conversion overhaul demand at existing utility-scale PV sites.
- US Inflation Reduction Act credits:Domestic content bonuses for wind component manufacturing are incentivizing regional MRO hub development near assembly facilities.
Industry Challenges
- Fall-protection certification backlogs:OSHA-compliant tower access training programs face 12-16 week wait times, constraining workforce deployment velocity.
- Legacy SCADA integration:Proprietary turbine control architectures from 2005-2015 vintages resist standardized predictive analytics overlay without expensive gateway retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Energy MRO Market |
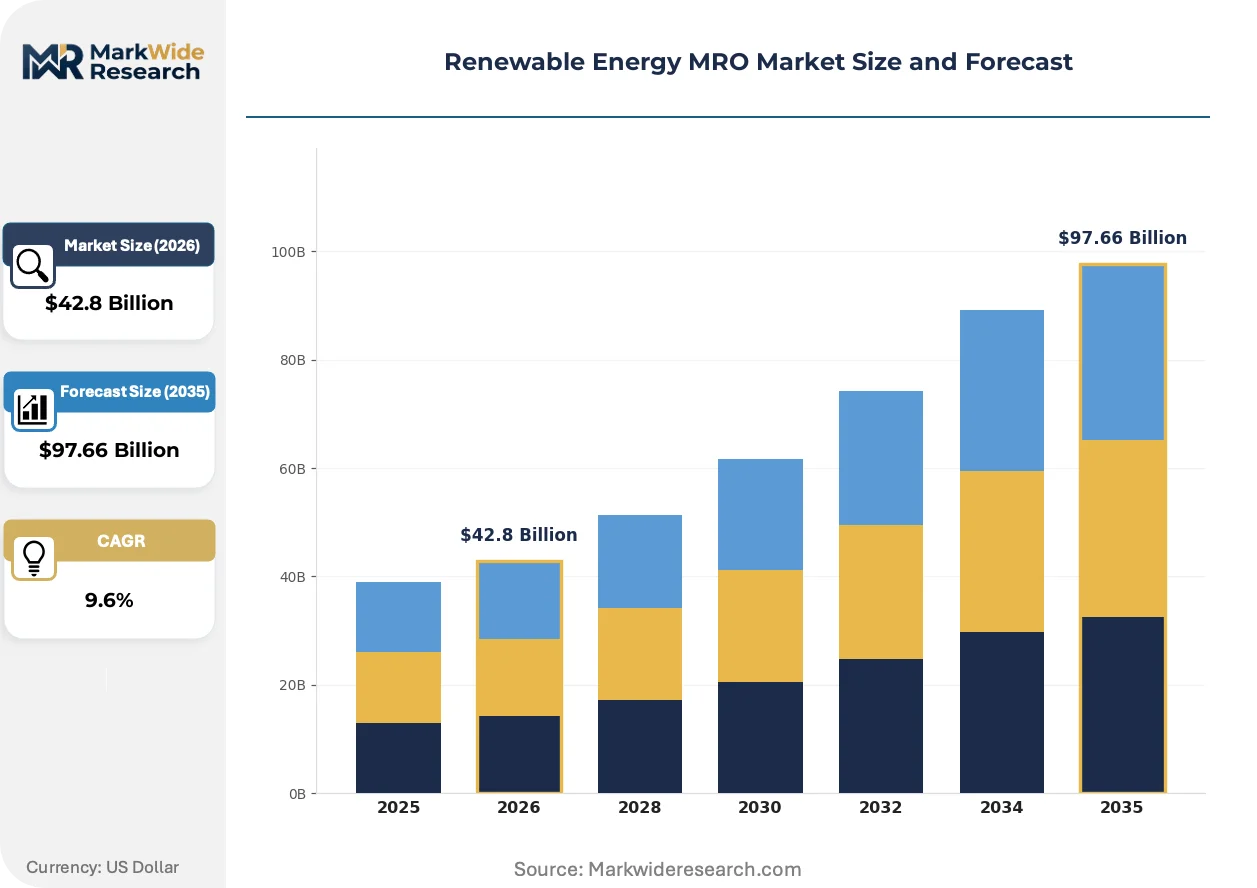
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $97.66 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preventive Maintenance, Corrective Maintenance, Predictive Maintenance, Overhaul Technology: Solar, Wind, Biomass, Geothermal Customer Type: Utilities, Independent Power Producers, Industrial Users, Government End Use Sector: Commercial, Residential, Institutional, Educational |
| Companies Covered | General Electric, Siemens Energy AG, Mitsubishi Heavy Industries Ltd, Baker Hughes Company, Rolls-Royce Holdings plc, Honeywell International Inc., Safran S.A., MAN Energy Solutions SE, Sulzer Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Energy MRO Market Trends and Innovations
Digital twin technology is decomposing traditional calendar-based maintenance schedules across renewable asset portfolios. Vibration signature libraries and thermal degradation models now enable component-specific replacement timing rather than fleet-wide overhaul campaigns.
Digital twin platforms aggregate sensor streams from gearbox bearings, generator windings, and blade pitch systems into unified degradation models. Iberdrola and Ørsted are deploying these systems across North Sea offshore arrays. The technology is decomposing the economics of scheduled component replacement by identifying individual units with remaining service life.
EPA Clean Air Act enforcement is tightening particulate matter thresholds for biomass combustion facilities in the US Northeast. Catalyst replacement cycles have compressed from 48 to 36 months for fluidized bed boilers. Wood pellet plants in Maine and Vermont are absorbing compliance costs through operational expenditure reallocation rather than capital upgrades.
Asset owners are unbundling OEM service agreements to procure predictive analytics and corrective maintenance from separate vendors. Independent service providers with multi-brand turbine expertise are capturing contracts from Vestas and Siemens Gamesa legacy agreements. This vendor fragmentation is most pronounced in German and Spanish onshore markets where 15-year original warranties are expiring.
Renewable Energy MRO Market Segmentation
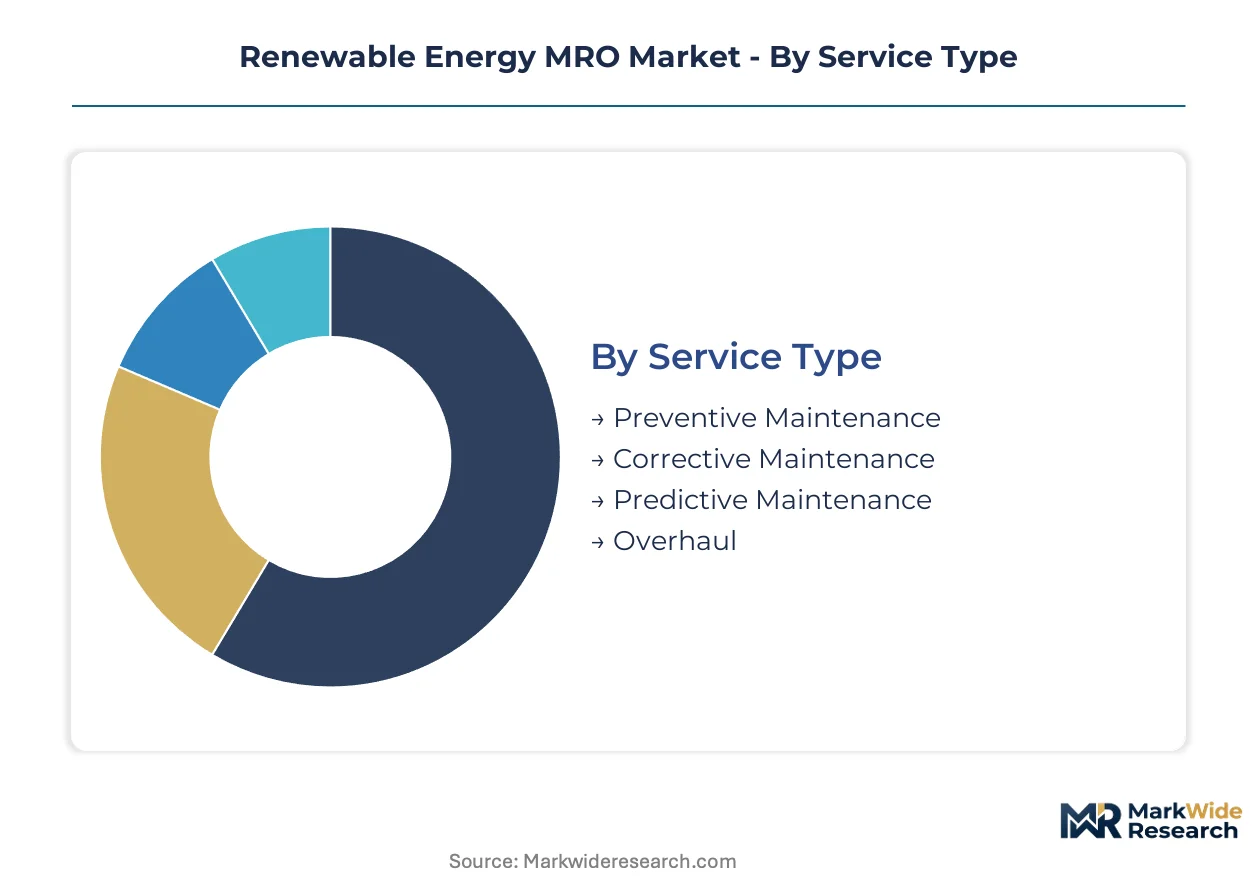
Service differentiation in renewable energy MRO determines contract profitability and customer retention. Segment boundaries shift as asset owners unbundle OEM agreements and adopt outcome-based pricing models.
Service Type:
Predictive maintenance platforms are displacing time-and-materials billing across all renewable asset classes, forcing legacy corrective providers to retool or exit.
- Preventive Maintenance:Scheduled inspections, lubrication cycles, and component replacements align with manufacturer warranty terms and seasonal generation windows. German and Spanish offshore wind operators are tightening preventive schedules to meet EU Green Deal uptime mandates.
- Corrective Maintenance:Unplanned repairs address component failures, blade damage, and electrical faults. Demand concentrates in aging North American wind fleets where 2005-2015 vintage turbines exceed original design life.
- Predictive Maintenance:Vibration monitoring, thermal imaging, and SCADA analytics enable condition-based intervention. Iberdrola and Ørsted deployments across North Sea arrays demonstrate revenue protection through downtime avoidance.
- Overhaul:Comprehensive generator rewinds, gearbox replacements, and structural refurbishments restore designed output capacity. Copper price volatility complicates fixed-price overhaul contracts for independent service providers.
Preventive maintenance retains volume leadership; predictive maintenance holds the steepest expansion curve.
Technology:
Technology cost tiers separate premium offshore wind service contracts from commoditized solar corrective work.
- Wind:Onshore and offshore turbine servicing encompasses blade repair, drivetrain overhaul, and control system upgrades. Siemens Energy AG anchors long-term contracts through European hub networks while independent providers capture expiring Vestas and Siemens Gamesa warranties in Germany and Spain.
- Solar:Array cleaning, inverter replacement, and module defect remediation span utility-scale and distributed rooftop installations. Regional installer density variations and fragmented ownership structures resist standardized service pricing.
- Biomass:Combustion chamber refractory replacement, catalyst management, and emission control system maintenance respond to EPA Clean Air Act enforcement. Fluidized bed boilers in Maine and Vermont face compressed 36-month catalyst cycles.
- Geothermal:Heat pump refrigerant system overhaul and high-temperature component replacement require specialized expertise. F-Gas Regulation compliance across Germany, France, and Italy drives insulation retrofit demand.
Wind technology commands premium pricing; solar maintenance is gaining share fastest through distributed asset proliferation.
Customer Type:
Procurement sophistication varies sharply across customer categories, with utilities demanding integrated analytics and industrial users prioritizing cost minimization.
- Utilities:Vertically integrated power generators with captive renewable fleets negotiate performance-guaranteed service agreements. Ørsted and Iberdrola unbundle OEM contracts to source predictive analytics separately from corrective work.
- Independent Power Producers:Non-utility asset owners lacking in-house technical staff outsource complete maintenance responsibility. IPP contract structures favor fixed-fee arrangements that transfer operational risk to service providers.
- Industrial Users:On-site renewable generation for manufacturing facilities prioritizes uptime assurance over technology optimization. Cogeneration biomass installations at pulp and paper mills require specialized combustion expertise.
- Government:Public sector procurement emphasizes compliance documentation and local content requirements. Municipal solar arrays and federal wind installations face distinct bidding protocols and certification standards.
Utilities dominate contract value; independent power producers are expanding most quickly as financial investors acquire operating assets.
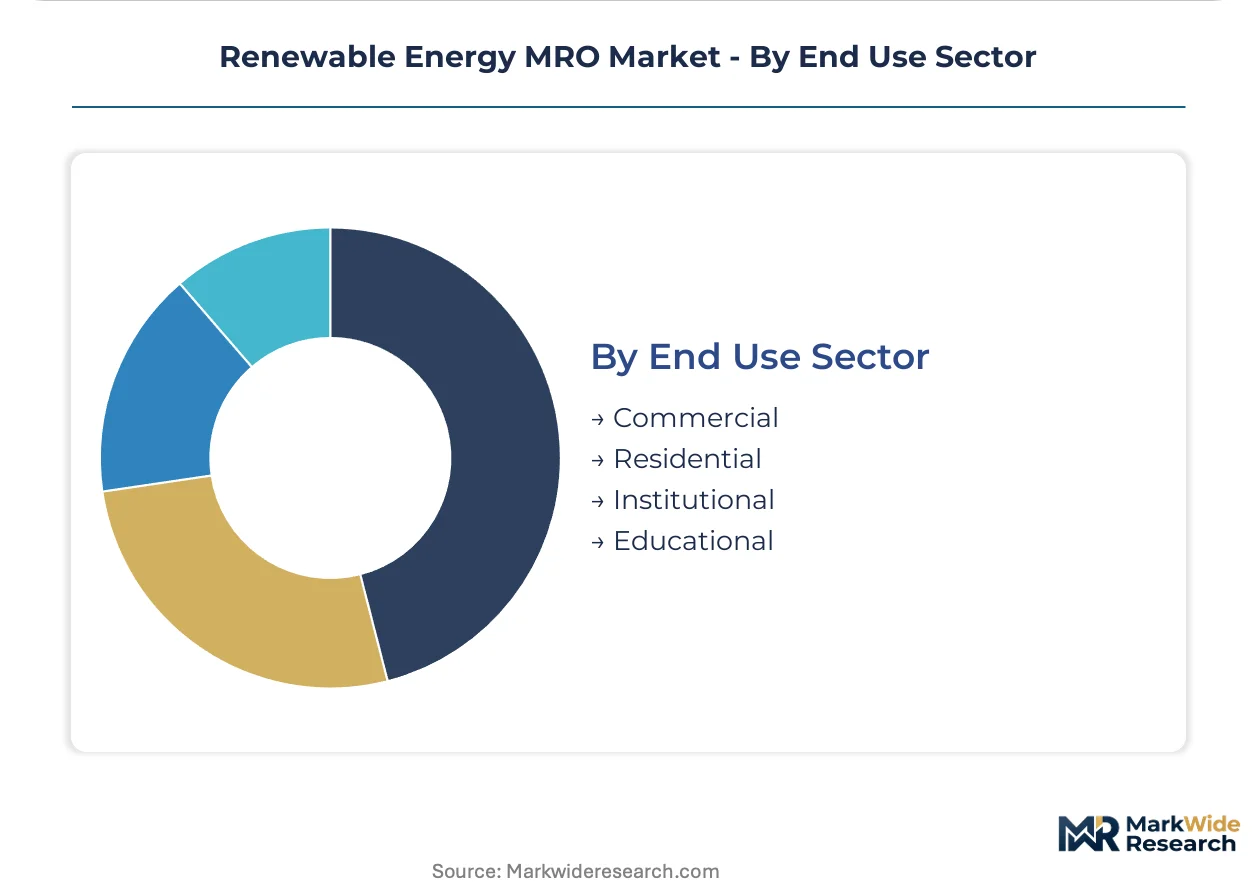
End Use Sector:
Application maturity separates established commercial solar servicing from nascent residential predictive maintenance adoption.
- Commercial:Office buildings, retail centers, and logistics facilities with rooftop solar and geothermal heat pump systems require integrated HVAC-renewable maintenance. Lease financing structures complicate service responsibility allocation between building owners and energy developers.
- Residential:Single-family and multi-family distributed solar installations depend on regional installer networks for corrective service. Customer acquisition costs limit preventive maintenance penetration in this price-sensitive segment.
- Institutional:Hospitals, government facilities, and military installations mandate stringent uptime guarantees and cybersecurity-compliant remote monitoring. Public procurement protocols extend vendor qualification timelines.
- Educational:University and K-12 campus renewable assets often combine solar carports, geothermal heating, and demonstration wind turbines. Budget cyclicality creates deferred maintenance backlogs during fiscal constraints.
Commercial applications retain the deepest service penetration; institutional demand is climbing the fastest through federal sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal enforcement by the European Commission anchors the dominant geography, mandating tighter uptime requirements that reshape service contract structures across member states.
Germany
Offshore wind clusters in the North Sea and Baltic Sea drive preventive maintenance demand as turbine fleets age beyond original design life. The F-Gas Regulation compels refrigerant system overhauls for geothermal heat pumps in residential and commercial buildings. Service providers concentrate around Hamburg and Bremerhaven to support port logistics for blade transport and drivetrain replacement.
United States
2005-2015 vintage wind turbines across the Great Plains and Texas trigger corrective maintenance cycles as original warranties expire. EPA Clean Air Act enforcement compresses catalyst replacement intervals for biomass facilities in Maine and Vermont. Independent service providers capture contracts from legacy OEM agreements in Iowa and Oklahoma wind corridors.
Spain
Onshore wind installations in Castile-La Mancha and Aragón expand drone-based blade inspection adoption to reduce tower climb frequency. National renewable portfolio standards tighten uptime obligations for existing assets. Service ecosystems mature around Zaragoza and Toledo to support predictive analytics deployment across aging turbine fleets.
Denmark
North Sea offshore arrays operated by Ørsted anchor predictive maintenance platform rollouts using digital twin technology. The Danish Energy Agency enforces stringent availability requirements for wind farm concessions. Esbjerg serves as the primary service hub for blade repair specialists and gearbox overhaul facilities.
China
Utility-scale solar and wind capacity expansion in Inner Mongolia and Gansu provinces generates corrective maintenance demand for inverter replacement and module defect remediation. Dual carbon goals under MEE oversight accelerate asset lifecycle management requirements. Regional service networks concentrate around Ulanqab and Jiuquan to support remote desert installations.
Renewable Energy MRO Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with OEM-affiliated service divisions commanding premium pricing through captive parts access and warranty continuity. Independent providers compete on multi-brand turbine expertise and outcome-based contract structures. Two strategic archetypes dominate: vertically integrated energy conglomerates with captive MRO capabilities, and pure-play service specialists targeting expiring OEM warranties. Competitive moves center on predictive analytics platform licensing and regional hub expansion to capture aging fleet contracts.
Within the integrated conglomerate tier, General Electric and Siemens Energy AG occupy positions defined by proprietary digital platforms and European hub networks. Mitsubishi Heavy Industries Ltd exemplifies the specialized industrial archetype, with high-temperature component expertise shaping competitive positioning in geothermal maintenance. These three anchors illustrate how technology heritage and geographic footprint determine contract capture in performance-guaranteed service agreements.
| Leading Market Players |
|---|
| General Electric |
| Siemens Energy AG |
| Mitsubishi Heavy Industries Ltd |
| Baker Hughes Company |
| Rolls-Royce Holdings plc |
| Honeywell International Inc. |
| Safran S.A. |
| MAN Energy Solutions SE |
| Sulzer Ltd. |
| Others |
Pricing and Supply Chain Analysis
GWO certification requirements for tower access technicians simultaneously gate supplier qualification and stratify service pricing across European and North American wind markets. This dual function compresses margins for uncertified corrective providers while elevating predictive analytics platforms that reduce labor-intensive site visits.
Pricing Analysis
Offshore wind service contracts in the North Sea command 40-60% premiums over onshore equivalents in Spain and Poland due to logistics complexity and weather window constraints. Three-tier pricing structure across premium, standard, and economy levels separates OEM-authorized service from independent multi-brand providers and regional corrective specialists. Pricing pressure stems from IPP procurement teams unbundling legacy agreements to extract predictive analytics separately from corrective work. Industrial biomass operators exhibit highest price sensitivity due to thin fuel margins, while utility offtakers prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Strait of Hormuz transit vulnerability exposes rare earth magnet supply chains feeding generator rewind facilities in Germany and Denmark. Component manufacturing concentrates in China for power electronics, Germany for precision gearbox bearings, and Vietnam for blade composite materials. Copper and neodymium price volatility complicates fixed-price overhaul contracting for independent service providers. Distribution runs through port-centric hub networks at Esbjerg, Bremerhaven, and Hamburg serving North Sea offshore arrays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
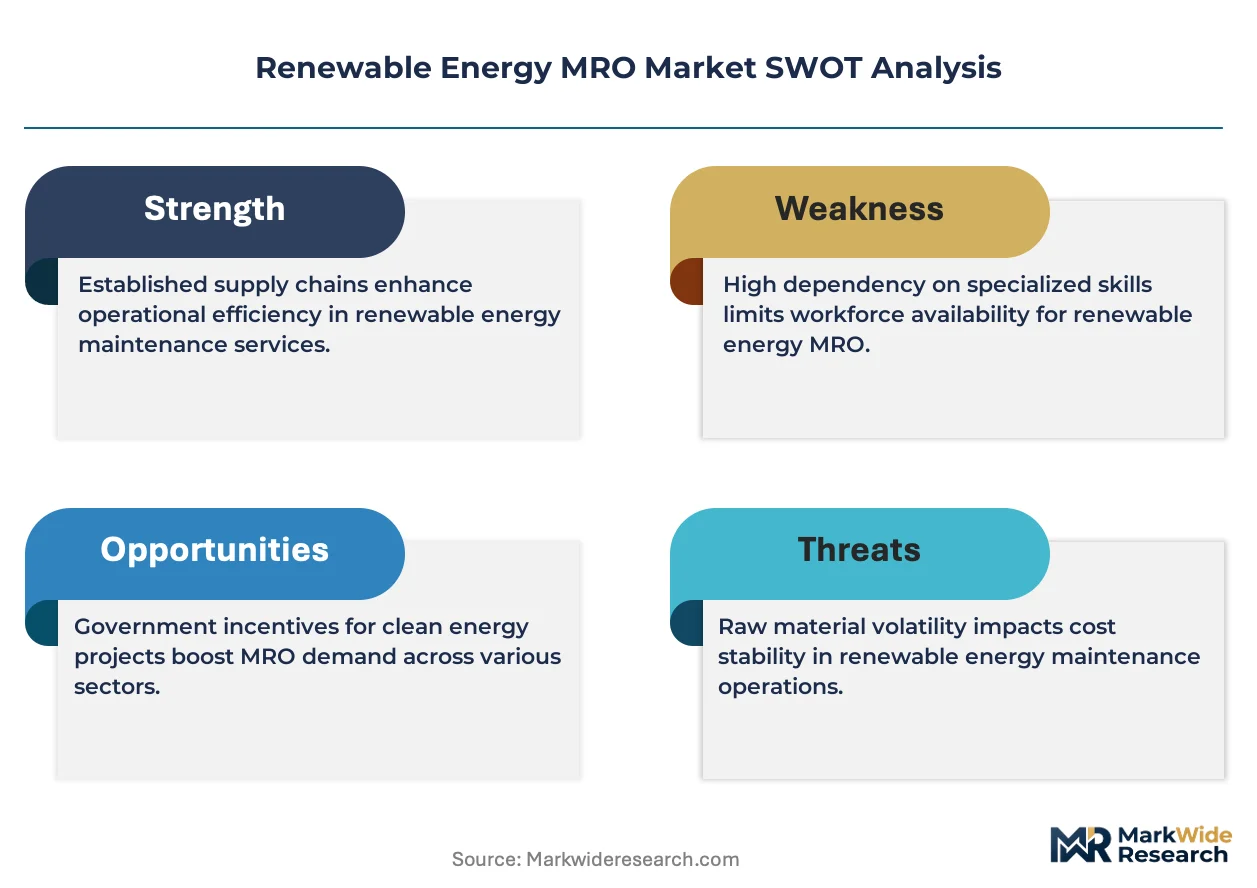
Certified technician scarcity across GWO training bottlenecks and OSHA compliance backlogs constrains service capacity expansion faster than fleet aging generates demand. This capability gap rewards first-movers in predictive platform deployment and regional hub positioning.
For Market Incumbents: Consolidate multi-brand turbine expertise through targeted acquisition of independent service providers holding expiring Vestas and Siemens Gamesa warranties in Germany and Spain. Deepen backward integration into blade repair training academies to bypass 12-16 week GWO certification queues constraining workforce velocity. Lock long-term copper and rare earth supply agreements to stabilize overhaul contract pricing against commodity volatility. For New Entrants and Emerging Players: Anchor in Polish and Romanian onshore wind clusters where mature turbine fleets lack established service ecosystems and first-mover contracts remain available. Target solar-plus-storage hybrid retrofits at utility-scale PV sites in the US Southwest where DC-coupled battery integration creates new inverter overhaul demand. Lead with drone-based thermography platforms to bypass capital-intensive tower climb infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across predictive maintenance software as sensor hardware commoditizes and analytics platforms achieve scale economics. Favor acquisition targets with captive technician training pipelines and multi-OEM turbine data libraries over asset-heavy corrective specialists. Monitor OSHA training program expansion timelines as the inflection signal for workforce-constrained market entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Analytics Platform Licensing | Iberdrola and Ørsted deployments across North Sea arrays demonstrate revenue protection through downtime avoidance. |
| Regional MRO Hub Expansion | US Inflation Reduction Act domestic content bonuses incentivize hub development near wind component assembly facilities. |
| Technician Training Pipeline Investment | GWO-certified blade repair specialist scarcity in Southern Europe creates captive workforce advantages for early movers. |
| Multi-Brand Turbine Data Aggregation | Independent providers capture expiring OEM warranties through proprietary SCADA integration across Vestas and Siemens Gamesa vintages. |
| Drone-Based Inspection Service Launch | Spanish and Danish operators reduce tower climb frequency through automated aerial thermography adoption. |
Research Methodology
Initial hypotheses were tested against primary input from wind farm operations directors, IPP asset managers, GWO training program administrators, and aftermarket service heads at major OEMs, then refined through secondary validation. Bottom-up triangulation drew from EIA generation databases, IEA renewable capacity reports, FERC interconnection queues, and EU Green Deal implementation tracking. Top-down cross-checks incorporated customs data on copper and rare earth trade flows, SEC filings from listed energy conglomerates, and project finance databases tracking service contract structures.
Variance decomposition across the projection horizon segmented modeled outputs by service type, technology class, customer procurement sophistication, and end-use sector regulatory exposure. CAGRs derived from asset-level maintenance cost curves, fleet aging demographics, and contractual pivot rates from time-and-materials toward performance-guaranteed structures. Forecast inputs included OEM warranty expiration schedules, grid interconnection backlog resolution timelines, and F-Gas Regulation compliance cost trajectories.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal enforcement and IRA credit continuity; material deviation in either regulatory regime would warrant model refresh. Practitioners should keep alternative scenarios live as copper price volatility and GWO training capacity expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
Germany Renewable Energy Market
Renewable Energy
East Europe Renewable Energy Market
Renewable Energy
Uzbekistan Renewable Energy Market
Renewable Energy
Solar Oven Market
Renewable Energy
Iran Renewable Energy Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Green Power Market
Renewable Energy
Europe Biomethane Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
Philippines Power Market
Renewable Energy
Nordic Countries Renewable Energy Market